
 Asia-Pacific Child Resistant Packaging Market | 2026-2036
Asia-Pacific Child Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Child Resistant Packaging Market Analytics
Multi-source procurement among pharmaceutical contract packagers is hardening as brands diversify supplier bases beyond single-country dependence. Amcor plc leverages its integrated film and conversion network across Australia and Southeast Asia to secure long-dated supply contracts. Berry Global Inc. anchors its regional position through high-volume injection molding of push-and-turn closures at facilities in China and India. Gerresheimer AG specializes in glass-primary packaging with integrated child-resistant functionality for European-destined exports.
Asia-Pacific child resistant packaging denotes engineered primary and secondary containers designed to prevent access by children under five years while remaining operable by adults, typically incorporating torque specifications of 1.5 N·m or higher for push-and-turn closures and validated under ISO 8317 protocols. Plastic resins dominate material selection due to impact resistance, design flexibility, and compatibility with multilayer barrier films for moisture-sensitive pharmaceuticals. Push-and-turn closures lead closure-type demand because this mechanism satisfies the widest range of regulatory acceptance across Asian pharmacopeias, while squeeze-and-slide formats grow fastest in household chemical applications where one-handed dispensing matters. Pouches capture expanding share in unit-dose pharmaceutical trials and travel-size cosmetics, though bottles retain the deepest margin pools due to higher barrier specifications and certification testing costs.
CDSCO in India mandates child-resistant standards for scheduled drug packaging under the Drugs and Cosmetics Act, while TGA in Australia enforces ISO 8317 compliance for all Schedule 4 and 8 medicines. China's NMPA has aligned with international closure-testing protocols, reducing re-certification burdens for multinational suppliers. REACH and RoHS frameworks affect material composition for export-bound production, particularly restricting phthalate plasticizers in PVC formulations. Stakeholders must monitor divergence between national pharmacopeia testing methods, as harmonization gaps between Indian, Chinese, and Australian protocols still force redundant validation spending.
Market Dynamics
Pharmaceutical contract packagers in China and India are hardening multi-source procurement strategies to reduce single-country supplier dependence, forcing closure converters to certify across CDSCO, NMPA, and TGA protocols simultaneously.
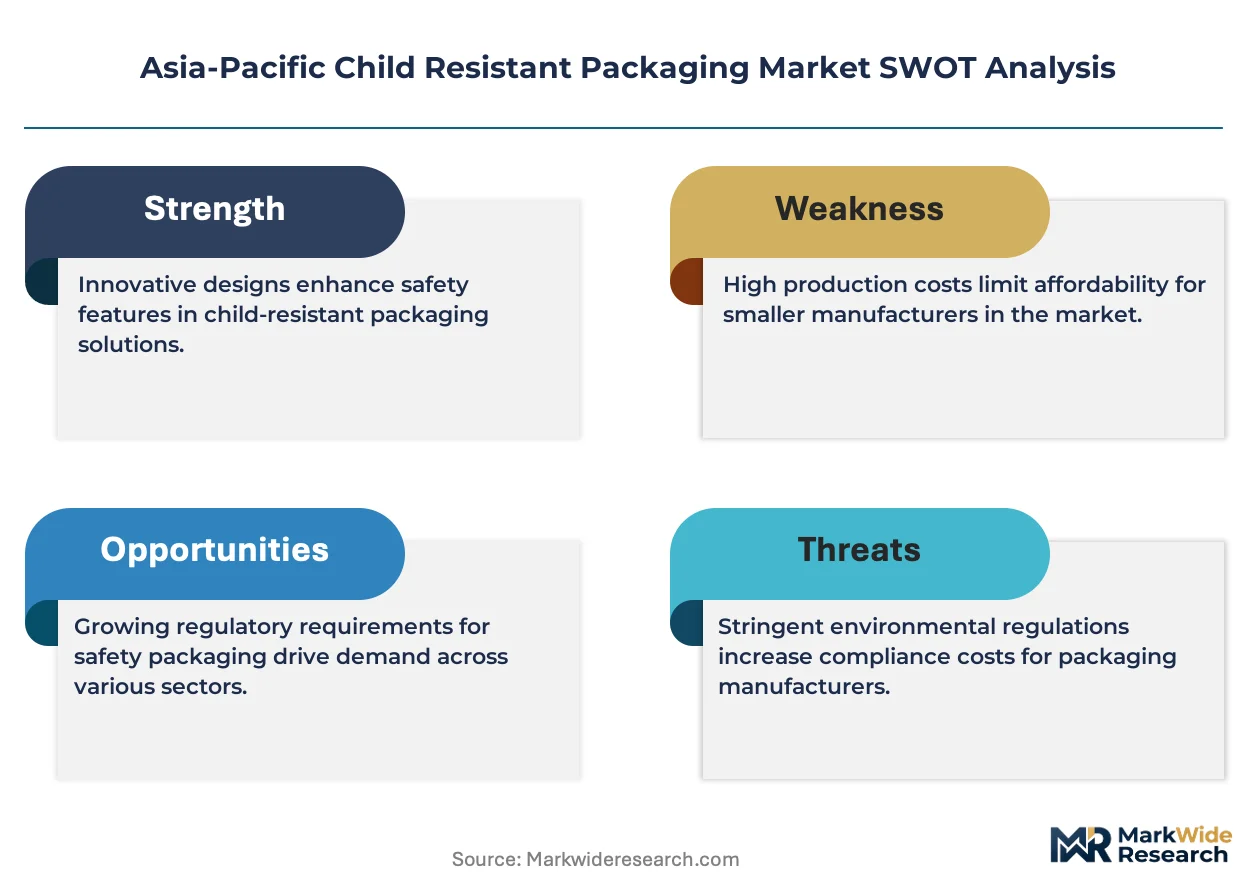
Growth Catalysts
- CDSCO Mandate Expansion:India's tightened child-resistant standards for scheduled drugs under the Drugs and Cosmetics Act compel domestic pharmaceutical brands to upgrade primary packaging specifications.
- Barrier Film Integration:Multilayer coextrusion technologies for moisture-sensitive pharmaceuticals enable converters to capture higher-margin bottle contracts requiring extended shelf-life validation.
- Southeast Asian Export Flows:China's eastern manufacturing corridor serves as the dominant conversion hub for pharmaceutical brands exporting to Indonesia, Vietnam, and Thailand.
Market Restraints
- Resin Price Volatility:Polypropylene and polyethylene input costs fluctuate with crude oil indices, compressing margins for high-volume injection molders serving generic drug packagers.
- Certification Redundancy:Non-harmonized testing methods between Indian, Chinese, and Australian pharmacopeias force suppliers to conduct parallel ISO 8317 validation cycles for each market.
- Glass-Primary Substitution:Gerresheimer's integrated child-resistant glass vials for European exports displace plastic closure demand in high-value biologics segments.
Strategic Opportunities
- Indonesia's Underpenetrated Market:Southeast Asia's largest pharmaceutical market lacks mature child-resistant packaging infrastructure, creating first-mover advantages for certified converters.
- Squeeze-and-Slide Convergence:One-handed dispensing mechanisms for household chemicals combine with pharmaceutical barrier specifications to open dual-use product lines.
- Unit-Dose Pouch Expansion:Clinical trial packaging and travel-size cosmetics in Japan and South Korea favor flexible formats with integrated child-resistant tear notches.
Industry Challenges
- Tooling Lead Times:Custom push-and-turn closure molds require 16-20 week production cycles, constraining rapid response to pharmaceutical tender deadlines.
- Validation Bottlenecks:CDSCO and TGA certification queues extend project timelines, delaying revenue recognition for contract packagers.
- Polymer Compatibility Expertise:Shortage of formulation chemists skilled in phthalate-free PVC alternatives undermines REACH-compliant export production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Child Resistant Packaging Market |
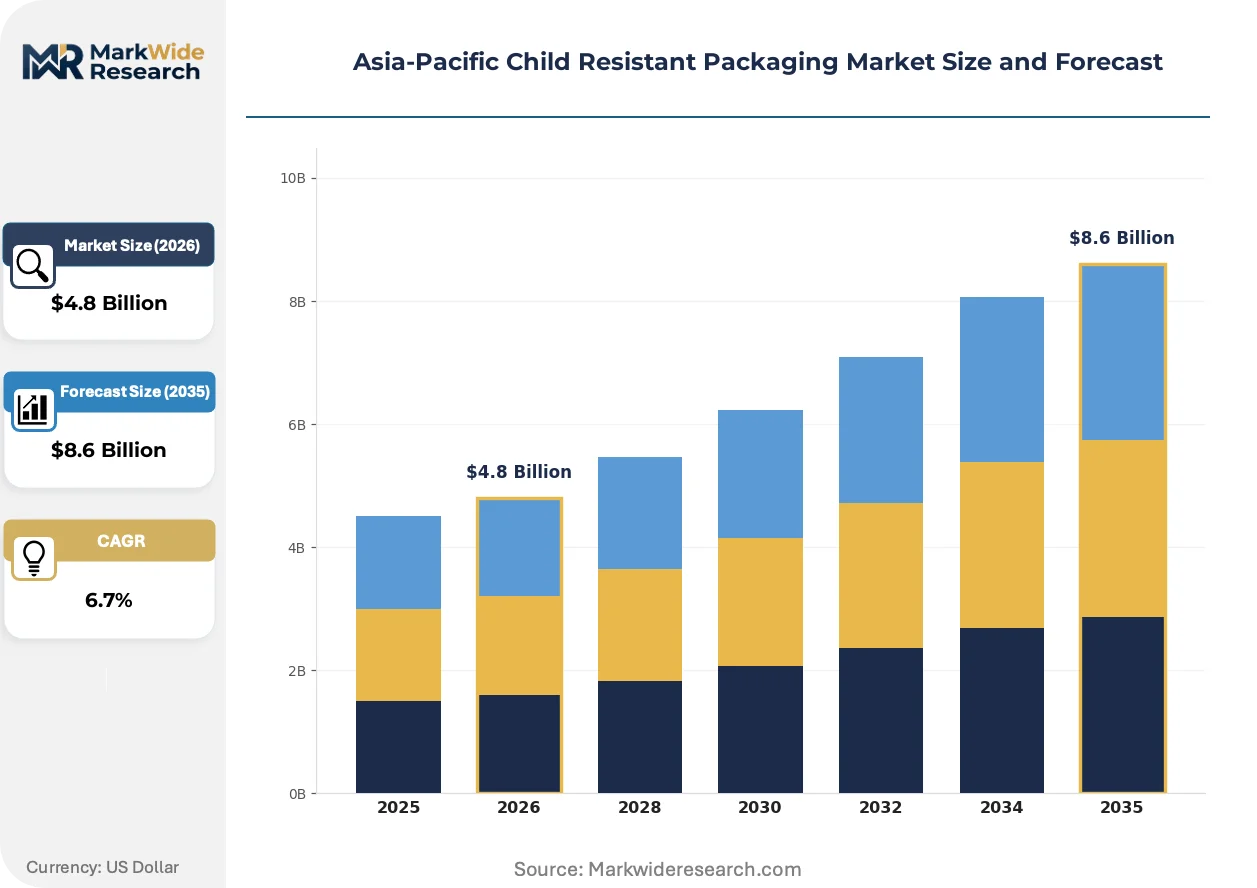
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Bottles, Pouches, Containers Material: Plastic, Glass, Metal, Composite Closure Type: Push-and-Turn, Squeeze, Locking, Slide Application: Pharmaceuticals, Household Chemicals, Cosmetics, Food |
| Companies Covered | Amcor plc, Berry Global Inc., Gerresheimer AG, WestRock Company, AptarGroup, Inc., Winpak Ltd, Constantia Flexibles, Bilcare Limited, Körber Medipak Systems GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Child Resistant Packaging Market Evolving Landscape
Digital printing and smart closure technologies are compressing batch customization timelines while regulatory divergence across Asia-Pacific pharmacopeias forces investments in multi-protocol testing infrastructure.
Biodegradable polymer formulations with equivalent torque retention to conventional resins are rewriting material selection criteria for sustainability-focused pharmaceutical brands. European-destined exporters from India and China face REACH and RoHS compliance deadlines that accelerate adoption of plant-derived barrier layers. This shift is compressing the viable supplier base to converters with in-house polymer compounding capabilities.
Australia's TGA enforcement of ISO 8317 for Schedule 4 and 8 medicines tightens compliance verification for imported packaging components. Chinese NMPA alignment with international closure-testing protocols reduces re-certification burdens for multinational suppliers. Pharmaceutical contract manufacturers in Australia now demand batch-level torque test documentation from Southeast Asian component suppliers.
Direct procurement relationships between pharmaceutical brands and specialized closure converters are displacing distributor-mediated sourcing in India's generic drug sector. Large contract packagers in Hyderabad and Mumbai now negotiate multi-year supply agreements with certified molders, bypassing traditional trading intermediaries. This channel consolidation concentrates volume with converters holding simultaneous CDSCO and NMPA certifications.
Asia-Pacific Child Resistant Packaging Market Segmentation
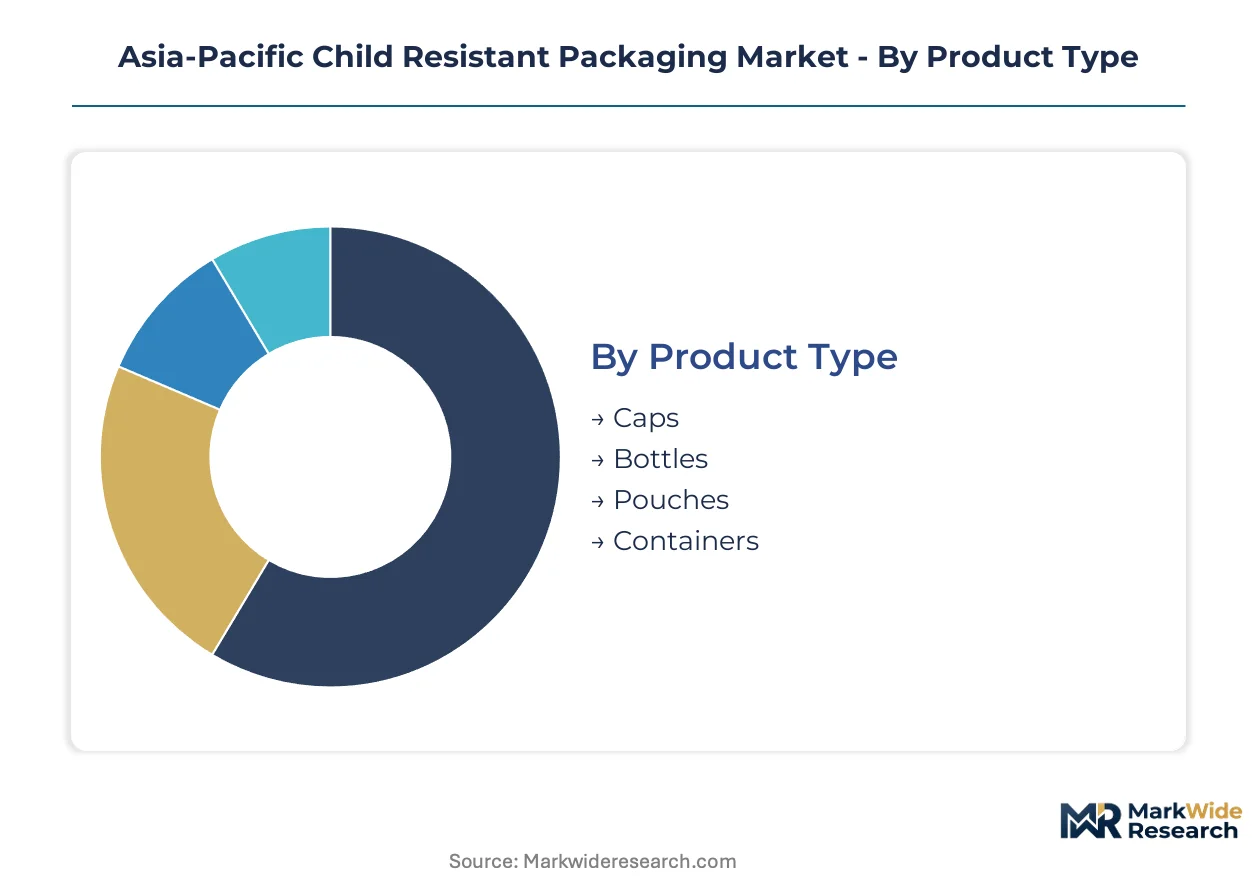
Child-resistant packaging segmentation in Asia-Pacific reflects divergent certification burdens across regulatory regimes. Each product format, material, and closure mechanism carries distinct validation requirements under CDSCO, NMPA, and TGA protocols.
Product Type:
Certification intensity varies sharply by primary container format, with bottles and pouches facing the most stringent torque and barrier testing mandates.
- Caps:Push-and-turn and squeeze-and-slide variants require ISO 8317 torque validation between 1.5-2.0 N·m. Indian generic drug packagers in Hyderabad source these in bulk for retrofit onto standard bottles, driving volume concentration.
- Bottles:Multilayer coextruded constructions with integrated child-resistant neck finishes dominate pharmaceutical applications. China's eastern manufacturing corridor supplies these for export to Southeast Asian markets where moisture barrier specifications are tightening.
- Pouches:Flexible unit-dose formats with tear-notch child-resistant features serve clinical trials and travel cosmetics in Japan and South Korea.
- Containers:Wide-mouth jars with dual-action locking mechanisms address household chemical storage needs under Australia's tightened TGA standards.
Leading the category by volume: Bottles. Growing fastest: Pouches.
Material:
Raw material selection determines REACH and RoHS compliance viability for European-destined exports from India and China.
- Plastic:Polypropylene and polyethylene resins offer design flexibility and impact resistance for high-volume injection molding. Resin price volatility tied to crude oil indices compresses margins for generic drug packagers.
- Glass:Borosilicate and soda-lime formulations with molded child-resistant neck rings serve high-value biologics. Gerresheimer's integrated vial solutions displace plastic alternatives in European export segments.
- Metal:Tinplate and aluminum closures provide tamper-evident functionality for topical pharmaceutical creams.
- Composite:Multilayer structures combining polymer barriers with paperboard exteriors address sustainability mandates from Japanese cosmetic brands.
Plastic retains the dominant share. Glass commands the steepest expansion trajectory in biologics packaging.
Closure Type:
Mechanism complexity directly correlates with regulatory acceptance breadth across Asian pharmacopeias.
- Push-and-Turn:The most widely accepted format across CDSCO, NMPA, and TGA jurisdictions. Berry Global anchors regional supply through high-volume injection molding at Chinese and Indian facilities.
- Squeeze:One-handed dispensing suits household chemical applications where user dexterity varies. Indonesia's underdeveloped child-resistant infrastructure creates first-mover opportunities for squeeze-and-slide convergence products.
- Locking:Dual-action mechanisms combining push-and-turn with squeeze functions serve high-risk scheduled drugs under India's tightened Drugs and Cosmetics Act enforcement.
- Slide:Linear motion closures gain traction in unit-dose pouch formats for clinical trial packaging where rapid access matters.
Push-and-Turn closures dominate procurement volumes. Squeeze mechanisms are climbing the fastest as household chemical regulations tighten.
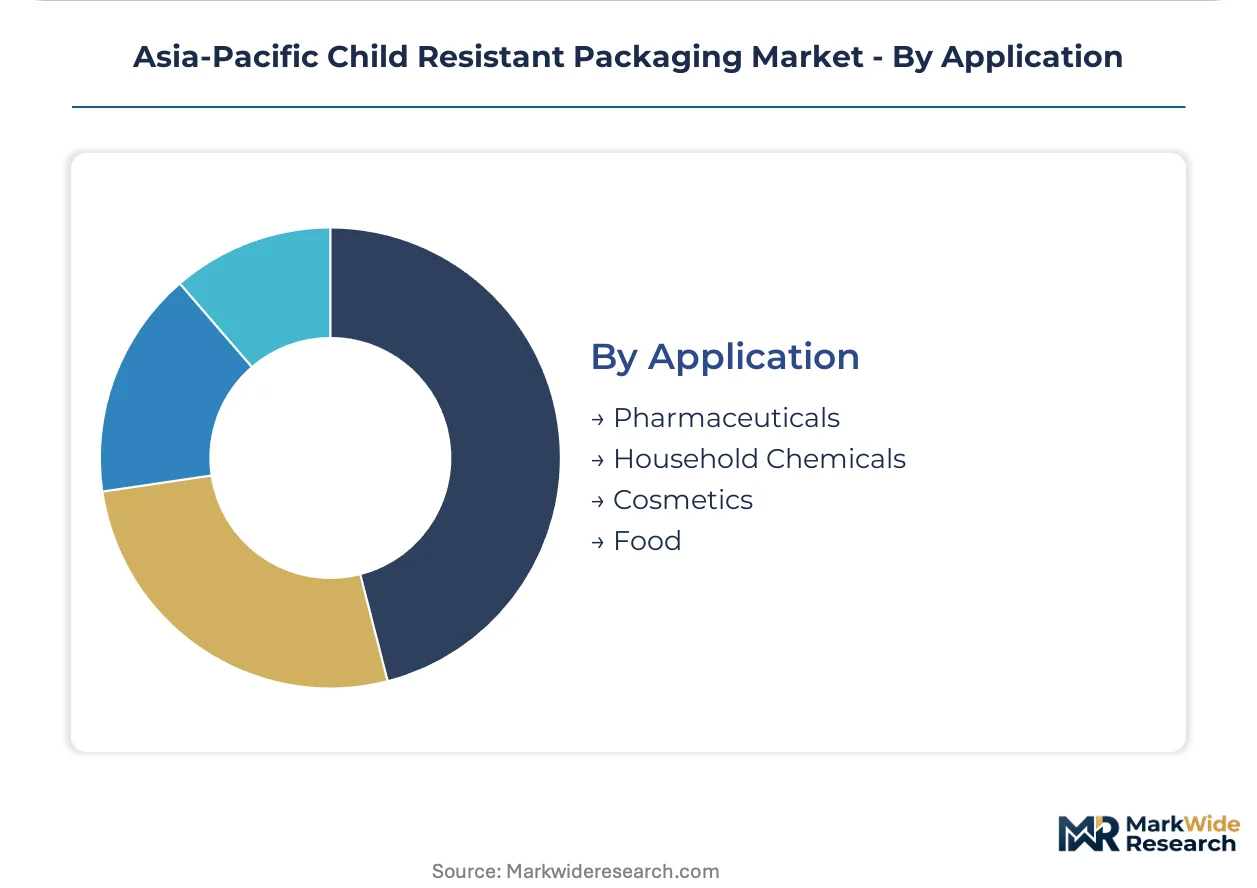
Application:
End-use sector determines the stringency of child safety standards and the acceptable cost premium for certified packaging.
- Pharmaceuticals:Schedule 4 and 8 medicines under Australian TGA rules mandate ISO 8317 compliance with batch-level torque documentation. Direct procurement relationships between Hyderabad packagers and certified molders are displacing distributor channels.
- Household Chemicals:India's CDSCO expansion into scheduled drug packaging has heightened awareness of child safety standards for bleach and detergent containers. Squeeze-and-slide formats with one-handed dispensing address this demand.
- Cosmetics:Travel-size and premium skincare brands in Japan favor unit-dose pouches with integrated tear-notch child resistance.
- Food:Minimal regulatory penetration currently, though nut and supplement packaging in Australia shows early adoption of voluntary standards.
Pharmaceuticals command the deepest margin pools. Household chemicals represent the steepest volume expansion path as standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin supply from Singapore's Jurong Island petrochemical cluster anchors material flows into Asia-Pacific child-resistant packaging converters. China's eastern manufacturing corridor and India's western pharmaceutical belt concentrate conversion capacity for domestic consumption and re-export. Regulatory divergence between CDSCO, NMPA, and TGA protocols forces redundant certification spending across the region.
China
Pharmaceutical contract packagers in Jiangsu and Zhejiang provinces drive demand for multilayer barrier bottles with integrated child-resistant neck finishes. NMPA alignment with ISO 8317 testing protocols reduces re-certification burdens for multinational suppliers entering domestic distribution. Suzhou and Hangzhou host the densest concentrations of injection molders serving both local brands and Southeast Asian export orders.
India
Generic drug manufacturers in Hyderabad and Mumbai retrofit push-and-turn closures onto standard bottles for scheduled medications under tightened CDSCO enforcement. The Drugs and Cosmetics Act mandates child-resistant standards for an expanding list of prescription drug categories. Maharashtra and Telangana states concentrate the nation's certified closure procurement relationships, displacing traditional distributor channels.
Japan
Clinical trial packaging and travel-size cosmetics in Tokyo and Osaka favor unit-dose pouches with integrated tear-notch child-resistant features. METI guidance on pharmaceutical packaging safety influences voluntary adoption standards beyond formal regulatory mandates. Kanto region converters specialize in flexible formats for moisture-sensitive drug trials requiring extended shelf-life validation.
Australia
TGA enforcement of ISO 8317 for Schedule 4 and 8 medicines tightens compliance verification for imported packaging components. Melbourne and Sydney-based contract manufacturers now demand batch-level torque test documentation from Southeast Asian suppliers. Victoria's pharmaceutical packaging sector leads domestic certification capacity for high-barrier biologics containers.
Indonesia
Southeast Asia's largest pharmaceutical market lacks mature child-resistant packaging infrastructure, creating first-mover opportunities for certified converters. Squeeze-and-slide mechanisms for household chemicals address regulatory gaps while one-handed dispensing suits local user preferences. Java-based packagers source components from Chinese and Indian suppliers pending domestic certification facility development.
Asia-Pacific Child Resistant Packaging Market Competitive Landscape
Multi-protocol certification investments dominate the current landscape as closure converters harden compliance capabilities across CDSCO, NMPA, and TGA jurisdictions simultaneously. The vendor base clusters around three strategic archetypes: integrated film-and-conversion networks, high-volume injection molding specialists, and glass-primary packaging integrators. Market position depends on simultaneous regulatory accreditations rather than scale alone. Geographic expansion and portfolio diversification represent the dominant competitive moves as suppliers chase Southeast Asian export flows.
Within the integrated network tier, Amcor plc exemplifies the archetype of film supply married to regional conversion assets. Berry Global Inc. and Gerresheimer AG occupy distinct positioning vectors—Berry represents high-volume plastic closure manufacturing, while Gerresheimer anchors glass-primary solutions with integrated child-resistant functionality. These three entities illustrate how material specialization and regulatory certification breadth determine competitive standing in a market where pharmaceutical tender requirements increasingly specify multi-jurisdiction compliance documentation.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Gerresheimer AG |
| WestRock Company |
| AptarGroup, Inc. |
| Winpak Ltd |
| Constantia Flexibles |
| Bilcare Limited |
| Körber Medipak Systems GmbH |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap molders across China's Jiangsu and Zhejiang provinces anchor regional supply discipline, converting polypropylene resins into certified closures under long-dated pharmaceutical contracts that bundle torque validation documentation with per-unit pricing. Their ownership structure limits aggressive price competition, preserving margin pools for CDSCO and NMPA dual-certified suppliers while forcing generic drug packagers in India to absorb resin volatility through contract renegotiation clauses.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from commodity converters, with batch-level torque documentation and ISO 8317 re-certification support included in long-term pharmaceutical contracts but unbundled for spot-market household chemical orders. Three-tier pricing structure across premium, standard, and economy levels reflects certification breadth, with dual-CDSCO-NMPA-accredited molders commanding 15-20% premiums over single-protocol competitors. Cost compression in standard-tier polypropylene closures is intensifying because crude-linked resin indices expose high-volume injection molders to margin squeeze. Generic drug packagers in Hyderabad exhibit the highest price sensitivity, while Australian TGA-compliant biologics manufacturers prioritize documentation reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical procurement guidelines are reshaping sourcing patterns, compelling multinational brands to qualify local closure suppliers in Maharashtra and Telangana alongside established Chinese vendors. Polypropylene resin flows from Singapore's Jurong Island petrochemical cluster, specialty barrier films from Japanese coextrusion specialists, and glass vial neck rings from European primary packaging integrators constitute critical input dependencies. Single-source vulnerability concentrates in certified mold tooling, where 16-20 week production cycles for push-and-turn closure dies create tender deadline risks. Distribution runs through direct procurement relationships between Hyderabad packagers and certified molders, displacing traditional trading intermediaries that previously mediated component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified conversion capacity scarcity across simultaneous CDSCO, NMPA, and TGA protocols props pricing power for qualified suppliers, with validation queue bottlenecks extending project timelines and concentrating volume with accredited molders. This supply-constrained structure favors incumbents holding multi-jurisdiction certifications while elevating entry costs for aspirant competitors.
For Market Incumbents: Anchor regional position through backward integration into polypropylene compounding capabilities that secure REACH-compliant resin supply for European-destined exports. Add captive torque-testing laboratory capacity in India's western pharmaceutical belt to bypass CDSCO certification queues and accelerate revenue recognition. Defend against glass-primary substitution in biologics by demonstrating multilayer barrier superiority for moisture-sensitive formulations under extended shelf-life validation protocols. For New Entrants and Emerging Players: Capture first-mover positioning in Indonesia's underpenetrated pharmaceutical packaging infrastructure, where domestic certification facility gaps force Java-based packagers to source from distant Chinese and Indian suppliers. Target household chemical applications with squeeze-and-slide convergence products that combine one-handed dispensing with pharmaceutical-grade barrier specifications. Establish go-to-market presence through technical partnership with established Southeast Asian distributors holding existing pharmaceutical channel relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap injection molders in China's eastern manufacturing corridor holding dormant NMPA certifications and underutilized cleanroom conversion capacity. Long-term viability over the five-to-ten year window rests on regulatory harmonization momentum that could collapse redundant validation spending into single-protocol acceptance. Watch for TGA-CDSCO mutual recognition agreement negotiations as the inflection signal that would revalue dual-certified asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Simultaneous CDSCO, NMPA, and TGA accreditation unlocks pharmaceutical tender eligibility across India's generic drug belt and Australia's biologics corridor. |
| Backward Integration into Polymer Compounding | In-house REACH-compliant resin formulation eliminates phthalate-related export barriers to European pharmaceutical brands. |
| Squeeze-and-Slide Product Line Expansion | Dual-use convergence for household chemicals and pharmaceuticals addresses Indonesia's regulatory gap while capturing one-handed dispensing preference. |
| Captive Torque Testing Laboratory Deployment | On-site ISO 8317 validation capability compresses project timelines and bypasses government certification queue bottlenecks. |
| Direct Procurement Channel Development | Relationship bypass of trading intermediaries in India's generic drug sector secures multi-year volume commitments from Hyderabad packagers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews covering pharmaceutical packaging procurement managers, closure converter operations directors, CDSCO regulatory affairs specialists, and polymer formulation chemists across India, China, and Australia. CDSCO scheduled drug notifications, NMPA closure-testing protocol alignments, TGA ISO 8317 enforcement guidelines, and Singapore petrochemical export statistics provided validation anchors. Bottom-up volume estimates from injection molding capacity utilization and top-down pharmaceutical packaging expenditure flows were triangulated against regional production cluster output data.
Granularity-level modeling disaggregated volume and value across product type, material composition, closure mechanism, and application sector, with additional dimensioning by regulatory jurisdiction cluster and certification tier. Segment-level CAGRs were derived from pharmaceutical production growth trajectories, scheduled drug expansion patterns under national pharmacopeia updates, and household chemical regulatory adoption curves. Input assumptions incorporated resin price elasticity, certification timeline distributions, and export flow redirection patterns between Chinese eastern corridor suppliers and Southeast Asian destination markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeia harmonization progress, polypropylene feedstock cost trajectories, and glass-primary packaging substitution rates in high-value biologics segments. Forecasts reflect documented assumptions regarding regulatory enforcement continuity, certification queue durations, and pharmaceutical tender specification evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market