
 Corrugated Mailers Market | 2026-2036
Corrugated Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Mailers Market Outlook
FSC Chain of Custody certification is rotating supplier eligibility across the corrugated mailers landscape. International Paper leverages its North American pulp integration to sustain cost advantages in kraft linerboard supply. Smurfit Kappa anchors European volume through its recycled fiber network and pan-regional converting footprint. WestRock competes on specialty coating capabilities that differentiate premium mailer grades for cosmetics shippers.
Corrugated mailers are rigid paper-based containers constructed from fluted paperboard laminated between flat linerboards, typically ranging from 200 to 350 grams per square meter in basis weight, designed to protect goods during single-parcel distribution. Die-cut mailers command premium positioning among e-commerce subscription services requiring tool-free assembly and printed brand surfaces. Recycled material grades are gaining volume fastest as brand owners face Scope 3 emissions disclosure requirements, though kraft paper variants still dominate margin pools in food-grade and cold-chain applications.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are reshaping material specifications and recyclability claims across European supply chains. ECHA substance restrictions limit certain adhesives and coatings, forcing converters to reformulate mailer constructions. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to internalize recycling infrastructure or absorb pass-through costs from integrated paper mills.
Market Dynamics
The corrugated mailers market is being fundamentally restructured by the EU Packaging and Packaging Waste Regulation's recyclability mandates, which are forcing converters to reformulate adhesive systems and linerboard specifications across European supply chains.
Growth Catalysts
- E-commerce fulfillment expansion:Subscription box services and direct-to-consumer apparel brands are driving demand for die-cut mailers with printed brand surfaces and tool-free assembly features.
- REACH chemical compliance:ECHA substance restrictions on certain coatings are accelerating adoption of water-based barrier treatments that maintain grease resistance without fluorochemicals.
- Recycled fiber infrastructure:Investments in European deinking and pulping capacity are expanding availability of high-performance recycled linerboard grades suitable for protective shipping applications.
Market Restraints
- Old corrugated container price volatility:OCC feedstock costs fluctuate with municipal collection rates and export demand to Asian paper mills, compressing converter margins during supply tightness.
- Kraft linerboard supply concentration:Integrated North American pulp producers control premium virgin fiber supply, creating dependency risk for European converters serving food-grade and cold-chain segments.
- Extended producer responsibility fees:Variable EPR cost structures across EU member states create pricing fragmentation and compliance complexity for pan-regional shippers.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution is creating demand for insulated corrugated mailers with phase-change material integration.
- Digital print personalization:Web-to-pack workflows enable batch-size-one customization for luxury cosmetics and gift subscription services.
- FSC Chain of Custody certification:Brand owner Scope 3 disclosure requirements are creating premium positioning for certified sustainable mailer grades in German and French markets.
Industry Challenges
- Adhesive reformulation timelines:ECHA's evolving substance restrictions require 18-24 month qualification cycles for new mailer constructions, delaying product launches.
- Die-cutting tooling capex:Custom mailer formats for subscription services require precision steel-rule die investments that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Mailers Market |
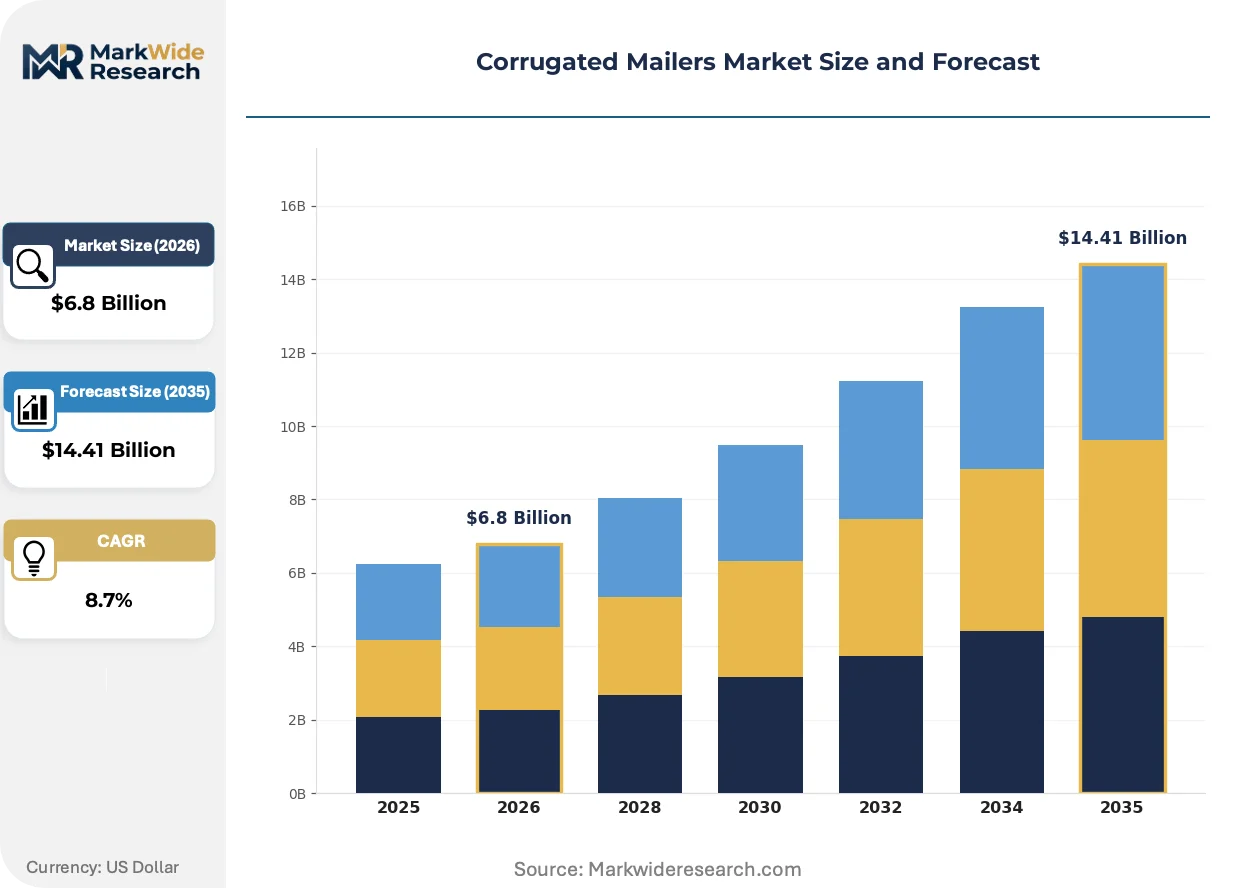
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Containers, Die-Cut Mailers, Foldable Mailers, Mailing Tubes Material: Fluted Paperboard, Kraft Paper, Recycled Material, Laminated Cardboard End User: E-Commerce, Retail, Food & Beverage, Cosmetics Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Packaging Corporation of America, Mondi Group, Rengo Co., Ltd., Oji Holdings, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Mailers Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape mailer construction standards, while digital production technologies are collapsing minimum order quantities for customized protective packaging.
Water-based barrier coatings are displacing polyethylene-laminated linerboards in food-contact mailer applications. Bakery and confectionery direct-to-consumer brands are specifying these treatments to meet EU single-use plastics directives. The shift is compressing demand for conventional extrusion-coated grades while expanding specialty coating capacity at European paper mills.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from mailer specifications. Converters must qualify fluorine-free alternatives for pizza boxes and prepared meal delivery formats. German and Italian food service distributors are demanding third-party verification of PFAS-free claims before contract renewal.
Brand owners are consolidating corrugated mailer procurement through sustainability scorecards that weight recycled content and carbon disclosure. Large e-commerce platforms are replacing fragmented supplier bases with approved vendor lists requiring FSC certification and science-based emissions targets. This concentration is most visible in French and Dutch fulfillment operations serving cross-border EU e-commerce.
Corrugated Mailers Market Segmentation
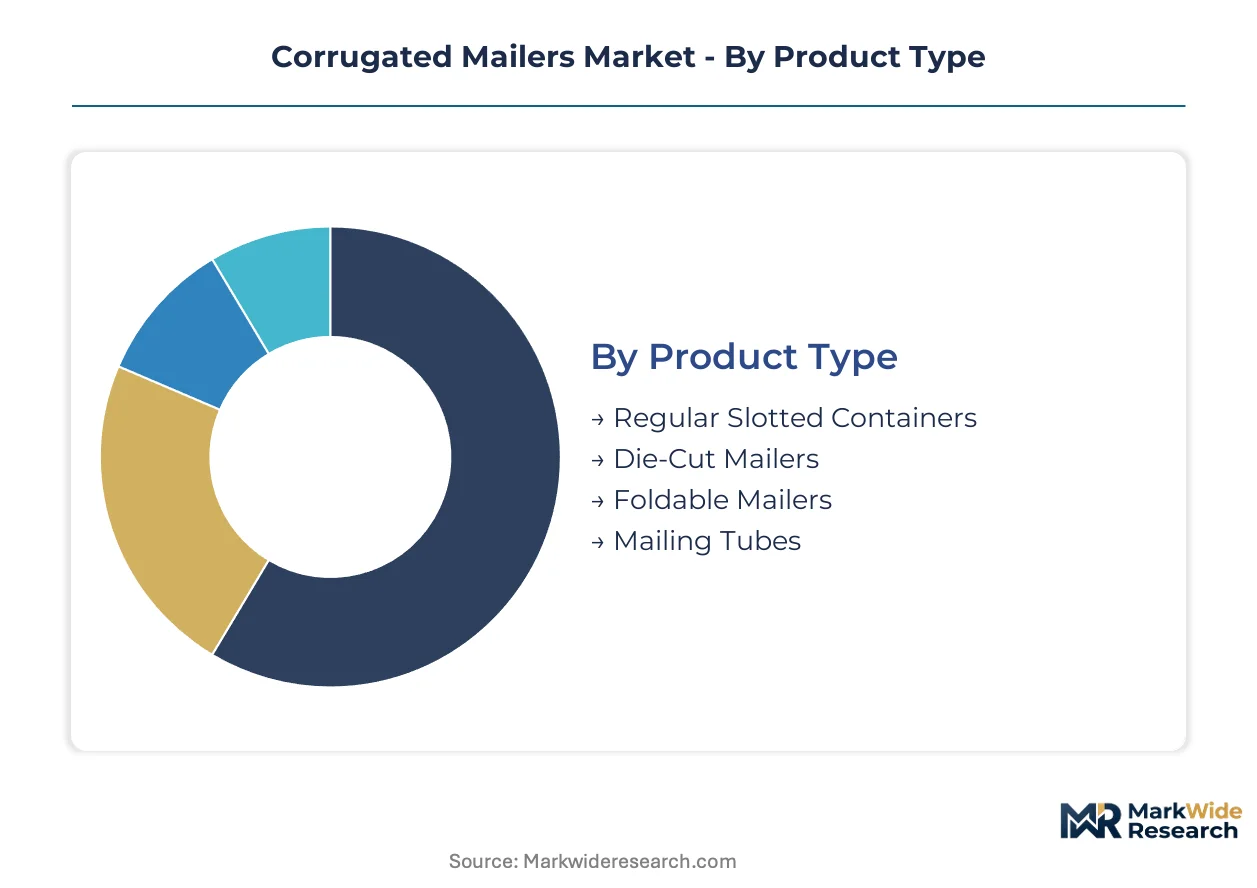
Corrugated mailer segmentation reveals distinct margin architectures across product construction, material sourcing, and channel economics. Procurement patterns diverge sharply between high-volume e-commerce fulfillment and specialized cold-chain applications.
Product Type:
Margin pools concentrate in precision-converted formats that reduce fulfillment labor and damage rates.
- Die-Cut Mailers:Engineered with pre-scored fold lines and integrated locking tabs that eliminate tape and void fill. Subscription box services in France and Germany specify these for tool-free assembly and direct-surface brand printing. Premium positioning reflects lower total fulfillment cost despite higher unit price.
- Regular Slotted Containers:Standard four-flap construction with taped closure dominates high-volume shipping for electronics and apparel. Demand clusters with third-party logistics providers serving pan-EU e-commerce platforms where cube utilization and stack strength outweigh unboxing experience.
- Foldable Mailers:Collapsible designs reduce inbound freight cost for converters and warehouse storage for distributors. Compact profile suits book and media shippers with predictable dimensional requirements.
- Mailing Tubes:Spiral-wound or convolute construction protects posters, blueprints, and rolled textiles. Niche volume reflects limited substitute competition from flat formats in document logistics.
The dominant share belongs to Regular Slotted Containers, while Die-Cut Mailers is closing the gap fastest.
Material:
Cost tier stratification separates virgin fiber grades from recycled alternatives with divergent performance specifications.
- Recycled Material:Post-consumer OCC-based linerboard with deinked fiber content meeting EN 643 Grade 1.02 standards. Dutch and Belgian converters leverage proximity to Antwerp-Rotterdam port recycling infrastructure. Scope 3 disclosure requirements from German retail chains are accelerating specification shifts.
- Kraft Paper:Unbleached virgin pulp linerboard with superior burst strength and moisture resistance. Cold-chain pharmaceutical distributors in Italy require this grade for temperature excursion protection. Virgin fiber concentration among North American integrated producers creates supply security premiums.
- Fluted Paperboard:Standard corrugated medium between linerboard facings, with flute profiles from E-flute to B-flute determining compression strength and printability. Volume production centers on FEFCO 0201 case styles.
- Laminated Cardboard:Polyethylene or bio-based barrier coatings for grease resistance in prepared meal delivery. REACH Annex XVII PFAS restrictions are forcing coating reformulation with 18-24 month qualification cycles.
Kraft Paper commands the pricing premium, though Recycled Material is expanding most quickly as EPR fees and carbon accounting reshape procurement scorecards.
End User:
Application intensity varies by damage sensitivity, return policy economics, and unboxing experience requirements.
- E-Commerce:Direct-to-consumer fulfillment with high return rates and damage liability exposure. French and German marketplaces are consolidating approved vendor lists around FSC certification and science-based emissions targets. Die-cut formats with printed interiors dominate premium positioning.
- Cosmetics:Fragile glass and pump-dispenser protection with shelf-ready presentation requirements. Italian and Spanish luxury brands specify rigid mailers with foam or molded pulp inserts. Color consistency and scuff resistance drive linerboard grade selection.
- Food & Beverage:Bakery, confectionery, and prepared meal distribution with barrier performance and food-contact compliance. Water-based coatings are displacing PE-laminated grades under EU single-use plastics directives.
- Retail:Store replenishment and ship-from-store operations with standardized case counts and pallet pattern optimization. Volume concentrates with pan-European grocery and apparel chains.
E-Commerce captures the dominant volume position, while Cosmetics shows the steepest expansion trajectory as unboxing video culture elevates packaging to brand touchpoint status.
Distribution Channel:
Customer type and order scale determine converter sales force deployment and inventory positioning.
- Direct Sales:Converter field sales serving national accounts with annual contract structures and collaborative design engineering. German automotive parts distributors and French pharmaceutical wholesalers negotiate specification lock-ins with volume commitments.
- Wholesale:Merchant distributors stocking standard FEFCO styles for same-day shipment to regional printers and packaging buyers. Inventory risk sits with distributors who aggregate fragmented demand.
- Online Retail:Digital catalog ordering of standard sizes with credit card payment and parcel freight delivery. Small e-commerce sellers and startup subscription services source here for low minimums and rapid turnaround.
- Others:Cooperative purchasing groups, packaging brokers, and reverse logistics providers serving specialized procurement situations.
Direct Sales holds the margin leadership, though Wholesale is gaining share fastest as mid-cap converters seek channel diversification without account management overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redrawing procurement geography across corrugated mailer supply chains. National implementation timelines and extended producer responsibility fee structures are concentrating converter investments in markets with harmonized compliance frameworks.
Germany
E-commerce fulfillment hubs in North Rhine-Westphalia and Bavaria are driving die-cut mailer specification for subscription services. The country's national packaging regulator enforces strict dual-system participation fees that favor high recycled-content grades. The Düsseldorf-Cologne corridor hosts converter clusters serving pan-EU automotive parts distributors with FSC-certified mailer programs.
France
Luxury cosmetics direct-to-consumer channels in Île-de-France are elevating unboxing experience requirements. ECHA REACH compliance mandates on adhesive chemistry are forcing 18-month reformulation cycles at converting facilities. The Lyon logistics cluster is emerging as a cold-chain mailer production center for pharmaceutical temperature-sensitive distribution.
Italy
Prepared meal delivery services in Lombardy and Emilia-Romagna are specifying water-based barrier coatings under EU single-use plastics directives. The national pharmaceutical regulator enforces strict temperature excursion documentation for biologics shipping. Milan-area converters are integrating phase-change materials into insulated mailer constructions for vaccine distribution.
United States
Third-party logistics consolidation in the Midwest and Southeast is standardizing regular slotted container procurement for high-volume e-commerce. EPA environmental justice screening is influencing siting decisions for new recycled fiber mills. The Chicago-Indianapolis corridor anchors North American linerboard supply integration with captive pulp production.
China
Cross-border e-commerce export hubs in the Yangtze River Delta are demanding foldable mailer formats for cube-optimized ocean freight. The Ministry of Ecology and Environment enforces dual carbon goals that restrict virgin fiber expansion. The Suzhou-Nantong manufacturing belt concentrates die-cutting capacity serving global subscription box brands.
Corrugated Mailers Market Competitive Environment
Player mix skews toward integrated paper producers with captive linerboard supply and specialty converters with coating differentiation capabilities. The vendor base separates into three tiers: North American integrated pulp producers controlling virgin fiber economics, European recycled fiber networks leveraging port-proximate OCC collection, and Asian scale converters serving export manufacturing. Consolidation pressure is intensifying through mill-level asset acquisitions and cross-border converting footprint expansion.
Among North American integrated producers, International Paper and WestRock exemplify the virgin fiber archetype with backward integration into kraft pulp production. Smurfit Kappa represents the European recycled fiber model with pan-regional converting density. These three anchors illustrate divergent strategic positions: captive raw material security versus circular economy compliance versus geographic coverage optimization.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| DS Smith |
| Packaging Corporation of America |
| Mondi Group |
| Rengo Co., Ltd. |
| Oji Holdings |
| Georgia-Pacific |
| Others |
Value Chain & Pricing Dynamics
FSC Chain of Custody certification gates supplier eligibility and price differentiation simultaneously, as German and French retail chains disqualify uncertified converters from approved vendor lists while paying premiums for verified sustainable grades. The EU Packaging and Packaging Waste Regulation tightens this filter by embedding recyclability mandates into procurement scorecards, forcing mailer producers to absorb certification costs or exit premium tier bidding.
Pricing Analysis
Certification level creates the primary spread between mailer tiers, with FSC-certified grades commanding substantial premiums over uncertified alternatives in cosmetics and pharmaceutical channels. Three-tier pricing structure across premium, standard, and economy levels reflects linerboard grade, recycled content percentage, and barrier coating complexity. Cost compression in recycled fiber grades is intensifying because OCC feedstock volatility compresses converter margins during supply tightness. Third-party logistics providers serving pan-EU e-commerce platforms exhibit highest price sensitivity, while luxury cosmetics brands prioritize unboxing experience over unit cost.
Supply Chain Analysis
Antwerp-Rotterdam port infrastructure underwrites European recycled fiber availability, with OCC collection networks feeding deinking capacity concentrated in Belgium and the Netherlands. Kraft pulp supply draws from integrated North American producers, while fluting medium production centers on German and Italian paper mills. Single-source vulnerability persists in virgin linerboard grades controlled by captive pulp producers. Distribution runs through converter direct sales for national accounts, wholesale merchants for regional fragmentation, and digital catalog platforms for small e-commerce sellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated mailer procurement is consolidating around sustainability scorecards that weight certification and carbon disclosure, with design engineering services and inventory management programs expanding faster than commodity box sales. Recurring revenue from vendor-managed inventory and collaborative packaging engineering now outpaces hardware growth in German and French fulfillment markets.
For Market Incumbents: Shield margin position by deepening backward integration into recycled fiber collection networks near Antwerp-Rotterdam ports, and accelerate fluorine-free barrier coating qualification before ECHA Annex XVII enforcement tightens. Water-based coating R&D investment represents the critical lever against specialty coating competitors. For New Entrants and Emerging Players: Lead with digital print personalization capabilities targeting French luxury cosmetics subscription services, where batch-size-one customization commands premium positioning. Italian pharmaceutical cold-chain expansion offers the most penetrable white space, with phase-change material integration expertise as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty coating capacity as REACH compliance forces 18-24 month reformulation cycles. Five-to-ten year viability favors converters with FSC certification infrastructure and pharmaceutical temperature-sensitive qualifications. Monitor EPR fee harmonization progress across EU member states as the signal for pan-regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Coating Qualification | ECHA REACH Annex XVII compliance secures food-service contracts with German distributors. |
| FSC Chain of Custody Certification Investment | Approved vendor list eligibility with French and German retail chains requires verified sustainable sourcing. |
| Phase-Change Material Integration | Italian pharmaceutical temperature-sensitive distribution demands insulated mailer construction expertise. |
| Digital Print Personalization Capacity | Web-to-pack workflows capture batch-size-one demand from luxury cosmetics subscription services. |
| Recycled Fiber Network Expansion | Antwerp-Rotterdam port proximity reduces OCC feedstock cost volatility for European converters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade association filings, customs records, and mill capacity disclosures. Conversations with converter operations managers, corrugated procurement leads at third-party logistics providers, sustainability directors at German retail chains, and barrier coating R&D specialists informed demand segmentation. Secondary validation drew from FEFCO industry statistics, ECHA substance restriction updates, and paper mill environmental disclosure reports. Bottom-up volume builds triangulated against top-down macroeconomic sizing.
Segmentation dimensions modeled include mailer construction type, linerboard grade tier, end-use industry, and distribution channel complexity across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates and regulatory compliance cost pass-through assumptions. Forecast inputs weighted pharmaceutical cold-chain expansion velocity and digital print adoption curves in cosmetics channels.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation and ECHA REACH substance restriction timelines; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EPR fee harmonization and OCC export demand patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market