
 Baby Care Packaging Market | 2026-2036
Baby Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Care Packaging Market Analysis
Subscription-based refill services is restructuring revenue models in baby care packaging, shifting unit economics from one-time purchases toward recurring replenishment cycles. Amcor plc leverages its flexible film expertise to supply pouch-based refill systems for major diaper brands. Mondi Group anchors European demand through sustainably sourced paperboard solutions for premium baby product lines. Berry Global Group, Inc. dominates North American injection-molded rigid container production for lotion and cream applications.
Baby care packaging encompasses engineered containment systems designed to preserve product integrity, prevent contamination, and enable controlled dispensing for infant hygiene and skincare products; these solutions typically incorporate multi-layer barrier films, child-resistant closures, and tamper-evident seals manufactured through blow molding, thermoforming, or extrusion processes. Flexible pouches now lead volume growth in diaper and wipe segments due to reduced material weight and improved shelf efficiency. Rigid containers sustain higher margin pools in lotions and creams where pump-dispensing precision commands premium positioning. Paperboard material types are gaining structural share among eco-conscious retailers seeking curbside-recyclable primary packaging alternatives.
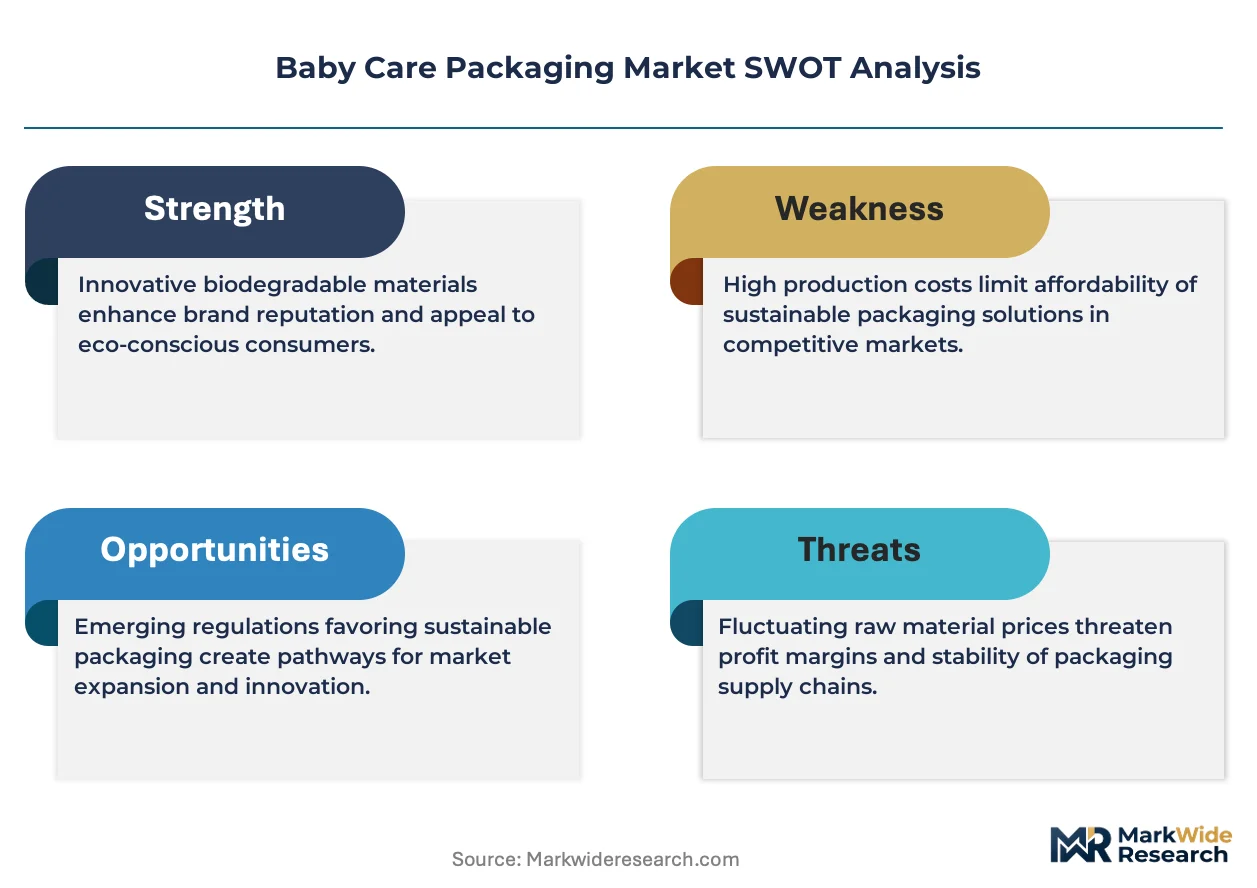
FDA regulates indirect food-contact substances under 21 CFR, while EPA oversees chemical safety through TSCA, and both frameworks directly shape permissible resin compositions in U.S. baby care packaging. The EU REACH regulation and F-Gas Regulation constrain fluorinated barrier chemistries and propellant systems used in European aerosol dispensers. Stakeholders must monitor evolving state-level extended producer responsibility laws and chemical disclosure mandates that will determine which material platforms retain market access across key selling regions.
Market Dynamics
Subscription-based refill systems are restructuring revenue models across baby care packaging, shifting unit economics from one-time purchases toward recurring replenishment cycles anchored by pouch-based flexible formats.
Growth Catalysts
- REACH chemical disclosure mandates:European retailers accelerate adoption of mono-material pouches to preempt compliance costs and secure shelf placement.
- Flexible barrier films:Multi-layer coextrusion advances enable oxygen and moisture protection at reduced caliper, cutting shipping weights for diaper refill packs.
- China tier-one city concentration:Dual-income households in Shanghai and Beijing prioritize convenience-oriented formats with single-hand dispensing features.
Market Restraints
- Resin input volatility:Polypropylene and polyethylene price swings compress margins for rigid container producers serving lotion segments.
- Fluorinated barrier restrictions:EU F-Gas Regulation and state-level PFAS limits in US jurisdictions constrain high-performance film options for wipe packaging.
- Curbside recyclability gap:Multi-layer laminates face rejection from municipal sorting facilities, limiting circular claims in North American retail channels.
Strategic Opportunities
- Indian urban middle-class expansion:Metro markets in Mumbai and Delhi present underpenetrated demand for pump-dispense skincare formats.
- IRActivated domestic content credits:US manufacturers can capture tax incentives by reshoring injection-molded closure production.
- Digital printing convergence:Variable-data decoration enables regional SKU customization without plate changeover costs.
Industry Challenges
- Child-resistant certification timelines:ASTM D3475 testing protocols extend product launch windows by four to six months for topical cream dispensers.
- Legacy ERP integration:Refill subscription platforms require real-time inventory APIs that conflict with established batch-oriented manufacturing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Care Packaging Market |
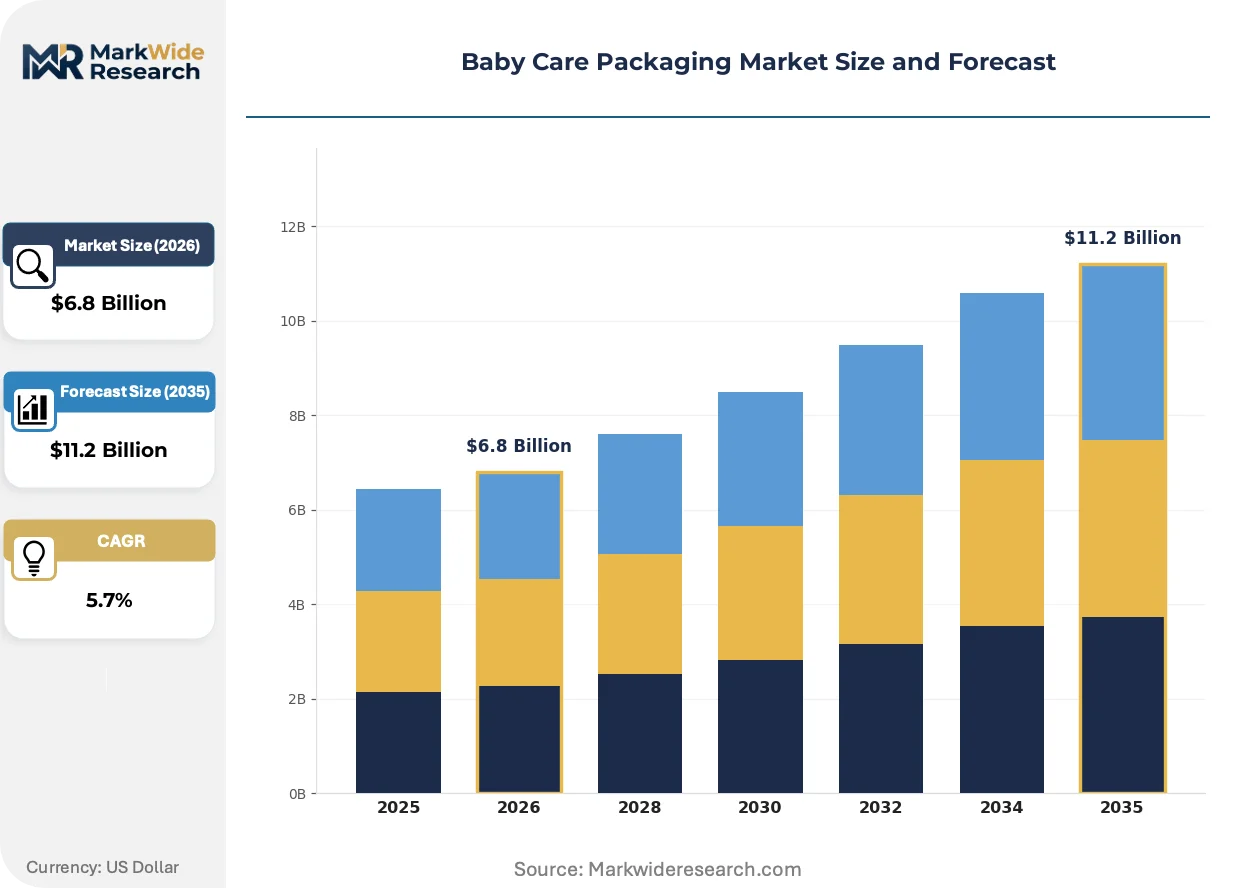
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Rigid Containers, Bottles, Tubes Material Type: Plastic, Glass, Metal, Paperboard End User: Retailers, E-commerce Platforms, Distributors, Manufacturers Product Type: Diapers, Wipes, Lotions, Creams |
| Companies Covered | Amcor plc, Sonoco Products Company, Mondi Group, WestRock Company, Smurfit Kappa Group plc, Berry Global Group, Inc., DS Smith Plc, AptarGroup, Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Care Packaging Market Emerging Trajectories
Material science advances and regulatory tightening are compressing acceptable chemistries while elevating performance requirements for infant-contact surfaces.
Mono-material polyethylene pouches is unifying the diaper refill segment by eliminating aluminum oxide barrier layers. Major retail chains in Germany and France now mandate recyclable single-polymer construction for private-label wipe packaging. This unification is collapsing the historical premium attached to multi-layer laminate expertise.
EPA TSCA Section 6 restrictions on phthalates and bisphenols are forcing reformulation of polycarbonate and PVC components in pump mechanisms. US lotion brands face accelerated compliance deadlines compared to cosmetic-grade packaging exemptions. Rigid container suppliers are responding with bio-based polypropylene certifications from ISCC PLUS mass-balance schemes.
Direct-to-consumer subscription bundling is displacing conventional retail replenishment patterns among millennial parent cohorts. Online-native brands now capture recurring revenue through auto-ship algorithms calibrated to diaper size progression. This channel rotation concentrates in US coastal metropolitan markets where delivery density supports unit economics.
Baby Care Packaging Market Segmentation
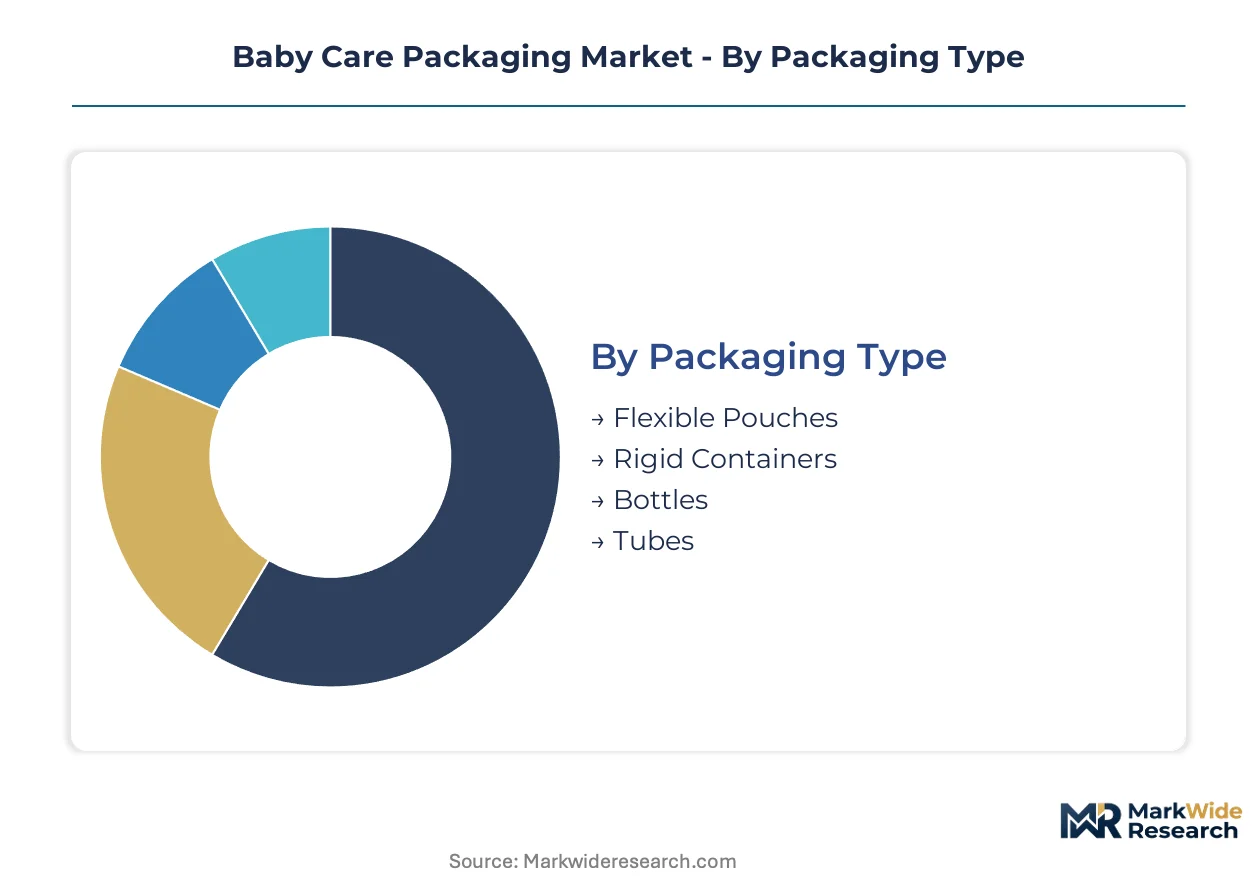
Packaging format selection in baby care hinges on liquid viscosity, dispensing precision needs, and shelf-life requirements. Material and channel configurations determine margin capture and regulatory compliance pathways across infant hygiene categories.
Packaging Type:
Flexible pouches operate as standalone refill systems, while rigid containers, bottles, and tubes embed into broader dispensing ecosystems with pump or squeeze mechanisms.
- Flexible Pouches:Multi-layer polyethylene laminates with spout fitments enable lightweight, collapsible containment for diaper and wipe refills. Demand clusters in subscription-based direct-to-consumer channels where shipping weight reduction drives unit economics. Mono-material construction advances are displacing aluminum oxide barriers under EU retailer mandates.
- Rigid Containers:Injection-molded polypropylene or polyethylene vessels provide dimensional stability for stacked retail display and precise pump-actuated dispensing. North American lotion brands specify these for child-resistant closure integration, though resin price volatility compresses converter margins.
- Bottles:Blow-molded HDPE or PET constructions with nipple-compatible neck finishes serve liquid formula and wash applications.
- Tubes:Laminated or extruded plastic cylinders with flip-top or screw closures target travel-size and sample formats.
Volume placements concentrate in Flexible Pouches; the faster expansion belongs to Rigid Containers as pump-dispense skincare gains premium positioning.
Material Type:
Cost tiers separate commodity resins from certified substrates, with bio-based alternatives commanding structural premiums in European retail channels.
- Plastic:Polypropylene dominates injection-molded closures and rigid vessels through FDA 21 CFR compliance for indirect food contact. Polyethylene flexible films capture diaper refill volume via reduced gauge multi-layer coextrusion. REACH chemical disclosure mandates are accelerating ISCC PLUS mass-balance certifications for bio-based polypropylene alternatives.
- Paperboard:Solid bleached sulfate and coated unbleached kraft grades enable curbside-recyclable primary packaging for premium baby product lines. German and French retail chains now mandate single-material construction for private-label wipe cartons.
- Glass:Borosilicate and soda-lime compositions serve niche preservative-free skincare positioning.
- Metal:Aluminum tubes and aerosol cans retain limited share in barrier-sensitive pharmaceutical-grade applications.
Plastic retains dominant volume placement; paperboard is climbing the fastest as ESG procurement criteria harden across European retail.
End User:
Channel concentration shapes order cadence and customization requirements, with digital-native platforms demanding real-time inventory APIs incompatible with legacy batch systems.
- E-commerce Platforms:Direct-to-consumer subscription algorithms calibrate replenishment to diaper size progression, concentrating in US coastal metropolitan markets with delivery density supporting unit economics. Auto-ship bundling displaces conventional retail replenishment among millennial parent cohorts.
- Retailers:Mass merchandisers and specialty baby chains specify shelf-ready secondary packaging with retail-specific SKU proliferation. Digital printing convergence enables regional customization without plate changeover costs.
- Distributors:Wholesale intermediaries aggregate fragmented brand portfolios for institutional and regional retail placement.
- Manufacturers:Contract packagers and co-manufacturers specify packaging compatible with multi-brand filling line changeovers.
Volume placements concentrate in Retailers; the steepest expansion trajectory belongs to E-commerce Platforms as subscription bundling restructures replenishment patterns.
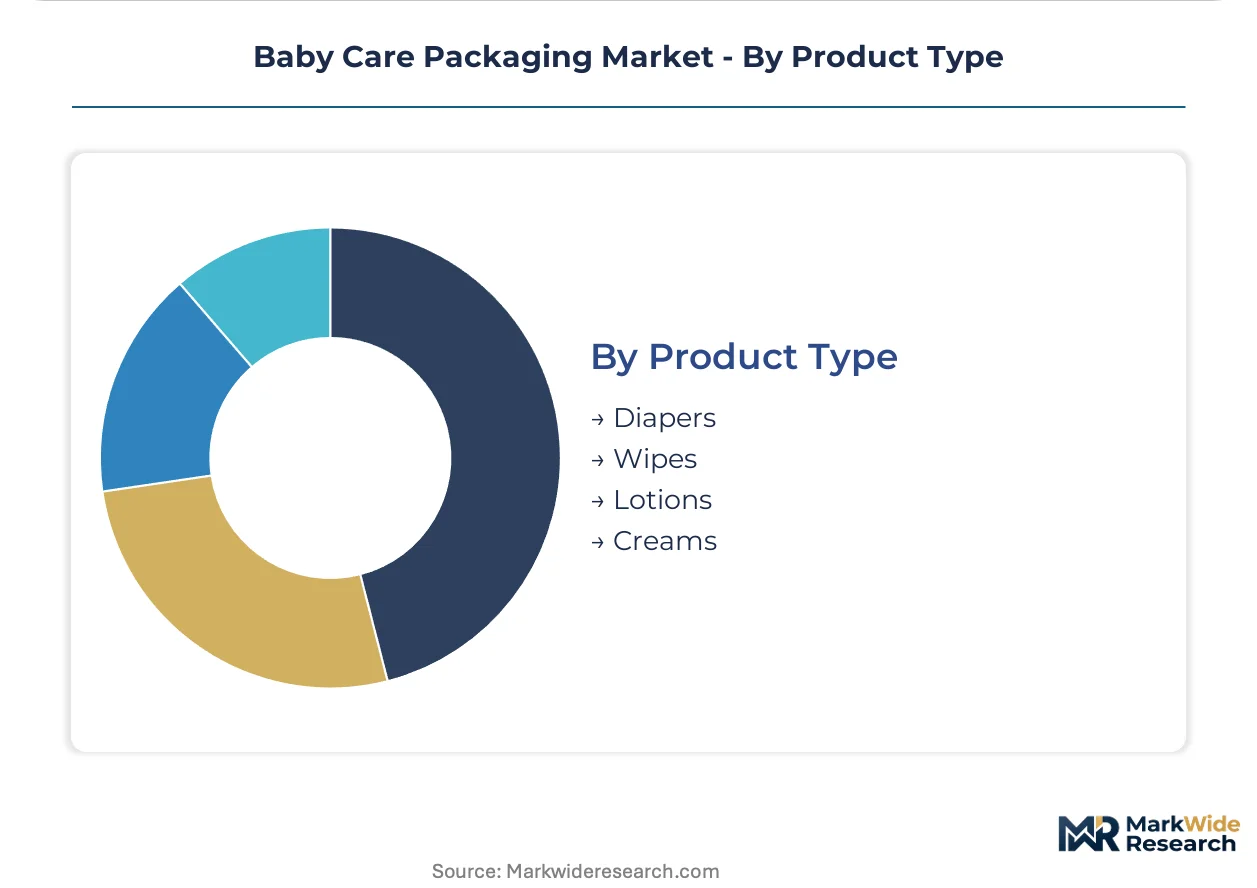
Product Type:
Application viscosity and usage frequency determine barrier specifications, with high-moisture categories demanding superior oxygen and vapor protection.
- Diapers:Bulk absorbent core products require breathable yet liquid-impermeable films to prevent moisture ingress while allowing vapor transmission. Flexible pouch refill systems now lead volume growth through reduced material weight and improved shelf efficiency.
- Wipes:Saturated nonwoven substrates demand high-barrier packaging to prevent desiccation and preservative degradation. EU F-Gas Regulation and state-level PFAS limits constrain fluorinated film options, forcing migration to mono-material polyethylene constructions.
- Lotions:Medium-viscosity emulsions require pump-dispensing precision that commands premium positioning in rigid containers.
- Creams:High-viscosity occlusive formulations utilize tube or jar formats with wide-mouth access.
Volume placements concentrate in Diapers; the fastest share gain belongs to Wipes as on-the-go convenience formats proliferate in dual-income households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the most concentrated demand cluster for convenience-oriented baby care packaging formats, where dual-income households in China's tier-one cities drive premium pouch adoption through subscription channels.
United States
Coastal metropolitan markets from Boston to Seattle concentrate direct-to-consumer subscription bundling for diaper refill systems. EPA TSCA Section 6 restrictions on phthalates and bisphenols force accelerated reformulation of polycarbonate pump components in topical cream dispensers. Berry Global Group, Inc. anchors North American injection-molded rigid container production from its manufacturing footprint across the Midwest and Southeast.
Germany
Retail chains in Frankfurt and Munich now mandate mono-material polyethylene construction for private-label wipe packaging under ECHA REACH chemical disclosure protocols. The EU F-Gas Regulation constrains fluorinated barrier chemistries previously standard in high-performance films. Mondi Group supplies sustainably sourced paperboard solutions from its integrated mill network in Bavaria and Baden-Württemberg.
China
Beijing's dual-income households prioritize single-hand dispensing features for on-the-go convenience formats. NMPA and SAMR oversight of infant-contact material safety tightens permissible chemical thresholds in imported plastic components. Yangtze River Delta manufacturing clusters around Suzhou and Ningbo produce multi-layer coextruded films for regional diaper brands.
India
Mumbai and Delhi present underpenetrated demand for pump-dispense skincare formats among urban middle-class consumers. BIS certification requirements for food-contact plastics extend to infant hygiene packaging categories. Gujarat's petrochemical corridor near Vadodara supplies polypropylene resin to emerging domestic converters serving regional lotion brands.
France
Paris-based premium baby product lines specify curbside-recyclable paperboard primary packaging under retailer ESG procurement criteria. ANSM oversight of medical-grade infant products influences barrier specifications for pharmaceutical-positioned skincare. The Auvergne-Rhône-Alpes region hosts flexible packaging converters developing aluminum oxide-free barrier alternatives.
Baby Care Packaging Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the baby care packaging landscape, where integrated resin-to-converter operations face specialized flexible film innovators. The vendor base stratifies into three tiers: multinational integrated packaging conglomerates, regional rigid container specialists, and niche subscription-platform suppliers. Two dominant competitive moves define current positioning: backward integration into resin compounding to secure bio-based polypropylene certifications, and strategic partnerships with direct-to-consumer brands to capture recurring refill revenue streams.
Among integrated packaging conglomerates, Amcor plc and Mondi Group exemplify divergent geographic anchoring strategies. Amcor plc occupies a position within the flexible film archetype, supplying pouch-based systems from its global manufacturing network. Mondi Group represents the paperboard-forward specialization tier, leveraging European fiber sourcing for curbside-recyclable formats. Berry Global Group, Inc. sits within the North American rigid container segment, anchoring injection-molded production for lotion and cream pump applications.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| Mondi Group |
| WestRock Company |
| Smurfit Kappa Group plc |
| Berry Global Group, Inc. |
| DS Smith Plc |
| AptarGroup, Inc. |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ISCC PLUS bio-based polypropylene and commodity resin tiers manifests in both pricing premiums and supply chain configurations, with European retailers commanding mass-balance documentation while North American converters absorb spot-market volatility.
Pricing Analysis
Margin tightening in rigid container segments reflects polypropylene price swings and child-resistant closure certification costs. Three-tier pricing structure across premium certified, standard food-grade, and economy commodity resin levels separates subscription-format pouch suppliers from mass-market converters. Cost-down pressure on injection-molded lotion vessels accelerates because dual-income households in tier-one Chinese cities prioritize convenience features over unit price. Brand managers at direct-to-consumer platforms exhibit lowest price sensitivity; mass merchandisers in India show highest.
Supply Chain Analysis
Polyethylene resin supply rests on Gulf Coast petrochemical complexes in the United States, Yangtze River Delta integrated refineries in China, and Gujarat corridor producers in India. Multi-layer coextrusion films and injection-molded pump components draw from these feedstock clusters. Single-source vulnerability concentrates in specialty barrier film additives constrained by EU F-Gas Regulation. Distribution runs through brand-direct subscription platforms, retail consolidation centers, and regional co-manufacturer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material polyethylene pouch technology is displacing aluminum oxide multi-layer laminates, forcing converters to retool extrusion lines and recertify barrier performance.
For Market Incumbents: Hedge resin cost exposure through backward integration into bio-based polypropylene compounding or long-term offtake agreements with ISCC PLUS-certified suppliers. Defend subscription-channel relationships against digital-native entrants by embedding real-time inventory APIs. Child-resistant ASTM D3475 certification timelines represent a moat worth extending through regulatory affairs investment. For New Entrants and Emerging Players: Enter via pump-dispense skincare formats in Mumbai and Delhi metro corridors where urban middle-class penetration remains below coastal Chinese benchmarks. Target e-commerce subscription bundling with auto-ship algorithms calibrated to diaper size progression. Lead with digital-printed variable decoration enabling regional SKU customization without plate costs. For Investors and Strategic Acquirers: Re-rating potential sits with flexible film converters possessing mono-material barrier expertise given EU retailer mandates collapsing historical laminate premiums. Five-to-ten-year viability favors asset-light designers partnered with direct-to-consumer brands over capital-heavy integrated conglomerates. Watch for state-level PFAS restriction acceleration as inflection trigger for aluminum oxide-free technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Compounding | ISCC PLUS certification secures European retail access under REACH disclosure mandates. |
| Direct-to-Consumer Subscription Platform Partnership | Recurring refill revenue displaces one-shot retail economics in coastal US metros. |
| Mono-Material Pouch Manufacturing Scale-Up | Aluminum oxide elimination satisfies German and French retailer ESG procurement criteria. |
| Real-Time Inventory API Development | Legacy ERP integration enables auto-ship algorithms for millennial parent cohorts. |
| Digital Printing Convergence Investment | Variable-data decoration reduces plate changeover costs for regional SKU proliferation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging procurement managers at major diaper brands, flexible film plant engineers, retail category buyers, subscription-platform operations heads, and regulatory affairs specialists at converters. FDA 21 CFR submissions, EPA TSCA Section 6 dockets, ECHA REACH registration databases, and EU F-Gas Regulation implementation reports provided compliance pathway documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Reconciling production capacity announcements with import-export statistics and channel inventory positions shaped the analytical framework across the analysis window. Segmentation dimensions modeled include packaging format, material type, product category, and channel configuration. CAGRs derived from elasticity-adjusted demand curves incorporating dual-income household formation rates and e-commerce penetration trends. Infant-contact material safety threshold tightening and resin price volatility surfaced as key forecast sensitivities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction timelines or polypropylene supply disruptions. Projections reflect documented assumptions on regulatory implementation schedules and substitution elasticity. A small set of triggers—state-level chemical disclosure mandates, EU retailer mono-material deadlines, and subscription-platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market