
 APAC Baby Food Packaging Market | 2026-2036
APAC Baby Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Baby Food Packaging Market Outlook
Organic infant formula and toddler snack categories are realigning packaging procurement priorities across APAC. Amcor PLC leverages its regional flexibles footprint to serve multinational brand owners expanding pouch formats in China and India. Huhtamaki Oyj anchors its position through molded fiber and paperboard innovation targeting Southeast Asian markets with tightening plastic restrictions. Tetra Laval dominates aseptic carton supply for ambient-stored baby cereals, sustaining volume leadership through dairy-processing co-location strategies.
APAC baby food packaging encompasses engineered containment systems designed to preserve nutritional integrity, ensure portion-controlled dispensing, and comply with infant-specific food-contact safety protocols. These systems employ multi-layer barrier films with oxygen transmission rates below 0.5 cc/m²/day, retort-compatible polypropylene structures, and tamper-evident closures to prevent contamination across ambient, chilled, and frozen distribution chains. Flexible pouches with spout-and-cap integration are capturing the fastest growth trajectory as parents prioritize one-handed feeding convenience and reduced food waste. Glass jars retain margin concentration in premium organic segments where brand equity depends on visual product transparency and perceived purity. Biodegradable films remain structurally immature at scale, though pilot deployments in South Korea and Japan signal longer-term material transition potential.
China's SAMR enforces GB 4806 food-contact material standards that mandate migration testing for infant formula packaging, while Japan's PMDA and METI coordinate on pharmaceutical-grade hygiene expectations extending into functional baby food categories. India's FSSAI is tightening labeling and shelf-life declaration requirements that directly impact packaging surface area and print specification decisions. Stakeholders must monitor how ASEAN harmonization of food-contact regulations reshapes cross-border supply chain qualification costs and format standardization timelines.
Market Dynamics
Urban millennial parents across China, India, and Southeast Asia are demanding single-serve flexible pouches and organic-ready formats, forcing brand owners to compress development cycles and reconfigure portion architecture around convenience-first consumption patterns.
Growth Catalysts
- China's GB 4806 food-contact standards:Migration testing mandates for infant formula packaging are elevating barrier film specifications and disqualifying substandard suppliers, tightening vendor qualification pools.
- Flexible pouch spout-and-cap integration:One-handed feeding convenience is capturing parent preference in tier-one Chinese cities and Indian metropolitan clusters, accelerating format migration from glass jars.
- E-commerce subscription models:Direct-to-parent delivery platforms in Shanghai, Beijing, and Mumbai are reshaping how packaging value is captured through recurring replenishment cycles.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:Barrier film feedstock relies on concentrated petrochemical suppliers in Northeast Asia, exposing converters to input volatility and allocation risk.
- Biodegradable film structural immaturity:Pilot deployments in South Korea and Japan demonstrate that polylactic acid and polyhydroxyalkanoate films lack the oxygen barrier performance required for retort baby food applications at commercial scale.
- Japan's METI pharmaceutical-grade hygiene expectations:Functional baby food categories face extended qualification timelines and elevated cleanroom manufacturing costs that compress margin structures for mid-tier brands.
Strategic Opportunities
- India's tier-two and tier-three urban corridors:Underpenetrated parent populations in cities like Pune, Ahmedabad, and Surat present whitespace for portion-controlled formats adapted to emerging middle-class purchasing power.
- ASEAN harmonization of food-contact regulations:Cross-border standardization initiatives are reducing supply chain qualification costs and enabling format standardization timelines across Vietnam, Thailand, and Indonesia.
- Molded fiber and paperboard convergence:Huhtamaki's innovation pipeline targets plastic-restricted Southeast Asian markets with fiber-based containment systems that satisfy tightening municipal waste ordinances.
Industry Challenges
- Migration testing laboratory capacity:China's SAMR-accredited facilities face bottlenecks as GB 4806 compliance requirements expand, extending certification timelines for new packaging submissions.
- Retort-compatible polypropylene coextrusion expertise:Thin-gauge high-barrier structures require specialized extrusion engineering talent that concentrates in Japan and South Korea, creating recruitment friction for regional converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Baby Food Packaging Market |
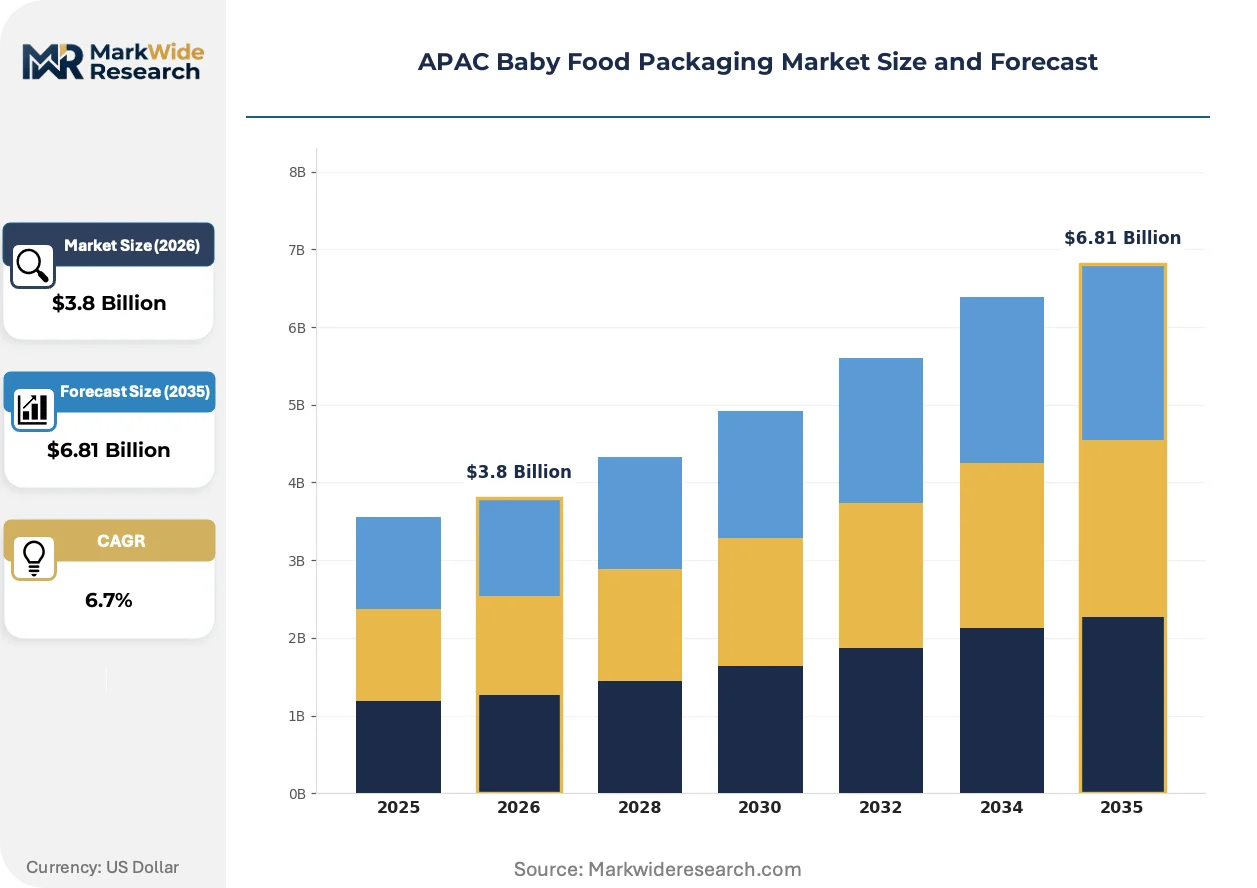
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jar, Flexible Pouch, Rigid Container, Tetra Pack Material: Plastic, Aluminum, Paperboard, Biodegradable Film Closure Type: Screw Cap, Peel-off Lid, Child-resistant Closure, Zip Lock Sales Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Amcor PLC, Huhtamaki Oyj, Berry Global Inc., Aptar Group Inc., Winpak Ltd., Tetra Laval, Uflex Ltd., DS Smith Plc, Ardagh Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Baby Food Packaging Market Strategic Shifts
Active material science breakthroughs and regulatory tightening are compressing format innovation cycles while parent behavioral shifts are redefining how packaging value is communicated and monetized across distribution channels.
Spouted flexible pouches with integrated child-resistant closures are integrating oxygen scavenger layers and laser-perforated venting systems to extend ambient shelf stability without preservative additives. Premium organic brands in China's tier-one cities are adopting these structures fastest, compressing the traditional glass jar segment's margin concentration as parents prioritize portability and reduced food waste over visual transparency.
Japan's METI guidelines on food-contact material safety are extending pharmaceutical-grade hygiene expectations into functional baby food categories, mandating particulate-controlled manufacturing environments that disqualify standard food-grade converters. This regulatory elevation is forcing brand owners to consolidate supplier relationships around qualified cleanroom operators, compressing the vendor base and extending qualification timelines for new market entrants.
Subscription-based replenishment platforms are displacing traditional retail stock-up behavior among urban millennial parents in Shanghai, Mumbai, and Jakarta. Direct-to-consumer channels now demand packaging optimized for individual shipment durability rather than palletized retail distribution, forcing structural redesigns around drop-test performance and single-unit protective features.
APAC Baby Food Packaging Market Segmentation
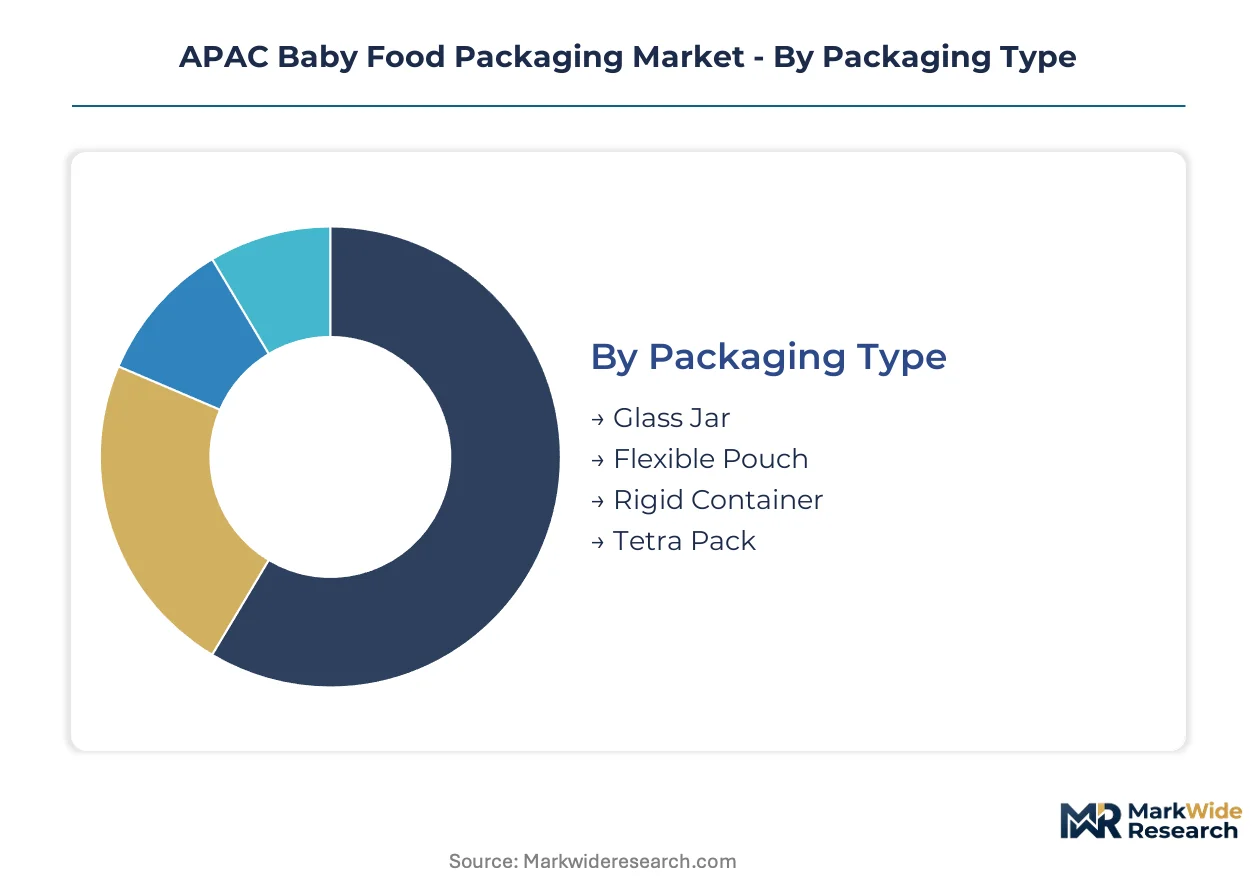
Packaging format decisions in APAC baby food directly determine compliance pathway complexity and shelf-life performance. Material and closure specifications must align with China's GB 4806 migration testing, Japan's METI hygiene protocols, and India's FSSAI labeling mandates.
Packaging Type:
Certification burden varies sharply by format: flexible pouches face the steepest barrier film qualification requirements under GB 4806, while glass jars trigger pharmaceutical-grade hygiene expectations in Japan's functional food categories.
- Flexible Pouch:Multi-layer coextruded structures with ethylene-vinyl alcohol barrier layers and integrated spout-and-cap systems achieve oxygen transmission below 0.5 cc/m²/day. Demand concentrates in Shanghai, Beijing, and Mumbai where millennial parents prioritize one-handed feeding convenience and reduced food waste over traditional formats.
- Glass Jar:Borosilicate and soda-lime glass formats with vacuum-sealed metal closures retain premium positioning in China's tier-one organic segments. Visual transparency supports brand equity around perceived purity, though weight and fragility limit e-commerce shipment viability.
- Rigid Container:Polypropylene and polyethylene terephthalate injection-molded tubs serve chilled and frozen distribution chains across Southeast Asian markets.
- Tetra Pack:Aseptic carton laminates dominate ambient-stored baby cereals through dairy-processor co-location strategies in Japan and South Korea.
Flexible pouch sits at the top of the volume ranking, with rigid container climbing the fastest as plastic-restricted municipalities expand across Southeast Asia.
Material:
Cost tier stratification separates commodity petrochemical feedstocks from emerging bio-based alternatives, with qualification timelines and barrier performance driving procurement decisions.
- Plastic:Polypropylene, polyethylene, and polyethylene terephthalate structures form the baseline for retort-compatible and aseptic applications. China's SAMR-accredited migration testing laboratories face capacity bottlenecks as GB 4806 compliance requirements expand, extending certification timelines for new submissions.
- Biodegradable Film:Polylactic acid and polyhydroxyalkanoate pilot deployments in South Korea and Japan demonstrate structural immaturity at commercial scale, lacking oxygen barrier performance required for retort baby food applications.
- Aluminum:Foil laminates and formed trays provide absolute light and oxygen barrier for sensitive nutrient preservation.
- Paperboard:Molded fiber and barrier-coated cartonboard targets plastic-restricted Southeast Asian markets with tightening municipal waste ordinances.
Plastic commands the dominant share by volume, though biodegradable film gains share fastest as Japan's METI extends pharmaceutical-grade hygiene expectations into functional categories.
Closure Type:
Application context dictates closure specification: ambient shelf-stable formats demand hermetic integrity, while refrigerated segments prioritize resealability and portion control.
- Child-resistant Closure:Integrated push-and-turn mechanisms with tamper-evident bands satisfy Japan's PMDA pharmaceutical-grade safety expectations extending into functional baby food. Manufacturing concentrates in cleanroom environments that disqualify standard food-grade converters.
- Screw Cap:Polypropylene and high-density polyethylene threaded closures with induction seals dominate glass jar and rigid container formats across Indian and Chinese retail channels.
- Peel-off Lid:Aluminum and multi-layer film lidding stocks enable single-serve convenience in hospital and travel contexts.
- Zip Lock:Press-to-close interlocking profiles support resealable pouch formats for multi-serve toddler snacks.
Screw cap maintains volume leadership, with child-resistant closure expanding most quickly as regulatory safety expectations tighten across Japan and South Korea.
Sales Channel:
Customer type bifurcation separates stock-up retail behavior from replenishment-driven subscription models, forcing structural redesigns around shipment durability versus palletized distribution.
- Online Retail:Direct-to-parent subscription platforms in Shanghai, Mumbai, and Jakarta displace traditional retail stock-up behavior among urban millennial demographics. Packaging now requires drop-test performance and single-unit protective features rather than case-level stacking strength.
- Supermarkets:Hypermarket and supermarket chains in China's tier-one cities and Indian metropolitan clusters sustain volume concentration for glass jar and tetra pack formats optimized for shelf-facing visibility.
- Specialty Stores:Organic and premium baby product boutiques in Tokyo, Seoul, and Singapore drive adoption of biodegradable and fiber-based formats.
- Convenience Stores:Limited-assortment retail in dense urban corridors supports impulse purchase of single-serve pouch formats.
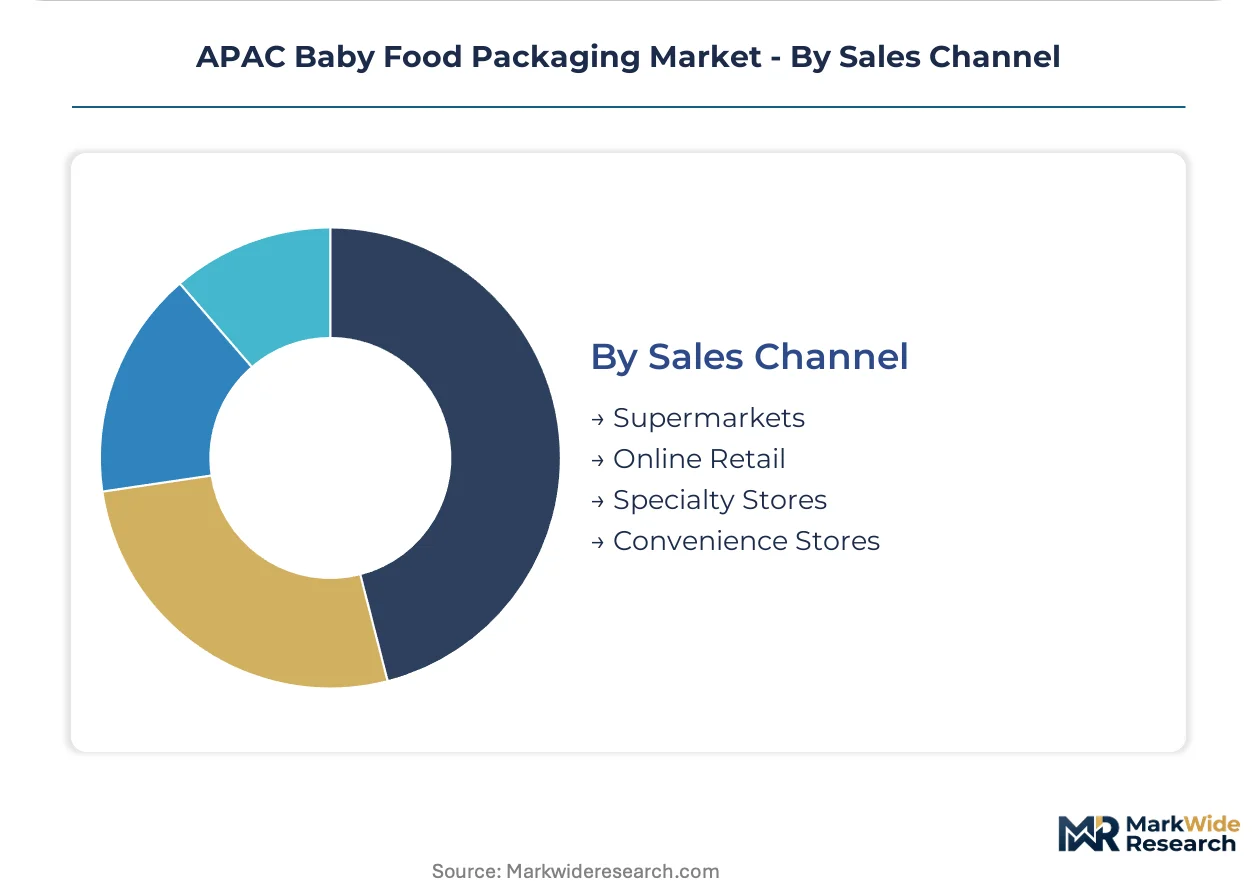
Supermarkets retain volume dominance, with online retail gaining share fastest as e-commerce subscription models reshape replenishment patterns across tier-one Chinese and Indian cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting packaging production toward jurisdictions with lower compliance-cost burdens, while tier-one urban clusters absorb premium-format demand. Migration testing capacity constraints in China are pushing converters to qualify alternative supply bases in Southeast Asia.
China
Shanghai and Beijing parents drive single-serve pouch adoption through e-commerce subscription platforms. SAMR enforces GB 4806 migration testing mandates that bottleneck laboratory capacity and extend certification timelines. Yangtze River Delta converters are expanding ethylene-vinyl alcohol copolymer coextrusion lines to serve multinational brand owners.
India
Mumbai, Delhi-NCR, and Bangalore millennial demographics prioritize portion-controlled formats for convenience feeding. FSSAI labeling and shelf-life declaration requirements directly impact packaging surface area specifications. Pune and Ahmedabad manufacturing clusters are attracting investment from flexible film converters seeking lower qualification costs than China.
Japan
Tokyo and Osaka functional baby food segments demand pharmaceutical-grade hygiene standards. METI guidelines extend PMDA-level expectations into cleanroom manufacturing environments that disqualify standard food-grade converters. Kanto region suppliers dominate retort-compatible polypropylene expertise, creating recruitment friction for regional competitors.
South Korea
Seoul metropolitan parents pilot biodegradable film formats despite structural immaturity in oxygen barrier performance. MFDS coordinates with METI on food-contact safety alignment, easing cross-border supplier qualification. Busan-Ulsan chemical complexes supply barrier film feedstocks to regional converters.
Vietnam
Ho Chi Minh City and Hanoi emerging middle-class consumers adopt rigid container formats for chilled distribution chains. ASEAN harmonization initiatives reduce cross-border supply chain qualification costs for converters serving Thai and Indonesian markets. Northern industrial zones attract packaging investment from Chinese firms seeking lower labor and compliance costs.
APAC Baby Food Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as converters add cleanroom manufacturing lines to meet Japan's pharmaceutical-grade hygiene expectations. The vendor base stratifies into three tiers: multinational integrated suppliers with regional flexibles footprints, specialized converters with coextrusion expertise concentrated in Northeast Asia, and emerging local players in Southeast Asian industrial zones. Strategic archetypes include barrier film specialists, aseptic carton laminators, and molded fiber innovators. M&A activity and geographic expansion into India's tier-two corridors represent the dominant competitive moves.
Among multinational integrated suppliers, Amcor PLC and Huhtamaki Oyj occupy distinct positioning archetypes. Amcor exemplifies the regional flexibles footprint model serving pouch format demand in Chinese and Indian metropolitan markets. Huhtamaki represents the fiber-based containment trajectory targeting plastic-restricted Southeast Asian jurisdictions. Tetra Laval anchors the aseptic carton segment through dairy-processor co-location strategies in Japan and South Korea. These three entities collectively illustrate how scale, material specialization, and regulatory anticipation define competitive positioning across the regional market.
| Leading Market Players |
|---|
| Amcor PLC |
| Huhtamaki Oyj |
| Berry Global Inc. |
| Aptar Group Inc. |
| Winpak Ltd. |
| Tetra Laval |
| Uflex Ltd. |
| DS Smith Plc |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Ethylene-vinyl alcohol copolymer feedstock costs cascade through three distinct pricing tiers as converters in China's Yangtze River Delta and Japan's Kanto region pass through barrier film specifications to multinational brand owners and regional distributors.
Pricing Analysis
Distributor margins compress as e-commerce subscription platforms in Shanghai and Mumbai disintermediate traditional wholesale channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and commodity-grade specifications separates Japan's METI-compliant cleanroom converters from standard Southeast Asian suppliers. Pricing pressure stems from SAMR laboratory bottlenecks extending GB 4806 certification timelines. Emerging middle-class buyers in India's tier-two cities exhibit highest price sensitivity, while Tokyo organic boutiques absorb premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Danone, Nestlé, and FrieslandCampina procurement teams, while specialized distributors serve mid-tier Indian and Vietnamese brand owners. Feedstock concentration rests on South Korean and Japanese petrochemical complexes for barrier film resins, Chinese coastal converters for coextrusion, and Southeast Asian molders for rigid containers. Single-source vulnerability concentrates in EVOH supply from Busan-Ulsan complexes. Distribution runs through dairy-processor co-location networks for aseptic cartons and third-party logistics for flexible pouch replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC baby food packaging represents a late-cycle quality story as urban millennial parents across China and India shift procurement criteria toward pharmaceutical-grade hygiene and single-serve convenience formats.
For Market Incumbents: To counter biodegradable film structural immaturity blocking sustainability roadmaps, Amcor and Huhtamaki should deepen backward integration into EVOH feedstock security through Northeast Asian supply agreements while adding cleanroom capacity in Japan's Kanto region to capture METI-compliant functional food contracts.
For New Entrants and Emerging Players: Molded fiber spout integration for plastic-restricted Southeast Asian municipalities offers the most penetrable white space. India's Pune-Ahmedabad corridor presents underexploited demand for portion-controlled formats. A certification-first go-to-market angle targeting FSSAI compliance ahead of GB 4806 qualification accelerates market access.
For Investors and Strategic Acquirers: Consolidation pressure builds where cleanroom manufacturing expertise concentrates in Japan and South Korea while mid-tier Chinese converters face margin compression from SAMR laboratory bottlenecks. Long-term viability favors converters with dual certification capability across pharmaceutical and food-grade protocols. The signal to watch is ASEAN harmonization timeline acceleration enabling cross-border format standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Manufacturing Scale-Up | Captures Japan METI functional food contracts disqualifying standard converters. |
| Barrier Film Backward Integration | Secures EVOH feedstock allocation from Busan-Ulsan chemical complexes. |
| Molded Fiber Format Development | Addresses plastic restrictions in Jakarta and Bangkok municipal ordinances. |
| GB 4806 Certification Investment | Unlocks SAMR-compliant supply to Shanghai and Beijing brand owners. |
| India Tier-Two Distribution Expansion | Reaches Pune and Ahmedabad emerging middle-class parent populations. |
Study Parameters
Direct dialogue with packaging procurement directors at multinational formula brands, coextrusion engineering leads at Japanese and South Korean converters, FSSAI regulatory affairs specialists, and e-commerce supply chain managers in Mumbai grounded qualitative insights. Secondary validation drew from SAMR GB standard filings, Japan METI food-contact guidelines, ASEAN harmonization protocols, and customs trade data for barrier film resin flows. Bottom-up volume modeling across format types triangulated with top-down spending estimates from dairy-processor capital expenditure disclosures.
Segment-level outputs across flexible pouch, glass jar, rigid container, and tetra pack formats trace volume and value trajectories over the projection horizon. Modeled dimensions include packaging type, material specification tier, closure safety grade, and sales channel structure. CAGRs derive from parent demographic shift rates, e-commerce penetration curves, and regulatory compliance cost trajectories. Forecast inputs incorporated urban millennial household formation data and municipal plastic restriction implementation schedules.
The model holds under stable GB 4806 laboratory capacity and continued EVOH feedstock availability; deviation in SAMR accreditation timelines or Northeast Asian petrochemical allocation would shift format adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market