
 Europe Baby Food Packaging Market | 2026-2036
Europe Baby Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Baby Food Packaging Market Foresight
Mono-material flexible packaging and digital printing integration is reshaping how baby food brands balance shelf appeal with recyclability mandates. Amcor Plc leverages its European film extrusion network to supply pre-qualified recyclable pouches for organic lines. Constantia Flexibles Group GmbH anchors its position through aluminum-free barrier laminates that maintain twelve-month shelf stability. Mondi Group competes via kraft-paper-based formats that align with retailer plastic-reduction commitments.
Europe baby food packaging encompasses primary and secondary containment systems engineered to protect infant nutrition from oxygen, light, and microbial ingress while enabling portion control and caregiver convenience. Pouch formats with spouted closures now dominate new product introductions due to reduced material weight and ambient distribution compatibility. Glass jars retain structural share in premium segments where thermal processing and inert contact surfaces justify higher unit costs. Paperboard cartons and Tetra Packs capture growth in liquid and ready-to-feed categories where aseptic filling extends refrigerated shelf life without preservatives.
EMA food-contact material guidelines, EU Packaging and Packaging Waste Regulation targets, and national extended producer responsibility schemes collectively dictate material choices and end-of-life obligations for converters. EFSA migration limits for printing inks and adhesives directly influence laminate construction decisions, particularly for fat-containing purees. The CSRD disclosure requirements will soon force packaging suppliers to document Scope 3 emissions tied to downstream brand owners. Stakeholders must now decide whether to prioritize capital deployment into chemical recycling partnerships or mechanical recycling-compatible mono-material platforms before compliance deadlines harden.
Market Dynamics
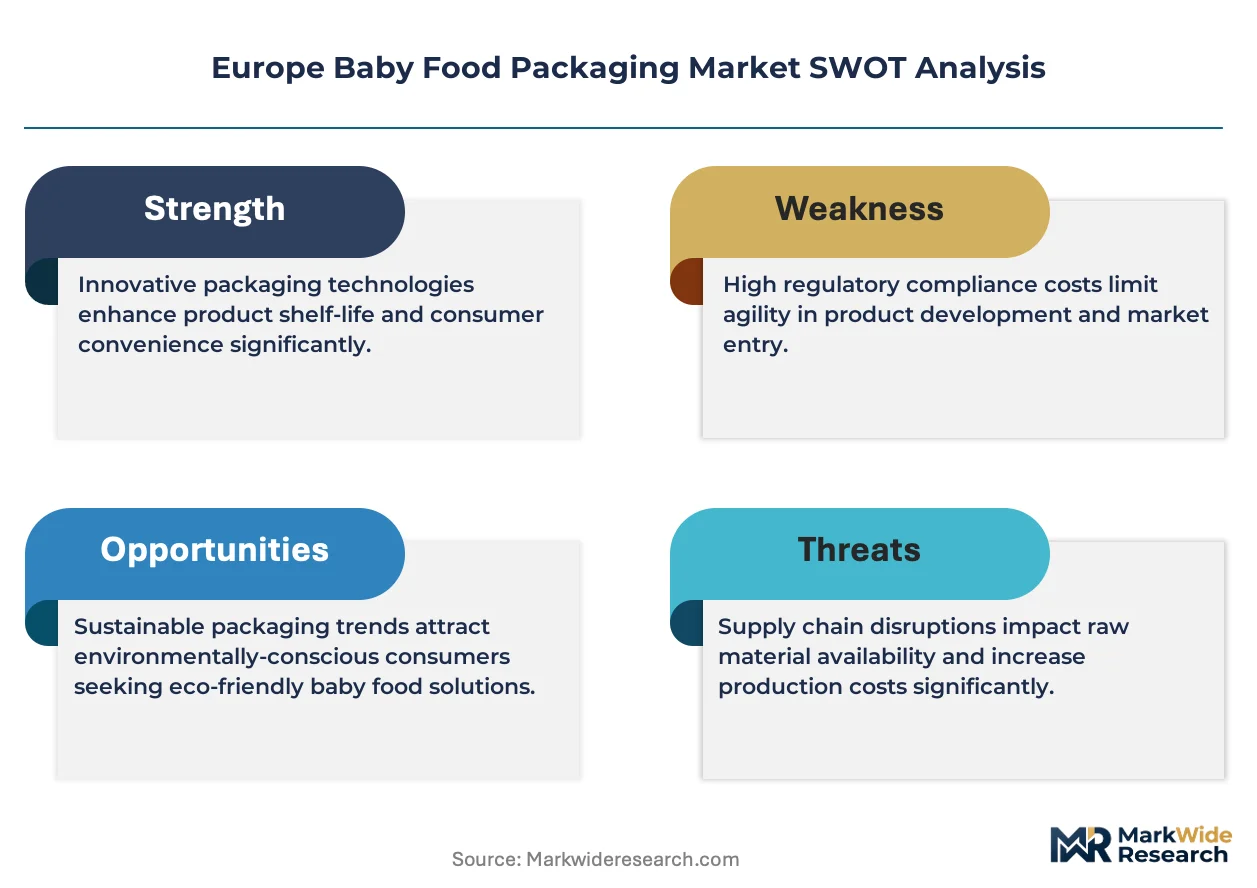
The EU Packaging and Packaging Waste Regulation is compressing design cycles for baby food converters, forcing rapid migration from multi-layer laminates to mono-material structures that satisfy extended producer responsibility schemes without sacrificing twelve-month shelf stability.
Growth Catalysts
- Organic purees in pouch formats:Parents prioritize portability and portion control, accelerating brand investment in spouted flexible packaging that reduces material weight versus glass jars.
- REACH-compliant adhesives:ECHA restrictions on conventional chemistries are pulling converters toward water-based and UV-cured alternatives that maintain barrier performance in fat-containing formulations.
- German retailer sustainability premiums:Private-label buyers in this market now mandate recyclability certifications, reshaping procurement criteria across Austria and Switzerland by extension.
Market Restraints
- Aluminum oxide barrier costs:EVOH and SiOx deposition technologies remain capital-intensive, squeezing margin structures for mid-tier converters serving economy-positioned brands.
- Mechanical recycling contamination thresholds:Current sorting infrastructure cannot reliably separate food-residue films from mono-material streams, limiting closed-loop claims.
- Glass jar substitution resilience:Premium thermal-processed lines retain format loyalty among parents prioritizing inert contact surfaces and visible product quality.
Strategic Opportunities
- Poland and Romania expansion:Modern trade penetration lags Western Europe, creating first-mover advantage for pouch-format entrants establishing ambient distribution networks.
- Digital printing convergence with track-and-trace:Serialization mandates under the EU Falsified Medicines Directive extension to food contact are enabling personalized packaging and inventory optimization.
- Chemical recycling partnerships:Pyrolysis and glycolysis investments by petrochemical majors offer converters an alternative end-of-life pathway for mixed-film legacy stocks.
Industry Challenges
- Migration testing capacity bottlenecks:EFSA notification backlogs for novel laminate structures delay product launches by six to eighteen months.
- Legacy filling line retrofits:Aseptic pouch systems require complete packaging hall reconfiguration, straining capex allocation for co-manufacturers serving multiple brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Baby Food Packaging Market |
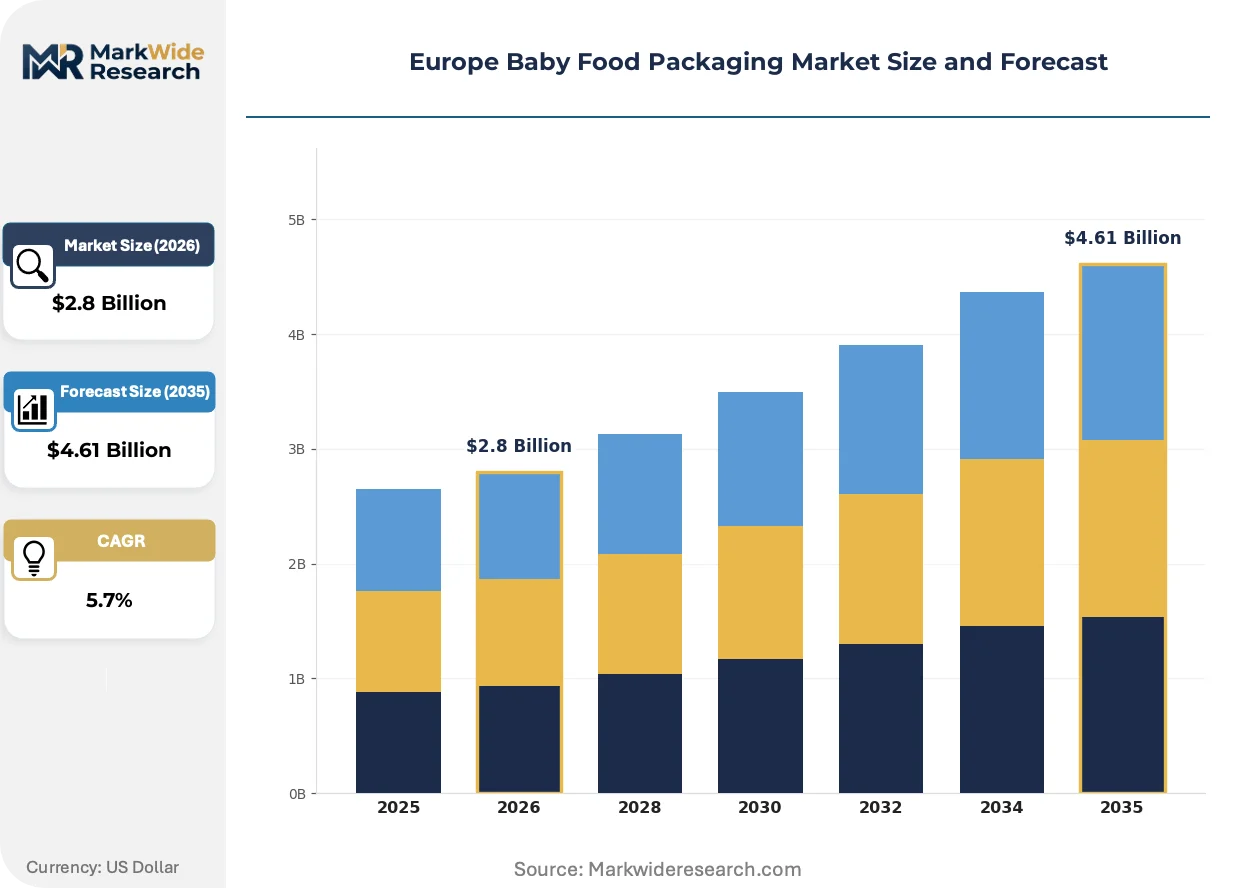
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jars, Pouches, Cans, Tetra Packs Material: Plastic, Paperboard, Metal, Glass End User: Parents, Caregivers, Healthcare Providers, Institutions Closure Type: Lids, Caps, Sealed Pouches, Pressure Seals |
| Companies Covered | WestRock Company, Sonoco Products Company, Amcor Plc, Constantia Flexibles Group GmbH, Mondi Group, DS Smith Plc, Winpak Ltd., Coveris Holdings S.A., Crown Holdings, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Baby Food Packaging Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are redefining how baby food packaging balances functional performance with circular economy accountability. Three developments dominate converter R&D roadmaps.
High-barrier mono-material polyethylene structures are collapsing the traditional trade-off between recyclability and shelf-life extension. German and Dutch organic brands are accelerating adoption of MDO-PE and BOPE films with plasma-deposited ceramic coatings. This shift is compressing demand for aluminum-foil laminates that require energy-intensive delamination before mechanical recycling.
CSRD disclosure requirements are forcing packaging suppliers to document Scope 3 emissions across downstream brand owner networks. The European Sustainability Reporting Standards mandate granular carbon accounting for purchased goods and services. Small-to-mid converters serving multinational infant nutrition corporations are scrambling to deploy lifecycle assessment software and secure supplier-specific emission factors before the 2025 reporting deadline.
Subscription-based replenishment models are fragmenting traditional retail procurement for baby food. Direct-to-consumer channels in France and the United Kingdom are displacing supermarket shelf presence for premium organic lines. This channel rotation is compressing batch sizes and accelerating demand for digital printing that enables versioning without plate changeover costs.
Europe Baby Food Packaging Market Segmentation
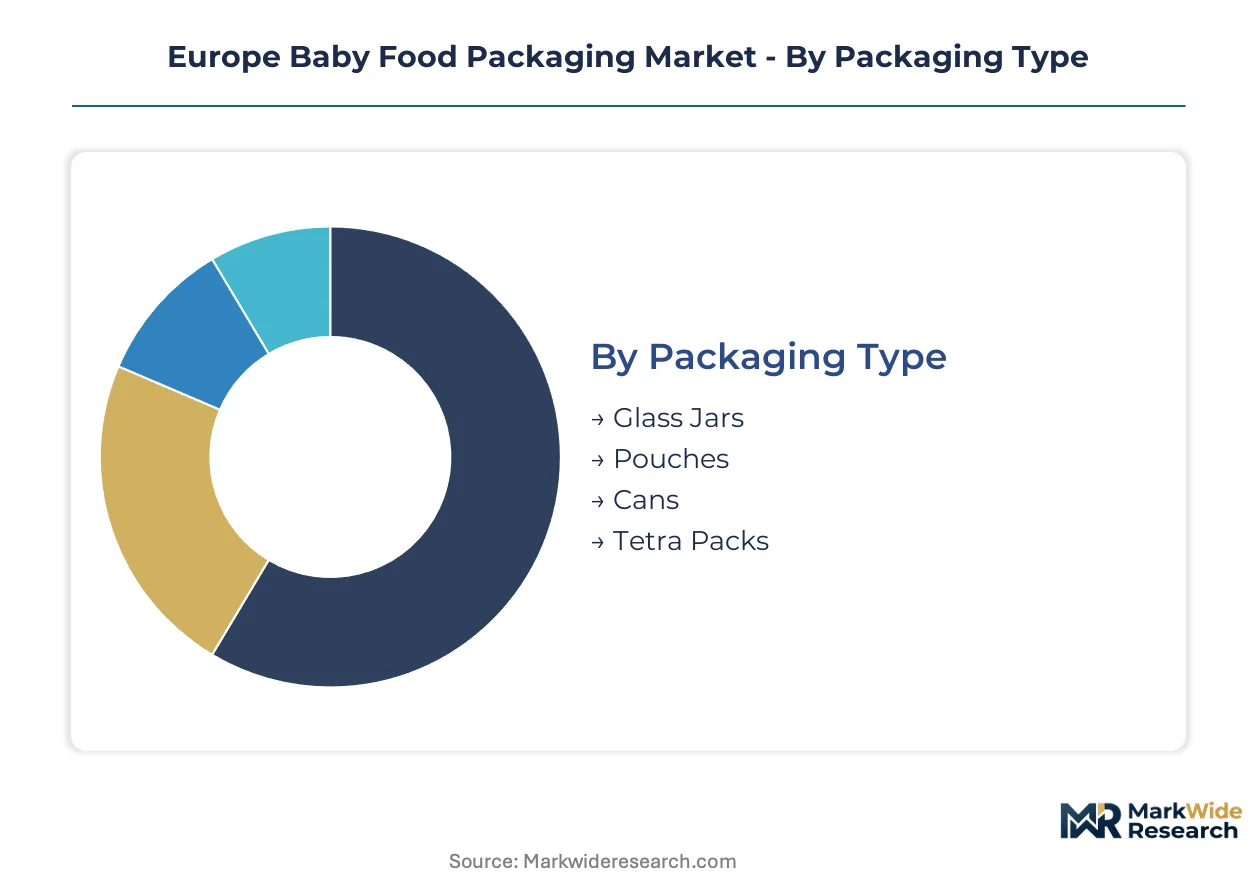
Packaging format decisions in infant nutrition balance shelf stability against circular economy mandates. Material selection and closure engineering determine compliance pathways under EU Packaging and Packaging Waste Regulation targets.
Packaging Type:
Mature formats retain structural importance while emerging pouch systems capture new product development investment.
- Pouches:Multi-layer flexible laminates with spouted closures reduce material weight versus rigid alternatives. German and Dutch organic brands concentrate procurement here, driven by parent demand for portability and ambient distribution compatibility.
- Glass Jars:Thermal processing compatibility and inert contact surfaces preserve premium positioning. France and Italy maintain format loyalty for visible product quality in traditional retail channels.
- Tetra Packs:Aseptic filling extends refrigerated shelf life without preservatives for liquid and ready-to-feed categories.
- Cans:Metal containment serves shelf-stable prepared meals with extended durability requirements.
Pouches handle the majority of new product throughput; Tetra Packs are expanding most quickly in liquid nutrition segments.
Material:
Cost tier stratification separates premium sustainable substrates from commodity feedstocks.
- Plastic:Mono-material polyethylene structures with plasma-deposited ceramic coatings now satisfy twelve-month barrier requirements. EFSA migration limits for fat-containing purees constrain adhesive selection in laminate construction.
- Paperboard:Kraft-paper-based formats align with retailer plastic-reduction commitments in the United Kingdom and Scandinavia.
- Glass:Silica-based containment offers chemical inertness for thermal-processed premium lines.
- Metal:Tinplate and aluminum provide oxygen impermeability for extended shelf-life applications.
Plastic dominates volume throughput; paperboard is gaining share fastest among sustainability-positioned brands.
End User:
Customer type determines packaging functionality requirements across convenience, safety, and institutional compliance dimensions.
- Parents:Portion control and one-hand operation drive spouted pouch preference in German and French household purchasing.
- Caregivers:Re-sealability and clear labeling for allergen identification shape procurement in childcare settings.
- Healthcare Providers:Sterile presentation and tamper-evident features meet clinical nutrition protocols.
- Institutions:Bulk formats with dispensing compatibility serve nursery and hospital feeding programs.
Parents represent the primary volume segment; healthcare providers are climbing the fastest on specialized format demand.
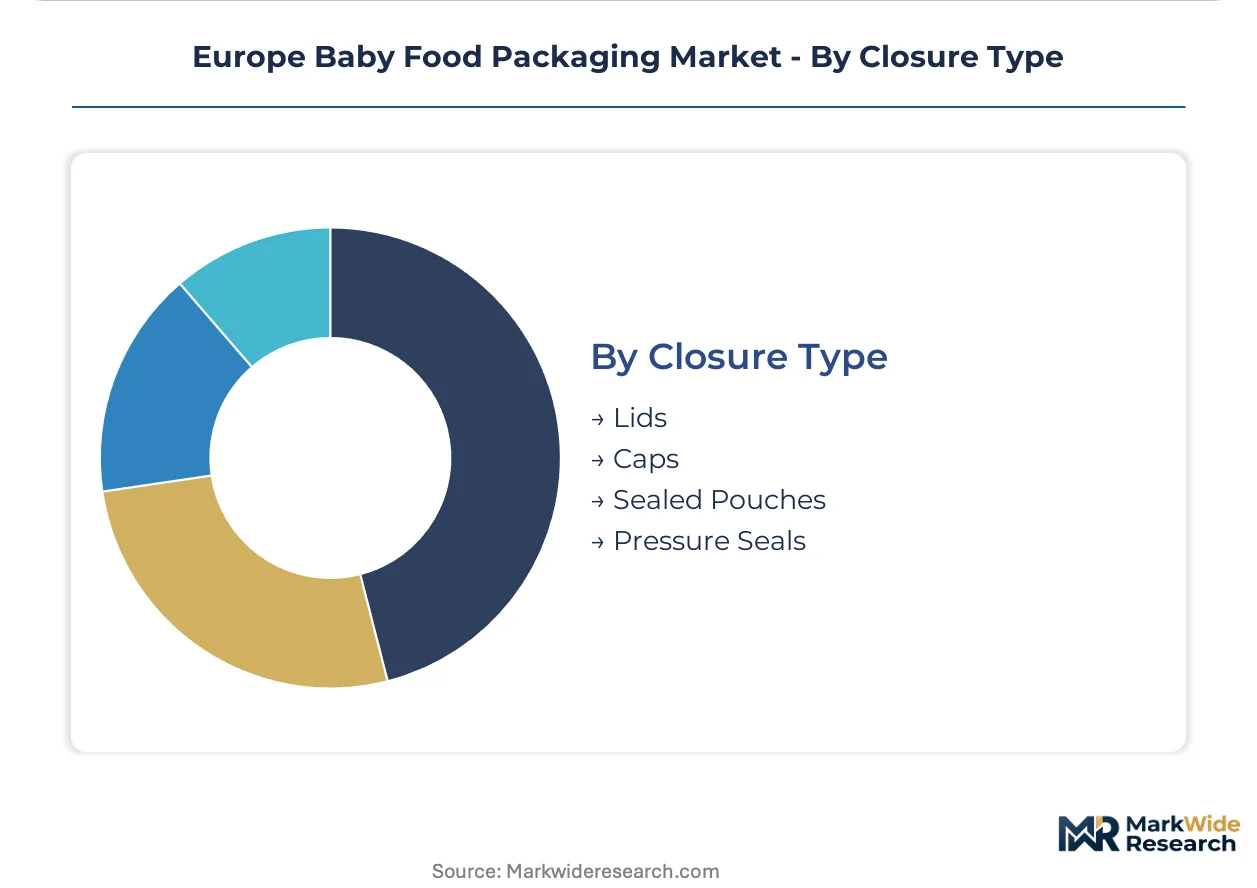
Closure Type:
Supply concentration among European converter networks favors established closure technologies over novel dispensing systems.
- Sealed Pouches:Pre-formed spout-and-cap assemblies enable aseptic filling without post-sterilization contamination risk.
- Lids:Metal lug closures maintain hermetic integrity for glass jar thermal processing.
- Caps:Child-resistant and easy-twist variants address divergent safety and accessibility requirements.
- Pressure Seals:Induction-sealed membranes provide tamper evidence for retail distribution.
Sealed pouches handle the majority of flexible format throughput; pressure seals are expanding most quickly in premium jar applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private-label buyers in Germany and sustainability-focused parents in Scandinavia drive format selection across the continent. Converter networks cluster near major infant nutrition manufacturing sites to minimize logistics costs for temperature-sensitive formulations.
Germany
Discounter private-label penetration forces packaging converters to deliver mono-material pouches at commodity price points. The national packaging ordinance mandates minimum recycled content thresholds for plastic containers. Bavarian converter clusters around Munich supply spouted pouch assemblies to organic brands expanding ambient distribution.
France
Premium thermal-processed lines in glass jars retain loyalty among traditional retail shoppers prioritizing visible product quality. ANSM food-contact material notifications create compliance lead times for novel laminate structures. The Paris basin hosts formulation facilities driving demand for aseptic carton systems in liquid nutrition.
United Kingdom
Retailer plastic-reduction commitments accelerate kraft-paper-based format adoption for subscription direct-to-consumer channels. Extended producer responsibility schemes under the UK Packaging Waste Regulations reshape end-of-life cost allocation. Converter capacity concentrates in the Midlands serving both domestic brands and export-oriented multinationals.
Netherlands
Aseptic filling expertise in liquid and ready-to-feed categories supports Tetra Pack format expansion. REACH-compliant adhesive migration limits constrain laminate construction for fat-containing purees. The Randstad corridor houses pilot facilities testing high-barrier mono-polyethylene structures with plasma-deposited ceramic coatings.
Poland
Modern trade penetration lags Western Europe, creating first-mover opportunity for pouch-format entrants establishing ambient distribution networks. EU Packaging and Packaging Waste Regulation targets apply with phased compliance timelines. Warsaw and Łódź industrial zones attract converter investments serving expanding domestic infant nutrition production.
Europe Baby Food Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. The vendor base separates into consolidated multinational converters with European film extrusion networks, mid-tier regional specialists serving private-label aggregators, and niche material science firms developing aluminum-free barrier laminates. Strategic moves concentrate on chemical recycling partnerships versus mechanical recycling-compatible mono-material platform investments, alongside digital printing integration for versioning flexibility.
Among diversified packaging conglomerates with European operational footprints, Amcor Plc, Constantia Flexibles Group GmbH, and Mondi Group occupy positions spanning flexible and rigid format portfolios. Amcor represents the scale-driven archetype with pre-qualified recyclable pouch supply capabilities. Constantia Flexibles exemplifies regional specialist consolidation through aluminum-free laminate development. Mondi anchors the fiber-based sustainability positioning aligned with retailer plastic-reduction commitments.
| Leading Market Players |
|---|
| WestRock Company |
| Sonoco Products Company |
| Amcor Plc |
| Constantia Flexibles Group GmbH |
| Mondi Group |
| DS Smith Plc |
| Winpak Ltd. |
| Coveris Holdings S.A. |
| Crown Holdings, Inc. |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation compliance deadlines determine both pricing tier spreads and supply chain shape by forcing converters into capital-intensive mono-material platform investments before mechanical recycling infrastructure matures. Parent demand for organic pouch formats in Germany and the Netherlands compresses margin structures as private-label buyers extract sustainability premiums without corresponding price tolerance.
Pricing Analysis
Cost-plus contracts with ethylene indexation dominate converter-brand relationships, insulating margin volatility from resin price swings. Pricing stratifies across premium mono-material laminates with ceramic barrier coatings, standard aluminum-oxide EVOH structures, and economy multi-layer films facing obsolescence risk. Cost compression in the standard tier intensifies because REACH-compliant adhesive migration testing extends qualification cycles. Private-label procurement teams in German discount channels exhibit highest price sensitivity, while organic brand owners in France and Scandinavia absorb sustainability premiums with lowest resistance.
Supply Chain Analysis
Extended payment terms from multinational infant nutrition corporations strain working capital for mid-tier converters serving secondary brand owners. Raw material concentration draws from German and Dutch polymer extrusion hubs, Italian adhesive formulators, and Austrian metallized film specialists. Single-source vulnerability sits with plasma-deposition equipment suppliers controlling ceramic barrier coating capacity. Distribution runs through Bavarian converter clusters co-located with major formulation facilities, minimizing temperature-sensitive logistics exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe baby food packaging sits in early-cycle expansion as organic pouch penetration in Poland and Romania trails Western European saturation by seven to ten percentage points. CSRD disclosure mandates create immediate compliance service demand ahead of reporting deadlines.
For Market Incumbents: Build certification moats around EFSA pre-notified mono-material structures before notification backlogs extend to twenty-four months. Capture backward integration into MDO-PE film extrusion to defend margin position against resin price volatility. Anchor channel control through exclusive spouted pouch assembly supply to expanding ambient distribution networks in Eastern Europe.
For New Entrants and Emerging Players: Establish a beachhead in aluminum-free barrier laminate supply for Dutch and German organic brands seeking twelve-month shelf stability without delamination complexity. Target childcare institution procurement channels where re-sealability specifications remain underspecified. Lead with digital printing convergence offering versioning flexibility for subscription direct-to-consumer channels in the United Kingdom.
For Investors and Strategic Acquirers: Regional specialists with pilot-scale plasma-deposition capabilities represent the most defensible acquisition profile as ceramic coating technology consolidates. Monitor EFSA notification queue clearance rates as the inflection signal separating qualified from speculative mono-material platforms. Five-to-ten year viability hinges on chemical recycling partnership traction versus mechanical recycling infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Investment | Converters deploying MDO-PE extrusion lines capture EFSA pre-qualified supply positions ahead of PPWR enforcement. |
| Chemical Recycling Partnership | Pyrolysis agreements with petrochemical majors offer legacy multi-layer film end-of-life pathways beyond mechanical sorting limits. |
| Digital Printing Integration | Versioning capability without plate changeover costs aligns with subscription channel batch size fragmentation. |
| Aluminum-Free Barrier Development | SiOx and ceramic coatings eliminate energy-intensive delamination steps while maintaining oxygen impermeability for fat-containing purees. |
| Extended Producer Responsibility Pre-Compliance | Early adoption of national packaging ordinance thresholds in Germany secures retailer shelf access before mandate hardening. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA migration limit notifications, EU Packaging and Packaging Waste Regulation impact assessments, and converter capacity disclosures. Primary interviews engaged packaging development directors at infant nutrition multinationals, procurement leads at German and French retailers, technical R&D heads at flexible film converters, and sustainability officers facing CSRD disclosure deadlines. Secondary validation drew from ECHA REACH restriction updates, national extended producer responsibility scheme filings, and trade data on ethylene-based polymer imports. Bottom-up volume modeling triangulated against top-down value estimates across format and material segments.
Forecast inputs incorporate capacity expansion announcements, regulatory compliance timeline phasing, and parent purchasing survey data on format preference shifts. Segmentation dimensions span packaging type, material substrate, closure engineering, and end-user channel across the analysis window. CAGRs derive from curve-fitting historical format penetration rates against projected regulatory adoption deadlines. Industry-specific inputs include EFSA notification queue clearance assumptions and aseptic filling line retrofit capex cycles.
Sensitivities concentrate around mechanical recycling contamination threshold revisions, ceramic barrier coating equipment delivery delays, and German retailer sustainability premium persistence. Forecasts reflect documented assumptions on regulatory enforcement rigor and parent willingness-to-pay for recyclability claims. Macroeconomic contraction, EFSA migration limit tightening, or chemical recycling technology underperformance would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market