
 US Pet Food Packaging Market | 2026-2036
US Pet Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Food Packaging Market Analytics
Multi-source flexible film procurement is restructuring supply relationships across the US pet food packaging value chain. Amcor plc leverages its blown film extrusion network to sustain national supply security for dry kibble brands. Berry Global Inc. anchors its position through preformed pouch capacity concentrated in the Midwest. Sonoco Products Company differentiates via fiber-based canisters targeting premium treat segments.
US pet food packaging encompasses barrier laminates, formed trays, and sealed containers engineered to preserve nutritional integrity, prevent oxidation, and withstand distribution stress from filling through retail shelf life. Flexible pouches and rigid containers represent the dominant format pairing, with pouches capturing margin pools in grain-free and raw-coated diets while cans retain volume leadership in therapeutic and veterinary-prescribed wet nutrition. Plastic and paperboard material streams diverge sharply by product type, as dried food packaging prioritizes high-barrier polyethylene terephthalate laminates and wet food formats require metallized or aluminum-integrated structures.
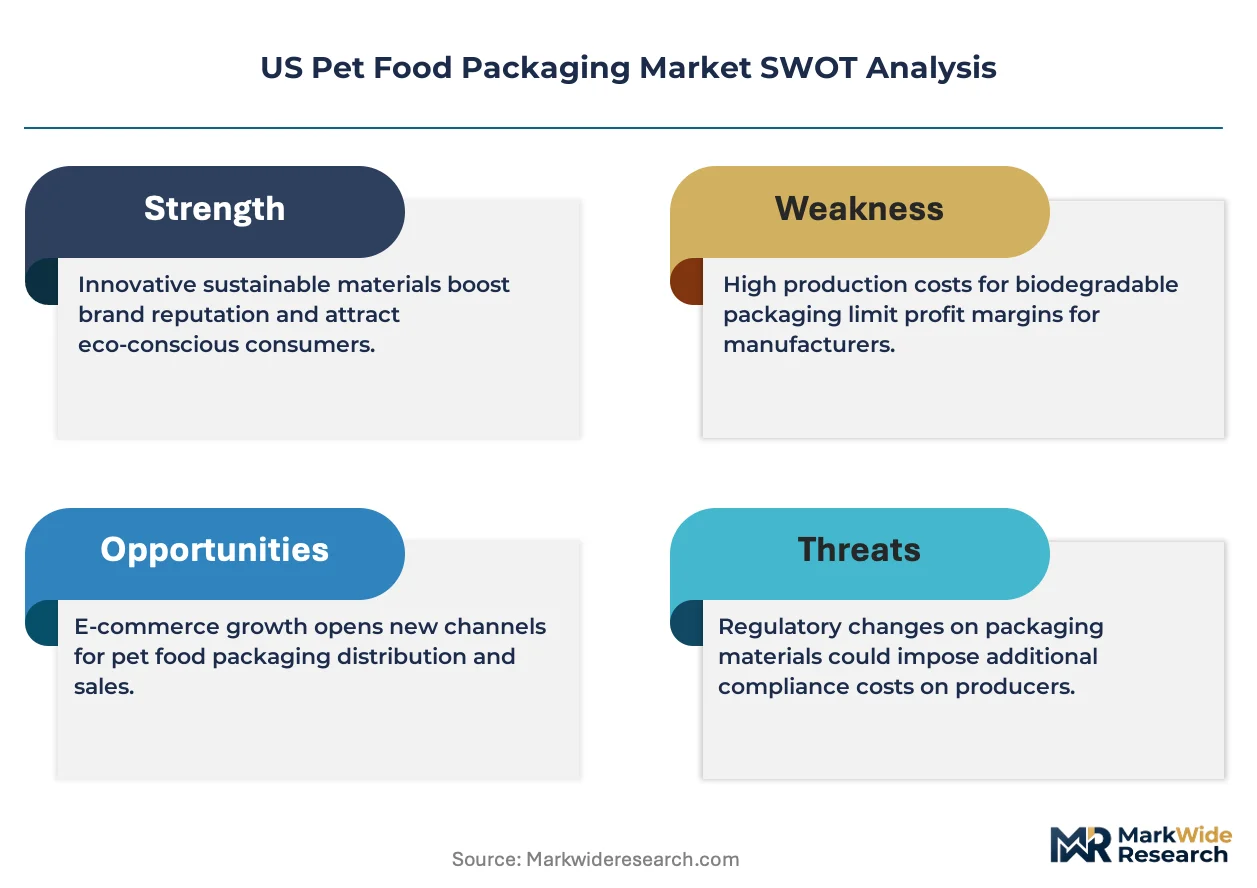
FDA food-contact substance regulations under 21 CFR 170-189 govern migration limits and additive approvals for all pet food packaging substrates sold in the United States. EPA guidelines on per- and polyfluoroalkyl substances are accelerating fluorochemical phase-outs in grease-resistant paperboard applications. State-level extended producer responsibility frameworks, particularly California's SB 54 mandates, are forcing brand owners to validate recycled content claims and redesign multi-material laminates. Stakeholders must monitor emerging PFAS restrictions and recycled-content thresholds as these rules will determine which material technologies retain market access.
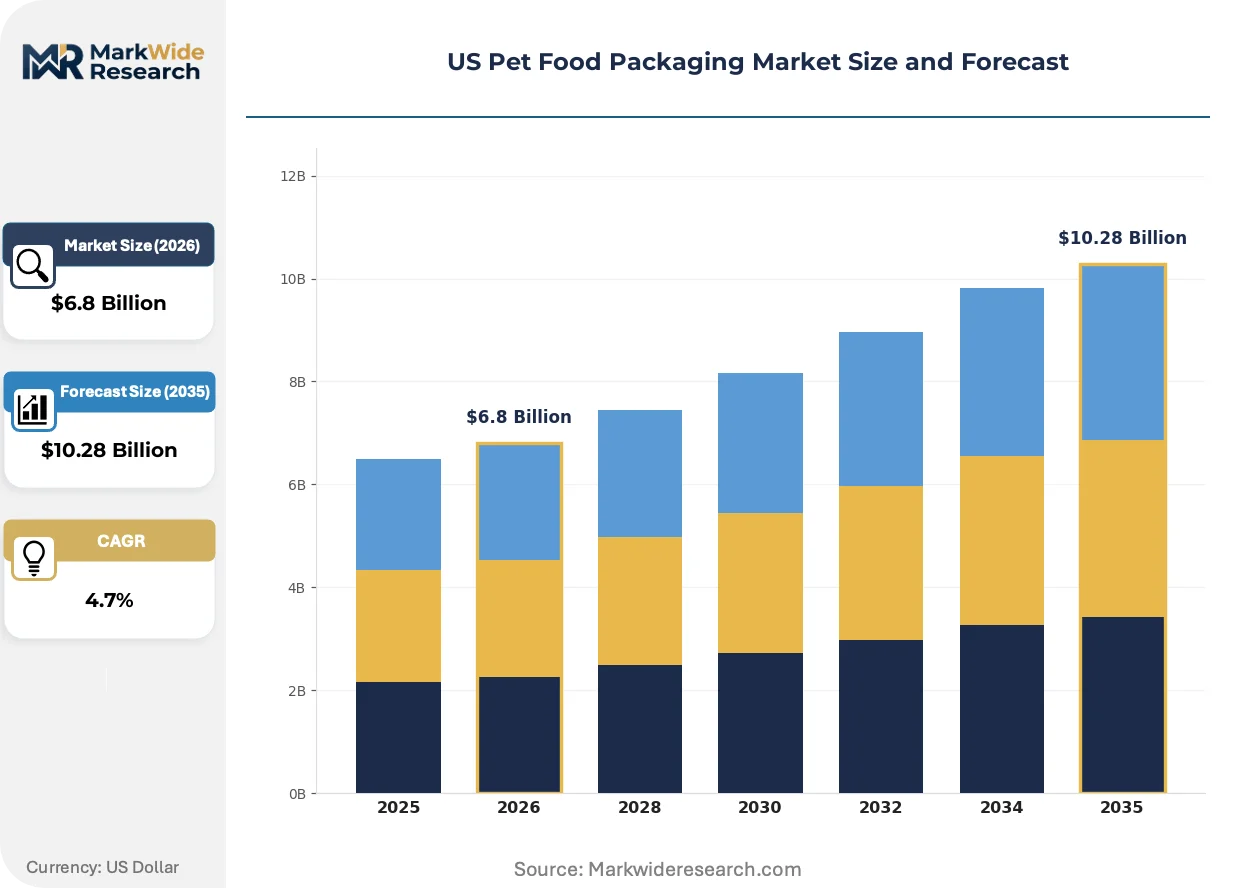
Market Dynamics
California's SB 54 mandates are forcing immediate packaging redesigns across the US pet food sector, compelling brands to validate recycled content claims and eliminate non-recyclable multi-material laminates before enforcement deadlines tighten material specifications nationwide.
Growth Catalysts
- Fresh-refrigerated format expansion:Urban pet owners in metropolitan corridors are demanding portion-controlled, preservative-free nutrition that requires oxygen-scavenging films and temperature-stable substrates.
- Extended producer responsibility frameworks:State-level EPR laws in California and New York are creating compliance-driven demand for mono-material pouches and validated post-consumer recycled content streams.
- Veterinary therapeutic nutrition:Prescription wet food formats require metallized barrier structures that sustain shelf integrity through extended distribution cycles.
Market Restraints
- Resin input volatility:Polyethylene terephthalate and polypropylene feedstock costs fluctuate with petrochemical refining capacity concentrated along the US Gulf Coast.
- Fluorochemical phase-out friction:EPA guidelines on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings before viable replacements achieve comparable performance at scale.
- Multi-material laminate lock-in:Existing high-barrier pouch formats bond incompatible polymer layers that municipal recycling streams cannot separate, creating stranded asset risk for production lines.
Strategic Opportunities
- Southeast co-packing corridor:Georgia and South Carolina manufacturing clusters offer contract packaging capacity for emerging brands seeking national distribution without capital-intensive facility investment.
- Mono-material flexible innovation:Polyethylene-only pouch structures compatible with store-drop-off recycling streams are capturing shelf space as retailers enforce sustainability scorecards.
- Smart packaging integration:Time-temperature indicators and freshness sensors are penetrating premium treat segments where unit economics support added substrate cost.
Industry Challenges
- Migration testing bottlenecks:FDA food-contact substance notifications under 21 CFR 170-189 face extended review timelines that delay new barrier coating commercialization.
- Recycled content verification:Mass-balance accounting for post-consumer resin integration requires third-party certification infrastructure that remains underdeveloped for flexible packaging grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Food Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Rigid Containers, Tetra Packs, Cans Material: Plastic, Paperboard, Metal, Glass Product Type: Dried Food, Wet Food, Treats, Supplements Closure Type: Screw Caps, Snap-Fit, Resealable, Twist Tops |
| Companies Covered | Amcor plc, Berry Global Inc., ProAmpac LLC, Sealed Air Corporation, Coveris Holdings SA, American Packaging Corporation, Crown Holdings Inc., Sonoco Products Company, Mondi plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Food Packaging Market Evolving Landscape
Active and intelligent packaging systems are penetrating the US pet food sector as brands seek differentiation through freshness assurance and supply chain transparency rather than conventional graphic design alone.
Oxygen-scavenging films incorporating iron-based or enzymatic chemistries are extending shelf life for grain-free and raw-coated kibble formats. Premium and super-premium brands are adopting these substrates fastest, with adoption timelines compressing from multi-year pilots to single-season rollouts. The technology is integrating quality assurance directly into package structure, reducing reliance on nitrogen flushing and enabling slimmer barrier constructions.
EPA enforcement of per- and polyfluoroalkyl substance restrictions is accelerating elimination of grease-resistant treatments from paperboard treat packaging. Converting operations face capital outlays for plasma coating or clay-based barrier alternatives. Wet food can applications are most affected, as manufacturers retrofit lines to handle non-fluorinated internal sprays while maintaining fat-barrier performance through retort processing.
Direct-to-subscription purchasing is compressing traditional distributor margins and reshaping order fulfillment requirements. E-commerce-native brands are specifying ship-ready primary packaging that eliminates secondary corrugated, while conventional retail suppliers struggle to serve dual-channel demand from single production assets. The Pacific Northwest and Northeast urban corridors exhibit the strongest channel shift velocity, with subscription penetration highest among raw and fresh-format buyers.
US Pet Food Packaging Market Segmentation
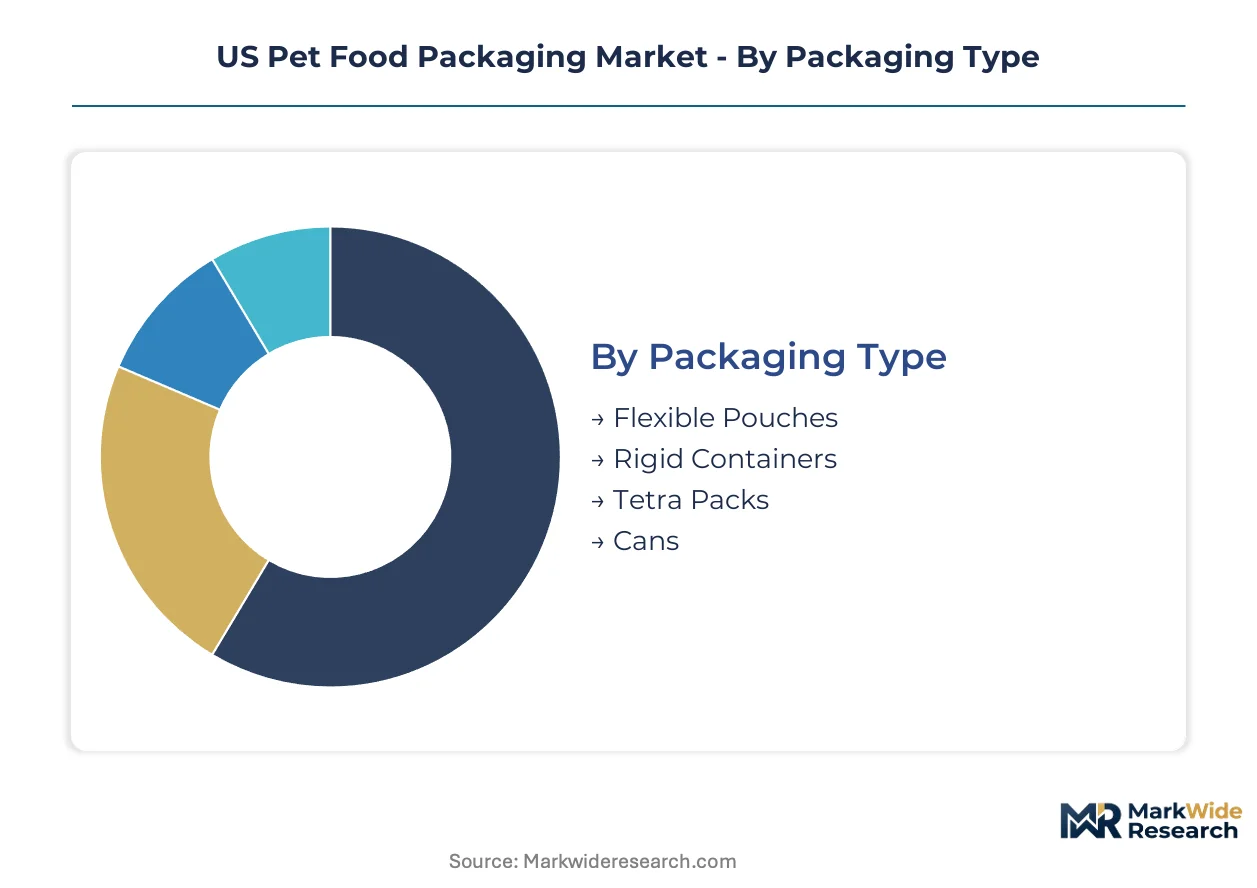
Packaging specification in the US pet food sector is diverging sharply by format complexity and regulatory exposure, with FDA food-contact notifications required for barrier coatings in wet food formats while dry kibble pouches face lighter compliance burdens.
Packaging Type:
Certification intensity scales with oxygen sensitivity and retort processing requirements, with metallized flexible pouches triggering extended FDA migration testing timelines compared to standard polyethylene constructions.
- Flexible Pouches:Multi-layer polyethylene terephthalate laminates with oxygen-scavenging chemistries dominate grain-free and raw-coated diet packaging. Demand concentrates among subscription-format brands in Pacific Northwest urban corridors where portion-controlled dispensing drives zipper-resealable specifications.
- Rigid Containers:Injection-molded polypropylene tubs with in-mold labels serve fresh-refrigerated formats requiring temperature stability through cold-chain distribution. California SB 54 compliance is forcing rapid transitions to mono-material constructions that retain barrier performance without bonded dissimilar layers.
- Tetra Packs:Aseptic carton formats with aluminum-integrated barrier layers occupy niche positions in broth and gravies.
- Cans:Two-piece aluminum and steel containers retain volume leadership in veterinary-prescribed therapeutic nutrition.
Flexible pouches sit at the top of the volume ranking, with rigid containers climbing the fastest.
Material:
Cost stratification follows barrier performance tiers, with metallized films commanding premium positions against commodity polyethylene grades.
- Plastic:High-barrier polyethylene and polypropylene streams account for the majority of flexible pouch output, with FDA 21 CFR 170-189 compliance required for all food-contact layers.
- Paperboard:Grease-resistant cartons for treat applications are undergoing forced redesign as EPA PFAS restrictions eliminate fluorochemical coatings before plasma-based alternatives achieve cost parity.
- Metal:Aluminum can stock and steel substrates sustain wet food shelf stability through retort processing cycles.
- Glass:Premium treat jars occupy super-premium positioning where unit economics support weight and fragility penalties.
Plastic holds the dominant volume position, with paperboard gaining share fastest as mono-material substitution accelerates.
Product Type:
Application-driven specification divergence separates oxidation-sensitive formats from shelf-stable constructions.
- Dried Food:High-barrier flexible pouches with nitrogen flushing dominate kibble packaging, with oxygen-scavenging film adoption compressing from multi-year pilots to single-season rollouts among premium brands.
- Wet Food:Metallized barrier structures and aluminum cans sustain shelf integrity through extended distribution cycles for therapeutic and veterinary-prescribed formats.
- Treats:Paperboard cartons and flexible pouches split demand by premium positioning.
- Supplements:Blister packs and bottles with desiccant integration address moisture sensitivity for chewable and powder formats.
Dried food commands the largest volume share, with wet food expanding most quickly through fresh-refrigerated format proliferation.
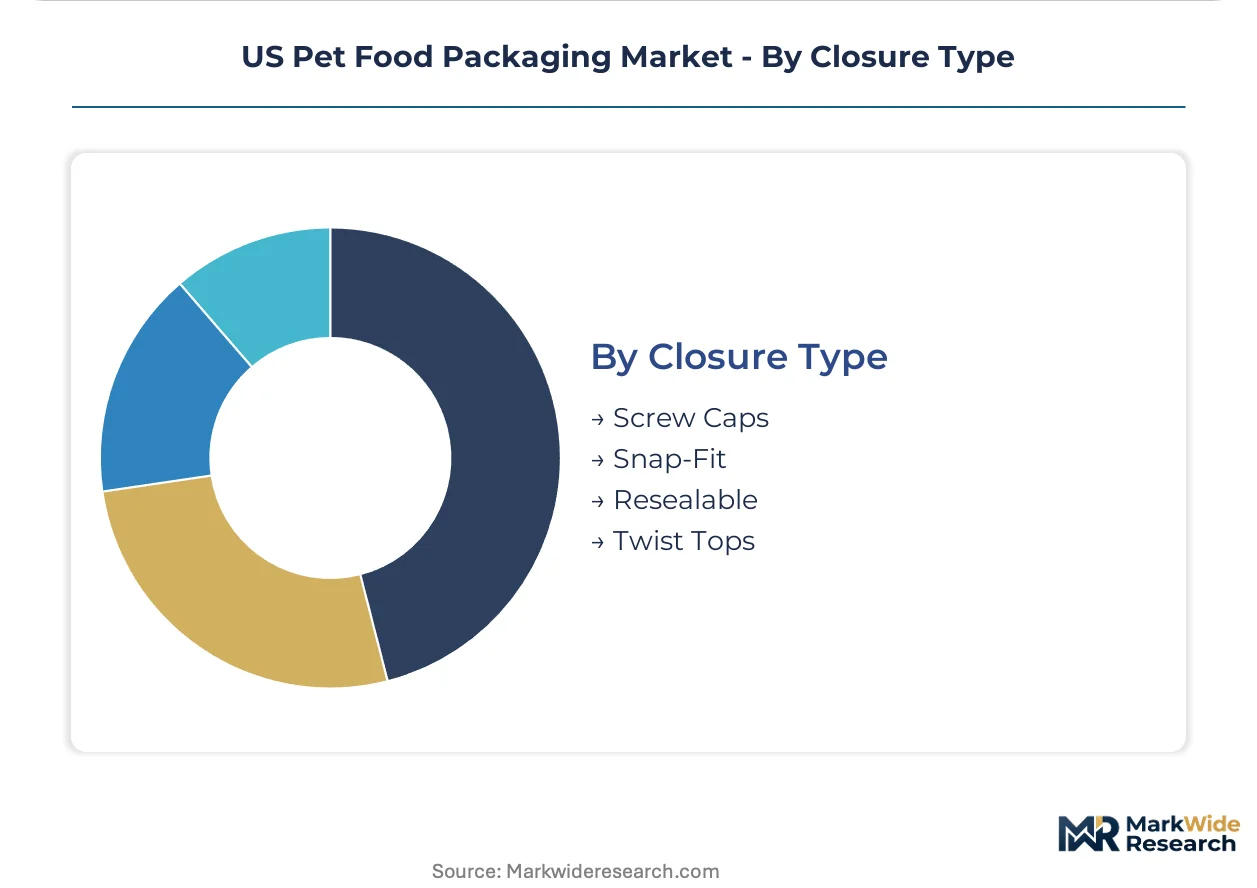
Closure Type:
Customer-type differentiation separates retail shelf formats from direct-to-subscription specifications requiring ship-ready integrity.
- Screw Caps:Polypropylene closures with induction seals dominate wet food tubs and supplement bottles.
- Snap-Fit:Injection-molded lid designs for treat canisters balance resealability against production speed.
- Resealable:Zipper and slider mechanisms on flexible pouches enable portion control for urban pet owners in Northeast metropolitan corridors.
- Twist Tops:Threaded closures for broth and gravy formats in Tetra Pack constructions.
Resealable closures lead volume rankings, with screw caps climbing fastest through fresh-refrigerated tub expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeast manufacturing corridor spanning Georgia and South Carolina anchors US pet food packaging production, serving national brands through integrated co-packing clusters.
California
Fresh-refrigerated format demand concentrates in Los Angeles and San Francisco metropolitan corridors, driven by urban pet owner preferences for portion-controlled nutrition. SB 54 mandates are forcing immediate packaging redesigns to validate recycled content claims and eliminate non-recyclable multi-material laminates. Sacramento's regulatory enforcement infrastructure is accelerating compliance timelines statewide.
New York
Extended producer responsibility frameworks in the New York Metro area are creating compliance-driven demand for mono-material pouches and validated post-consumer recycled content streams. The state's environmental regulator is aligning with California's material specifications. Rochester and Buffalo manufacturing nodes are retrofitting lines for EPR-compatible output.
Georgia
Contract packaging capacity for emerging brands seeking national distribution concentrates in Atlanta and Augusta industrial zones. FDA food-contact substance regulations under 21 CFR 170-189 govern migration limits for all substrates shipped from these facilities. The Savannah port corridor enables efficient raw material import for flexible film converters.
South Carolina
Co-packing clusters in Greenville-Spartanburg serve subscription-format brands requiring ship-ready primary packaging that eliminates secondary corrugated. The state's manufacturing incentives have attracted blown film extrusion investments. Charleston's logistics infrastructure supports cold-chain distribution for fresh-refrigerated formats.
Illinois
Preformed pouch capacity concentrates in Chicago-area converting operations, supplying Midwest pet food processors with high-barrier polyethylene terephthalate laminates. The state's central location reduces freight costs to Southeast distribution hubs. Rockford manufacturing corridors are integrating oxygen-scavenging film technologies for grain-free diet packaging.
US Pet Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty barrier technologies and mono-material innovation. The vendor base organizes around three tiers: multinational converters with national extrusion networks, regional specialists in preformed pouch capacity, and niche players in fiber-based canisters. Strategic moves concentrate on M&A for geographic coverage and capacity expansion for EPR-compliant substrate output.
Among Australia-based multinational converters, Amcor plc exemplifies scale-driven supply security through blown film extrusion networks. Berry Global Inc. and Sonoco Products Company occupy distinct specialization tiers—Berry anchors preformed pouch capacity in the Midwest while Sonoco represents fiber-based canister differentiation for premium treat segments. These three producers illustrate how geographic concentration and format-specific expertise structure competitive positioning.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| ProAmpac LLC |
| Sealed Air Corporation |
| Coveris Holdings SA |
| American Packaging Corporation |
| Crown Holdings Inc. |
| Sonoco Products Company |
| Mondi plc |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up flexible film specialists dominate substrate supply, concentrating pricing power among blown extrusion networks while compressing margin pools for converters lacking backward integration into resin sourcing or captive recycled content streams.
Pricing Analysis
Polyethylene terephthalate and polypropylene feedstock pass-through dominates contract structures, with Gulf Coast petrochemical capacity disruptions transmitting directly to pouch converters within 30-60 day adjustment windows. Pricing stratifies across premium oxygen-scavenging laminates, standard high-barrier polyethylene constructions, and economy-grade mono-material pouches. Cost compression in standard tiers intensifies because California SB 54 compliance investments are absorbing converter capital, while subscription-format brands exhibit lowest price sensitivity and mass-market retail private labels face acute margin pressure.
Supply Chain Analysis
Metallized film supply rests on Japanese and German specialty coating producers, with domestic substrate finishing concentrated in Georgia and Illinois manufacturing corridors. Raw material streams draw from Saudi Arabian and Qatari polyethylene feedstock, South Korean biaxially oriented polypropylene, and Chinese aluminum metallization equipment. Single-source vulnerability sits with oxygen-scavenging additive chemistries from limited European suppliers. Distribution runs through Southeast co-packing clusters serving national brands via Savannah and Charleston port infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with California SB 54 mandates forcing packaging redesigns that create sustained demand for EPR-compliant substrate engineering and certified recycled content verification services.
For Market Incumbents: Cement supply security through backward integration into blown film extrusion capacity in the Southeast manufacturing corridor, where Savannah port access reduces resin import costs. Defend margin position by acquiring FDA food-contact notification expertise to accelerate barrier coating commercialization timelines, as emerging mono-material specialists threaten high-barrier laminate incumbents with faster regulatory approval pathways.
For New Entrants and Emerging Players: Begin with fresh-refrigerated format pouches for subscription-channel brands in Pacific Northwest urban corridors, where ship-ready primary packaging specifications remain underserved by legacy retail-focused converters. Target veterinary therapeutic nutrition segments requiring metallized barrier structures, as FDA migration testing bottlenecks deter rapid incumbent response and create regulatory moats for patient capital entrants.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional preformed pouch specialists lacking EPR-compliant substrate portfolios but possessing FDA 21 CFR 170-189 regulatory infrastructure. Long-term viability hinges on recycled content verification capabilities and mono-material innovation pipelines. The signal to watch is enforcement tightening on California SB 54 post-consumer recycled thresholds, which will strand non-compliant production assets and accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Capacity Expansion | Enables California SB 54 compliance and store-drop-off recycling compatibility for national brand portfolios. |
| Oxygen-Scavenging Film Technology Licensing | Accelerates shelf-life extension for grain-free and raw-coated diet formats without nitrogen flushing infrastructure. |
| Backward Integration into Blown Film Extrusion | Captures resin margin pools and insulates against Gulf Coast petrochemical supply disruptions. |
| FDA Food-Contact Notification Investment | Reduces barrier coating commercialization delays from multi-year timelines to single-season rollouts. |
| Southeast Co-Packing Corridor Partnership | Accesses contract packaging capacity for emerging brands seeking national distribution without capital-intensive facility investment. |
Research Methodology
Multiple input streams — converter production data, resin procurement patterns, and regulatory filing trajectories — were reconciled through structured primary interviews with flexible packaging plant managers, pet food brand supply chain directors, FDA regulatory affairs consultants, and retail category buyers, cross-validated against secondary sources including FDA 21 CFR food-contact substance notifications, EPA PFAS enforcement guidance, California SB 54 implementation documents, and trade customs records for polyethylene and polypropylene imports. Bottom-up capacity assessments triangulated against top-down demand modeling from pet food production volumes.
Data-stream reconciliation anchored volume and value projections across the analysis window through segmented modeling of packaging type, material substrate, product format, and closure mechanism, with geographic clustering by state-level regulatory exposure and manufacturing corridor concentration. CAGRs derived from elasticity-adjusted demand curves incorporating fresh-refrigerated format proliferation rates and EPR compliance investment cycles. Forecast inputs included oxygen-scavenging film adoption velocity and mono-material substitution timelines driven by retailer sustainability scorecards.
Several conditions sit outside the modeled scope, including unforeseen EPA PFAS restriction acceleration, breakthrough barrier technologies bypassing FDA notification requirements, and petrochemical supply disruptions exceeding historical volatility bands. Forecasts reflect documented assumptions about regulatory enforcement consistency and recycled content certification infrastructure development. A small set of named triggers warrants ongoing watch: California SB 54 threshold adjustments, FDA migration testing backlog resolution, and Gulf Coast resin capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market