
 Europe Nano Radiation Sensors Market | 2026-2036
Europe Nano Radiation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nano Radiation Sensors Market Insights
The Europe nano radiation sensors landscape is consolidating around a widening gap between premium semiconductor detector platforms and commodity Geiger-based units. First Sensor AG leverages its MEMS fabrication heritage to dominate high-resolution medical imaging subsystems. Hamamatsu Photonics K.K. sustains leadership in photodetector sensitivity through proprietary avalanche diode architectures. Kromek Group PLC specializes in cadmium zinc telluride crystals that anchor nuclear safety applications across British power stations.
Europe nano radiation sensors are solid-state or scintillation devices engineered to detect ionizing radiation at nanometer-scale feature resolution, typically employing semiconductor junctions with depletion widths below 100 nanometers or organic crystal matrices doped with wavelength-shifting fluorophores to achieve real-time dose-rate measurement in medically relevant energy bands. Fixed sensors command the largest installed base across European healthcare facilities, while integrated sensors represent the fastest-expanding category as OEMs embed radiation monitoring into CT gantries and radiotherapy delivery systems. Portable sensors occupy a mature margin pool dominated by industrial maintenance contracts, whereas standalone devices face displacement from modular platform strategies.
The EU Medical Device Regulation and ECHA REACH frameworks mandate biocompatibility and substance restriction compliance for sensors deployed in clinical settings, while the Euratom treaty directives enforce traceable calibration chains for nuclear safety equipment. France's ASN and Germany's BfS impose additional national type-approval requirements that fragment market access for non-European suppliers. Stakeholders must monitor the convergence of MDR cybersecurity annexes with radiation sensor data-integrity standards to anticipate certification cost escalations.
Market Dynamics
The EU Medical Device Regulation's calibration mandates are compressing the installed base toward certified semiconductor platforms while phasing out legacy Geiger-based units across German and French healthcare networks.
Growth Catalysts
- MDR cybersecurity annexes:France's ASN and Germany's BfS now require traceable digital calibration chains for radiotherapy dosimeters, forcing hospital procurement toward integrated sensor platforms.
- Cadmium zinc telluride crystal maturity:British nuclear power stations are retrofitting fixed sensor arrays with CZT-based units for real-time fuel rod monitoring under Euratom treaty enforcement.
- Precision radiotherapy expansion:German university hospitals are embedding nano-scale dosimeters directly into CT gantries to enable adaptive dose delivery during tumor targeting procedures.
Market Restraints
- Rare earth element concentration:CZT crystal feedstock depends on Chinese tellurium refining capacity, exposing European OEMs to supply quota volatility.
- Biocompatibility certification costs:ECHA REACH substance restrictions on sensor coatings add eighteen-month approval timelines for clinical deployment.
- Photodetector sensitivity thresholds:Avalanche diode architectures face fundamental quantum efficiency limits below 50 keV, constraining low-dose medical imaging applications.
Strategic Opportunities
- Polish industrial maintenance contracts:Underpenetrated Polish steel and chemical facilities lack radiation monitoring infrastructure, creating first-mover openings for portable sensor vendors.
- Scintillation-photodetector hybrid platforms:Converging organic crystal matrices with silicon photomultipliers enables single-chip dose-rate measurement across expanded energy bands.
- EU Green Deal decommissioning mandates:Accelerated French and Belgian reactor shutdowns require dense sensor networks for spent fuel pool monitoring and site remediation.
Industry Challenges
- MEMS fabrication skill scarcity:European foundries lack trained process engineers for sub-100 nanometer depletion width semiconductor junctions.
- Legacy system integration friction:Hospital IT networks resist radiation sensor data streams due to incompatible DICOM-RT protocols and cybersecurity audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nano Radiation Sensors Market |
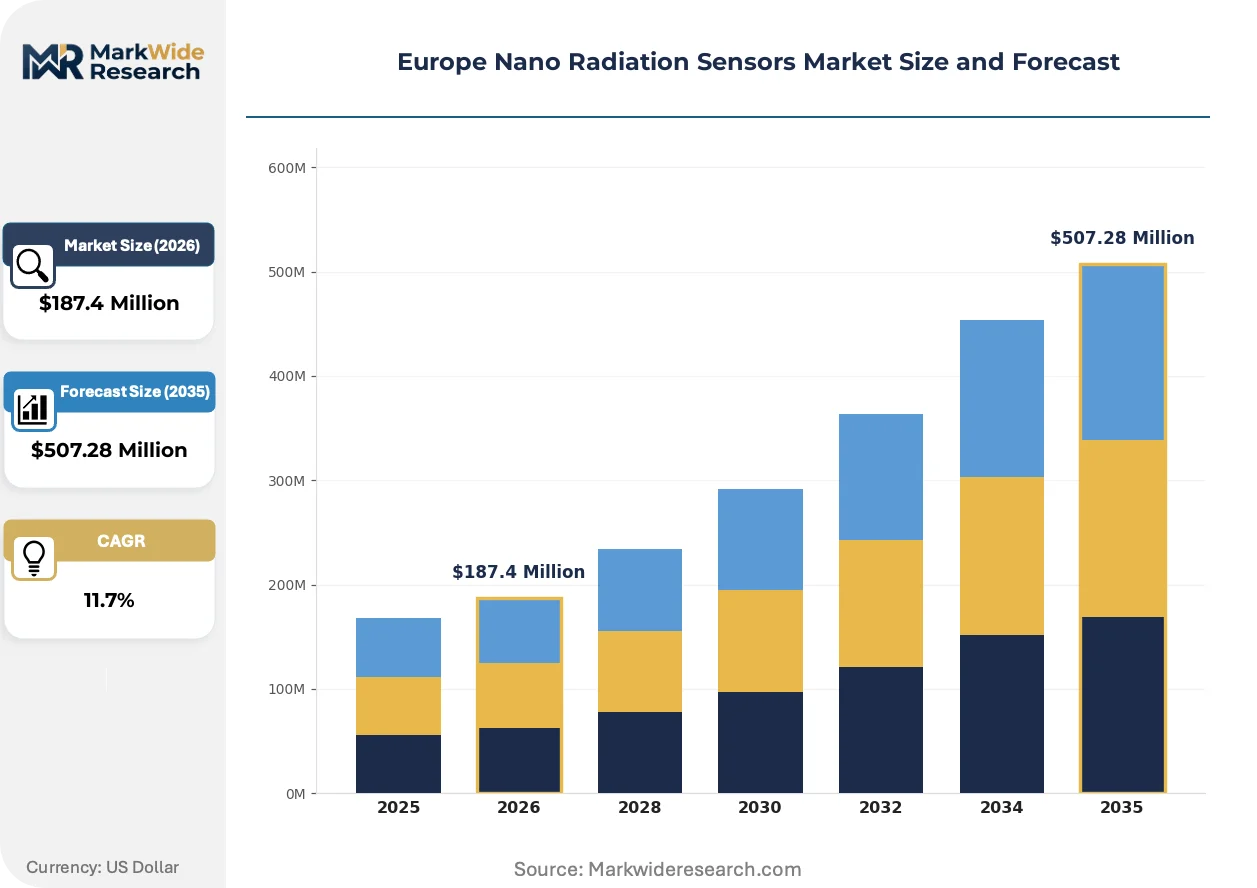
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Fixed Sensors, Integrated Sensors, Standalone Devices End User: Healthcare Facilities, Research Institutions, Industrial Applications, Military Technology: Semiconductor Detectors, Photodetectors, Organic Scintillators, Geiger Counters Application: Radiation Monitoring, Environmental Safety, Medical Imaging, Nuclear Safety |
| Companies Covered | First Sensor AG, Hamamatsu Photonics K.K., Thermo Fisher Scientific Inc., Mirion Technologies, Robert Bosch GmbH, Kromek Group PLC, Baker Hughes Company, Fluke Corporation, Sensor Systeme-Geraetetechnik GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nano Radiation Sensors Market Trends and Innovations
Semiconductor junction miniaturization is compressing feature resolution thresholds while regulatory data-integrity mandates reshape certification pathways. Three forces are actively restructuring competitive positioning.
Solid-state avalanche photodiodes with nanometer-scale multiplication layers are overtaking vacuum photomultiplier tubes in scintillation readout chains. German radiotherapy OEMs are adopting these platforms for integrated gantry-mounted dosimetry. The shift is compressing after-sales service revenue pools as solid-state units eliminate dynode replacement cycles.
REACH substance restriction expansions are forcing coating reformulations for clinical-grade sensors. Industrial consequence includes eighteen-month recertification timelines for existing product lines. French medical device distributors are responding by consolidating supplier portfolios around pre-certified semiconductor platforms.
Hospital procurement committees now mandate cybersecurity validation alongside radiometric performance in radiation detection equipment. Traditional component distributors are losing share to authorized OEM channels with embedded compliance documentation. This behavioral shift is most visible in German university hospital networks with centralized procurement functions.
Europe Nano Radiation Sensors Market Segmentation
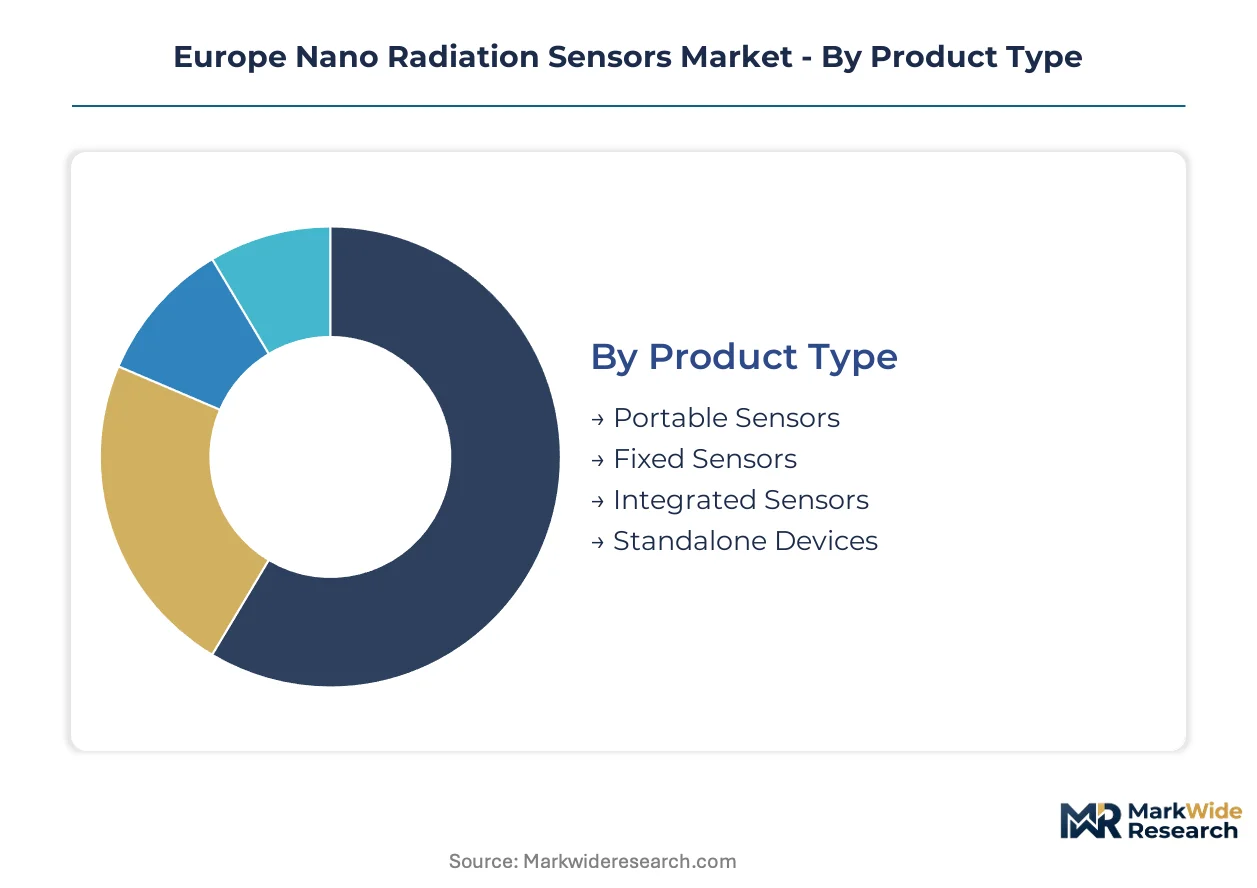
Nano radiation sensors fragment across four critical dimensions that determine procurement workflows, certification burdens, and margin structures. Product architecture dictates whether units ship as discrete instruments or embedded subsystems. End-user concentration in German healthcare and French nuclear facilities shapes regional demand patterns. Technology selection between solid-state and legacy platforms carries direct implications for MDR compliance timelines.
Product Type:
Integration depth separates segments that demand standalone calibration infrastructure from those that ride inside OEM equipment. Fixed and integrated sensors anchor hospital capital expenditure cycles, while portable and standalone units serve spot-check maintenance workflows.
- Portable Sensors:Battery-powered handheld units with silicon photodiode front-ends and wireless data logging. Polish steel mills and chemical plants procure these for confined-space maintenance crews where fixed infrastructure is absent. REACH coating recertification delays are compressing vendor margins on replacement cycles.
- Fixed Sensors:Permanently mounted semiconductor junction arrays with hardwired power and centralized monitoring backends. British nuclear power stations deploy CZT-based fixed grids for continuous fuel rod surveillance under Euratom treaty traceability mandates. The installed base here commands the largest revenue pool across European healthcare and nuclear networks.
- Integrated Sensors:Subsystem modules designed for embedding into CT gantries and radiotherapy delivery systems. German university hospitals specify these for adaptive dose-rate feedback during tumor targeting procedures.
- Standalone Devices:Self-contained instruments with internal processing and local display readouts. Industrial maintenance contractors favor these for decommissioning site surveys where network connectivity is unreliable.
Fixed sensors lead volumes today; integrated sensors are climbing the fastest as OEMs embed radiation monitoring into imaging equipment.
End User:
Customer type determines regulatory pathway complexity and procurement committee composition. Healthcare and nuclear sectors impose the strictest calibration chains, while industrial and military buyers prioritize field durability over certification depth.
- Healthcare Facilities:German university hospitals and French cancer centers drive procurement of gantry-embedded dosimeters. MDR cybersecurity annexes now require traceable digital calibration chains, forcing procurement toward integrated platforms with embedded compliance documentation.
- Research Institutions:CERN and similar facilities demand custom semiconductor detector arrays for particle physics applications. Budget cycles here run on multi-year grant timelines with delayed purchasing decisions.
- Industrial Applications:Steel, chemical, and waste processing facilities across Poland and Eastern Europe lack radiation monitoring infrastructure, creating first-mover openings for portable sensor vendors.
- Military:Defense procurement offices specify ruggedized units with EMP-hardened electronics and offline operational modes. Contracts favor established suppliers with security clearance frameworks.
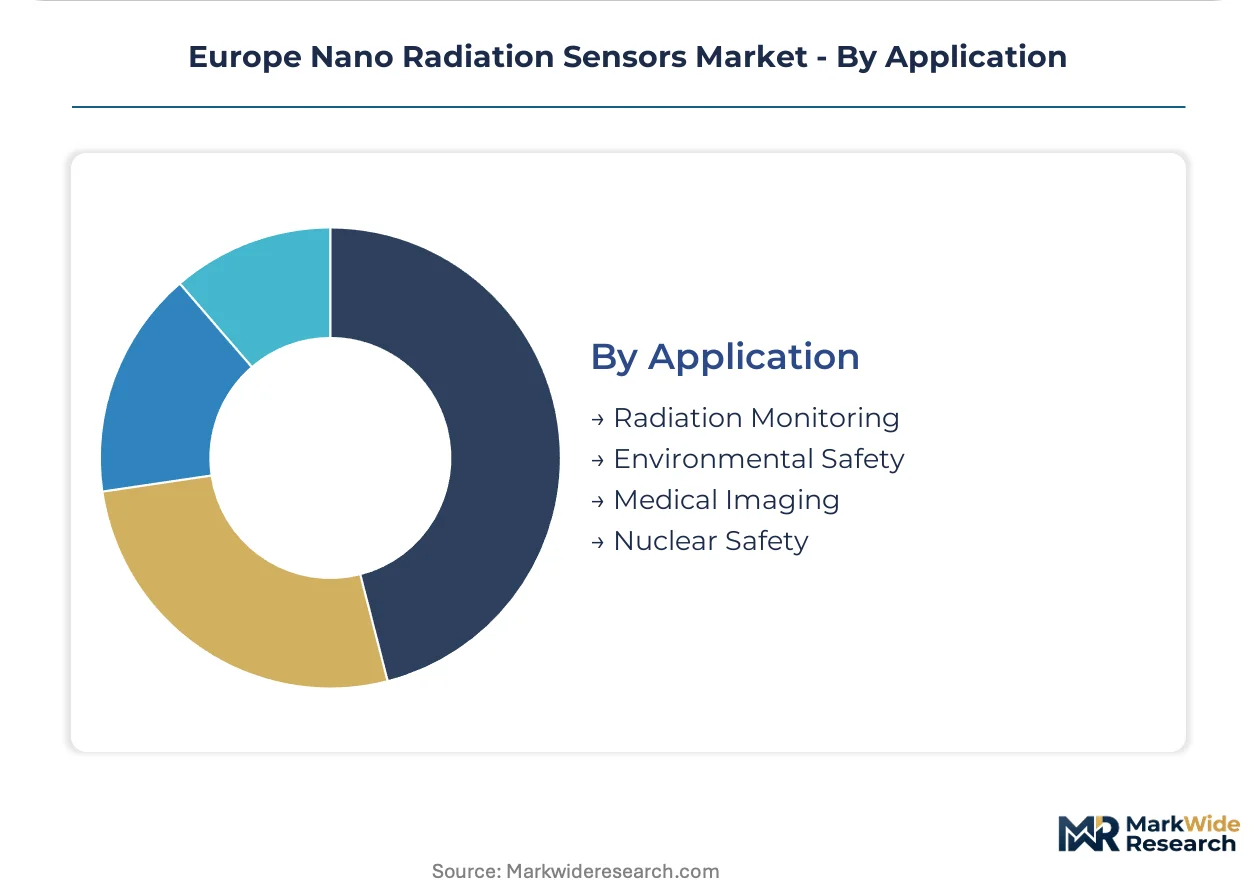
Healthcare facilities dominate revenue concentration; industrial applications show the steepest expansion trajectory as Polish and Romanian facilities retrofit safety infrastructure.
Technology:
Platform selection crystallizes the competitive divide between premium semiconductor architectures and legacy Geiger-based units facing phase-out under tightening calibration standards.
- Semiconductor Detectors:Solid-state junction devices with depletion widths below 100 nanometers for nanometer-scale spatial resolution. First Sensor AG leverages MEMS fabrication heritage to anchor high-resolution medical imaging subsystems. MEMS process engineer scarcity across European foundries constrains capacity scaling.
- Photodetectors:Avalanche diode architectures with proprietary multiplication layer geometries. Hamamatsu Photonics K.K. sustains leadership in sensitivity thresholds, though quantum efficiency limits below 50 keV constrain low-dose imaging applications.
- Organic Scintillators:Crystal matrices doped with wavelength-shifting fluorophores for real-time dose-rate measurement. Convergence with silicon photomultipliers enables single-chip solutions across expanded energy bands.
- Geiger Counters:Legacy gas-filled tubes with simple pulse-counting electronics. MDR calibration mandates are compressing the installed base toward certified semiconductor platforms while phasing these units out of German and French healthcare networks.
Semiconductor detectors command the premium tier; organic scintillator-photodetector hybrids are expanding most quickly as vendors converge crystal and solid-state readout technologies.
Application:
Use-case context determines sensor specification, from medical energy bands to nuclear fuel rod monitoring spectra, with direct impact on crystal material selection and readout chain architecture.
- Radiation Monitoring:Continuous dose-rate surveillance in occupational health contexts. German BfS mandates shape procurement specifications for workplace safety compliance.
- Environmental Safety:Atmospheric and groundwater monitoring around decommissioning sites. EU Green Deal reactor shutdowns in France and Belgium are accelerating deployment of dense sensor networks for spent fuel pool surveillance.
- Medical Imaging:Real-time dosimetry integrated into CT and radiotherapy workflows. Precision radiotherapy expansion at German university hospitals is embedding nano-scale dosimeters directly into gantry architectures for adaptive dose delivery.
- Nuclear Safety:Critical infrastructure protection and fuel cycle monitoring. French ASN type-approval requirements fragment market access for non-European suppliers seeking entry to this segment.
Medical imaging generates the highest unit margins; nuclear safety applications are gaining share fastest under EU Green Deal decommissioning mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates medical imaging procurement while France dominates nuclear safety deployment, yet Poland's industrial retrofit wave is generating the steepest expansion trajectory across the continent.
Germany
German university hospitals are embedding nano-scale dosimeters into CT gantries for adaptive radiotherapy. The BfS mandates traceable digital calibration chains that compress procurement toward certified semiconductor platforms. Bavaria's precision engineering clusters around Munich anchor MEMS fabrication capacity for medical imaging subsystems.
France
French cancer centers drive gantry-embedded dosimeter procurement alongside ASN-mandated nuclear safety networks. The EU Green Deal accelerates reactor decommissioning around Normandy and Grand Est, requiring dense sensor arrays for spent fuel monitoring. Île-de-France hosts Europe's densest concentration of radiotherapy equipment OEMs.
United Kingdom
British nuclear power stations retrofit CZT-based fixed sensor grids for continuous fuel rod surveillance. Euratom treaty enforcement demands traceable calibration infrastructure that favors established semiconductor vendors. The Cumbrian nuclear cluster around Sellafield represents the continent's largest decommissioning sensor deployment site.
Poland
Polish steel mills and chemical facilities lack radiation monitoring infrastructure, creating first-mover openings for portable sensor vendors. REACH substance restrictions delay coating recertification but do not block market entry for compliant suppliers. The Silesian industrial basin around Katowice concentrates unmet demand from legacy heavy industry facilities.
Belgium
Belgian reactor shutdowns under EU Green Deal mandates require sensor networks for site remediation and spent fuel pool surveillance. The national nuclear regulator enforces type-approval requirements that fragment access for non-European suppliers. The Mol-Dessel nuclear research cluster drives specialized procurement for experimental reactor monitoring applications.
Europe Nano Radiation Sensors Market Competitive Landscape
Top-tier vendors anchor premium semiconductor detector platforms, while mid-tier specialists occupy scintillation-photodetector hybrid niches and legacy Geiger-based units face phase-out. The vendor base stratifies across MEMS fabrication heritage, crystal growth specialization, and integrated OEM subsystem supply. Two strategic archetypes dominate: semiconductor junction miniaturization leaders and CZT crystal vertical integrators. Competitive moves concentrate on strategic partnerships with radiotherapy OEMs and geographic expansion into underpenetrated Eastern European industrial markets.
Within the MEMS fabrication tier, First Sensor AG exemplifies German precision engineering heritage applied to medical imaging subsystems. Hamamatsu Photonics K.K. occupies a position among photodetector sensitivity specialists leveraging proprietary avalanche architectures. Kromek Group PLC represents the CZT crystal vertical integration archetype serving nuclear safety applications.
| Leading Market Players |
|---|
| First Sensor AG |
| Hamamatsu Photonics K.K. |
| Thermo Fisher Scientific Inc. |
| Mirion Technologies |
| Robert Bosch GmbH |
| Kromek Group PLC |
| Baker Hughes Company |
| Fluke Corporation |
| Sensor Systeme-Geraetetechnik GmbH |
| Others |
Pricing and Supply Chain Analysis
Tellurium spot price volatility on the Shanghai Metals Market cascades through CZT crystal feedstock costs, compressing margins for European OEMs while forcing pricing stratification across premium semiconductor platforms and commodity Geiger-based units facing phase-out.
Pricing Analysis
Capacity additions in Bavaria's MEMS foundry clusters are reshaping price floors for medical imaging subsystems. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified integrated sensors from portable maintenance units. Price differentiation hinges on calibration traceability depth and cybersecurity documentation bundling. Pricing pressure stems from REACH coating recertification timelines extending eighteen months. Industrial maintenance contractors in Poland exhibit highest price sensitivity; German university hospital procurement committees prioritize compliance over unit cost.
Supply Chain Analysis
MDR cybersecurity annexes and ECHA REACH substance restrictions gate supplier qualification, extending vendor onboarding cycles. Crystal feedstock concentrates in Chinese tellurium refineries and Japanese selenium processors; MEMS fabrication anchors in German and Taiwanese foundries. Raw material dependencies span CZT ingots, avalanche diode wafers, and wavelength-shifting fluorophores. Single-source vulnerability runs through Chinese tellurium quota administration. Distribution runs through authorized OEM channels with embedded compliance documentation, displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe nano radiation sensors market compounds steadily as precision radiotherapy expansion and EU Green Deal decommissioning mandates sustain replacement cycles across healthcare and nuclear infrastructure.
For Market Incumbents: Deploy backward integration into CZT crystal growth to secure feedstock against Chinese tellurium quota volatility. Fortify hospital system partnerships with embedded cybersecurity documentation to defend against emerging semiconductor detector specialists. Capture Polish industrial maintenance contracts before REACH-compliant coating capacity saturates. For New Entrants and Emerging Players: Radiotherapy OEM channel partners represent the fastest path to integrated sensor procurement committees. Polish steel and chemical facilities lack radiation monitoring infrastructure, creating first-mover openings for portable sensor vendors with REACH-compliant coatings. Target decommissioning site surveys in Belgium and France where standalone device demand outpaces incumbent service capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with MEMS fabrication specialists possessing sub-100 nanometer depletion width process expertise. Five-to-ten year viability favors vendors with dual healthcare-nuclear certification pathways. Watch for inflection when German BfS publishes revised cybersecurity calibration annexes triggering hospital procurement committee vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Accelerates hospital procurement committee access under tightened German BfS calibration mandates. |
| CZT Crystal Backward Integration | Reduces exposure to Chinese tellurium quota volatility for nuclear safety sensor arrays. |
| Polish Distribution Partnership | Captures first-mover position in Silesian steel mill radiation monitoring retrofit wave. |
| Scintillation-Photodetector Hybrid R&D | Enables single-chip dose-rate measurement spanning expanded medical imaging energy bands. |
| Decommissioning Site Service Contract | Locks recurring revenue from EU Green Deal reactor shutdowns in France and Belgium. |
Research Methodology
Direct dialogue with radiotherapy equipment OEMs, hospital biomedical engineers, nuclear safety procurement officers, and CZT crystal foundry managers grounded qualitative findings in operational reality. Secondary validation drew from EMA MDR guidance documents, Euratom treaty implementation reports, ECHA REACH substance restriction updates, and German BfS calibration standard publications. Bottom-up unit demand modeling across healthcare facilities and nuclear power stations triangulated against top-down semiconductor and scintillator material flow analysis.
Segment-level revenue outputs across product type, end user, technology, and application dimensions fed into analytical framework calibration over the projection horizon. CAGRs derived from weighted average of historical replacement cycle analysis and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated German university hospital capital expenditure pipelines and French reactor decommissioning timelines under EU Green Deal commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese rare earth export policy shifts and MEMS fabrication engineer training pipeline expansion. Model outputs reflect assumptions on MDR cybersecurity annex enforcement timing and REACH coating recertification backlog resolution. A model refresh is warranted upon material change in German BfS calibration standard publication schedules or Chinese tellurium quota administration announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
RET Controller Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market