
 Ultrasound Sensors Market | 2026-2036
Ultrasound Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Sensors Market Outlook
Multi-source procurement for piezoelectric elements and MEMS wafers is broadening as OEMs reduce single-supplier risk in ultrasound sensor fabrication. Keyence Corporation leverages its direct-sales channel to control pricing and technical support across Asian manufacturing hubs. Pepperl+Fuchs AG anchors its position through hazardous-area certifications that dominate process-industry deployments. Siemens AG extends its footprint by integrating ultrasound level sensors into its distributed control system architecture.
Ultrasound sensors convert electrical energy into acoustic waves above human hearing range, typically operating between 20 kHz and 10 MHz depending on medium and target resolution, to detect distance, flow, or material integrity without physical contact. Industrial ultrasound and medical ultrasound represent the largest product categories, with industrial applications maturing around level measurement while medical imaging commands premium margins through transducer array complexity. Piezoceramic technology leads in transmit-receive efficiency for long-range detection, whereas MEMS technology captures the fastest growth trajectory through silicon-batch scalability and integration with automotive parking-assist modules.
The FDA's 510(k) clearance pathway shapes product development timelines for medical ultrasound sensors entering the US market, while EU MDR technical documentation requirements raise compliance costs for European access. ISO 10993 biocompatibility standards and IEC 60601 electromagnetic compatibility frameworks further constrain design choices for healthcare-bound devices. Stakeholders must monitor convergence between automotive functional-safety mandates and industrial IoT cybersecurity standards as sensor platforms serve dual-use environments.
Market Dynamics
The ultrasound sensors market faces a structural squeeze between automotive OEM cost-down mandates and medical device quality escalation, forcing fabricators to reconcile MEMS batch economics with piezoceramic performance benchmarks across dual certification regimes.
Growth Catalysts
- EU MDR technical documentation mandates:European conformity requirements for medical ultrasound transducers are accelerating replacement cycles in diagnostic imaging suites, pulling demand for next-generation probe arrays.
- Automotive parking-assist module proliferation:ADAS integration timelines in passenger vehicle platforms are absorbing silicon-MEMS ultrasound units at volumes that justify dedicated wafer capacity.
- German precision engineering clusters:Industrial sensor procurement from Baden-Württemberg and Bavaria manufacturing hubs is concentrating supply relationships around hazardous-area certified level measurement systems.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity PZT powder production clusters in specific Asian jurisdictions create single-source vulnerability for long-range industrial detection applications.
- FDA 510(k) clearance timelines:US regulatory pathway duration for novel ultrasound transducer designs extends product development cycles and freezes capital commitment until predicate device equivalence is established.
- Optical time-of-flight substitution:Solid-state LiDAR modules in premium automotive segments are capturing price-insensitive positioning applications that previously defaulted to ultrasound arrays.
Strategic Opportunities
- Point-of-care diagnostics expansion:Portable ultrasound system deployment in rural India and Southeast Asian primary care networks is opening volume markets for simplified transducer architectures.
- ISO 10993 biocompatibility convergence:Harmonized material safety standards across FDA and notified body frameworks are enabling single-design medical probes to serve dual-continent registration strategies.
- Industrial IoT cybersecurity standard integration:IEC 62443 framework adoption for process automation networks is creating certified-secure ultrasound level sensor demand in chemical and pharmaceutical facilities.
Industry Challenges
- MEMS-CMOS process engineer scarcity:Foundry-level talent capable of integrating ultrasound transducer fabrication with automotive-grade silicon production commands premium compensation and extended recruitment cycles.
- Legacy distributed control system integration:Brownfield industrial facilities running proprietary fieldbus protocols require custom gateway development to deploy modern ultrasound level sensors without wholesale automation replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Sensors Market |
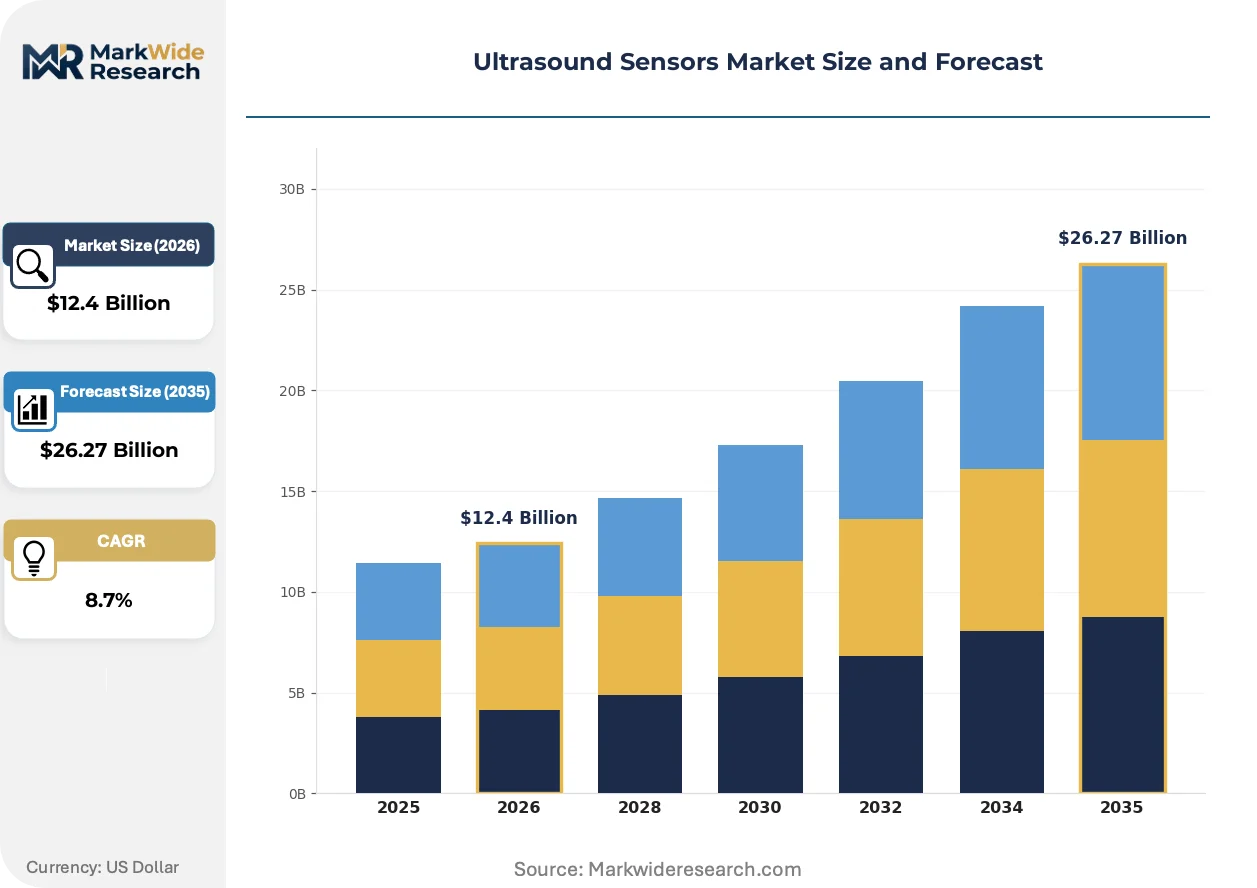
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Ultrasound, Industrial Ultrasound, Automotive Ultrasound, Consumer Electronics Technology: Piezoceramic, MEMS, Capacitive, Optical Application: Non-destructive Testing, Medical Imaging, Level Measurement, Liquid Flow Measurement End User: Healthcare Providers, Manufacturing Facilities, Automotive Industry, Research Institutions |
| Companies Covered | Keyence Corporation, Pepperl+Fuchs AG, Honeywell International Inc., SICK AG, Baumer Holding AG, Omron Corporation, Rockwell Automation Inc., Siemens AG, Banner Engineering Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Sensors Market Strategic Shifts
Capacitive micromachined ultrasound transducers are rewriting competitive boundaries between medical imaging fidelity and automotive cost structures, while regulatory fragmentation between FDA 510(k) and EU MDR pathways is forcing parallel development tracks.
CMUT arrays are rewriting the trade-off between acoustic bandwidth and manufacturing scalability in diagnostic probe fabrication. Cardiology and obstetrics departments in US hospital systems are piloting CMUT-enabled portable scanners that compress examination room footprint requirements. The technology is rewriting margin structures by collapsing the discrete transducer assembly steps that previously dominated piezoceramic probe production economics.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for ultrasound transducer manufacturers seeking European market access. Notified body capacity constraints are creating queue delays that compress product launch windows against competitor entries. Medical device divisions are responding by front-loading clinical evaluation reports and biocompatibility testing to parallelize rather than sequence submission packages.
Direct procurement relationships between automotive OEMs and MEMS foundries are disintermediating traditional ultrasound sensor module suppliers in parking-assist and cabin monitoring applications. Tier-1 electronics distributors are losing specification influence as vehicle platform engineers specify transducer die characteristics at the wafer level. This pattern is most visible in German and South Korean automotive engineering centers where vertical integration into silicon fabrication is being replicated across multiple OEMs.
Ultrasound Sensors Market Segmentation
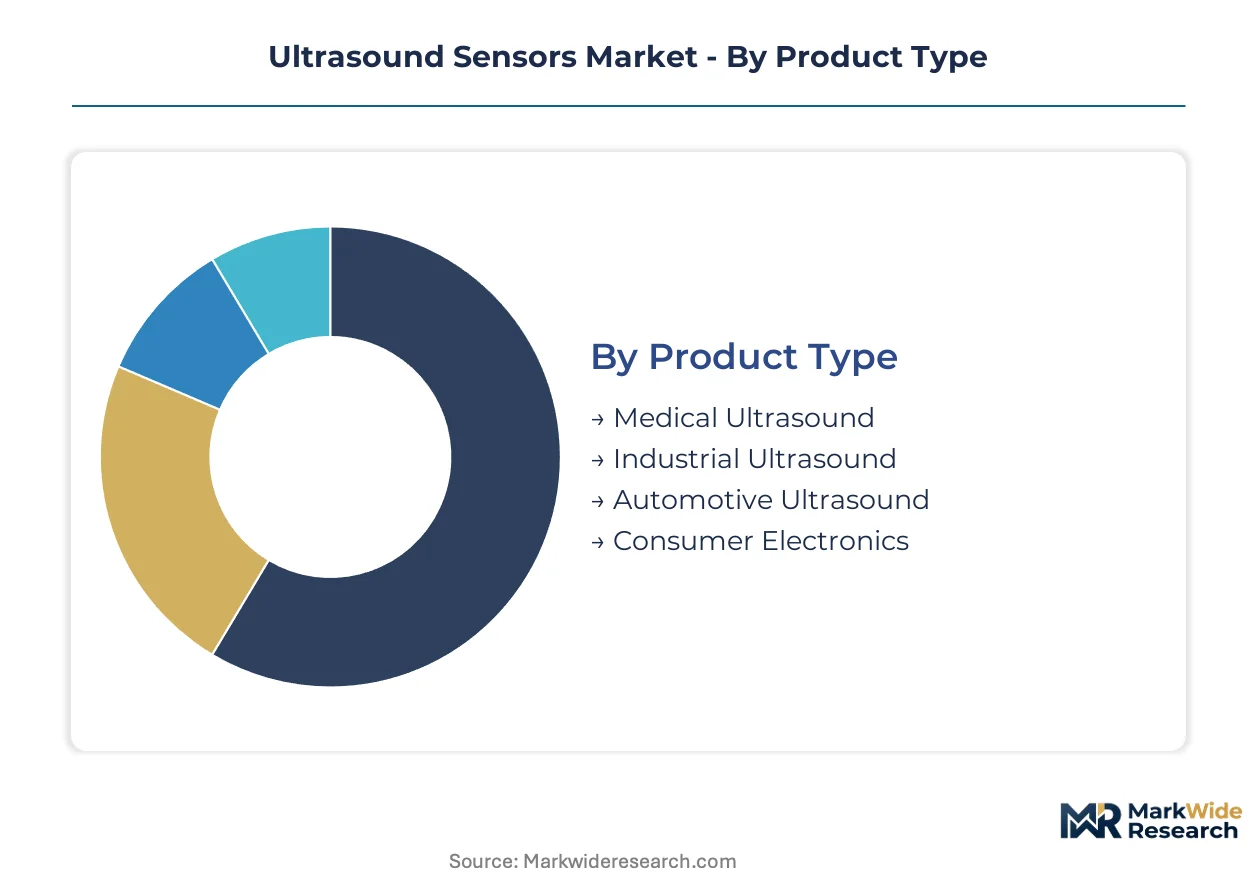
Ultrasound sensor architectures diverge sharply between premium medical imaging arrays demanding acoustic precision and high-volume automotive modules prioritizing silicon-batch economics. Fabricators must maintain dual process competencies across piezoceramic transmit-receive efficiency and MEMS-CMOS integration to serve these diverging value pools.
Product Type:
Medical ultrasound commands premium pricing through transducer array complexity while automotive ultrasound absorbs unit volumes that justify dedicated wafer foundry capacity.
- Medical Ultrasound:Diagnostic imaging transducers operate across 2-15 MHz bandwidths with 128-512 element arrays for tissue differentiation. US hospital systems and German university medical centers are standardizing on portable probe architectures that reduce examination room footprints.
- Industrial Ultrasound:Level measurement and non-destructive testing systems deploy piezoceramic elements for long-range detection in chemical processing and pipeline integrity monitoring. Procurement concentrates in German precision engineering clusters around Baden-Württemberg hazardous-area certified installations.
- Automotive Ultrasound:Parking-assist and cabin-monitoring modules integrate silicon-MEMS transducers at volumes that disintermediate traditional sensor suppliers through direct OEM-foundry relationships.
- Consumer Electronics:Gesture recognition and proximity detection in smartphones and wearables employ compact MEMS packages with simplified signal processing chains.
Today's leader: Medical Ultrasound. Tomorrow's challenger: Automotive Ultrasound.
Technology:
Material platforms separate around transmit-receive efficiency versus semiconductor scalability, with capacitive micromachined alternatives rewriting fabrication economics.
- Piezoceramic:Lead zirconate titanate (PZT) compositions deliver superior electromechanical coupling for long-range industrial detection. Single-source vulnerability in high-purity powder production constrains supply security for critical infrastructure applications.
- MEMS:Silicon-batch fabrication enables automotive parking-assist integration at cost structures piezoceramics cannot match. South Korean and German automotive engineering centers are driving wafer-level specification trends.
- Capacitive:CMUT arrays collapse discrete assembly steps through semiconductor-compatible processes, gaining traction in cardiology and obstetrics portable scanners.
- Optical:Laser-based alternatives capture price-insensitive positioning applications in premium automotive segments where solid-state LiDAR substitutes for ultrasound arrays.
Piezoceramic retains performance dominance. MEMS scales fastest.
Application:
Functional requirements range from sub-millimeter defect resolution in materials testing to continuous level monitoring in bulk chemical storage.
- Non-destructive Testing:Ultrasonic flaw detection in aerospace components and welded structures requires calibrated probe arrays with documented traceability to ISO standards.
- Medical Imaging:Diagnostic suites in US and European healthcare systems are replacing legacy probe inventories to meet EU MDR technical documentation mandates.
- Level Measurement:Process industry deployments in pharmaceutical and chemical facilities require IEC 62443 cybersecurity certification for networked sensor integration.
- Liquid Flow Measurement:Clamp-on transit-time and Doppler systems serve water utility and hydrocarbon custody transfer applications with non-invasive installation advantages.
Medical Imaging generates margin concentration. Level Measurement expands through industrial IoT retrofit cycles.
End User:
Procurement authority varies between centralized hospital system purchasing committees and distributed automotive platform engineering teams.
- Healthcare Providers:US hospital networks and Indian primary care expansion programs are driving demand for simplified transducer architectures in point-of-care deployment.
- Manufacturing Facilities:Brownfield chemical plants running proprietary fieldbus protocols require custom gateway development to integrate modern ultrasound level sensors.
- Automotive Industry:OEM engineering centers in Germany and South Korea specify transducer die characteristics at wafer level, compressing Tier-1 distributor influence.
- Research Institutions:Academic medical centers and materials science laboratories pilot CMUT-enabled scanners and advanced non-destructive testing methodologies.
Healthcare Providers anchor premium demand. Automotive Industry reshapes supply chain geometry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering clusters anchor industrial ultrasound procurement through automotive OEM supply chains and hazardous-area certified process instrumentation.
United States
FDA 510(k) clearance pathways shape medical transducer development timelines for diagnostic imaging suites. US hospital networks are standardizing on portable probe architectures that compress examination room footprints. Greater Boston and Minneapolis-St. Paul medical device corridors concentrate CMUT pilot deployments in cardiology departments.
Germany
EU MDR technical documentation mandates accelerate replacement cycles in university medical centers and diagnostic imaging networks. KBA automotive safety standards integrate MEMS ultrasound modules into parking-assist platforms. Bavaria and Baden-Württemberg manufacturing hubs concentrate hazardous-area certified level sensor procurement for chemical processing facilities.
China
NMPA medical device registration reforms streamline ultrasound transducer approval timelines for domestic manufacturers. MIIT industrial automation standards drive MEMS sensor integration into smart manufacturing lines. Yangtze River Delta semiconductor foundries absorb wafer-level specifications from automotive engineering centers.
Japan
METI industrial IoT cybersecurity guidelines shape networked ultrasound sensor deployment in pharmaceutical and chemical facilities. PMDA quality management requirements maintain stringent benchmarks for diagnostic probe exports. Nagoya automotive engineering corridors specify silicon-MEMS transducer characteristics for cabin monitoring systems.
South Korea
MFDS medical device approval pathways align with international standards to accelerate probe registration for export markets. Automotive OEM engineering centers in Seoul and Busan-Ulsan regions specify wafer-level transducer die characteristics, compressing traditional Tier-1 distributor influence in parking-assist module procurement.
Ultrasound Sensors Market Competitive Environment
Global majors compete with regional champions across certification regimes and direct-sales channel control. The vendor base stratifies around three tiers: diversified industrial automation conglomerates with distributed control system integration capabilities, specialized sensor fabricators holding hazardous-area and functional-safety certifications, and MEMS foundry-direct suppliers serving automotive OEM wafer-level specifications. Dominant competitive moves include backward integration into piezoelectric material supply and strategic partnerships to bridge legacy fieldbus protocols with industrial IoT architectures.
Among diversified industrial automation conglomerates, Siemens AG and Rockwell Automation Inc. exemplify platform-integrated positioning through distributed control system architectures. Keyence Corporation anchors the specialized sensor fabricator tier through direct-sales channel control across Asian manufacturing hubs. Pepperl+Fuchs AG occupies a certification-differentiated position through hazardous-area approvals that dominate process-industry deployments.
| Leading Market Players |
|---|
| Keyence Corporation |
| Pepperl+Fuchs AG |
| Honeywell International Inc. |
| SICK AG |
| Baumer Holding AG |
| Omron Corporation |
| Rockwell Automation Inc. |
| Siemens AG |
| Banner Engineering Corp. |
| Others |
Value Chain & Pricing Dynamics
CMUT semiconductor fabrication is collapsing discrete transducer assembly costs while simultaneously concentrating probe manufacturing in MEMS-capable foundries. This dual compression of cost structure and supplier base is reshaping how medical device OEMs negotiate wafer-level contracts versus traditional piezoceramic module procurement.
Pricing Analysis
Input-cost pass-through from high-purity PZT powder and silicon wafer substrates dominates pricing mechanics across the three-tier structure separating premium medical arrays from standard industrial units and economy automotive modules. Price differentiation hinges on FDA 510(k) certification tier and volume scale commitments, with automotive OEMs extracting steepest discounts through wafer-level direct sourcing. Pricing pressure stems from automotive cost-down mandates compressing MEMS module margins. Healthcare providers show least price sensitivity due to reimbursement insulation, while consumer electronics buyers drive hardest bargain.
Supply Chain Analysis
China's NMPA domestic-content incentives and India's PLI scheme for medical devices are reshaping sourcing patterns for transducer assembly and final probe manufacturing. Geographic supply concentration centers on China for PZT powder refining, Taiwan and South Korea for MEMS wafer fabrication, and Germany for precision industrial sensor finishing. Raw material dependencies include lead zirconate titanate ceramics, silicon wafers, and specialized acoustic matching layers. Single-source vulnerability in high-purity piezoelectric powder creates structural risk for long-range industrial detection applications. Distribution runs through direct OEM-foundry relationships in automotive, specialized sensor distributors in industrial, and GPO contracts in healthcare.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasound sensors market represents a late-cycle quality story as EU MDR technical documentation mandates and FDA 510(k) predicate requirements elevate certification barriers. Demand is shifting toward premium probe architectures that satisfy dual-continent registration strategies.
For Market Incumbents: Acquire MEMS-CMOS process engineering talent pools to defend against foundry-direct disintermediation by automotive OEMs. Consolidate backward integration into piezoelectric material supply to secure PZT powder access against single-source concentration risk. Invest in IEC 62443 cybersecurity certification for industrial IoT level sensor deployments.
For New Entrants and Emerging Players: Rural Indian primary care networks present an underserved buyer archetype with volume potential for simplified portable ultrasound architectures. Target Southeast Asian point-of-care diagnostics expansion where regulatory pathways remain less congested than US or EU. Pursue software-companion development partnerships with existing probe manufacturers rather than competing on transducer hardware.
For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor fabricators holding hazardous-area certifications because EU MDR and automotive functional-safety mandates are fragmenting compliance capabilities across smaller players. Five-to-ten year viability favors firms with dual piezoceramic and MEMS process competencies. Monitor notified body capacity constraints as inflection indicator for medical device registration bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Materials | Captive PZT powder supply secures long-range industrial sensor production against Asian supply concentration. |
| CMUT Manufacturing Scale-Up | Semiconductor-compatible fabrication collapses cardiology probe costs for portable scanner deployment. |
| EU MDR Technical Documentation Investment | Front-loaded conformity assessment accelerates diagnostic imaging suite replacement cycles. |
| Automotive Wafer-Level Partnership | Direct OEM-foundry relationships disintermediate Tier-1 distributors in parking-assist module supply. |
| IEC 62443 Cybersecurity Certification | Networked level sensor demand in chemical facilities requires certified-secure process automation integration. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and specification shifts. Primary engagement spanned biomedical engineers at US hospital systems, automotive platform engineers in German and South Korean engineering centers, and process automation procurement leads at chemical facilities. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, and automotive supplier registration databases. Bottom-up probe shipment modeling and top-down healthcare capital equipment expenditure analysis were cross-referenced for triangulation.
Historical reference periods anchored volume and value projections across the analysis window, with growth trajectories derived from segment-specific adoption curves and replacement cycle timing. Segmentation dimensions modeled include product architecture, material technology platform, end-use application, and regional regulatory cluster. Forecast inputs incorporated EU MDR implementation timelines, automotive ADAS penetration assumptions, and industrial IoT retrofit cycle patterns.
Underlying measurement precision varies by segment; medical imaging transducers carry tighter precision than emerging consumer electronics applications due to established procurement reporting channels. Forecasts reflect assumptions about regulatory pathway durations and automotive platform engineering decisions that could shift materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Europe Machine Control System Market