
 Nano Radiation Sensors Market | 2026-2036
Nano Radiation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Radiation Sensors Market Foresight
Medical imaging is restructuring the buyer landscape for nano radiation sensors as hospitals replace legacy ionization chambers with solid-state alternatives. Thermo Fisher Scientific leverages its life sciences distribution network to dominate hospital procurement channels. Hamamatsu Photonics K.K. anchors its position through captive photodiode manufacturing that feeds directly into scintillation detector assemblies. Kromek Group plc differentiates via cadmium zinc telluride (CZT) material science that enables room-temperature spectroscopy without cryogenic cooling.
Nano radiation sensors are solid-state devices engineered with nanoscale active layers—typically CZT, silicon PIN structures, or quantum dot films—that convert incident ionizing radiation into quantifiable electrical signals with energy resolution below 2% at 662 keV. Their primary commercial purpose is real-time dose quantification and isotope identification in environments where conventional Geiger-Müller tubes lack spectral discrimination. Portable detectors command premium pricing in emergency response deployments where field-deployable spectroscopy determines contamination spread within minutes. Quantum dot technology is gaining fastest among research institutions exploring solution-processed alternatives to epitaxial semiconductor growth. Fixed monitors represent the mature revenue base, with nuclear power plants running 10-15 year replacement cycles that sustain predictable aftermarket demand.
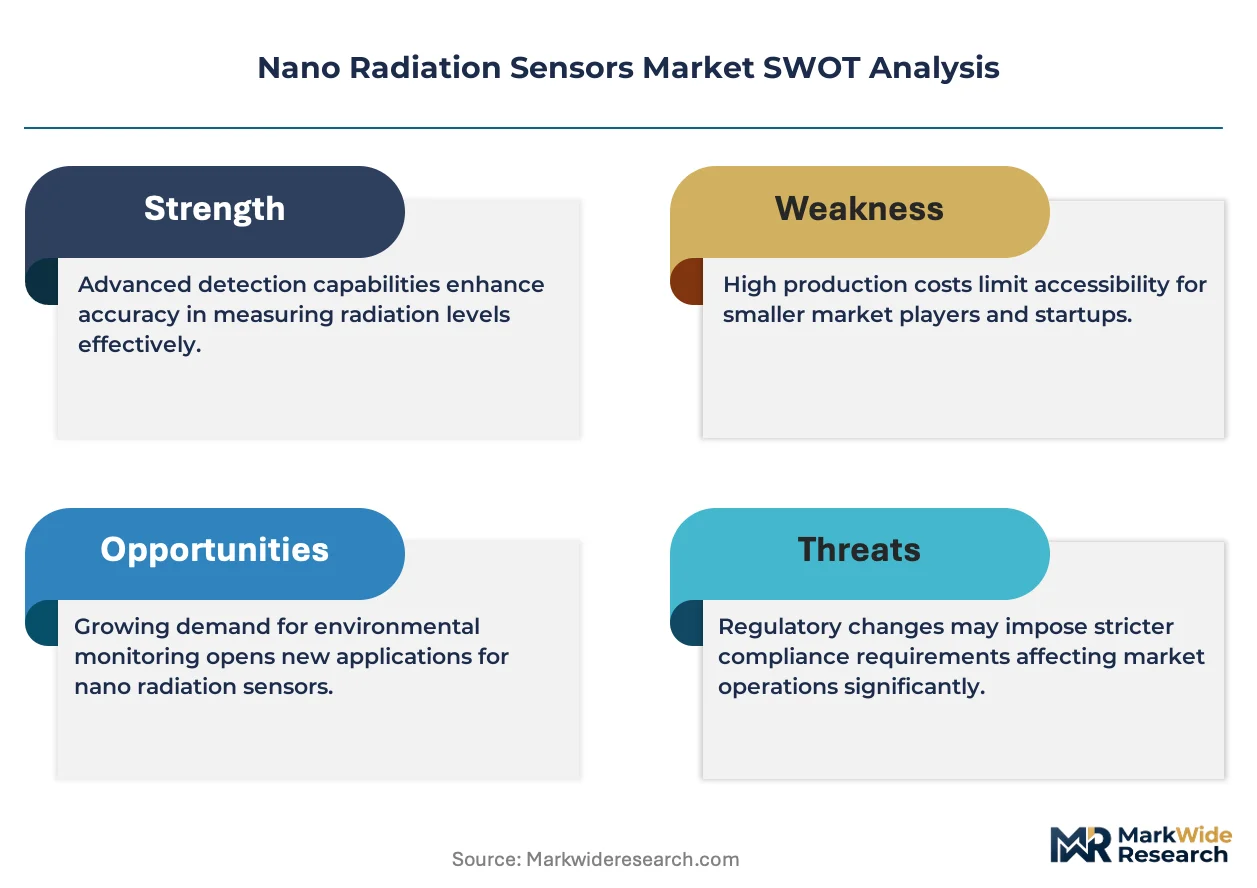
The FDA enforces device performance standards under 21 CFR 1020.32 for diagnostic x-ray systems, while the EPA's RadNet program mandates environmental monitoring specifications that shape sensor sensitivity requirements for federal contractors. ISO 4037 and IEC 60580 provide international calibration protocols that manufacturers must satisfy for cross-border hospital sales. Stakeholders must weigh quantum dot maturity against silicon detector reliability when allocating R&D budgets across next-generation product platforms.
Market Dynamics
Solid-state nano sensors are compressing replacement cycles across medical imaging and environmental monitoring as hospitals abandon gas-filled ionization chambers for semiconductor-based alternatives with superior energy resolution.
Growth Catalysts
- CT/PET Calibration Mandates:Medical imaging departments at university hospitals are expanding procurement of CZT-based nano sensors to meet ISO 4037 calibration protocols for dose verification workflows.
- EPA RadNet Specifications:Federal environmental monitoring contractors must satisfy the EPA's sensitivity requirements for isotope identification, pulling quantum dot detectors into fixed monitoring networks.
- German Research Infrastructure:Helmholtz Association laboratories are driving early adoption of room-temperature spectroscopy platforms for materials science applications.
Market Restraints
- Cryogenic Cooling Elimination:CZT material costs remain elevated despite eliminating liquid nitrogen infrastructure, constraining penetration in price-sensitive municipal monitoring programs.
- Epitaxial Wafer Supply Concentration:Silicon PIN substrate fabrication concentrates in East Asian foundries, exposing European and North American detector assemblers to single-source vulnerability.
- FDA 21 CFR 1020.32 Certification Friction:Diagnostic x-ray system integration requires extended validation timelines that delay hospital deployment by 18-24 months.
Strategic Opportunities
- Emergency Response Portables:Field-deployable spectroscopy units command premium positioning in contamination mapping scenarios where rapid isotope identification determines evacuation scope.
- Solution-Processed Quantum Dots:Research institutions are exploring printable detector films that bypass molecular beam epitaxy, opening capacity-constrained supply chains to new entrants.
- Nuclear Plant Aftermarket Cycles:Fixed monitor replacement schedules running 10-15 years create predictable revenue streams for sensor manufacturers with installed base service contracts.
Industry Challenges
- Scintillation Crystal Integration Complexity:Matching nano sensor electrical output to legacy photomultiplier tube electronics requires custom signal conditioning that extends system commissioning.
- IEC 60580 Calibration Specialist Scarcity:Cross-border hospital sales demand certified technicians capable of executing international protocols, creating bottlenecks in field service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Radiation Sensors Market |
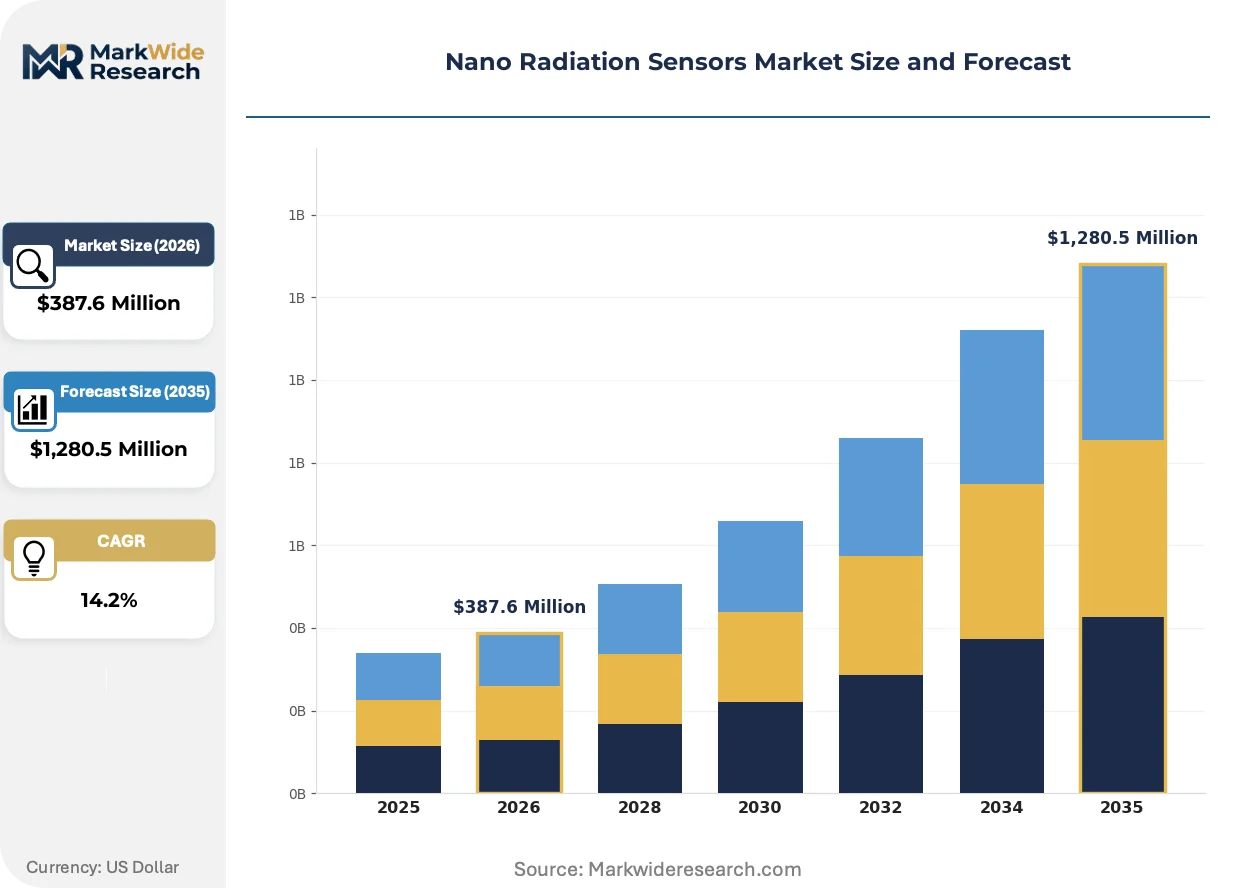
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Monitors, Personal Dosimeters, Spectrometers Technology: Silicon Detectors, Scintillation Detectors, Geiger-Müller Counters, Quantum Dots Application: Medical Imaging, Environmental Monitoring, Nuclear Power, Homeland Security End User: Research Institutions, Hospitals, Industrial Facilities, Government Agencies |
| Companies Covered | Thermo Fisher Scientific Inc., Mirion Technologies Inc., Hamamatsu Photonics K.K., Analog Devices Inc., Baker Hughes Company, First Sensor AG, Fluke Corporation, Kromek Group plc, Canon Electron Tubes & Devices Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Radiation Sensors Market Shifts & Advancements
Semiconductor process migration and regulatory dose-tracking mandates are compressing technology generations while fragmenting procurement authority across hospital radiology departments and centralized health system supply chains.
Quantum dot thin-film deposition is unifying energy resolution performance with solution-processed manufacturing scalability. Research consortia in Germany and Japan are piloting printable detector arrays for wearable dosimetry applications. This convergence is unifying laboratory-grade spectroscopy with mass-production economics previously reserved for silicon photodiodes.
The FDA's renewed enforcement under the Mammography Quality Standards Act is tightening device certification requirements for diagnostic x-ray systems. Manufacturers must now document traceable dose calibration chains from sensor wafer to installed monitor. Hospital procurement teams are responding by consolidating vendor qualification lists to pre-certified suppliers with established 21 CFR compliance histories.
Radiology departments are assuming direct control over sensor specification rather than deferring to centralized biomedical engineering. This decentralization is fragmenting purchasing authority and compressing decision timelines as clinical specialists demand vendor-specific performance guarantees. Germany's university hospital networks exhibit this pattern most acutely, with individual imaging directors negotiating directly with CZT detector specialists.
Nano Radiation Sensors Market Segmentation
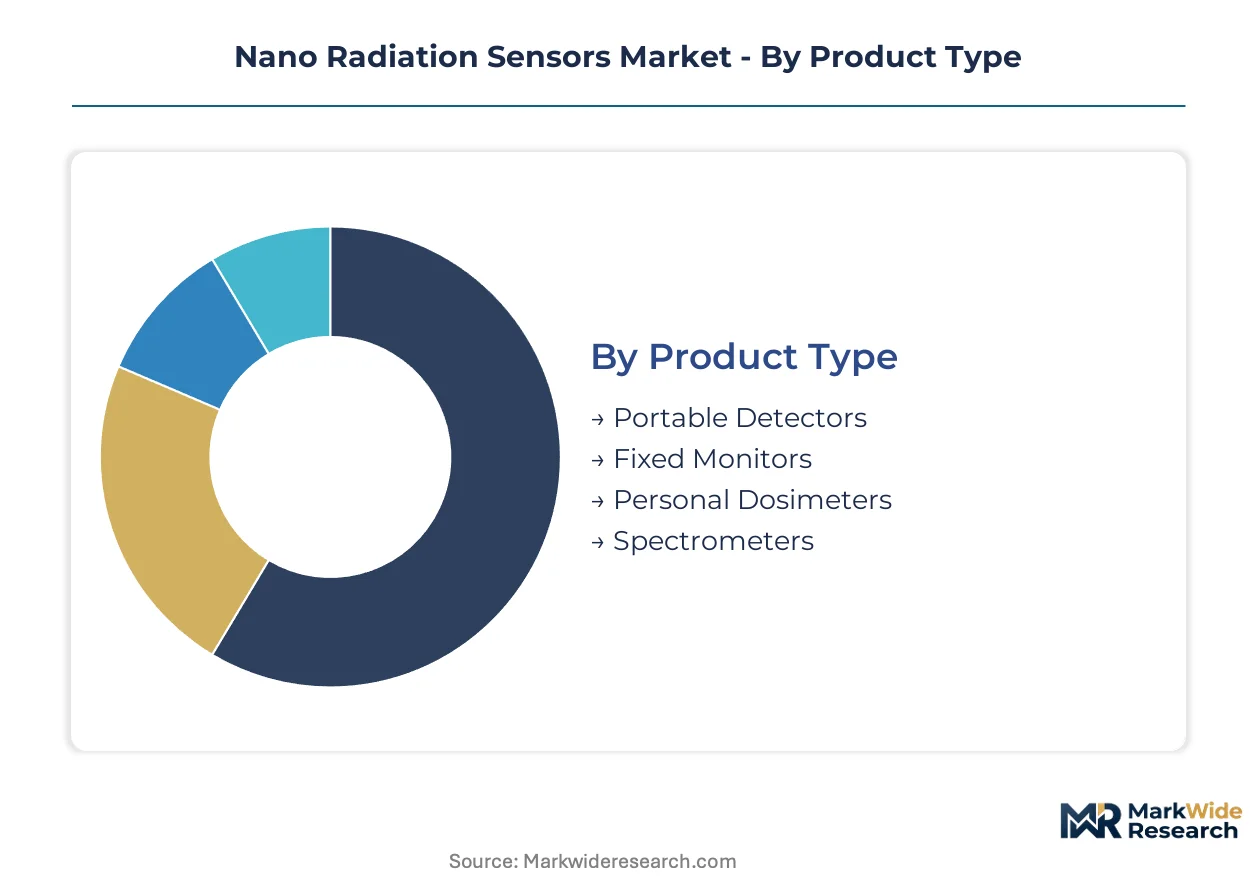
Segmentation in nano radiation sensors reveals distinct procurement patterns between standalone field instruments and embedded subsystem components. Hospitals favor integrated solid-state modules for CT calibration workflows, while environmental contractors deploy complete portable units for EPA RadNet compliance.
Product Type:
Integration depth separates self-contained instruments from subsystem modules destined for larger assemblies. Standalone units carry full signal conditioning and user interfaces; embedded variants demand external power and data acquisition infrastructure.
- Portable Detectors:Battery-powered units with integrated CZT or silicon PIN sensors, onboard multichannel analyzers, and wireless data transmission. Emergency response teams at Germany's federal radiation protection office deploy these for rapid contamination mapping following nuclear incidents.
- Fixed Monitors:Permanently installed sensors with hardened enclosures, continuous power supplies, and networked telemetry. Nuclear power plants in France and Sweden run these through 10-15 year replacement cycles that sustain predictable aftermarket service contracts.
- Personal Dosimeters:Wearable devices with solid-state sensors and cumulative dose logging. Research technicians at Helmholtz Association laboratories favor lightweight variants for hands-on materials science work.
- Spectrometers:High-resolution instruments with cryogenically cooled or room-temperature detector arrays. Environmental monitoring stations require these for EPA-mandated isotope identification in air and water sampling.
Volume placements concentrate in Fixed Monitors; the faster expansion belongs to Portable Detectors.
Technology:
Cost tier stratification separates mature silicon platforms from emerging quantum dot alternatives with unproven field reliability. Premium positioning attaches to materials enabling room-temperature spectroscopy without cryogenic infrastructure.
- Silicon Detectors:PIN diode structures fabricated on epitaxial wafers with established foundry supply chains. Hamamatsu Photonics K.K. anchors production through captive photodiode manufacturing feeding scintillation detector assemblies.
- Scintillation Detectors:Crystal-sensor hybrids coupling sodium iodide or lanthanum bromide to solid-state photodetectors. Medical imaging departments demand these for CT calibration workflows requiring high count-rate tolerance.
- Geiger-Müller Counters:Gas-filled tubes with limited energy resolution but extreme cost efficiency. Municipal monitoring programs in price-sensitive markets retain these for threshold alarm functions.
- Quantum Dots:Solution-processed semiconductor nanocrystals with tunable bandgaps and printable deposition. Japan's METI-funded consortia pilot these for wearable dosimetry applications.
Silicon Detectors dominate current procurement volumes; Quantum Dots are climbing the fastest despite manufacturing immaturity.
Application:
Customer type fragmentation splits procurement authority between centralized health system supply chains and decentralized radiology departments with direct vendor relationships.
- Medical Imaging:Dose verification and calibration workflows for CT, PET, and mammography systems. FDA enforcement under 21 CFR 1020.32 tightens certification requirements for diagnostic x-ray sensor integration.
- Environmental Monitoring:Fixed networks and mobile surveys for isotope identification in air, water, and soil matrices. EPA RadNet specifications pull quantum dot detectors into federal contractor deployments.
- Nuclear Power:Reactor perimeter monitoring, fuel handling oversight, and waste stream characterization. Plant operators prioritize CZT-based room-temperature spectroscopy to eliminate liquid nitrogen logistics.
- Homeland Security:Border screening, event security, and emergency response for radiological dispersal devices. Field-deployable units command premium positioning where rapid isotope identification determines evacuation scope.
Medical Imaging captures the largest revenue share; Homeland Security applications are expanding most quickly.
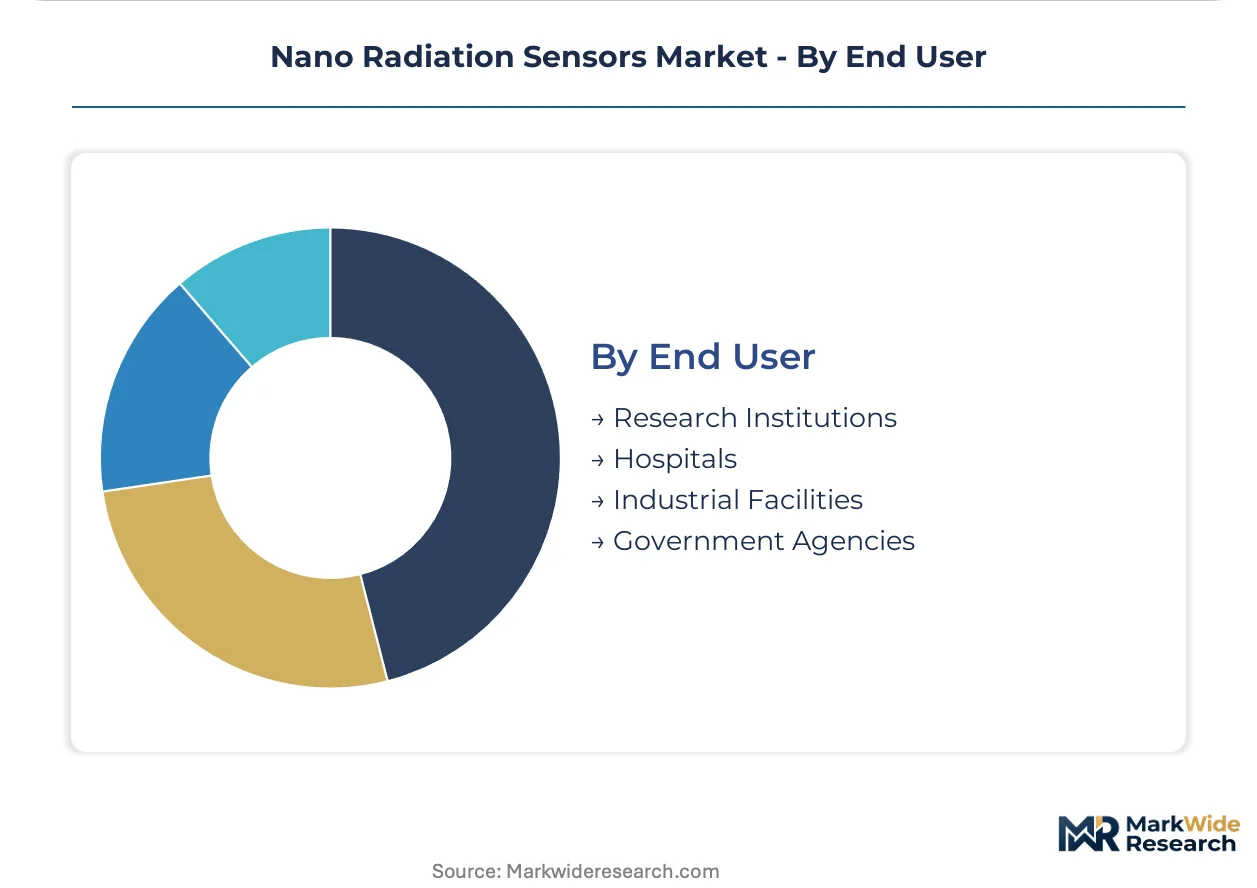
End User:
Maturity differentiation separates research-led early adoption from compliance-driven institutional procurement with extended validation timelines.
- Research Institutions:Materials science, physics, and radiochemistry laboratories exploring novel detector architectures. Helmholtz Association facilities in Germany drive early adoption of printable quantum dot arrays.
- Hospitals:Radiology and nuclear medicine departments with ISO 4037 calibration mandates. University hospital networks in Germany exhibit acute decentralization, with imaging directors negotiating directly with CZT specialists.
- Industrial Facilities:Non-destructive testing, process control, and occupational safety monitoring. Semiconductor fabrication plants deploy personal dosimeters for ionizing radiation exposure tracking.
- Government Agencies:Federal environmental monitoring, nuclear safeguards, and emergency response coordination. EPA contractors must satisfy RadNet sensitivity specifications for isotope identification.
Volume concentrates in Hospitals; Research Institutions show the steepest expansion trajectory for emerging quantum dot platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian epitaxial wafer foundries, while consumption pulls toward German research infrastructure and American hospital procurement channels. This geographic split shapes regulatory compliance requirements and supply chain vulnerability profiles across the analysis window.
United States
Federal environmental contractors drive demand through EPA RadNet deployment specifications for isotope identification networks. FDA enforcement under 21 CFR 1020.32 tightens certification timelines for diagnostic x-ray sensor integration. Boston's medical technology corridor hosts validation laboratories serving hospital procurement teams with decentralized radiology authority.
Germany
Helmholtz Association laboratories anchor European early adoption of room-temperature spectroscopy platforms for materials science applications. The country's national radiation protection regulator mandates stringent calibration protocols under ISO 4037 for hospital dose verification workflows. Munich and Dresden university hospital networks negotiate directly with CZT detector specialists, bypassing centralized supply chains.
Japan
METI-funded research consortia pilot printable quantum dot arrays for wearable dosimetry applications. The country's pharmaceutical and medical device agency maintains performance standards for diagnostic equipment integration. Hamamatsu anchors photodiode manufacturing that feeds scintillation detector assemblies serving domestic and export markets.
China
Domestic semiconductor fabrication plants deploy personal dosimeters for ionizing radiation exposure tracking in cleanroom environments. The Ministry of Industry and Information Technology oversees standards for environmental monitoring equipment deployed in nuclear power expansion zones. Shanghai and Beijing research institutes explore solution-processed alternatives to epitaxial semiconductor growth.
France
Électricité de France operates nuclear power plants running 10-15 year fixed monitor replacement cycles that sustain predictable aftermarket service demand. The national agency for food, environmental and occupational health safety enforces monitoring specifications for environmental surveillance networks. The Grenoble instrumentation cluster hosts detector assembly operations serving European hospital and industrial accounts.
Nano Radiation Sensors Market Competitive Landscape
Top-tier vendors anchor hospital procurement channels and federal contractor supply chains, while mid-scale specialists concentrate on material science differentiation and captive manufacturing control. The competitive field organizes around three strategic archetypes: diversified life sciences conglomerates with distribution scale, photonics specialists with vertical manufacturing integration, and compound semiconductor material scientists with cryogen-free spectroscopy platforms. Dominant competitive moves include strategic partnerships for regulatory certification acceleration and capacity expansion in epitaxial wafer substrate fabrication.
Among diversified instrumentation providers, Thermo Fisher Scientific Inc. occupies a position representing life sciences distribution scale, while Mirion Technologies Inc. exemplifies nuclear measurement specialization. Hamamatsu Photonics K.K. anchors the photonics manufacturing tier with captive photodiode production feeding detector assemblies. Kromek Group plc sits within the compound semiconductor archetype, representing material science differentiation through cadmium zinc telluride platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Mirion Technologies Inc. |
| Hamamatsu Photonics K.K. |
| Analog Devices Inc. |
| Baker Hughes Company |
| First Sensor AG |
| Fluke Corporation |
| Kromek Group plc |
| Canon Electron Tubes & Devices Co., Ltd. |
| Others |
Supply & Pricing Matrix
Epitaxial wafer fabrication specialists concentrated in East Asian foundries create labor-cost differentials that widen pricing-tier spreads between premium CZT-based detectors and economy silicon PIN alternatives. German research institutions absorb premium positioning for room-temperature spectroscopy platforms, while municipal environmental programs in price-sensitive markets default to Geiger-Müller threshold alarms.
Pricing Analysis
Margin tightening in portable emergency-response units reflects cryogenic-cooling elimination premiums and field-deployable certification costs. Three-tier pricing structure across premium CZT spectroscopy, standard silicon PIN modules, and economy scintillation hybrids stratifies by energy resolution performance and ISO 4037 calibration documentation. Price differentiation hinges on FDA 21 CFR 1020.32 pre-certification status, with hospital procurement teams least sensitive to unit cost and municipal radiation offices most constrained by budget ceilings.
Supply Chain Analysis
Refurbishment flows for nuclear plant fixed monitors—running 10-15 year replacement cycles—sustain aftermarket service revenue streams that buffer primary equipment sales volatility. CZT crystal growth concentrates in Japan and the United States, while silicon epitaxial substrate fabrication draws from Taiwan and South Korea. Single-source vulnerability in high-purity tellurium feedstock creates tariff exposure for compound semiconductor detector assemblers. Distribution runs through life sciences conglomerates with hospital GPO contracts and direct federal contractor channels for EPA RadNet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase as solid-state nano sensors displace legacy gas-filled ionization chambers across medical imaging calibration workflows. Quantum dot thin-film deposition represents the most disruptive substitution threat to established epitaxial semiconductor platforms.
For Market Incumbents: Acquire captive epitaxial wafer capacity to secure silicon PIN substrate supply against East Asian foundry concentration risk. Deepen backward integration into CZT crystal growth to defend margin position against emerging quantum dot entrants. Prioritize FDA pre-certification investment for diagnostic x-ray system integration to compress 18-24 month validation timelines.
For New Entrants and Emerging Players: Direct-to-research-institution digital channels bypass entrenched hospital GPO procurement blocks. Target German Helmholtz Association laboratories with solution-processed quantum dot prototypes for materials science applications. Emphasize printable detector film scalability as the go-to-market wedge against molecular beam epitaxy incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with compound semiconductor material scientists given CZT room-temperature spectroscopy adoption acceleration. Long-term viability centers on 5-10 year nuclear plant fixed monitor aftermarket service contracts with predictable replacement scheduling. Monitor EPA RadNet specification updates for quantum dot detector eligibility as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CZT Crystal Growth | Captive tellurium refining secures supply against commodity volatility for spectroscopy platforms. |
| FDA 21 CFR 1020.32 Pre-Certification Investment | Accelerated hospital deployment timelines compress competitive qualification windows for diagnostic x-ray integration. |
| Research Institution Direct Channel Development | Bypasses consolidated health system supply chains fragmenting radiology procurement authority. |
| Quantum Dot Printable Deposition Scale-Up | Solution-processed manufacturing opens capacity-constrained epitaxial supply chains to new entrants. |
| Nuclear Plant Service Contract Expansion | 10-15 year fixed monitor replacement cycles generate predictable aftermarket revenue streams. |
Research Methodology
Independent corroboration across hospital biomedical engineering directors, EPA environmental monitoring contractors, CZT detector specialists, and nuclear plant radiation safety officers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 510(k) filings, ISO 4037 calibration protocol documentation, hospital procurement databases, and nuclear regulatory commission inspection reports. Bottom-up unit economics and top-down market sizing triangulation anchor volume and value estimates.
Rate-of-change decomposition separates replacement-cycle dynamics from net-new installation demand across portable, fixed, and wearable product categories. Segmentation modeling incorporates technology type, application vertical, end-user institution, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed base penetration curves and replacement cycle scheduling. Industry-specific inputs include EPA RadNet sensitivity specification evolution and FDA enforcement intensity under the Mammography Quality Standards Act.
The model holds under stable regulatory enforcement and intact East Asian epitaxial supply chains; deviation in tariff regimes or tellurium export restrictions would shift volume trajectories. Practitioners should monitor quantum dot field reliability data and German research infrastructure funding cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Speed Sensor Market