
 RET Controller Market | 2026-2036
RET Controller Market Size, Share, and Industry Trends Forecast 2026-2036
RET Controller Market Analytics
A shortage of RF engineering specialists is unwinding deployment timelines for advanced antenna systems. CommScope leverages its vertically integrated manufacturing footprint to sustain controller supply for North American tower upgrades. Huawei anchors procurement decisions across emerging markets through bundled radio and RET controller offerings. Ericsson differentiates via embedded AI-driven tilt algorithms that reduce manual site visits.
A RET controller electrically adjusts the vertical tilt of a base station antenna without physical climbing, typically operating over AISG protocols with motor-driven phase shifters inside the antenna housing. The device enables network operators to optimize cell coverage patterns and manage interference in real time from remote operations centers. Silicon controllers dominate volume shipments due to cost efficiency at scale, while smart controllers capture expanding margin pools as carriers prioritize autonomous network optimization. Digital technology leads new installations, though hybrid architectures persist in retrofit scenarios where legacy analog infrastructure remains in service.
The US FCC governs RF emissions and equipment authorization, while the EU's Radio Equipment Directive mandates interoperability and electromagnetic compatibility for network hardware sold across member states. India's TRAI spectrum allocation rules and BIS certification requirements shape market access timelines for imported RET controller modules. Stakeholders must weigh the pace of Open RAN standardization against proprietary integrated solutions when allocating R&D budgets and vendor qualification resources.
Market Dynamics
Telecommunications infrastructure buildouts are concentrating procurement power among tower companies and mobile network operators, compressing vendor margins while demanding higher controller intelligence for autonomous network management.
Growth Catalysts
- EU F-Gas Regulation:Mandates for energy-efficient network hardware are accelerating replacement cycles for legacy RET controller installations across European Union member states.
- India PLI Scheme:Production-linked incentives for telecom manufacturing are drawing supply chain investment and establishing local controller assembly capacity in Gujarat and Tamil Nadu.
- AISG Protocol Evolution:Enhanced antenna interface standards enable seamless interoperability between multi-vendor radio heads and intelligent tilt controllers, reducing operator integration costs.
Market Restraints
- Rare Earth Magnet Supply:Motor-driven phase shifters depend on neodymium-iron-boron magnets concentrated in Chinese processing facilities, exposing controller manufacturers to input cost volatility and export restriction risk.
- RF Engineering Talent Scarcity:Specialized workforce shortages in antenna optimization and remote electrical tilt calibration are extending deployment timelines for advanced antenna systems.
- Legacy Analog Infrastructure:Hybrid controller architectures persist in retrofit scenarios where sunk costs in existing tower equipment delay full digital migration.
Strategic Opportunities
- US Inflation Reduction Act:Tax credits and procurement incentives for energy-efficient telecommunications infrastructure are creating preferential purchasing pathways for smart controller vendors.
- Open RAN Standardization:Disaggregated radio access network architectures are converging with intelligent controller platforms to enable multi-vendor interoperability and reduce operator lock-in.
- Autonomous Network Optimization:Embedded AI-driven tilt algorithms are creating new service revenue streams through predictive coverage management and interference mitigation.
Industry Challenges
- BIS Certification Timelines:India's Bureau of Indian Standards testing protocols for imported RET controller modules are creating extended market access delays for foreign suppliers.
- Multi-Protocol Integration:Controller vendors must maintain simultaneous compatibility with legacy AISG 1.1, AISG 2.0, and emerging 3GPP specifications, fragmenting firmware development resources.
- Site Visit Reduction Economics:Operators are demanding tilt adjustment precision that eliminates physical tower climbs, pressuring motor accuracy and remote diagnostic reliability thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RET Controller Market |
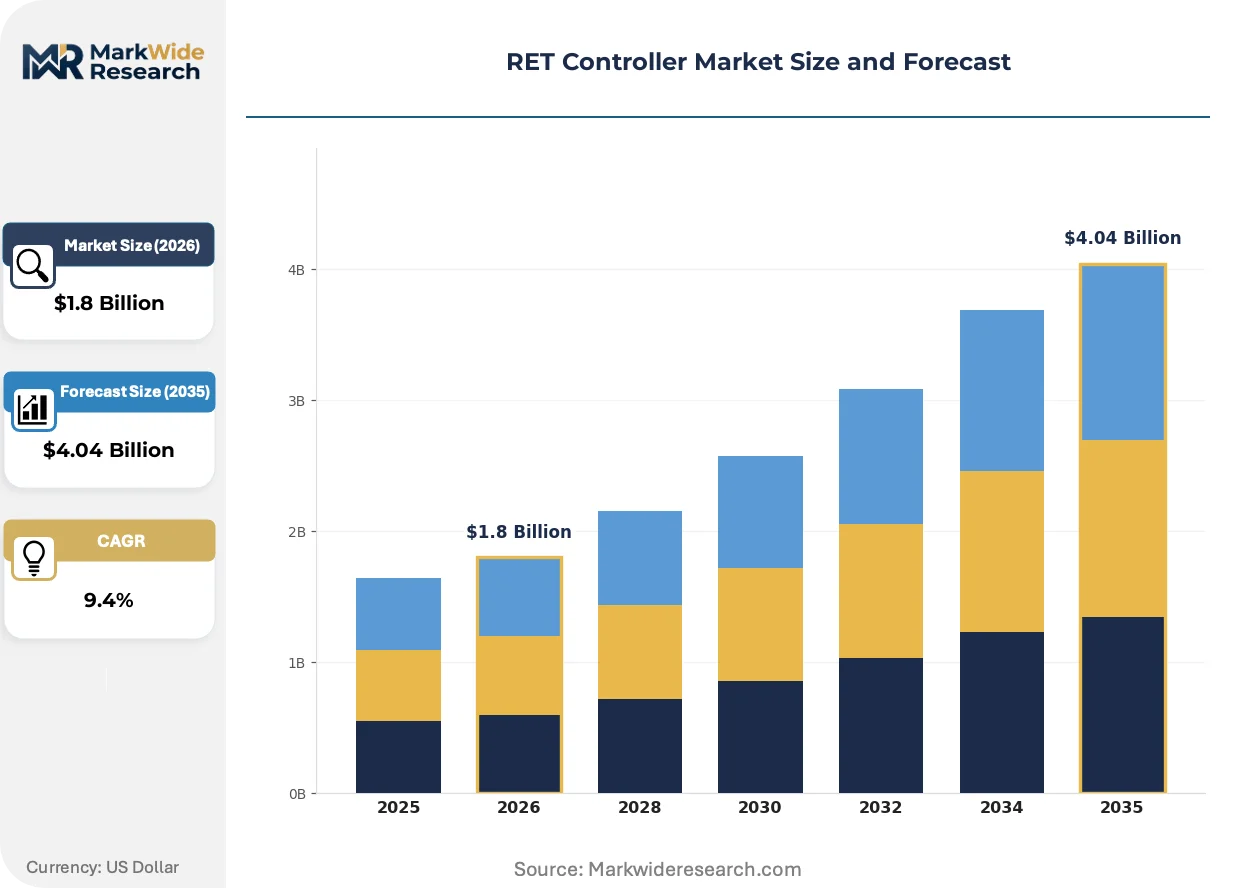
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Controllers, High-Speed Controllers, Smart Controllers, Programmable Controllers End User: Telecommunications, Automotive, Industrial Automation, Consumer Electronics Technology: Analog Technology, Digital Technology, Hybrid Technology, Mixed Signal Technology Deployment: On-Premise, Cloud-Based, Edge-Based, Integrated Solutions |
| Companies Covered | CommScope, Amphenol Antenna Solutions, Kathrein, TESSCO Technologies, Huawei, Ericsson, RFS, ACE Technologies, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RET Controller Market Evolving Landscape
Digital controller architectures are displacing analog alternatives across greenfield deployments, while embedded intelligence and autonomous optimization capabilities are redefining value capture in the supply chain.
Silicon-based motor controllers are supplanting electromechanical relay systems in volume shipments. Tower operators in North America and Western Europe are adopting these platforms for 5G mid-band deployments. The transition is compressing controller bill-of-materials costs while enabling firmware-over-the-air updates that extend field service life.
Europe's F-Gas Regulation is restricting fluorinated greenhouse gas use in cooling systems co-located with antenna equipment. This regulatory pressure is forcing controller manufacturers to certify operating temperature ranges that eliminate supplemental climate control. Vendors serving EU mobile network operators are redesigning thermal management into sealed outdoor housings.
Carrier procurement teams are consolidating vendor qualification lists around integrated radio-controller bundles. Traditional standalone controller distributors are losing shelf space to original equipment manufacturers offering tilt management as a subscription feature. This concentration is most visible in emerging markets where Huawei and Ericsson anchor procurement decisions through bundled offerings.
RET Controller Market Segmentation
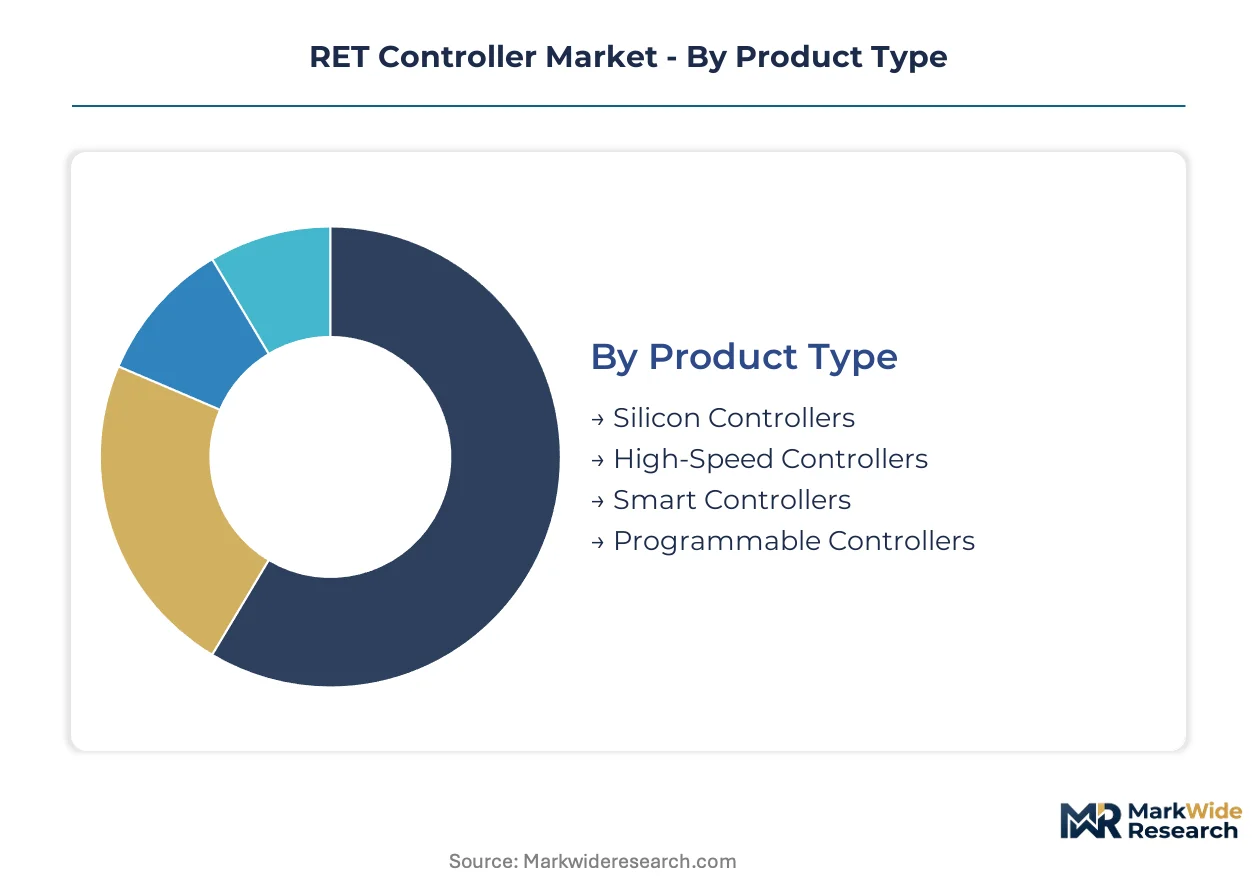
RET controller segmentation reveals divergent growth trajectories across product architectures and deployment models. Procurement patterns vary sharply between telecommunications infrastructure buildouts and industrial automation retrofits, with regulatory compliance requirements further stratifying vendor selection criteria.
Product Type:
Silicon controllers dominate domestic manufacturing footprints in India and Vietnam, while smart controllers drive export-led revenue from European and North American design houses.
- Silicon Controllers:Motor-driven phase shifters built on CMOS architectures deliver cost efficiency at volume scale. Demand concentrates in Indian tower deployments under the PLI scheme, where local assembly requirements favor silicon-based bill-of-materials optimized for Gujarat and Tamil Nadu production lines.
- Smart Controllers:Embedded AI-driven tilt algorithms enable autonomous coverage optimization from remote operations centers. European mobile network operators under the F-Gas Regulation are prioritizing these platforms for energy-efficient network hardware procurement, creating premium pricing corridors for vendors with certified thermal management.
- High-Speed Controllers:Sub-millisecond tilt response specifications serve 5G mid-band densification requirements in South Korean and Japanese metropolitan clusters.
- Programmable Controllers:Firmware-over-the-air update capabilities extend field service life for North American tower company portfolios.
Silicon controllers command the established base. The steepest expansion runs through smart controllers.
End User:
Cost tier stratification separates mission-critical telecommunications infrastructure from price-sensitive consumer electronics applications.
- Telecommunications:Base station antenna optimization represents the dominant revenue pool, with AISG protocol compliance mandatory for multi-vendor interoperability. Tower companies and mobile network operators in India, Germany, and the United States are consolidating procurement around integrated radio-controller bundles.
- Automotive:V2X antenna positioning systems for connected vehicle infrastructure are emerging as a specification-driven segment with extended qualification timelines.
- Industrial Automation:Remote monitoring of distributed antenna systems in manufacturing facilities favors hybrid controller architectures.
- Consumer Electronics:Minimal viable tilt functionality serves residential small cell and signal booster applications at compressed margins.
Telecommunications anchors volume procurement. Automotive applications are climbing the fastest as V2X deployment accelerates.
Technology:
Technology maturity curves diverge between legacy analog installed base and digital greenfield installations.
- Digital Technology:Precise motor control via pulse-width modulation enables firmware-defined tilt algorithms. New installations across European Union member states favor digital architectures under Radio Equipment Directive interoperability mandates.
- Hybrid Technology:Bridging interfaces for legacy AISG 1.1 infrastructure persist in North American retrofit scenarios where sunk costs delay full digital migration.
- Analog Technology:Electromechanical relay systems retain residual demand in emerging market tower upgrades with constrained capital budgets.
- Mixed Signal Technology:Combined analog sensing with digital processing serves specialized industrial automation deployments requiring deterministic tilt response.
Hybrid technology commands the established base. Digital technology is gaining share fastest as greenfield 5G deployments accelerate.
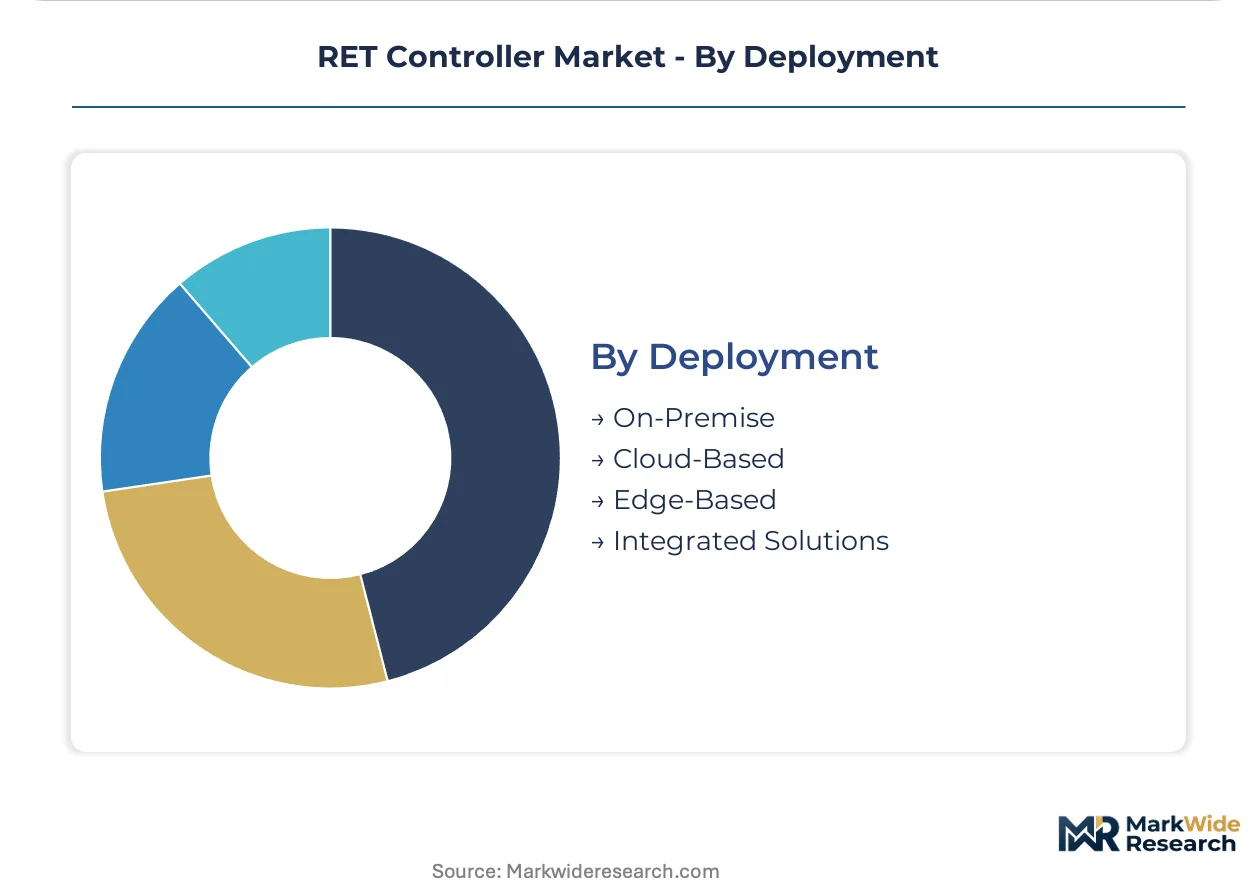
Deployment:
Customer type segmentation separates capital-intensive integrated solutions from subscription-oriented cloud-based service models.
- Integrated Solutions:Bundled radio and controller offerings from original equipment manufacturers dominate emerging market procurement. Huawei and Ericsson anchor these decisions through multi-year managed service contracts.
- Edge-Based:Distributed tilt processing at tower baseband units reduces latency for real-time interference mitigation in dense urban clusters.
- Cloud-Based:Centralized optimization platforms enable multi-site coverage coordination from network operations centers, favored by European tower companies with geographically dispersed portfolios.
- On-Premise:Standalone controller installations persist in regulated environments requiring air-gapped operational technology networks.
Integrated solutions command the established base. Cloud-based deployment is expanding most quickly as autonomous network optimization matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs RF emissions and equipment authorization in the United States, anchoring the regulatory framework that shapes procurement patterns across the dominant telecommunications infrastructure market. Tower operators and mobile network operators concentrate investment in regions with streamlined permitting and established supplier relationships.
United States
Mid-band 5G densification drives controller demand across metropolitan clusters. The Inflation Reduction Act channels tax credits toward energy-efficient network hardware procurement. Tower companies in Texas and the Southeast are consolidating vendor qualification lists around integrated radio-controller bundles.
Germany
Deutsche Telekom and Vodafone anchor European demand for intelligent tilt management systems. The EU F-Gas Regulation mandates thermal management certifications that eliminate supplemental climate control in outdoor housings. Industrial clusters in Bavaria and Baden-Württemberg host assembly operations serving Central European mobile network operators.
India
Jio and Bharti Airtel are accelerating base station deployments under aggressive 5G rollout timelines. TRAI spectrum allocation rules and BIS certification requirements shape market access for imported controller modules. Manufacturing lines in Gujarat and Tamil Nadu are scaling local assembly capacity under the PLI scheme for telecom equipment.
South Korea
SK Telecom and KT Corporation prioritize sub-millisecond tilt response specifications for dense urban 5G networks. The Ministry of Science and ICT coordinates spectrum policy with infrastructure deployment targets. Seoul metropolitan clusters represent concentrated demand for high-speed controller architectures in mmWave small cell installations.
Japan
NTT Docomo and KDDI integrate autonomous tilt algorithms into network operations center workflows. METI industrial policy supports domestic manufacturing of telecommunications infrastructure components. The Kanto region around Tokyo hosts R&D facilities developing next-generation antenna interface standards.
RET Controller Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Original equipment manufacturers bundle radio and controller offerings through multi-year managed service contracts, compressing margins for standalone controller distributors. Strategic archetypes include vertically integrated infrastructure giants, specialist antenna subsystem providers, and component-scale fabricators. Competitive moves concentrate on backward integration into motor and magnet supply chains, plus firmware-over-the-air capability development to extend field service life.
Within the integrated infrastructure tier, CommScope leverages its North American manufacturing footprint to sustain controller supply for tower upgrade cycles, while Huawei anchors procurement decisions across emerging markets through bundled radio and RET controller offerings. Ericsson occupies a position exemplifying the AI-driven differentiation archetype, with embedded tilt algorithms that reduce manual site visits. These three companies represent distinct strategic vectors: geographic supply security, emerging market bundling power, and autonomous optimization technology.
| Leading Market Players |
|---|
| CommScope |
| Amphenol Antenna Solutions |
| Kathrein |
| TESSCO Technologies |
| Huawei |
| Ericsson |
| RFS |
| ACE Technologies |
| Molex |
| Others |
Value Network & Pricing Analysis
Volume scale at Gujarat and Tamil Nadu assembly facilities compresses unit economics for silicon controllers while establishing price floors that distant competitors struggle to match. Indian PLI scheme beneficiaries leverage captive magnet sourcing and local labor arbitrage to undercut import-dependent rivals serving European and North American tower operators.
Pricing Analysis
Geographic price spreads of 40-60% separate Indian-manufactured silicon controllers from European smart controller exports bearing F-Gas Regulation thermal certification costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by embedded intelligence and AISG protocol generation, with smart controllers capturing service-subscription premiums. Price erosion runs through standard-tier silicon units as Chinese motor suppliers expand capacity. Tower companies in India exhibit highest price sensitivity, while German mobile network operators prioritize energy-efficiency certification over unit cost.
Supply Chain Analysis
Controller inventory cycles stretch 8-12 weeks for neodymium-iron-boron magnets concentrated in Chinese processing facilities, exposing manufacturers to export restriction risk. Motor-driven phase shifter assembly draws from China, Vietnam, and India, with magnet sourcing tethered to Sino-Japanese rare earth refining partnerships. Single-source vulnerability concentrates in magnet supply, compounded by TRAI-mandated BIS certification delays for imported modules. Distribution runs through original equipment manufacturer direct contracts and tower company procurement consortia, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation between integrated radio-controller bundles and standalone intelligent platforms creates niche opportunities for specialists targeting autonomous optimization and Open RAN interoperability. The disaggregation of radio access network architectures splits procurement decisions away from incumbent bundling power.
For Market Incumbents: Secure backward integration into motor and magnet supply chains to neutralize Chinese rare earth processing bottlenecks. Expand firmware-over-the-air capability development to extend field service life and justify subscription pricing. Counter Ericsson's AI-driven tilt algorithms through embedded intelligence partnerships or acquisition of specialist software houses. For New Entrants and Emerging Players: Lead with Open RAN-native controller architectures targeting European tower companies seeking multi-vendor interoperability and reduced operator lock-in. Exploit BIS certification backlogs delaying foreign supplier market access in India by establishing local assembly partnerships under PLI scheme incentives. Position around cloud-based deployment models for geographically dispersed portfolio optimization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with autonomous optimization IP and established AISG 3GPP compliance roadmaps over commodity silicon controller fabricators. Five-to-ten year viability hinges on embedded AI differentiation and thermal management certification for F-Gas Regulation compliance. Monitor Open RAN standardization velocity as inflection indicator for bundling power erosion versus sustained integrated solution dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium-iron-boron sourcing insulates margins from Chinese export volatility. |
| Firmware-over-the-Air Platform Launch | Remote update capabilities extend controller service life and enable subscription revenue streams. |
| Open RAN Certification Investment | Multi-vendor interoperability compliance unlocks European tower company procurement lists. |
| PLI Scheme Local Assembly Partnership | Gujarat and Tamil Nadu manufacturing access accelerates Indian market entry under BIS rules. |
| Embedded AI Tilt Algorithm Development | Autonomous coverage optimization commands premium pricing from Deutsche Telekom and Vodafone. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on F-Gas Regulation implementation and PLI scheme operational details. Network planning executives at European mobile operators, procurement directors at Indian tower companies, RF engineering leads at North American infrastructure deployers, and antenna subsystem specialists at Asian manufacturing facilities contributed operational data. FCC equipment authorization databases, EU Radio Equipment Directive compliance registries, TRAI spectrum allocation orders, and BIS certification timelines provided secondary validation. Bottom-up unit shipment estimates from controller assembly lines reconciled against top-down telecommunications infrastructure capex disclosures.
Sensitivity analysis around rare earth magnet price volatility and Open RAN standardization velocity frames the projection boundaries across the analysis window. Segmentation modeling spans product architecture, end-use application, technology generation, and deployment model, with geographic regulatory clusters as an additional dimension. CAGRs derive from fitted growth curves against historical infrastructure deployment cycles, incorporating 5G mid-band densification timelines and energy-efficiency procurement incentive trajectories as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding or accelerated F-Gas Regulation enforcement would require recalibration. Forecasts reflect documented assumptions on magnet supply continuity and AISG protocol evolution. Rare earth export restrictions, BIS certification timeline extensions, or Open RAN standardization delays represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Industrial Controllers Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Inertial Sensing Products Market