
 Vibration Sensor Market | 2026-2036
Vibration Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Vibration Sensor Market Analysis
Modular sensor-to-gateway bundling is hardening as the dominant procurement configuration for industrial buyers seeking plug-and-deploy condition monitoring. TE Connectivity leverages its interconnect portfolio to anchor bundled offerings across aerospace and heavy manufacturing accounts. SKF AB competes through vertical integration into bearing-integrated sensing systems that combine hardware with diagnostic software layers. Honeywell International Inc. differentiates by sustaining dual certification pathways for hazardous-environment and standard industrial deployments.
A vibration sensor is a transducer that converts mechanical oscillation into an electrical signal, typically operating across frequency ranges from 0.1 Hz to 20 kHz and generating output proportional to acceleration, velocity, or displacement for machine diagnostics and structural integrity assessment. Its primary industrial purpose centers on detecting bearing faults, imbalance, and misalignment before catastrophic equipment failure. MEMS technology leads unit volume due to silicon-batch scalability and shrinking form factors for edge-mounted applications, while piezoresistive architectures retain margin concentration in high-temperature and high-shock environments where MEMS reliability remains constrained. Wireless connectivity is expanding fastest among technology segments as battery-harvesting designs and mesh protocols reduce cabling costs in retrofit installations.
ISO 10816 mechanical vibration standards and OSHA machinery safety directives shape product certification requirements and limit market access for uncertified suppliers in regulated industrial environments. The EU Machinery Directive and CE marking enforcement in Europe further constrain sensor design, mandating electromagnetic compatibility and safety integrity levels that elevate engineering costs for non-compliant manufacturers. Stakeholders must monitor evolving wireless spectrum allocation decisions and cybersecurity labeling requirements that will determine which connectivity architectures secure preferred vendor status in next-generation procurement frameworks.
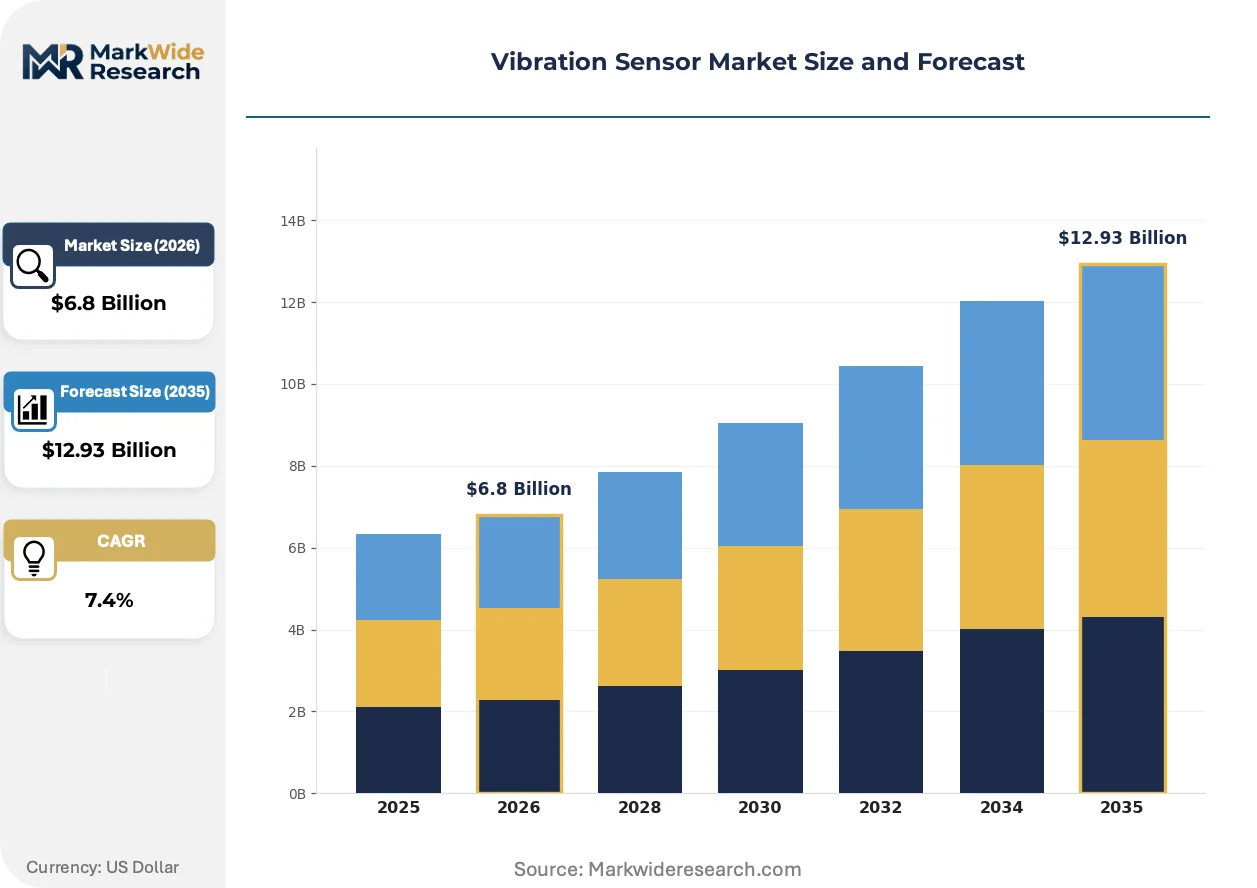
Market Dynamics
Wireless mesh networking is compressing installation timelines for predictive maintenance programs, forcing incumbent suppliers to re-architect hardware portfolios around battery-harvesting designs and edge-native analytics.
Growth Catalysts
- Industrial IoT mandates:Factory digitization programs across Germany's automotive sector are mandating real-time condition monitoring, pulling MEMS-based sensors into standard equipment specifications.
- OSHA machinery safety enforcement:US regulatory pressure on unplanned downtime incidents is accelerating sensor deployment in food processing and petrochemical facilities.
- Piezoelectric material advances:New high-temperature ceramic formulations are extending operational ranges beyond 400°C, opening geothermal and steelmaking applications previously closed to silicon-based alternatives.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium dependency on Chinese processing facilities creates input cost volatility for magnet-based velocity sensors.
- ISO 10816 certification timelines:Multi-month validation protocols for vibration severity grading delay product launches and freeze working capital.
- Optical encoder substitution:Non-contact displacement measurement is capturing precision alignment applications above 10 kHz where contact sensors face wear limitations.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods are attracting sensor assembly investments serving domestic textile and cement plant modernization.
- Edge-AI convergence:On-device vibration signature classification is enabling standalone diagnostic nodes that bypass cloud latency for critical rotating equipment.
- Aftermarket channel digitization:Direct-to-maintenance-crew e-commerce platforms are disintermediating traditional industrial distribution in North American MRO procurement.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers combining signal processing expertise with wireless protocol stack development is throttling product roadmap velocity.
- Legacy DCS integration friction:Proprietary 4-20 mA loops and vendor-locked control architectures resist seamless sensor-to-ERP data flow in brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibration Sensor Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Piezoresistive, Capacitive, Optical, MEMS End User: Manufacturing, Automotive, Aerospace, Healthcare Technology: Wireless, Wired, Cloud-Based, Analog Application: Condition Monitoring, Machine Health, Structural Health, Automotive Testing |
| Companies Covered | Analog Devices, Inc., TE Connectivity Ltd., Electro-Sensors, Inc., Emerson Electric Co., SKF AB, Grace Technologies, Honeywell International Inc., PCB Piezotronics, Inc., ALTHEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibration Sensor Market Emerging Trajectories
Three intersecting developments are restructuring how vibration data is captured, transmitted, and monetized across industrial asset classes. Each trend carries distinct implications for hardware design, certification pathways, and customer engagement models.
Energy-harvesting piezoelectric designs are electrifying retrofit deployment economics by eliminating battery replacement cycles in hard-to-access rotating equipment. Wind turbine operators in Denmark and offshore platforms in the North Sea are adopting self-powered nodes at scale. This architecture is compressing total cost-of-ownership calculations and displacing wired installations where cable routing exceeds hardware costs.
REACH substance restrictions on lead-based soldering and cadmium plating are forcing European suppliers to redesign connector assemblies and housing materials. The industrial consequence extends beyond component substitution to full supply chain requalification for CE-marked product lines. German precision engineering clusters are responding fastest, integrating material compliance into upfront design specifications rather than retrofitting existing platforms.
Maintenance departments are consolidating vendor relationships around full-stack condition monitoring providers who bundle hardware, cloud analytics, and corrective action recommendations. Integrated service contracts are displacing component-only procurement in pulp and paper facilities across Sweden and Finland. This bundling preference is most visible in capital-intensive process industries where downtime costs exceed sensor hardware expenditures by orders of magnitude.
Vibration Sensor Market Segmentation
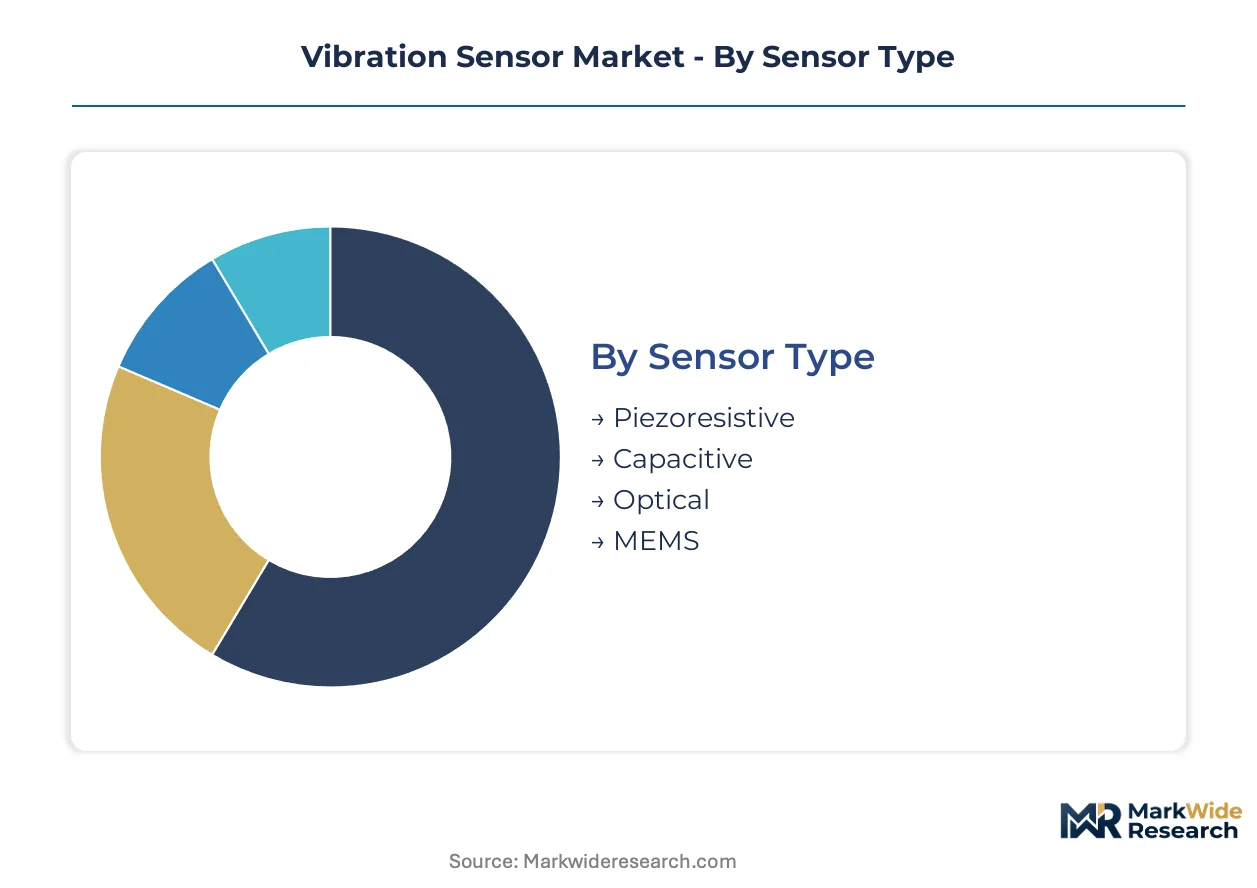
Industrial buyers configure vibration monitoring systems around specific performance envelopes and connectivity constraints. Procurement patterns diverge sharply across sensor architectures, with each technology commanding distinct price points and integration requirements. Understanding these segment boundaries clarifies where suppliers can defend margin positions versus where commoditization pressures dominate.
Sensor Type:
Supply concentration in piezoelectric ceramic processing tilts competitive advantage toward manufacturers with captive material sourcing or long-term offtake agreements with Japanese and Chinese substrate suppliers.
- MEMS:Silicon-batch fabrication enables sub-millimeter form factors and unit economics below ten dollars at volume. Automotive powertrain teams in Stuttgart and Detroit specify MEMS accelerometers for engine knock detection and transmission shift quality monitoring. The segment dominates unit shipments but faces margin compression from foundry commoditization.
- Piezoresistive:Bulk-micromachined silicon or metal foil strain elements operate reliably beyond 150°C where MEMS reliability degrades. Steel rolling mills in Duisburg and geothermal plants in Iceland deploy these for bearing temperature-immune monitoring. Material science differentiation sustains premium pricing against silicon alternatives.
- Capacitive:Variable-gap electrode architectures achieve nanometer displacement resolution for precision alignment verification in semiconductor lithography equipment.
- Optical:Laser Doppler and fiber Bragg grating designs eliminate electromagnetic interference in MRI suite equipment monitoring and high-voltage transformer applications.
Today's leader: MEMS. Tomorrow's challenger: Piezoresistive.
End User:
Application maturity varies dramatically across industrial verticals, with some sectors treating vibration sensing as standard equipment while others remain in pilot-deployment phases.
- Manufacturing:Predictive maintenance mandates in German automotive stamping plants and Japanese precision machining facilities drive specification of triaxial accelerometers with edge-native FFT processing. Brownfield integration complexity favors suppliers offering protocol translation gateways for legacy PLC architectures.
- Aerospace:FAA airworthiness directives and EASA certification pathways impose multi-year validation timelines for engine-mounted health monitoring systems. Boeing and Airbus supply chains demand AS9100 quality systems and full material traceability that exclude commodity sensor vendors.
- Automotive:EV powertrain NVH optimization and battery pack structural monitoring expand addressable sensor count per vehicle platform.
- Healthcare:MRI-compatible vibration isolation and surgical robot joint feedback impose non-magnetic construction requirements that constrain supplier eligibility.
Manufacturing commands current volume. Aerospace captures value through certification barriers.
Technology:
Connectivity architecture selection determines installation economics, with wireless designs eliminating cable costs that often exceed hardware expenditure in retrofit scenarios.
- Wireless:Battery-harvesting piezoelectric nodes and LoRaWAN mesh protocols enable deployment in rotating equipment where slip rings fail. Offshore wind operators in the North Sea and pulp mill dryer sections in Finland adopt self-powered designs to avoid maintenance access costs.
- Wired:4-20 mA loop-powered accelerometers dominate greenfield installations with available cable infrastructure. IP67-rated M12 connectors and shielded twisted-pair routing remain standard in petrochemical facilities governed by intrinsic safety requirements.
- Cloud-Based:Cellular-enabled sensors with direct AWS or Azure streaming bypass local SCADA infrastructure for distributed asset fleets.
- Analog:Raw voltage-output designs persist in R&D environments and custom signal conditioning applications requiring user-defined filtering.
Wired maintains installed base dominance. Wireless is climbing the fastest.
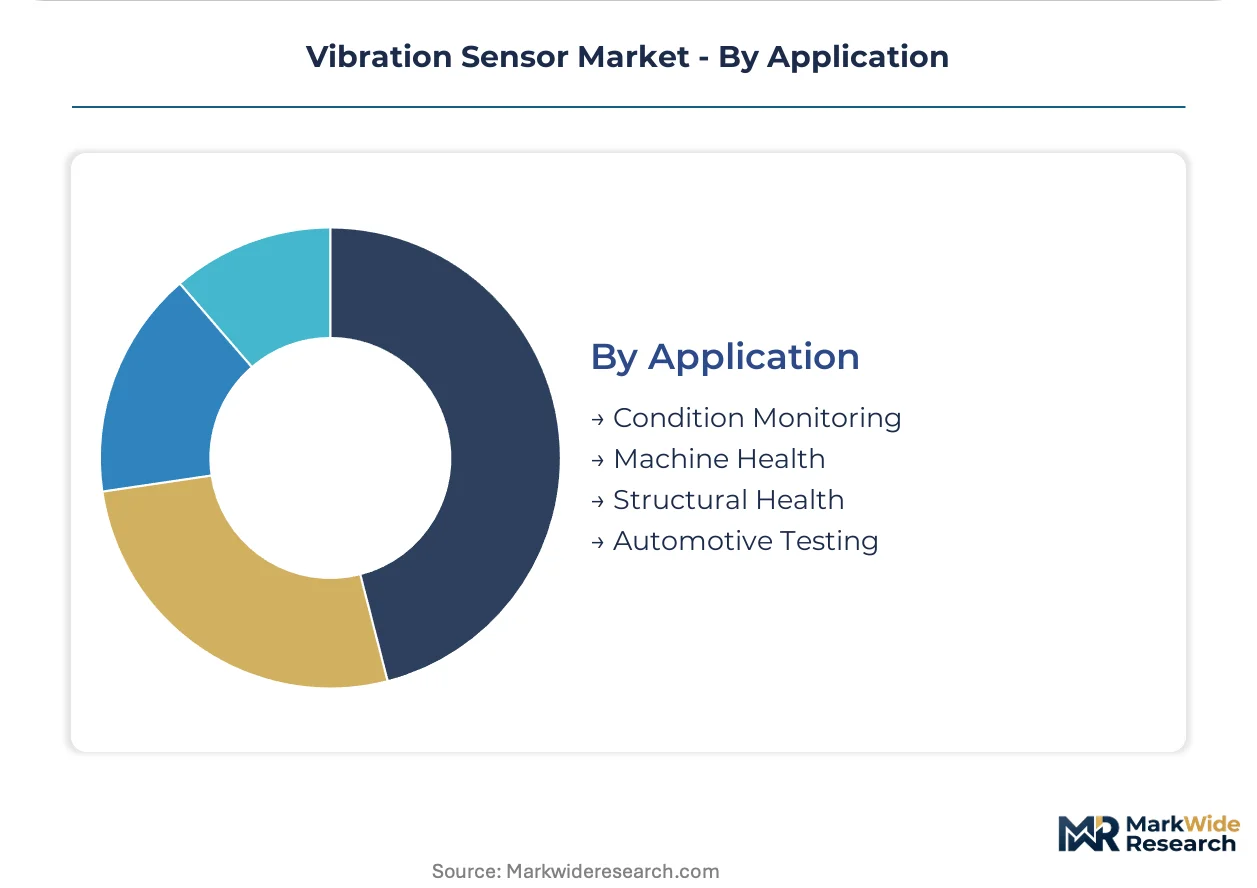
Application:
Functional use case segmentation separates commodity condition alerting from premium diagnostic services that monetize data interpretation rather than hardware shipment.
- Condition Monitoring:Continuous bearing temperature and vibration trending enables scheduled maintenance windows before catastrophic failure. Cement kiln support rollers in India's UltraTech facilities and paper machine dryer cans in Stora Enso mills deploy standardized monitoring nodes with ISO 10816 severity alarm thresholds.
- Machine Health:AI-augmented signature classification distinguishes root cause categories—imbalance, misalignment, looseness, bearing degradation—without human analyst intervention. SKF and Schaeffler bundle this capability into bearing-integrated smart sensor offerings.
- Structural Health:Bridge deck strain and building seismic response monitoring serve civil infrastructure operators with decade-long deployment horizons.
- Automotive Testing:NVH development laboratories and crash test facilities require calibrated reference-grade accelerometers with traceable NIST documentation.
Condition Monitoring anchors revenue. Machine Health is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vibration sensor industry traces its industrial-scale origins to post-war precision engineering clusters in Germany and the United States, where machine tool builders first standardized condition monitoring protocols for rotating equipment. German automotive stamping plants and American steel mills pioneered the integration of piezoelectric sensing into predictive maintenance workflows during the 1970s and 1980s.
Germany
Automotive powertrain teams in Stuttgart and Munich specify triaxial MEMS accelerometers for NVH optimization and transmission quality monitoring. The EU Machinery Directive and CE marking enforcement mandate electromagnetic compatibility certification that elevates engineering costs for non-compliant sensor vendors. Precision engineering clusters in Baden-Württemberg and Bavaria drive specification requirements for high-reliability sensing hardware in bearing-integrated systems.
United States
OSHA machinery safety enforcement accelerates sensor deployment across food processing facilities in the Midwest and petrochemical complexes along the Gulf Coast. The FAA airworthiness certification pathway imposes multi-year validation timelines for engine-mounted health monitoring systems in Seattle and Wichita aerospace manufacturing hubs. Brownfield industrial installations in Ohio and Pennsylvania favor suppliers offering protocol translation gateways for legacy PLC architectures.
China
Steel rolling mills in Duisburg-replica facilities in Hebei Province and geothermal plants in Tibet deploy piezoresistive sensors for bearing temperature-immune monitoring. GB standards and MIIT industrial digitization mandates shape local certification requirements for vibration severity grading equipment. Manufacturing modernization in the Yangtze River Delta pulls MEMS-based sensors into standard equipment specifications for automotive stamping operations.
Japan
METI industrial IoT promotion programs mandate real-time condition monitoring in precision machining facilities around Nagoya and Osaka. JIS standards and PMDA-equivalent industrial safety frameworks constrain sensor design for semiconductor lithography equipment manufacturers in Kyoto and Hiroshima. Automotive powertrain development centers in Toyota City specify sub-millimeter form factor accelerometers for EV NVH optimization.
India
The PLI scheme for capital goods attracts sensor assembly investments serving textile plant modernization in Surat and Ahmedabad. BIS certification timelines and CEA electrical safety directives shape product compliance requirements for cement kiln monitoring systems at UltraTech facilities. Brownfield industrial corridors in Maharashtra and Gujarat favor wireless mesh deployments to avoid cable routing costs in retrofit installations.
Vibration Sensor Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive interconnect portfolios and specialized bearing manufacturers with diagnostic software integration. Tier-one suppliers anchor bundled hardware-gateway offerings while mid-scale specialists concentrate on high-temperature ceramic formulations and hazardous-environment certifications. Dominant competitive moves include backward integration into piezoelectric material sourcing and strategic partnerships with cloud analytics platforms for machine health monetization.
Among diversified industrial technology providers, TE Connectivity Ltd. and Honeywell International Inc. occupy positions exemplifying the bundled hardware-certification archetype. SKF AB represents the vertical specialist model combining bearing manufacturing with integrated sensing systems. PCB Piezotronics, Inc. and Electro-Sensors, Inc. sit within the application-specific tier focused on calibrated reference-grade instrumentation. Emerson Electric Co. and Analog Devices, Inc. anchor the signal conditioning and edge-processing vector.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| TE Connectivity Ltd. |
| Electro-Sensors, Inc. |
| Emerson Electric Co. |
| SKF AB |
| Grace Technologies |
| Honeywell International Inc. |
| PCB Piezotronics, Inc. |
| ALTHEN |
| Others |
Supply Flow & Price Mechanics
German automotive OEM procurement teams anchor pricing power through consolidated volume contracts that favor bundled sensor-gateway configurations over component-only transactions. This buyer concentration enforces three-tier pricing stratification across AS9100-certified aerospace-grade, CE-marked industrial-standard, and uncertified economy tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction architecture, with AS9100 certification and ISO 10816 compliance grading serving as primary price differentiation drivers. Cost compression in MEMS foundry output is intensifying because silicon-batch commoditization erodes margin buffers at the economy tier. Maintenance departments in capital-intensive process industries exhibit lowest price sensitivity, prioritizing uptime guarantees over per-unit hardware costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Detroit automotive clusters, while authorized distributors serve mid-tier MRO procurement across North American brownfield installations. Manufacturing concentrates in China, Japan, and Germany, with piezoelectric ceramic substrates drawing from Japanese and Chinese material processors. Rare earth magnet dependency on Chinese neodymium processing creates single-source vulnerability for velocity sensor architectures. Distribution runs through bearing manufacturers with captive sensing integration and industrial automation specialists with protocol gateway expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA machinery safety enforcement and EU Machinery Directive compliance deadlines compound regulatory-driven replacement cycles, cementing demand visibility for certified suppliers across the analysis window.
For Market Incumbents: Extend certification portfolio coverage into emerging wireless spectrum allocations and cybersecurity labeling frameworks before procurement specifications harden. Deepen backward integration into piezoelectric ceramic sourcing to offset rare earth cost volatility threatening magnet-based velocity sensor margins. Channel control through authorized distributor exclusivity remains essential for defending service attach rates in aftermarket revenue streams. For New Entrants and Emerging Players: Direct-to-maintenance-crew e-commerce platforms offer the most penetrable route for bypassing entrenched industrial distribution in North American MRO procurement. India's PLI scheme for capital goods presents white-space opportunity for sensor assembly investments serving domestic textile and cement plant modernization. Edge-AI convergence in standalone diagnostic nodes enables go-to-market positioning around cloud-bypass latency advantages for critical rotating equipment. For Investors and Strategic Acquirers: Industrial conglomerates with captive interconnect portfolios are the most active acquirer in this space, seeking diagnostic software capabilities to complete full-stack condition monitoring offerings. Acquisition targets should display AS9100 or equivalent certification assets and proven integration with cloud analytics platforms. Watch for wireless spectrum allocation decisions as inflection indicator determining which connectivity architectures secure preferred vendor status in next-generation procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Material Sourcing | Captive ceramic substrate supply insulates SKF and TE Connectivity from Japanese-Chinese offtake volatility. |
| Wireless Mesh Protocol Certification Investment | LoRaWAN and battery-harvesting design validation secures preferred positioning in North Sea offshore wind retrofit procurement. |
| Edge-AI Diagnostic Software Development | On-device vibration signature classification enables Schaeffler to monetize data interpretation beyond hardware shipment. |
| Regulatory Compliance Pre-Certification | Early OSHA machinery safety and EU Machinery Directive alignment accelerates approval timelines for Honeywell's hazardous-environment deployments. |
| Aftermarket Channel Digitization | Direct e-commerce platforms disintermediate traditional industrial distribution for PCB Piezotronics in North American MRO segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads with secondary validation against SEC 10-K filings, customs and trade data, and industrial automation association reports. Bottom-up sensor shipment modeling and top-down predictive maintenance market sizing were triangulated to constrain estimate variance.
Segment-weighting across sensor type, connectivity technology, end-use vertical, and regional regulatory cluster shaped analytical framework deployment over the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle acceleration, and technology substitution curves specific to MEMS displacement of piezoelectric architectures in sub-150°C applications.
Rare earth supply disruption, wireless spectrum reallocation, and REACH substance restriction expansion are the dominant revision risks that could compress or extend forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Europe Wearable Sensors Market