
 Water and Wastewater Sensors Market | 2026-2036
Water and Wastewater Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Water and Wastewater Sensors Market Analytics
Municipal water treatment is rebalancing toward smart network monitoring as industrial discharge compliance tightens globally. Xylem Inc. leverages its vertical integration across electrochemical and optical sensing platforms to dominate utility retrofit programs. Endress+Hauser anchors European market share through specialized pH and conductivity instrumentation for chemical processing plants. Hach Company competes aggressively in North American environmental monitoring channels with portable turbidity analyzers.
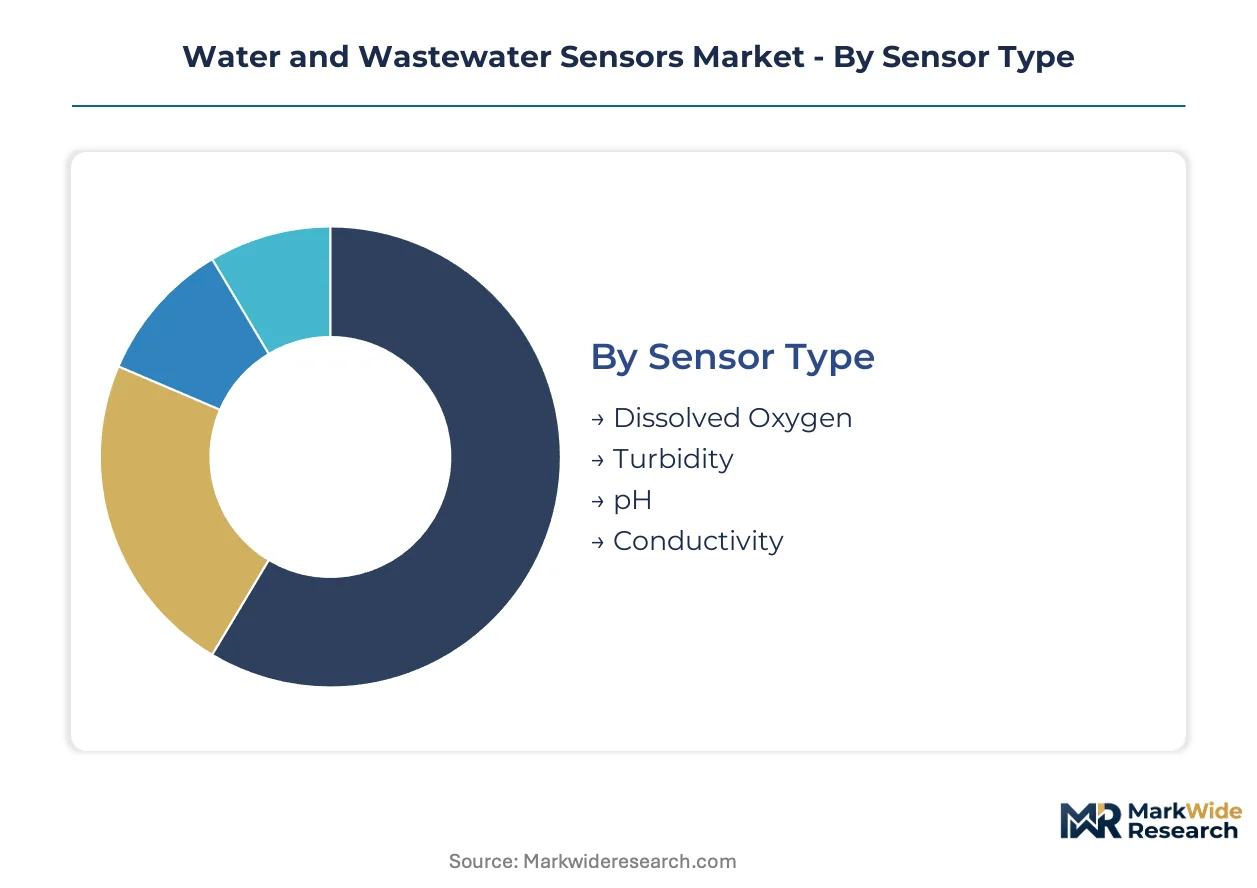
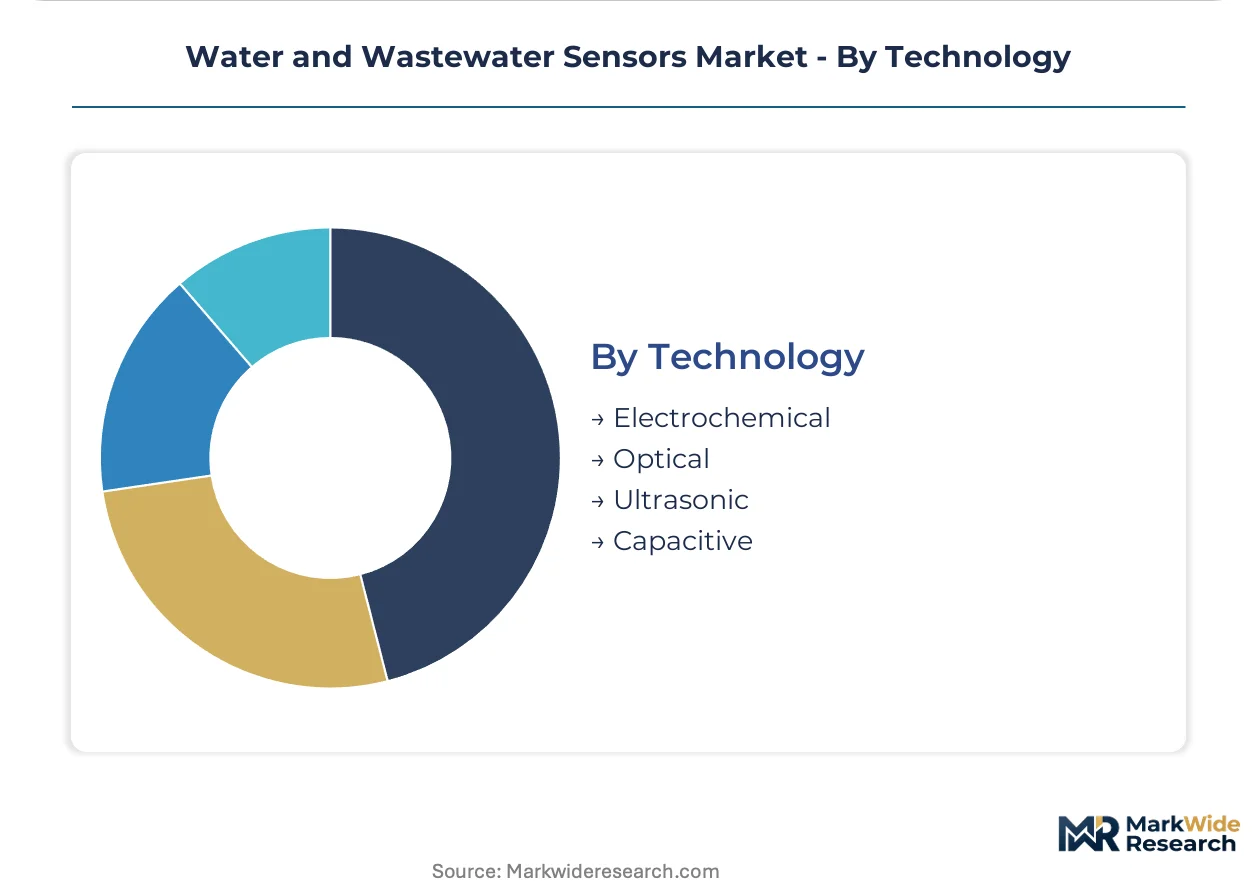
Water and wastewater sensors are electrochemical, optical, ultrasonic, or capacitive transducers that detect dissolved oxygen, turbidity, pH, conductivity, and other physicochemical parameters in liquid streams, typically operating within temperature ranges of minus five to fifty degrees Celsius and pressure ratings up to ten bar for industrial immersion applications. Their primary purpose is to enable real-time process control, regulatory compliance verification, and early warning of contamination events across treatment infrastructure. The sensor type dimension shows dissolved oxygen and pH modules commanding the largest installed base due to universal applicability in biological treatment stages, while optical turbidity sensors represent the fastest-expanding margin pool as drinking water plants replace legacy nephelometers with laser-based units. The technology dimension reveals electrochemical methods still occupying the majority of legacy installations, though optical platforms are displacing them in high-fouling wastewater environments where reduced maintenance intervals justify premium sensor costs.
The US EPA enforces Clean Water Act discharge limits that mandate continuous parameter logging, while the EU Urban Wastewater Treatment Directive and China's MEE surface water quality standards are converging toward tighter ammonia and total nitrogen thresholds that demand multi-parameter sensor arrays. These regulatory frameworks shape product standards by requiring IEC 60529 IP68 housings, ISO 15839 compliance for online analyzers, and NIST-traceable calibration protocols that create certification barriers for unqualified suppliers. Stakeholders must monitor how the EU's forthcoming pharmaceutical micropollutant monitoring obligations and China's dual carbon goals for treatment energy efficiency will reshape sensor specification requirements and procurement criteria across municipal and industrial buyer segments.
Market Dynamics
Smart network monitoring is absorbing capital allocation as municipal utilities confront tightening discharge compliance thresholds across Germany, the United States, and China's industrial corridors. Electrochemical and optical sensing platforms are competing for retrofit budgets against legacy nephelometer replacements.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Revisions mandate tighter ammonia and total nitrogen thresholds, forcing multi-parameter sensor array installations across Rhine-Ruhr metropolitan treatment plants.
- Optical turbidity platforms:Laser-based units are displacing legacy nephelometers in drinking water infrastructure as maintenance intervals compress operational budgets.
- Yangtze River Delta industrial corridor:China's MIIT water quality mandates are accelerating dissolved oxygen and turbidity monitoring procurement for chemical processing discharge compliance.
Market Restraints
- IP68 housing supply concentration:IEC 60529-certified enclosure manufacturing clusters in East Asia create single-source vulnerability for immersion-rated sensor assemblies.
- Calibration protocol fragmentation:NIST-traceable standards diverge from EU reference materials, forcing dual certification costs for suppliers serving transatlantic utility buyers.
- Electrochemical sensor fouling:High-solids wastewater environments degrade membrane performance, compressing replacement cycles and raising total cost of ownership.
Strategic Opportunities
- Pharmaceutical micropollutant monitoring:The EU's forthcoming discharge obligations for active pharmaceutical ingredients will create demand for specialized organic compound detection arrays.
- Dual carbon efficiency mandates:China's MEE energy efficiency targets for treatment plants are opening procurement channels for sensors enabling aeration optimization and power consumption reduction.
- Edge computing convergence:On-device analytics integration with LoRaWAN transmission protocols is enabling predictive maintenance models for distributed rural treatment networks.
Industry Challenges
- ISO 15839 certification timelines:Online analyzer validation protocols extend product launch cycles by 12-18 months, compressing competitive response windows.
- Legacy SCADA integration complexity:Municipal utilities operate heterogeneous control architectures that resist standardized sensor communication protocols.
- Field calibration skill scarcity:Electrochemical sensor maintenance requires specialized technician training that utility workforces lack across aging infrastructure regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water and Wastewater Sensors Market |
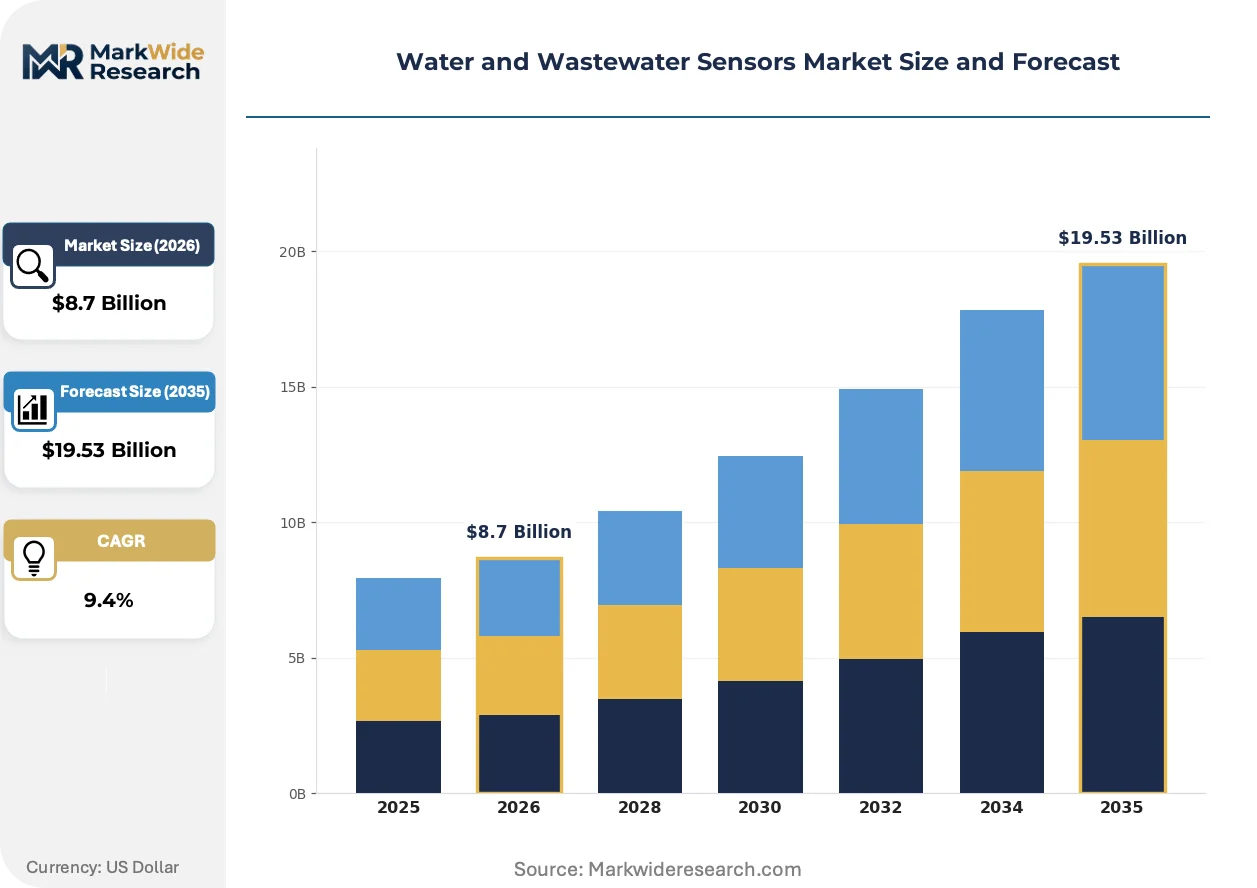
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Dissolved Oxygen, Turbidity, pH, Conductivity Application: Industrial Processes, Environmental Monitoring, Waste Treatment, Aquaculture End User: Municipalities, Manufacturing Plants, Research Institutions, Agriculture Technology: Electrochemical, Optical, Ultrasonic, Capacitive |
| Companies Covered | Xylem Inc., Hach Company, Endress+Hauser, ABB Ltd., Yokogawa Electric Corporation, Thermo Fisher Scientific Inc., Emerson Electric Co., Teledyne Technologies Incorporated, KROHNE Messtechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water and Wastewater Sensors Market Evolving Landscape
Digital twin deployment is reshaping how utilities simulate treatment performance before sensor hardware procurement. Predictive maintenance algorithms and self-cleaning optical surfaces are converging to reduce field service dependency.
Self-cleaning optical turbidity sensors are absorbing maintenance budget allocations as German and Dutch utilities prioritize reduced field intervention. Drinking water plants in the Rhine-Ruhr region are replacing nephelometer arrays with laser-based units that incorporate ultrasonic surface vibration. The technology is absorbing service contract revenue that previously flowed to third-party calibration providers.
China's MEE surface water quality standards are converging with EU ammonia thresholds, creating harmonized specification demand for multi-parameter arrays. Industrial discharge permits in the Yangtze River Delta now require continuous total nitrogen logging that matches EU Urban Wastewater Treatment Directive stringency. Sensor suppliers are consolidating product lines around unified measurement ranges to serve both regulatory regimes without SKU proliferation.
Utility procurement departments are unbundling sensor hardware from installation and calibration service contracts. North American municipal buyers are separating capital equipment acquisition from multi-year maintenance agreements, forcing suppliers to compete on device price rather than bundled lifecycle value. This pattern is most visible in EPA-regulated metropolitan districts where procurement transparency rules mandate competitive bidding for each contract element.
Water and Wastewater Sensors Market Segmentation
Sensor specification choices directly determine compliance viability and maintenance economics across treatment infrastructure. Procurement teams evaluate measurement range, fouling resistance, and protocol compatibility before platform selection.
Sensor Type:
Measurement parameter selection governs biological treatment efficiency and discharge permit adherence.
- Dissolved Oxygen:Electrochemical membrane or optical luminescent probes quantify oxygen availability for activated sludge processes. German municipal utilities in the Rhine-Ruhr region deploy these arrays for nitrification control under tightened EU ammonia thresholds.
- Turbidity:Laser-based nephelometric sensors detect suspended particle density in clarified effluent streams. Drinking water plants across the United States are accelerating procurement of self-cleaning optical units to compress field service intervals.
- pH:Glass electrode assemblies with reference junctions measure hydrogen ion concentration for chemical dosing feedback loops.
- Conductivity:Four-electrode cells assess total dissolved solids and salinity variations in industrial discharge monitoring.
Dissolved Oxygen leads on scale; Turbidity leads on momentum.
Application:
Deployment context shapes housing specifications, calibration frequency, and data logging requirements.
- Industrial Processes:High-temperature immersion-rated assemblies monitor chemical reaction kinetics and cooling tower cycles. China's Yangtze River Delta chemical corridor demands continuous multi-parameter logging under MIIT discharge mandates.
- Environmental Monitoring:Portable battery-powered units with GPS tagging track surface water quality at compliance checkpoints. EPA-regulated watershed programs in the United States specify NIST-traceable calibration protocols for these deployments.
- Waste Treatment:IP68-hardened sensors withstand aggressive biological media and hydrogen sulfide exposure in anaerobic digesters.
- Aquaculture:Low-power dissolved oxygen transmitters with alarm relays protect intensive fish farm operations from hypoxic mortality events.
Waste Treatment dominates procurement volume; Environmental Monitoring shows steepest specification escalation.
End User:
Capital allocation authority and technical staffing levels create divergent purchasing patterns across buyer categories.
- Municipalities:Public utilities operate aging infrastructure with heterogeneous SCADA architectures that resist standardized sensor integration. German and United States metropolitan districts unbundle hardware from service contracts under competitive procurement rules.
- Manufacturing Plants:Private sector buyers prioritize total cost of ownership metrics and predictive maintenance integration for continuous process streams.
- Research Institutions:Academic and government laboratories specify high-precision laboratory-grade analyzers with expanded measurement ranges for method development.
- Agriculture:Irrigation districts and livestock operations deploy simplified conductivity and pH probes for nutrient runoff monitoring.
Municipalities anchor installed base; Manufacturing Plants drive specification upgrades fastest.
Technology:
Transduction method selection trades initial capital outlay against operational longevity and measurement accuracy.
- Electrochemical:Amperometric and potentiometric techniques dominate legacy installations through proven reliability in low-solids applications. Membrane fouling in high-solids wastewater compresses replacement cycles and elevates total ownership costs.
- Optical:Laser-induced fluorescence and absorbance spectroscopy displace electrochemical platforms in fouling-prone environments. Reduced maintenance intervals justify premium sensor costs for Rhine-Ruhr utilities replacing nephelometer arrays.
- Ultrasonic:Time-of-flight and Doppler principles measure flow velocity and suspended solids concentration without immersion electrode degradation.
- Capacitive:Dielectric property sensing enables non-contact level and interface detection in corrosive chemical storage.
Electrochemical retains largest installed base; Optical platforms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is fragmenting production location decisions as sensor suppliers chase compliance-cost arbitrage. German and Chinese utilities face the steepest ammonia threshold escalations, while US metropolitan districts absorb legacy SCADA integration burdens. Suppliers are consolidating certification efforts around IEC and ISO harmonization to serve multiple regimes without SKU multiplication.
United States
EPA Clean Water Act discharge mandates force continuous parameter logging across aging municipal infrastructure. Metropolitan utilities in the Great Lakes and Ohio River watersheds unbundle hardware procurement from service contracts under competitive bidding rules. Chicago and Cleveland districts accelerate dissolved oxygen array installations for nitrification control upgrades.
Germany
EU Urban Wastewater Treatment Directive revisions tighten total nitrogen thresholds across Rhine-Ruhr metropolitan treatment plants. ECHA chemical discharge protocols shape sensor housing specifications for industrial immersion applications. Düsseldorf and Essen utilities replace nephelometer arrays with laser-based turbidity units incorporating ultrasonic self-cleaning surfaces.
China
MIIT water quality mandates and MEE surface water standards converge on EU-equivalent ammonia thresholds. Yangtze River Delta chemical processors procure multi-parameter arrays for continuous discharge compliance logging. Shanghai and Suzhou industrial corridors absorb the fastest sensor deployment rates under dual carbon efficiency targets for aeration optimization.
Japan
METI industrial water recycling directives drive sensor demand in semiconductor and chemical processing facilities. JIS standards for online analyzers create certification barriers for non-domestic suppliers. Osaka and Nagoya manufacturing belts deploy conductivity and pH instrumentation for closed-loop cooling tower monitoring.
Water and Wastewater Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line instrumentation groups commanding municipal retrofit programs and component fabricators penetrating price-sensitive industrial accounts. The vendor base stratifies into three tiers: electrochemical legacy specialists defending installed base, optical platform innovators capturing replacement cycles, and Asian contract manufacturers supplying enclosure and electrode subassemblies. Consolidation pressure concentrates among mid-scale European sensor houses lacking the calibration infrastructure to serve transatlantic dual-certification requirements. Dominant competitive moves include backward integration into optical component manufacturing and strategic partnerships with edge computing software vendors for predictive maintenance bundling.
Among the named instrumentation groups, Xylem Inc. and Endress+Hauser occupy positions on opposite sides of the Atlantic, with the former exemplifying vertical integration across sensing platforms and the latter representing specialized European market anchoring through pH and conductivity instrumentation. Hach Company sits within the North American environmental monitoring channel as a reference point for portable turbidity analyzer competition. These three entities illustrate how geographic regulatory specialization shapes competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| Xylem Inc. |
| Hach Company |
| Endress+Hauser |
| ABB Ltd. |
| Yokogawa Electric Corporation |
| Thermo Fisher Scientific Inc. |
| Emerson Electric Co. |
| Teledyne Technologies Incorporated |
| KROHNE Messtechnik GmbH |
| Others |
Value Network & Pricing Analysis
Calibration technician clusters in Germany's Rhine-Ruhr metropolitan region anchor labor-cost differentials that widen pricing-tier spreads between premium optical platforms and economy electrochemical units. Municipal utilities unbundle hardware from service contracts, compressing margins on bundled offerings while amplifying price sensitivity at the standard tier.
Pricing Analysis
Distributor margins on IEC 60529-certified immersion assemblies absorb 18-25 points before reaching municipal procurement departments. Three-tier pricing structure across premium optical, standard electrochemical, and economy capacitive levels separates buyers by certification stringency and maintenance bundling. Pricing pressure stems from North American competitive bidding rules that force transparent hardware-only tenders. Manufacturing plants show least price sensitivity due to total-cost-of-ownership procurement criteria, while agricultural irrigation districts drive economy-tier volume.
Supply Chain Analysis
Certification gating through NIST-traceable calibration protocols and ISO 15839 validation concentrates qualified supply among German, Japanese, and US instrumentation houses. IP68 housing fabrication draws from East Asian enclosure specialists, while optical component sourcing rests on German laser diode and Japanese photodetector suppliers. Single-source vulnerability in IEC-certified enclosure manufacturing creates procurement risk for immersion-rated assemblies. Distribution runs through authorized instrumentation distributors serving municipal utility and industrial plant verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with the EU's forthcoming pharmaceutical micropollutant monitoring obligations creating sustained replacement demand across Rhine-Ruhr treatment infrastructure.
For Market Incumbents: Lock in calibration infrastructure advantages by acquiring NIST-traceable reference material suppliers, neutralizing dual-certification cost burdens that threaten mid-scale European competitors. Deepen backward integration into optical component manufacturing to defend margin position against Asian contract manufacturers penetrating price-sensitive industrial accounts.
For New Entrants and Emerging Players: Capture edge computing convergence opportunities in distributed rural treatment networks where predictive maintenance algorithms remain underdeployed. Target China's Yangtze River Delta chemical corridor through MIIT-compliant multi-parameter arrays, leveraging aeration optimization specifications under dual carbon mandates as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European sensor houses lacking transatlantic calibration infrastructure to serve dual-certification requirements. Long-term viability favors suppliers with captive optical component production and software bundling capability. Watch EU pharmaceutical discharge obligation implementation timelines as the inflection signal for organic compound detection array demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captures laser diode and photodetector margin pools that currently flow to German and Japanese suppliers. |
| Calibration Infrastructure Acquisition | Neutralizes dual-certification cost barriers that fragment competitive positioning across transatlantic utility buyers. |
| Edge Computing Software Partnership | Enables predictive maintenance bundling that differentiates offerings in distributed rural treatment network tenders. |
| MIIT Compliance Certification Investment | Opens procurement channels in China's Yangtze River Delta chemical corridor under tightening discharge mandates. |
| Pharmaceutical Micropollutant Detection Development | Positions suppliers for EU discharge obligation implementation across Rhine-Ruhr metropolitan treatment plants. |
Research Methodology
Bottom-up municipal utility procurement modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with wastewater treatment plant engineers, municipal procurement officers, OEM instrumentation product managers, and aftermarket service heads combined with secondary validation from EPA discharge enforcement databases, EU Urban Wastewater Treatment Directive implementation reports, MIIT water quality mandate filings, and ISO 15839 certification registries.
Input-output matrices map sensor type, application, end user, and technology dimensions across the projection horizon. Segmentation outputs reflect modeled interactions between regulatory threshold tightening, replacement cycle compression, and procurement unbundling trends. CAGRs derive from installed base turnover rates and specification upgrade intensities, with aeration optimization demand under China's dual carbon goals and pharmaceutical micropollutant detection requirements shaping trajectory assumptions.
Underlying measurement precision varies by segment; optical turbidity and dissolved oxygen arrays carry tighter precision than conductivity and pH modules due to standardization maturity. Forecasts reflect documented assumptions around regulatory implementation timelines and infrastructure replacement funding availability. Deviation in EU pharmaceutical discharge obligation scheduling or China MIIT enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Mexico Digital Thermometer Market