
 Laser Beam Welding Equipment Market | 2026-2036
Laser Beam Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Beam Welding Equipment Market Insights
Aluminum substitution for steel in automotive body-in-white construction is broadening the addressable market for high-power fiber laser welders. TRUMPF leverages its vertical integration in beam source manufacturing to control cost structures across the equipment stack. IPG Photonics Corporation anchors its position through captive diode production, while Han's Laser Technology Group competes aggressively on price in the Asian contract equipment market.
Laser beam welding equipment joins metallic workpieces through a concentrated coherent light beam generating temperatures exceeding ten thousand degrees Celsius at the focal point, with typical power densities ranging from one hundred kilowatts per square centimeter to ten megawatts per square centimeter depending on the source architecture. Solid-state platforms, particularly fiber and disk laser variants, now dominate capital procurement for thick-section industrial applications due to superior wall-plug efficiency and beam quality. Pulsed wave systems retain margin advantages in microelectronics and jewelry manufacturing where heat-affected zone minimization commands premium pricing. CO2 laser technology persists in legacy shipyard installations but captures shrinking share of new orders as direct diode and fiber alternatives displace gas-based architectures.
OSHA laser safety standards in the United States, the EU Machinery Directive's CE marking requirements, and China's GB laser product safety standards collectively shape equipment design protocols and market access conditions across major manufacturing jurisdictions. The EU AI Act's emerging conformity frameworks for automated welding cells will add compliance layers for systems integrating real-time seam tracking and adaptive process control. Stakeholders must monitor how regional carbon border adjustment mechanisms reshape total cost of ownership calculations for energy-intensive welding operations.
Market Dynamics
Automotive OEM electrification roadmaps are compressing capital equipment replacement cycles, forcing welding system suppliers to accelerate platform refresh rates while maintaining backward compatibility with legacy production lines.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Energy-efficiency requirements are accelerating displacement of CO2 laser architectures with solid-state fiber and disk variants in German, Italian, and French automotive plants.
- Aluminum body-in-white adoption:Automotive lightweighting programs are expanding the addressable application set for high-power fiber laser welders capable of processing reflective alloys at production speeds.
- EV battery pack assembly standardization:Cylindrical and prismatic cell formats are driving repeatable, high-throughput welding protocols across South Korean, Chinese, and US gigafactory deployments.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese refining operations creates input cost volatility for fiber laser resonator manufacturing.
- Technical limitation in copper welding:High reflectivity and thermal conductivity of electrical-grade copper remain process control challenges for infrared wavelength systems at speeds required for busbar applications.
- OSHA laser safety compliance burden:US manufacturers face extended engineering validation timelines for Class 4 enclosure designs, delaying field deployment of automated welding cells.
Strategic Opportunities
- India automotive supplier base expansion:PLI scheme incentives for advanced manufacturing are attracting welding equipment investment to Pune and Chennai precision engineering clusters.
- EU AI Act conformity frameworks:Real-time seam tracking and adaptive process control systems will command premium positioning as regulatory compliance layers become mandatory for automated installations.
- Green hydrogen infrastructure fabrication:Pressure vessel and pipeline welding specifications are opening new demand channels for high-power disk laser systems in German and Danish renewable energy supply chains.
Industry Challenges
- Multi-physics simulation expertise scarcity:Laser-material interaction modeling for new alloy qualification requires rare combinations of optical physics and metallurgical training that outpace vocational pipeline output.
- CE marking timeline compression:EU Machinery Directive conformity assessment for integrated robotic welding cells now averages 14-18 months, constraining revenue recognition for system integrators.
- Legacy CO2 system stranded asset risk:Declining spare part availability and service technician retirement are forcing premature replacement decisions before technical end-of-life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Beam Welding Equipment Market |
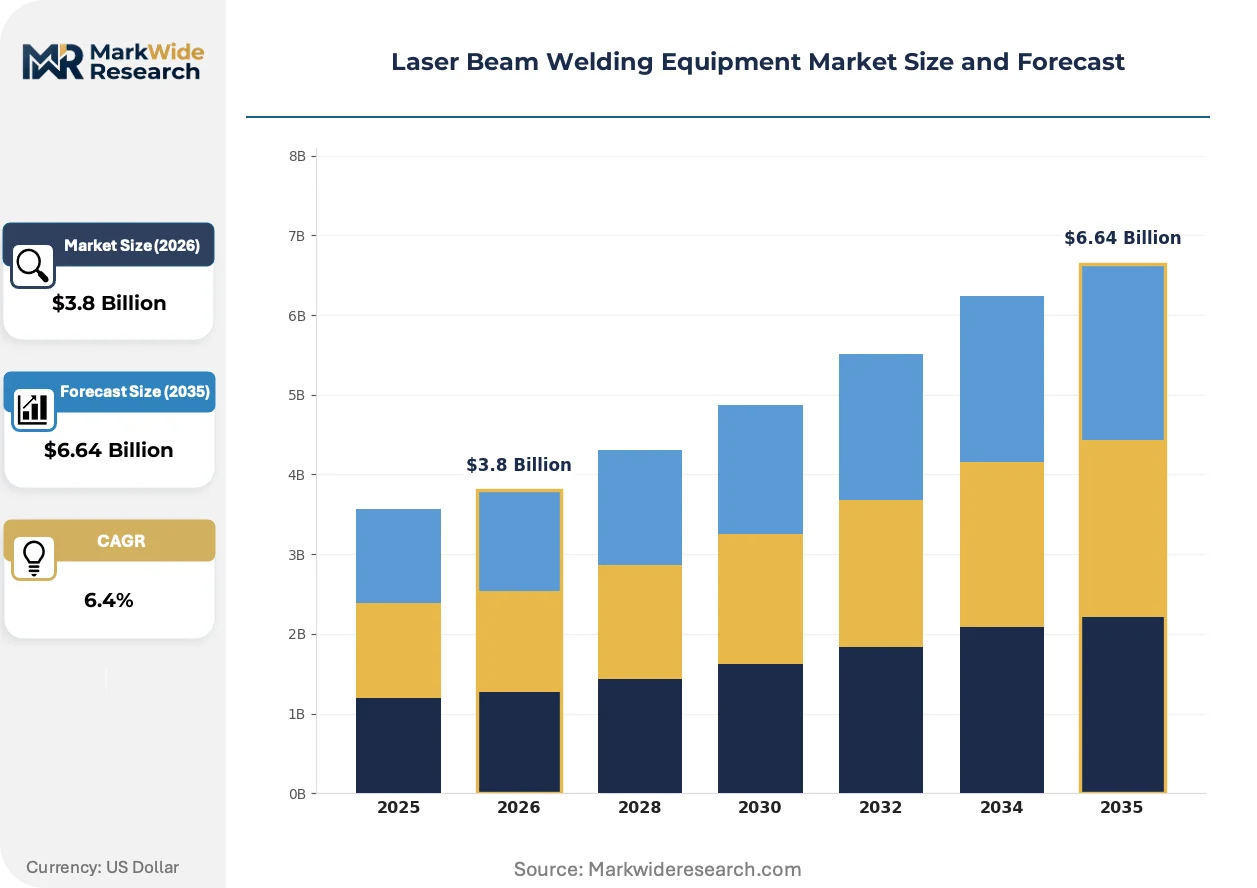
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave, Pulsed Wave, Hybrid, Fiber Laser, CO2 Laser Technology: Solid-state, Gas Laser, Semiconductor, Disk Laser, Direct Diode Application: Microelectronics, Aerospace Assembly, Shipbuilding, Jewelry Manufacturing, Tool Fabrication End User: Automotive OEMs, Precision Instrument Makers, Defense Contractors, Electronic Component Manufacturers |
| Companies Covered | TRUMPF, IPG Photonics Corporation, Coherent Corp, Han's Laser Technology Group, Jenoptik AG, Amada Weld Tech, Emerson Electric, CHIRON Group, Precitec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Beam Welding Equipment Market Trends and Innovations
Beam source architecture consolidation and process control digitization are compressing the traditional boundaries between welding equipment categories, creating hybrid platforms that span multiple power regimes and application types.
Single-mode fiber laser technology is unifying previously segmented power classes into continuous platforms spanning 1kW to 20kW with common beam delivery architectures. Automotive tier-one suppliers in Germany and Japan are standardizing on these scalable sources to reduce spare inventory and operator retraining burdens. This unification is compressing vendor margins at mid-power tiers while concentrating procurement decisions at the beam source level rather than the system integrator level.
China's GB laser product safety standards revision is tightening enclosure interlock and emission monitoring requirements for industrial installations. Domestic equipment manufacturers in Suzhou and Shenzhen are accelerating in-house certification capabilities to avoid third-party testing bottlenecks. Export-oriented Chinese suppliers are diverging product lines between domestic-compliance and international-certification variants, fragmenting their engineering resource allocation.
Buyers are unbundling after-sales service contracts from initial equipment procurement, shifting to time-and-materials arrangements with regional service boutiques. German automotive OEMs pioneered this model in Stuttgart and Munich manufacturing clusters, and the practice is propagating to Korean battery producers seeking to avoid long-term vendor lock-in. Equipment manufacturers are responding with remote diagnostics subscriptions to preserve recurring revenue streams independent of hardware margins.
Laser Beam Welding Equipment Market Segmentation
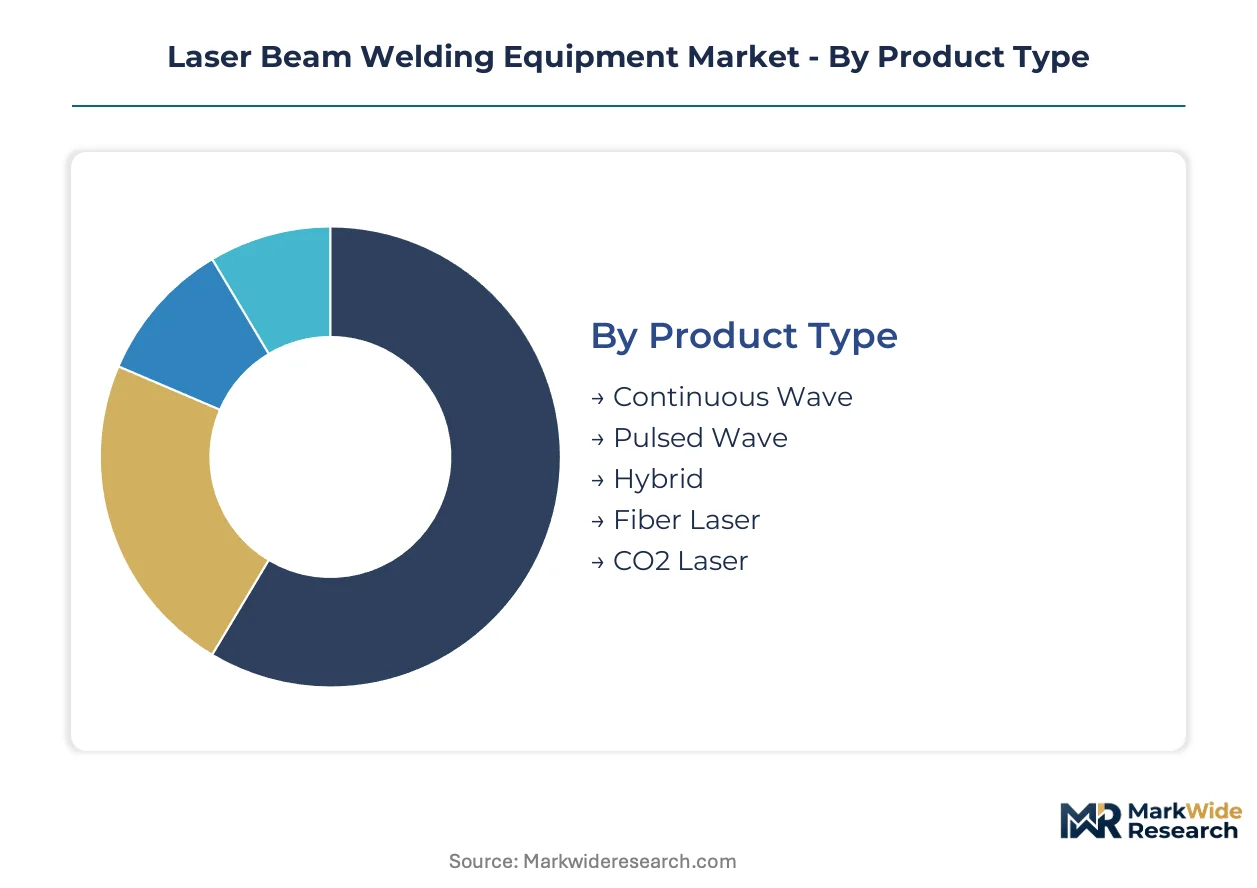
Segmentation in laser beam welding equipment reveals how beam source architecture, process control modes, and end-use precision requirements create distinct procurement patterns. Buyers optimize across thermal management, capital intensity, and regulatory compliance rather than selecting on power alone.
Product Type:
Customization spans from standardized continuous platforms for automotive lines to bespoke pulsed configurations for medical device microjoining.
- Continuous Wave:Sustained beam output delivers stable heat input for thick-section steel and aluminum joining in automotive body-in-white lines. German OEMs in Stuttgart and Munich anchor procurement volume as EV platform welding specifications standardize.
- Pulsed Wave:Discrete energy bursts minimize heat-affected zones in battery tab welding and sensor packaging. South Korean battery producers specify these systems for cylindrical cell interconnects where thermal damage risks cell degradation.
- Hybrid:Combines laser and arc processes for gap-bridging in heavy fabrication. Shipyards in South Korea and Japan deploy hybrid systems for thick plate assembly where fit-up tolerances exceed pure laser capability.
- Fiber Laser:Solid-state architecture with doped fiber gain medium dominates new capital procurement for wall-plug efficiency advantages.
- CO2 Laser:Gas-based systems persist in legacy installations but capture minimal share of current orders as fiber alternatives displace them.
Leading the category by volume: Continuous Wave. Expanding most quickly: Fiber Laser.
Technology:
Cost tiers separate mature gas architectures from premium solid-state platforms with superior beam quality metrics.
- Solid-state:Fiber and rod-based resonators using rare-earth dopants deliver electrical-to-optical conversion above thirty percent. Chinese equipment manufacturers in Suzhou compete aggressively on price for domestic battery plant contracts.
- Gas Laser:CO2 and excimer systems rely on gas discharge excitation with higher maintenance burdens and lower efficiency. Legacy tool fabrication shops in the United States retain these systems where amortization schedules delay replacement.
- Semiconductor:Direct diode arrays offer compact footprints and wavelength tunability for polymer welding applications. Medical device manufacturers specify semiconductor sources for catheter assembly where footprint constraints dominate.
- Disk Laser:Thin-disk geometry combines high power with excellent beam quality for precision aerospace component welding. German precision engineering clusters favor disk technology for turbine blade repair applications.
- Direct Diode:Eliminates intermediate gain medium for maximum electrical efficiency in high-volume production environments.
Highest margin capture: Disk Laser. Fastest volume growth: Solid-state.
Application:
Customer type stratification separates capital-intensive heavy fabrication from precision-limited microjoining operations.
- Microelectronics:Sub-millimeter feature welding for semiconductor packaging and MEMS devices demands sub-fifty-micron positioning accuracy. Taiwanese contract manufacturers specify pulsed fiber systems for flip-chip interconnect production.
- Aerospace Assembly:Titanium and nickel superalloy joining for engine components requires vacuum or inert atmosphere chambers. French and German aerospace suppliers invest in high-power disk laser cells for single-crystal blade repair.
- Shipbuilding:Thick steel plate welding in panel lines and block assembly favors hybrid laser-arc configurations. South Korean yards lead adoption as naval and commercial vessel specifications tighten.
- Jewelry Manufacturing:Pulsed Nd:YAG systems dominate precious metal joining where cosmetic finish requirements exceed structural load criteria.
- Tool Fabrication:Hardfacing and repair of cutting tools uses automated powder delivery with continuous wave sources.
Dominant by revenue: Aerospace Assembly. Steepest expansion trajectory: Microelectronics.
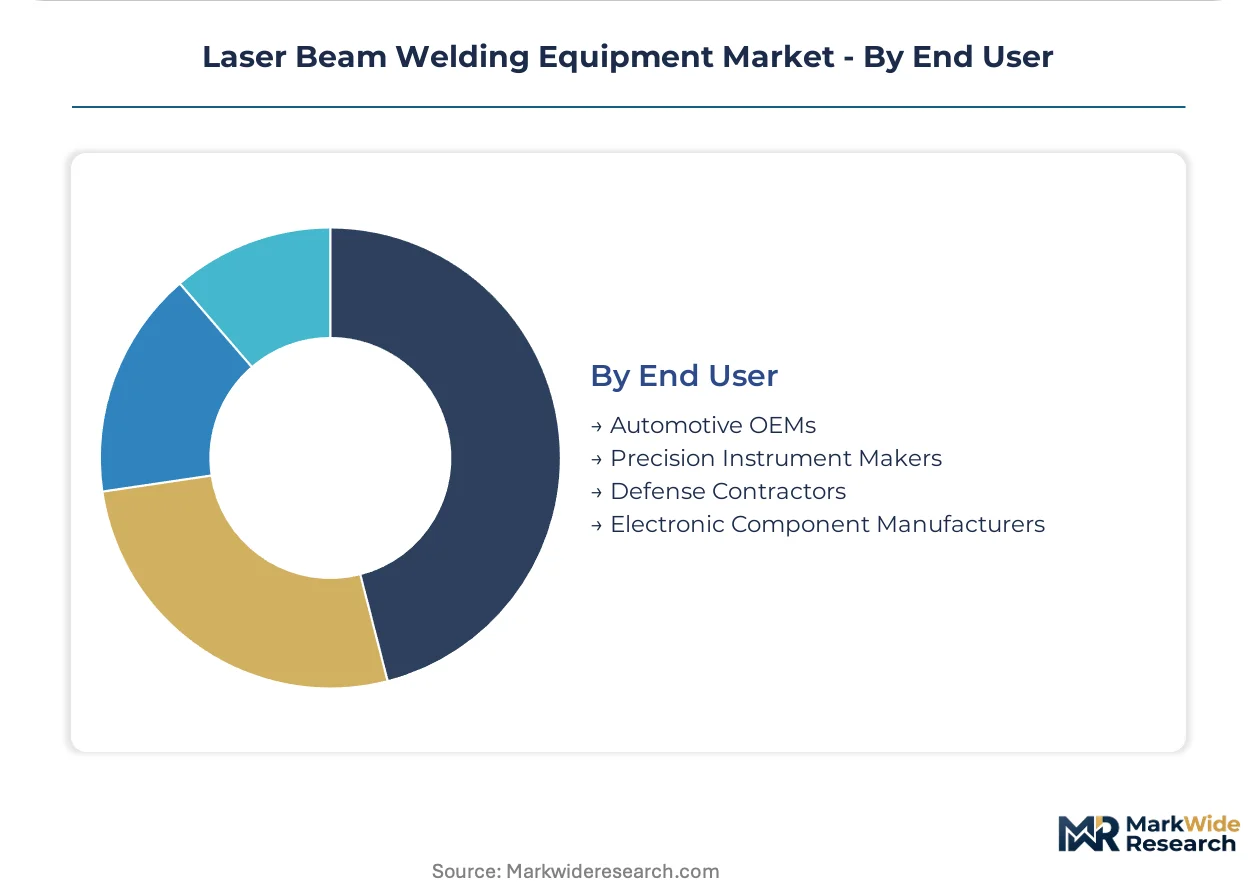
End User:
Geography of demand concentrates in manufacturing clusters with precision engineering heritage and automotive electrification investment.
- Automotive OEMs:Battery pack assembly lines and aluminum body construction drive the largest equipment procurement volumes. German, Chinese, and US manufacturers compress replacement cycles as platform architectures shift to electrification.
- Precision Instrument Makers:Medical device and analytical instrument manufacturers specify Class 1 enclosure systems for cleanroom compatibility. Swiss and German clusters anchor demand for validated welding protocols.
- Defense Contractors:Armor plating and weapons system fabrication require ITAR-compliant supply chains with restricted technology transfer. US and French contractors maintain captive welding capabilities for classified programs.
- Electronic Component Manufacturers:PCBA and sensor packaging operations prioritize throughput and thermal management over maximum penetration depth.
Volume leader: Automotive OEMs. Gaining share fastest: Precision Instrument Makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in manufacturing clusters with precision engineering heritage and automotive electrification investment. German automotive OEMs anchor European demand through Stuttgart and Munich engineering corridors. Chinese battery gigafactories and South Korean shipyards drive Asia-Pacific volume expansion.
Germany
Automotive electrification roadmaps from BMW, Mercedes-Benz, and Volkswagen compress capital equipment replacement cycles for fiber laser welding systems. The EU Green Deal's industrial decarbonization mandates accelerate displacement of CO2 laser architectures in Baden-Württemberg and Bavaria automotive plants. Stuttgart precision engineering clusters anchor advanced manufacturing investment for EV battery pack assembly lines.
China
Domestic battery producers CATL and BYD drive repeatable, high-throughput welding protocols across cylindrical and prismatic cell formats. GB laser product safety standards revisions tighten enclosure interlock requirements for industrial installations in Suzhou and Shenzhen manufacturing hubs. Yangtze River Delta equipment manufacturers compete aggressively on price for domestic gigafactory contracts while diverging export-oriented product lines.
United States
Detroit Three OEMs and Tesla compress platform refresh rates while maintaining backward compatibility with legacy production lines. OSHA laser safety standards extend engineering validation timelines for Class 4 enclosure designs, delaying automated welding cell deployment. Midwest automotive supplier bases in Michigan and Ohio face stranded asset risk from declining CO2 laser spare part availability.
South Korea
Hyundai, Kia, and SK On standardize welding specifications across battery gigafactory deployments for cylindrical cell interconnects. Korean battery producers pioneer unbundled after-sales service contracts to avoid long-term vendor lock-in. Busan-Ulsan shipyards lead hybrid laser-arc adoption for thick plate assembly where fit-up tolerances exceed pure laser capability.
India
Maruti Suzuki, Tata Motors, and Mahindra & Mahindra expand aluminum body-in-white construction for lightweighting programs. PLI scheme incentives for advanced manufacturing attract welding equipment investment to Pune and Chennai precision engineering clusters. Tamil Nadu automotive supplier bases specify high-power fiber laser welders for reflective alloy processing at production speeds.
Laser Beam Welding Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as beam source manufacturers align with system integrators to control equipment stack margins. The vendor base stratifies across three tiers: captive diode producers with upstream resonator manufacturing, mid-scale system integrators with regional service networks, and price-competitive Asian fabricators serving contract equipment markets. Consolidation pressure concentrates at the beam source level as procurement decisions shift from integrators to source manufacturers. Technology licensing agreements and backward integration into rare-earth magnet supply chains represent the dominant competitive moves.
Among German-based precision engineering groups, TRUMPF GmbH + Co. KG and Jenoptik AG exemplify the captive manufacturing archetype through in-house beam source production. IPG Photonics Corporation anchors the North American tier through its position in fiber laser resonator supply. Han's Laser Technology Group Co., Ltd. occupies the scale-driven end of Asian contract equipment fabrication. These three entities represent the structural poles around which competitive positioning organizes: European vertical integration, North American component supply dominance, and Chinese price-led volume manufacturing.
| Leading Market Players |
|---|
| TRUMPF |
| IPG Photonics Corporation |
| Coherent Corp |
| Han's Laser Technology Group |
| Jenoptik AG |
| Amada Weld Tech |
| Emerson Electric |
| CHIRON Group |
| Precitec |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's industrial decarbonization mandates gate qualified supply access and premium-tier pricing for fiber laser welding equipment, as energy-efficiency certification becomes a non-negotiable procurement filter for German automotive OEMs and battery manufacturers. Buyers without verified solid-state platforms face exclusion from high-volume contracts, compressing margins for legacy CO2 system vendors while concentrating pricing power among certified suppliers.
Pricing Analysis
Volume procurement concentrates at standard-tier fiber laser configurations where Chinese manufacturers in Suzhou compete aggressively, while premium-tier disk laser systems capture margin advantages through German precision engineering heritage. Price differentiation separates CE-marked automated cells from basic enclosure systems, with after-sales service unbundling intensifying cost compression in the mid-market. Korean battery producers drive pricing softness through time-and-materials service arrangements that bypass long-term vendor lock-in.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns for spare parts and field service deployment, with lead times stretching for rare-earth magnet-dependent resonator components. Manufacturing concentrates in Germany, China, and the United States for beam source production, while Japanese and South Korean facilities specialize in precision optics. The supply chain draws from neodymium and dysprosium refining operations concentrated in Chinese processing facilities, creating single-source vulnerability for fiber laser gain medium manufacturing. Distribution runs through OEM-direct channels for automotive tier-one suppliers and integrator networks for job shop fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive diode production and rare-earth magnet supply chain control determine margin sustainability. Players pursuing upstream control over resonator manufacturing gain durable cost advantages against system integrators dependent on external beam source procurement.
For Market Incumbents: Lock in rare-earth magnet supply agreements to insulate fiber laser resonator production from Chinese refining volatility. Deepen backward integration into diode manufacturing to defend margin position against price-led Asian competitors. Accelerate CE marking pre-certification for automated welding cells to compress the 14-18 month conformity assessment timeline that delays revenue recognition.
For New Entrants and Emerging Players: Capture the India automotive supplier base expansion as PLI scheme incentives attract welding equipment investment to Pune and Chennai precision engineering clusters. Target green hydrogen infrastructure fabrication specifications in German and Danish renewable energy supply chains where high-power disk laser demand outpaces established vendor capacity. Deploy remote diagnostics subscriptions as a service-led entry wedge to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: EU AI Act conformity framework finalization is the leading indicator that real-time seam tracking and adaptive process control systems will command premium positioning as mandatory compliance layers. The acquisition target archetype is mid-scale system integrators with established regional service networks but lacking captive beam source production. Long-term viability hinges on positioning for automated welding cell standardization as procurement decisions shift from integrators to source manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Manufacturing | Captive supply of pump diodes insulates TRUMPF and IPG Photonics from input cost volatility. |
| CE Marking Pre-Certification Investment | Early conformity assessment completion compresses time-to-revenue for robotic welding cell deployments. |
| Rare-Earth Magnet Supply Agreements | Long-term offtake contracts with Chinese refiners secure resonator manufacturing continuity. |
| Remote Diagnostics Platform Launch | Subscription revenue streams preserve recurring income independent of hardware margin compression. |
| India Manufacturing Footprint Expansion | Pune and Chennai facilities capture PLI scheme incentives for automotive supplier base growth. |
Research Methodology
Trade association filings, customs import records, and equipment registration databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with plant engineers at German automotive OEMs, procurement leads at Korean battery producers, aftermarket service heads at Chinese equipment manufacturers, and technical R&D directors at beam source suppliers validated demand patterns and technology adoption timelines. Bottom-up unit shipment estimates triangulated against top-down capital expenditure disclosures from major manufacturing clusters.
Historical trendline analysis of fiber laser adoption rates in automotive body-in-white lines established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across beam source architecture, process control mode, application precision requirements, and end-user industry vertical. CAGRs derived from equipment replacement cycle compression and platform standardization dynamics, with EV battery pack assembly specifications and aluminum welding protocol adoption as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply disruptions, EU AI Act implementation timing, and carbon border adjustment mechanism rollout. Forecasts reflect documented assumptions regarding electrification investment continuity and regulatory compliance layering. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Snow Pushers Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Boring Bar Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Tower Crane Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Construction Equipment Rental Market