
 Industrial Hydraulic Equipment Market | 2026-2036
Industrial Hydraulic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hydraulic Equipment Market Outlook
Market Overview
German pump manufacturers are pivoting toward electrified hydraulic architectures for mobile machinery. Bosch Rexroth leverages integrated drive systems to anchor its position in precision motion control. Parker Hannifin sustains manufacturing scale across North American distribution channels. Eaton Corporation Plc competes through fluid power consolidation in energy infrastructure projects.
Industrial hydraulic equipment transmits force through confined fluid to power heavy machinery, typically operating at pressures from 3,000 to 10,000 PSI with mineral oil-based or water-glycol fluids. Hydraulic pumps convert mechanical energy into fluid power, while cylinders and motors transform that energy into linear or rotary motion for lifting, pressing, and propulsion tasks. Variable displacement technology leads product margins due to its energy recovery capabilities in cyclic duty applications. Electro-hydraulic systems represent the fastest-growing technology segment as manufacturers integrate servo valves with digital controls for closed-loop precision.
EPA emissions standards for off-road diesel equipment and the EU F-Gas Regulation on fluorinated greenhouse gases shape hydraulic fluid formulations and system efficiency mandates in North America and Europe. China's GB standards on hydraulic component reliability and India's BIS certification for fluid power equipment govern market access across Asia. Stakeholders must monitor how electrification timelines in construction and agriculture reshape the competitive boundary between pure hydraulic and hybrid electro-mechanical powertrains.
Market Dynamics
Electrification of mobile machinery is compressing the addressable market for traditional hydraulic powertrains while simultaneously creating premium tiers for electro-hydraulic hybrid architectures. Equipment OEMs now specify integrated drive systems that recover energy during deceleration cycles.
Growth Catalysts
- EPA Tier 4 Final emissions mandates:Off-road diesel equipment standards force fleet operators in the US to replace aging hydraulic systems with higher-efficiency variable displacement pumps.
- Construction equipment fleet expansion:Southeast Asian contractors are accelerating hydraulic component procurement ahead of stricter emissions compliance deadlines in Indonesia, Vietnam, and Thailand.
- Energy recovery technology:Regenerative hydraulic circuits in material handling and injection molding applications reduce operating costs by capturing kinetic energy during load lowering.
Market Restraints
- Specialized steel and alloy supply concentration:High-grade cylinder barrel materials face sourcing constraints from concentrated European and Japanese metallurgical suppliers.
- Mineral oil price volatility:Base stock fluctuations for hydraulic fluids compress margin predictability for system integrators and maintenance providers.
- Electromechanical actuator substitution:Linear electric drives displace hydraulic cylinders in precision positioning applications below 50 kN force requirements.
Strategic Opportunities
- India's PLI scheme for capital goods:Production-linked incentives for domestic hydraulic component manufacturing reduce import dependence for construction and mining equipment.
- Remanufacturing services:Circular economy regulations in the EU create aftermarket revenue streams for pump and motor refurbishment.
- Digital hydraulic valve integration:Convergence of servo hydraulics with industrial IoT protocols enables predictive maintenance contracts.
Industry Challenges
- Fluid power engineering talent scarcity:Specialized expertise in hydraulic system design and troubleshooting is retiring faster than vocational programs replenish supply.
- Multi-standard certification complexity:Equipment must simultaneously satisfy ISO 4406 cleanliness codes, EU F-Gas Regulation on sealed systems, and China GB reliability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hydraulic Equipment Market |
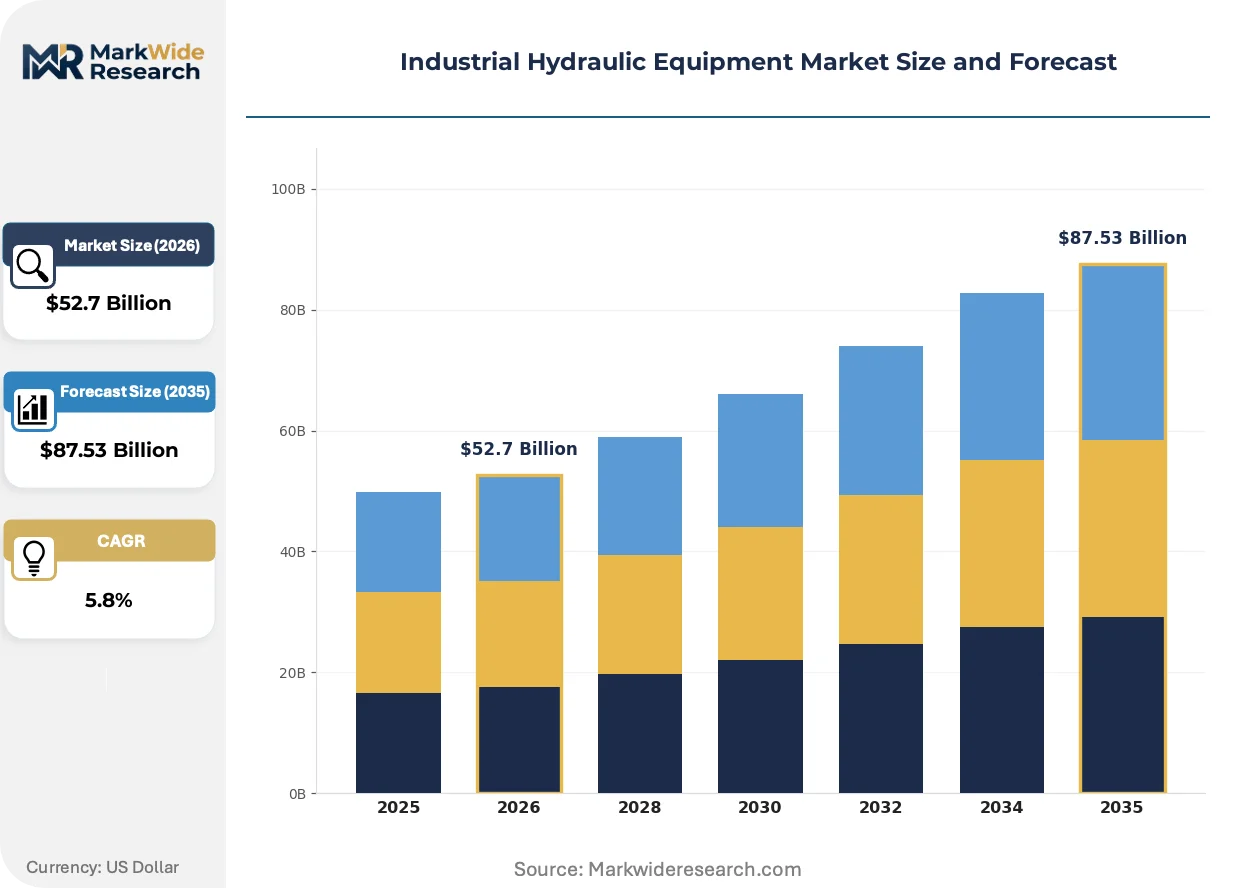
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Hydraulic Cylinders, Hydraulic Motors, Accessories Technology: Direct Drive, Variable Displacement, Electro-Hydraulic, Pneumatic End User: Aerospace, Manufacturing, Construction, Energy Application: Material Handling, Construction Equipment, Agricultural Machinery, Oil & Gas |
| Companies Covered | Kawasaki Heavy Industries, HAWE, Bosch Rexroth, Moog Inc., Hydac, Eaton Corporation Plc, Danfoss A/S, Linde Hydraulics, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hydraulic Equipment Market Strategic Shifts
Digitalization of fluid power systems is rewriting competitive boundaries between component suppliers and motion control integrators. Smart hydraulics now embed sensors and edge computing directly into valves and pumps.
Electro-hydraulic actuation is overtaking conventional proportional valve architectures in precision motion applications. These systems combine high-force hydraulic output with servo-motor responsiveness for closed-loop positioning. Machine tool builders and semiconductor manufacturing equipment OEMs are specifying electro-hydraulic axes for wafer handling and mold positioning. This technology is overtaking legacy servo-pneumatic and pure electromechanical alternatives in force-critical precision segments.
The EU F-Gas Regulation is tightening containment requirements for hydraulic systems using fluorinated greenhouse gas seals and heat transfer fluids. Equipment placed on the European market must demonstrate leak-tightness through enhanced testing protocols. Mobile machinery manufacturers serving EU construction and agriculture sectors are redesigning reservoir and hose connections to eliminate permeation pathways.
Service unbundling is fragmenting traditional distribution relationships in aftermarket hydraulic maintenance. End users now source seals, filters, and diagnostic tools directly from specialized e-commerce platforms rather than authorized distributor networks. This pattern concentrates in North American manufacturing facilities with mature MRO procurement functions and centralized storeroom operations.
Industrial Hydraulic Equipment Market Segmentation
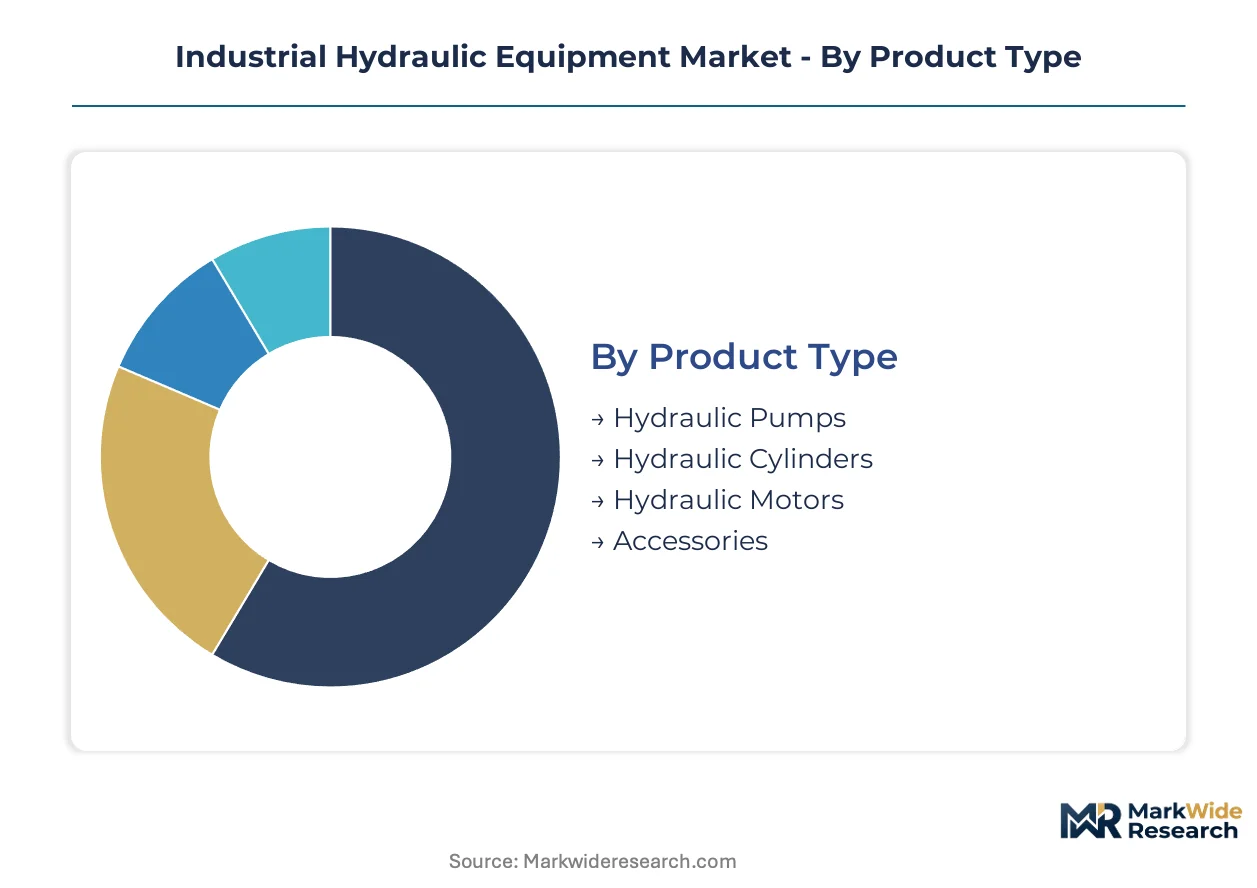
Segmentation in industrial hydraulics reveals divergent capital requirements and margin structures across product architectures. Equipment OEMs configure procurement strategies differently for high-volume standard components versus precision-engineered systems. Understanding these distinctions exposes where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Capital intensity escalates dramatically from accessories through integrated pump-motor assemblies, with cylinder manufacturing demanding specialized honing equipment and alloy forging capabilities that lock in multi-year investment cycles.
- Hydraulic Pumps:Positive displacement units convert mechanical energy to fluid power through gear, vane, or piston architectures. Variable displacement variants command premium positioning in German mobile machinery and Chinese injection molding corridors where energy recovery mandates tighten.
- Hydraulic Cylinders:Linear actuators fabricated from high-strength steel barrel stock with chrome-plated rods deliver force transmission for lifting and pressing operations. Demand clusters in Southeast Asian construction equipment fleets ahead of Indonesia's emissions compliance deadlines.
- Hydraulic Motors:Rotary output devices transform fluid pressure into torque for winch and conveyor drives. Orbital motors dominate agricultural machinery in India's PLI-supported manufacturing zones.
- Accessories:Hoses, fittings, filters, and reservoirs complete system architectures. Standardized SKUs face direct sourcing pressure from North American MRO e-commerce platforms.
Hydraulic pumps absorb the bulk of installed capacity; electro-hydraulic integrated pumps are expanding most quickly.
Technology:
Technology selection maps directly to application precision requirements and energy efficiency mandates, with hybrid architectures commanding development investment from major European and Japanese suppliers.
- Direct Drive:Fixed-displacement pumps deliver constant flow proportional to input speed. These units dominate cost-sensitive Indian construction equipment and legacy agricultural machinery where simplicity outweighs efficiency optimization.
- Variable Displacement:Swashplate or bent-axis designs modulate output flow to match load demand, cutting energy consumption in cyclic duty cycles. Germany's Ecodesign regulations accelerate specification of these units in mobile machinery.
- Electro-Hydraulic:Servo-motor-driven pumps with digital valve control enable closed-loop positioning precision. Machine tool builders around Shanghai and Suzhou specify these for semiconductor wafer handling equipment.
- Pneumatic:Compressed air systems compete in low-force applications below 10 kN. These face displacement by electromechanical alternatives in precision assembly operations.
Variable displacement technology captures the largest share of manufacturing value-add; electro-hydraulic systems show the steepest expansion trajectory.
End User:
End-user concentration determines service intensity and aftermarket attachment rates, with aerospace and energy sectors sustaining premium pricing for certified components.
- Aerospace:Flight control actuation and landing gear systems demand MIL-spec reliability with redundant architectures. FAA certification timelines and specialized alloy requirements create supply scarcity.
- Manufacturing:Presses, injection molding machines, and machine tools require precision motion control. China's industrial automation corridor around Shanghai anchors procurement volume for smart hydraulic axes.
- Construction:Excavators, loaders, and cranes operate under severe duty cycles with high contamination exposure. EPA Tier 4 Final mandates drive US fleet replacement demand for higher-efficiency systems.
- Energy:Offshore drilling and wind turbine maintenance platforms specify corrosion-resistant subsea-rated components. These applications sustain margin premiums through specialized sealing technologies.
Manufacturing end users absorb the bulk of installed capacity; energy sector specifications are gaining share fastest.
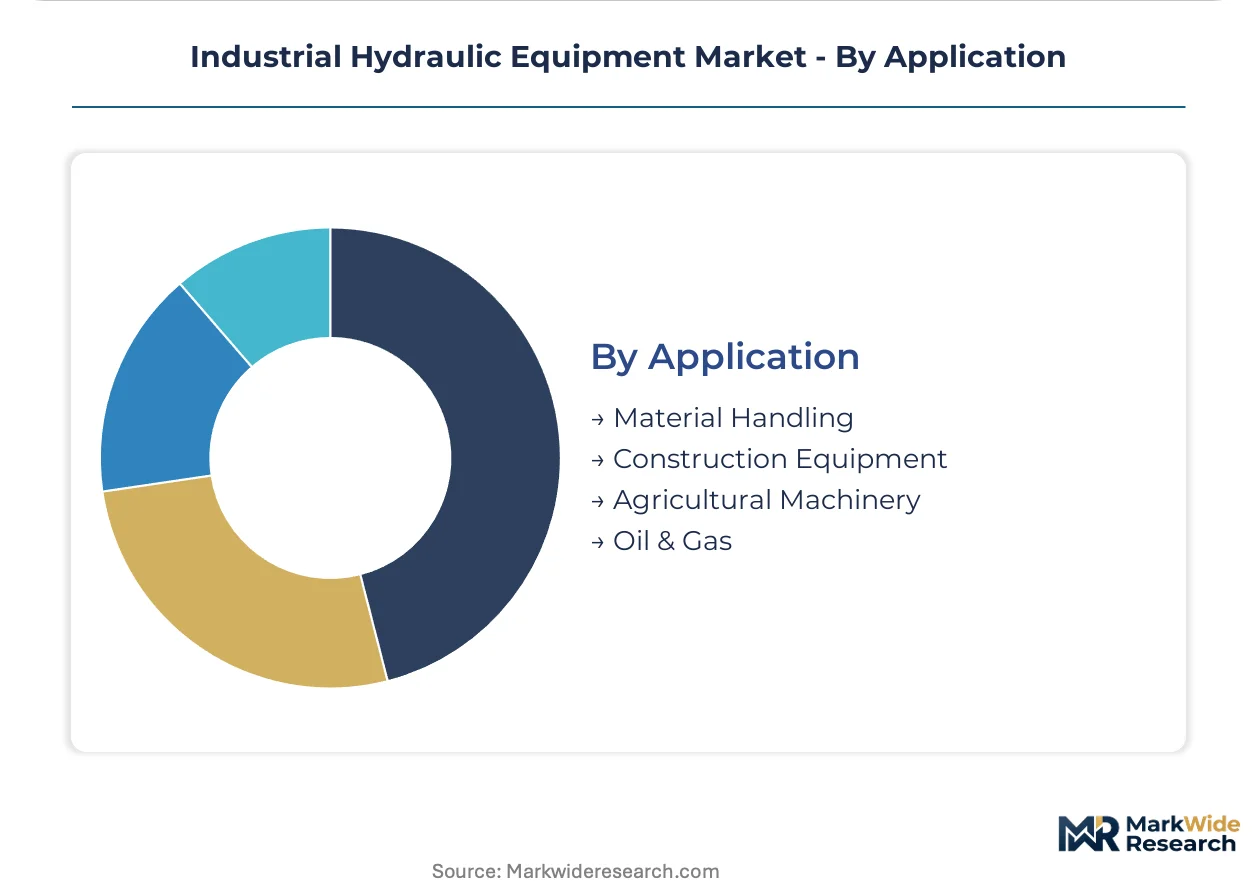
Application:
Application segmentation exposes divergent replacement cycles and fluid contamination tolerance, with outdoor construction equipment requiring more frequent maintenance than enclosed factory installations.
- Material Handling:Forklifts, conveyor systems, and automated storage retrieval equipment deploy hydraulic lifting and positioning. Regenerative circuits in warehouse automation recover energy during load lowering, cutting operating costs in German and Japanese distribution centers.
- Construction Equipment:Earthmoving and lifting machinery operates at pressures exceeding 5,000 PSI in abrasive environments. Southeast Asian contractors accelerate component procurement ahead of Vietnam and Thailand emissions compliance deadlines.
- Agricultural Machinery:Tractors and harvesters specify compact orbital motors for implement control. India's domestic manufacturing incentives reduce import dependence for these applications.
- Oil & Gas:BOP control systems and wellhead actuation require explosion-proof ratings and H2S-resistant materials. These specifications concentrate procurement with certified suppliers serving North Sea and Gulf of Mexico operations.
Construction equipment anchors the largest installed base; material handling applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel alloy supply chains in Düsseldorf and Osaka anchor hydraulic cylinder manufacturing, while fluid power demand clusters around construction corridors in Jakarta and automation hubs near Shanghai.
United States
EPA Tier 4 Final mandates force fleet operators to replace aging hydraulic systems with higher-efficiency variable displacement pumps. The Department of Energy's efficiency standards for industrial equipment tighten procurement specifications for mobile machinery. Construction equipment demand concentrates in Texas and the Southeast, where infrastructure spending accelerates hydraulic component orders ahead of compliance deadlines.
Germany
Ecodesign regulations accelerate specification of energy-efficient pumps in mobile machinery and factory automation. The EU F-Gas Regulation tightens containment requirements for hydraulic systems using fluorinated seals and heat transfer fluids. Manufacturing clusters in Bavaria and Baden-Württemberg anchor development of electrified hydraulic architectures for precision motion control.
China
GB standards on hydraulic component reliability govern market access for domestic and imported equipment. The dual carbon goals drive specification of energy recovery systems in injection molding and machine tool applications. Industrial automation demand clusters around Shanghai and Suzhou, where semiconductor equipment OEMs specify electro-hydraulic axes for wafer handling.
India
The PLI scheme for capital goods reduces import dependence for construction and mining equipment hydraulic components. BIS certification requirements for fluid power equipment create compliance barriers for non-domestic suppliers. Manufacturing activity concentrates in Maharashtra and Gujarat, where domestic orbital motor production expands to serve agricultural machinery demand.
Japan
METI efficiency standards for industrial machinery push adoption of variable displacement technology in cyclic duty applications. JIS certification requirements maintain quality barriers for hydraulic component imports. Precision equipment demand clusters in Nagoya and Osaka, where machine tool builders specify electro-hydraulic systems for mold positioning and semiconductor manufacturing.
Industrial Hydraulic Equipment Market Competitive Environment
Global majors compete with regional champions across technology tiers and geographic coverage. The vendor base separates into consolidated pump and motor specialists, diversified motion control integrators, and regional component fabricators serving single-country construction markets. Three archetypes dominate: German-Japanese precision engineering houses, North American diversified fluid power conglomerates, and emerging Asian specialists in cost-optimized standard components. Competitive moves center on electro-hydraulic technology licensing partnerships and backward integration into specialized alloy forging capabilities.
Among diversified motion control suppliers, Bosch Rexroth and Parker Hannifin exemplify the integrated systems archetype, while Eaton Corporation Plc occupies a position bridging fluid power consolidation with energy infrastructure project exposure. Danfoss A/S and Linde Hydraulics represent the European precision engineering tier, and Kawasaki Heavy Industries anchors the Asian industrial conglomerate model with heavy machinery heritage.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries |
| HAWE |
| Bosch Rexroth |
| Moog Inc. |
| Hydac |
| Eaton Corporation Plc |
| Danfoss A/S |
| Linde Hydraulics |
| Parker Hannifin |
| Others |
Value Chain & Pricing Dynamics
Captive forging of high-grade cylinder barrel steel in Düsseldorf and Osaka anchors supply positions for premium hydraulic component manufacturers, while outsourced seal and hose production in lower-cost geographies enables tiered pricing flexibility across standard and economy product lines. This integration choice concentrates pricing power with alloy-forging specialists who control bottleneck inputs for high-pressure applications.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium electro-hydraulic system pricing from unbundled standard component transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service attachment rates. Cost compression in economy-tier accessories intensifies because direct e-commerce sourcing by North American MRO buyers eliminates distributor markups. Fleet operators in construction and agriculture exhibit highest price sensitivity, while semiconductor equipment OEMs demonstrate lowest sensitivity due to precision requirements.
Supply Chain Analysis
Specialized fluid power engineering talent scarcity in German and Japanese manufacturing clusters constrains capacity expansion for precision pump and motor production. High-grade steel alloying draws from concentrated European and Japanese metallurgical suppliers, while seal compounds and electronic valve controllers source from diversified Asian component networks. Single-source vulnerability in specialized honing equipment for cylinder manufacturing creates supply chain risk. Distribution runs through authorized distributor networks for premium systems, while standard accessories flow through direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA Tier 4 Final and EU F-Gas Regulation create barrier-to-entry moats for certified players capable of meeting multi-standard certification requirements.
For Market Incumbents: Deploy backward integration into specialized alloy forging capabilities to secure cylinder barrel supply positions against Japanese and European metallurgical concentration. Anchor service revenue through predictive maintenance contracts enabled by digital hydraulic valve integration. Electromechanical actuator substitution in sub-50 kN applications threatens traditional cylinder demand in precision positioning segments. For New Entrants and Emerging Players: India's PLI scheme for capital goods opens a window for domestic orbital motor production serving agricultural machinery demand in Maharashtra and Gujarat manufacturing zones. Target remanufacturing services for pump and motor refurbishment under EU circular economy regulations as a low-capital entry point. Establish direct e-commerce distribution for standardized accessories to bypass incumbent distributor networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified motion control conglomerates seeking electro-hydraulic technology capabilities. Long-term viability favors specialists with captive alloy supply and certified positions in energy recovery technology. Watch electrification timelines in construction and agriculture equipment as the inflection signal for hybrid electro-hydraulic versus pure electromechanical powertrain competition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Secures cylinder barrel supply from Düsseldorf and Osaka metallurgical clusters against sourcing constraints. |
| Electro-Hydraulic Technology Licensing | Enables machine tool builders in Shanghai-Suzhou corridor to specify closed-loop positioning systems. |
| Predictive Maintenance Platform Launch | Converges servo hydraulics with industrial IoT protocols for aftermarket service contracts. |
| Remanufacturing Service Expansion | Captures EU circular economy revenue streams for pump and motor refurbishment. |
| PLI-Aligned Manufacturing Scale-Up | Reduces import dependence for construction and mining equipment components in India. |
Study Parameters
Document review covered regulatory filings with EPA, EU ECHA, and China MEE, complemented by interviews with maintenance directors at manufacturing facilities, OEM procurement teams for construction equipment, aftermarket service heads at fluid power distributors, and plant engineers in injection molding and machine tool operations. Secondary validation drew from customs trade data, SEC 10-K disclosures, ISO certification registries, and national industrial production statistics. Bottom-up component demand modeling triangulated against top-down equipment production forecasts.
Historical shipment data cross-referenced against panel input from hydraulic system integrators established baseline demand patterns across the projection horizon. Segmentation modeling incorporated product architecture, technology tier, end-user industry concentration, and application duty cycle intensity. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Energy recovery technology penetration and electrification timeline assumptions shaped scenario-weighted outputs.
The model assumes a particular technology adoption path; alternative pathways for full electromechanical substitution in mobile machinery would alter the outlook for traditional hydraulic powertrain demand. Forecasts reflect assumptions regarding emissions compliance enforcement intensity and alloy supply concentration stability. Material deviation in electrification adoption rates or specialized steel sourcing disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Case Erectors Market
Construction Equipment
Cranes Rental Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
TBR Hydraulic Curing Press Market