
 Backhoe Loaders Market | 2026-2036
Backhoe Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Backhoe Loaders Market Analysis
Municipal infrastructure agencies is unwinding the long-standing dominance of private rental fleets in backhoe procurement. Caterpillar Inc leverages its captive dealer network to sustain aftermarket parts revenue across North American municipal contracts. JCB anchors its position through deep vertical integration into engine and hydraulic component manufacturing. Komatsu competes on telematics integration, differentiating its fleet management offerings from legacy mechanical competitors.
A backhoe loader combines a tractor-like chassis with a front-mounted loading bucket and a rear-mounted excavator arm, typically delivering dig depths of 4.3 to 5.5 meters and breakout forces exceeding 6,000 kgf for trenching and material handling tasks. Standard backhoe loaders occupy the mature volume tier where price competition compresses margins, while electric backhoe loaders represent the fastest-growing technology segment as construction firms face tightening emissions compliance. Medium-size units concentrate demand in urban utility work where maneuverability and lift capacity must balance.
EPA Tier 4 Final standards and the EU F-Gas Regulation shape engine and hydraulic fluid specifications, forcing redesigns of diesel powertrains and accelerating electric platform investment. OSHA excavation safety rules and ISO 5006 visibility standards further dictate cab geometry and camera system requirements. Stakeholders must monitor battery-electric total cost of ownership trajectories against residual value risks in secondary equipment markets.
Market Dynamics
Municipal procurement departments are displacing private rental fleets as the primary volume buyers of backhoe loaders, driven by EPA Tier 4 Final compliance deadlines and dedicated infrastructure funding streams that favor direct ownership over short-term rental.
Growth Catalysts
- EPA Tier 4 Final mandates:Off-road diesel emissions standards are forcing fleet turnover at municipal agencies, creating replacement demand for compliant backhoe loaders across US public works departments.
- India's rural road-building programs:The Pradhan Mantri Gram Sadak Yojana and metro construction in Mumbai, Delhi, and Bangalore are concentrating demand for versatile earthmoving machinery in urban utility and rural connectivity projects.
- Electrification of compact equipment:Battery-electric powertrains are penetrating the sub-100-horsepower segment, opening municipal procurement to zero-emission alternatives that satisfy tightening air quality regulations.
Market Restraints
- Steel and hydraulic component cost volatility:Input price swings for high-strength steel and precision hydraulic valves compress margins for manufacturers without captive supply chains.
- Engine supplier concentration:Diesel powertrain sourcing depends on a narrow base of certified Tier 4 Final engine producers, creating supply risk for non-vertically integrated equipment assemblers.
- Battery-electric residual value uncertainty:Secondary market buyers lack standardized assessment protocols for used electric backhoe loaders, depressing trade-in valuations and lengthening payback calculations.
Strategic Opportunities
- Telematics-enabled fleet management:Komatsu's integrated telematics platform demonstrates how real-time equipment monitoring can shift municipal contracts from unit sales to performance-based service agreements.
- EU F-Gas Regulation compliance:Hydraulic fluid specifications under the F-Gas framework create openings for bio-based alternatives and sealed-system designs that reduce maintenance intervals.
- Urban utility contractor consolidation:Midsize excavation contractors in Germany and France are forming purchasing cooperatives, creating volume channels that bypass traditional dealer networks.
Industry Challenges
- Certified diesel technician shortage:EPA Tier 4 Final aftertreatment systems require specialized diagnostic training that vocational programs have not scaled to match fleet turnover timelines.
- ISO 5006 visibility compliance:Camera system integration and cab redesigns to meet updated visibility standards extend product development cycles and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backhoe Loaders Market |
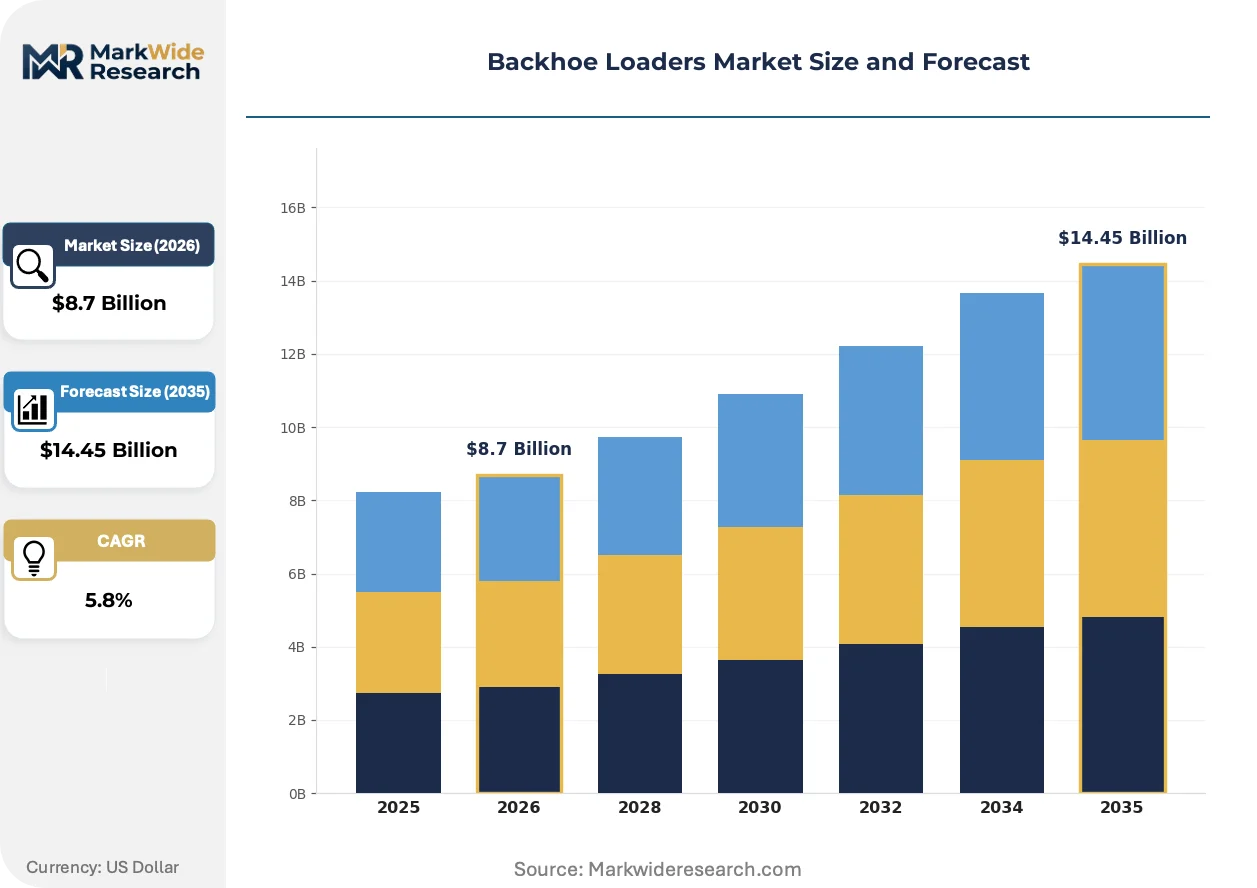
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Backhoe Loaders, Compact Backhoe Loaders, Heavy-Duty Backhoe Loaders, Electric Backhoe Loaders Technology: Hydraulic, Mechanical, Electric, Automated End User: Construction, Agriculture, Mining, Landscaping Size: Small, Medium, Large, Extra Large |
| Companies Covered | Komatsu, CNH Industrial, Caterpillar Inc, HD Hyundai Construction Equipment, Doosan Bobcat, JCB, Volvo Construction Equipment, John Deere, Deere & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backhoe Loaders Market Emerging Trajectories
Equipment electrification is fragmenting the historically unified diesel backhoe loader market into parallel technology tracks, each demanding distinct supply chains, service capabilities, and buyer education.
Battery-electric powertrains is fragmenting the compact equipment segment by creating separate certification, charging infrastructure, and technician training requirements that municipal fleets must navigate alongside conventional diesel procurement. Urban contractors in California and the Netherlands are piloting electric units for noise-restricted sites, but range anxiety and charging downtime limit deployment to fixed-yard operations with predictable duty cycles. This technological bifurcation is compressing economies of scale for mid-size manufacturers that cannot sustain parallel development programs.
The EU F-Gas Regulation is tightening hydraulic fluid specifications and accelerating phase-out of high-global-warming-potential working fluids in European-manufactured equipment. OEMs serving the German, French, and Italian markets are redesigning sealed hydraulic systems to reduce fluid volumes and extend service intervals. Construction firms bidding on public contracts in the EU must now document fluid compliance, shifting competitive advantage to suppliers with certified bio-based alternatives.
Rental fleet operators are unbundling maintenance contracts from equipment leases, forcing manufacturers to compete for aftermarket service revenue separately from original equipment sales. Municipal agencies in Texas and Florida are piloting this model, separating capital procurement from operating budgets through third-party maintenance agreements. This disintermediation pressures dealer networks to transform from sales channels to service platforms, with JCB's captive parts distribution demonstrating one defensive response.
Backhoe Loaders Market Segmentation
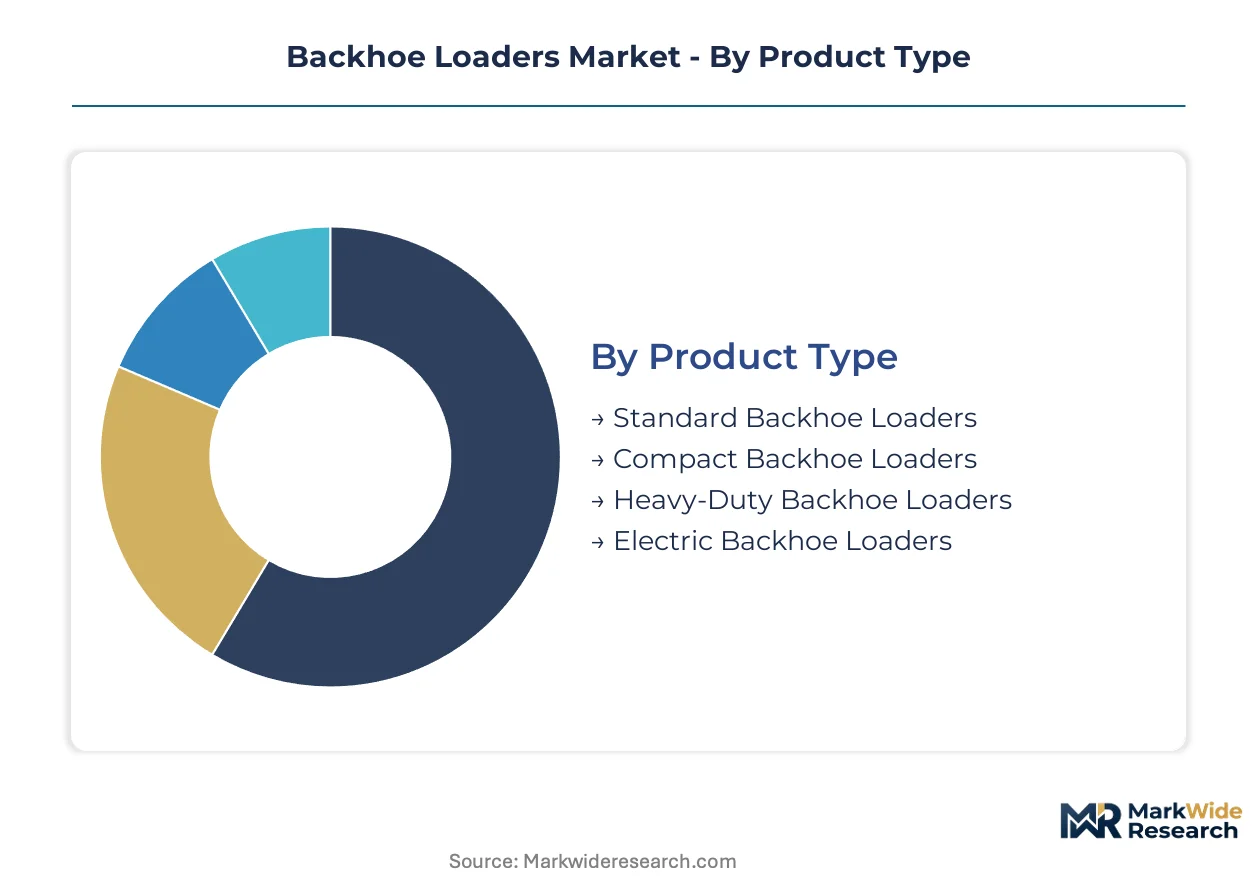
Segmentation in backhoe loaders determines procurement eligibility for municipal contracts and shapes manufacturer R&D allocation across powertrain technologies. EPA Tier 4 Final compliance deadlines and electrification roadmaps force buyers to match equipment specifications precisely to project duration, site constraints, and total cost of ownership calculations.
Product Type:
EPA Tier 4 Final and EU F-Gas Regulation differentiate equipment categories through emissions certification requirements and hydraulic fluid specifications, creating parallel procurement tracks for diesel and electric platforms.
- Standard Backhoe Loaders:Diesel-powered units with dig depths of 4.3 to 5.5 meters and breakout forces exceeding 6,000 kgf dominate municipal road maintenance and utility trenching in India and the United States. Price competition compresses margins where rental fleet operators and direct municipal procurement overlap.
- Electric Backhoe Loaders:Battery-electric powertrains in the sub-100-horsepower segment satisfy zero-emission mandates for urban construction sites in California and the Netherlands. Charging infrastructure requirements and range anxiety restrict deployment to fixed-yard operations with predictable duty cycles.
- Compact Backhoe Loaders:Maneuverable units prioritize urban utility work where site access limits equipment dimensions.
- Heavy-Duty Backhoe Loaders:High-capacity specifications serve mining and large-scale earthmoving where breakout force requirements exceed standard ratings.
Established volume favors Standard Backhoe Loaders; emerging adoption favors Electric Backhoe Loaders.
Technology:
Cost tier stratification separates premium telematics-integrated systems from mechanical alternatives, with price gaps widening as digital fleet management becomes a contract differentiator.
- Hydraulic:Precision valve systems and sealed designs reduce fluid volumes to comply with EU F-Gas Regulation specifications. German and French OEMs are redesigning architectures to extend service intervals and document fluid compliance for public tenders.
- Electric:Battery-electric powertrains eliminate diesel aftertreatment complexity but introduce new failure modes in thermal management and charging connector durability. Municipal fleets in California pilot these for noise-restricted sites.
- Mechanical:Simpler linkages persist in price-sensitive markets where technician training infrastructure lags Tier 4 Final diagnostic requirements.
- Automated:Semi-autonomous grading and trenching functions integrate with Komatsu's telematics platform for performance-based service agreements.
Mechanical systems retain share in cost-constrained procurement; Electric and Automated platforms are gaining share fastest in premium municipal contracts.
End User:
Application-specific duty cycles determine equipment specification, with construction and agriculture presenting divergent utilization patterns and resale value trajectories.
- Construction:Urban utility contractors and municipal public works departments drive replacement demand amid EPA Tier 4 Final fleet turnover deadlines. India's Pradhan Mantri Gram Sadak Yojana and metro projects in Mumbai, Delhi, and Bangalore concentrate volume.
- Agriculture:Seasonal utilization patterns and lower annual hours depress residual values, favoring rental over ownership in North American markets.
- Mining:Continuous-duty operations prioritize reliability metrics and captive maintenance capabilities over upfront capital cost.
- Landscaping:Noise restrictions and site sensitivity in residential zones create niche demand for electric alternatives in California and the Netherlands.
Construction commands the dominant procurement volume; Landscaping presents the steepest expansion trajectory for electrified equipment.
Size:
Customer type segmentation separates municipal fleet standardization from contractor equipment diversification, with medium units serving as the procurement default for mixed-use applications.
- Medium:Balanced maneuverability and lift capacity serve urban utility work where trenching depth requirements meet street-width constraints. Municipal agencies in Texas and Florida standardize on this tier for fleet interoperability.
- Small:Compact dimensions enable residential landscaping and confined-site utility repair where larger equipment cannot access.
- Large:Extended reach and breakout force specifications serve highway construction and mining overburden removal.
- Extra Large:Specialized high-capacity units address quarry and mass excavation projects with limited unit volume.
Medium units anchor municipal standardization; Small sizes are climbing fastest as urban site constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Quadrilateral highway network underwrites India's centrality to backhoe loader demand, while Germany's Rhine-Alpine rail corridor anchors European equipment specification standards. Municipal procurement patterns diverge sharply across these infrastructure backbones.
United States
Texas municipal fleets and Florida public works departments drive replacement demand amid EPA Tier 4 Final compliance deadlines. The federal Infrastructure Investment and Jobs Act channels dedicated funding toward direct equipment ownership rather than rental. Dallas-Fort Worth metro contractors concentrate volume for urban utility trenching projects.
India
The Pradhan Mantri Gram Sadak Yojana rural road program and metro construction in Mumbai, Delhi, and Bangalore concentrate demand for versatile earthmoving machinery. BIS certification requirements shape equipment specifications for domestic procurement. Maharashtra's construction clusters anchor manufacturing and distribution networks serving western India.
Germany
The EU F-Gas Regulation tightens hydraulic fluid specifications for equipment serving public tenders across Bavaria and North Rhine-Westphalia. KBA-type approval processes for off-road machinery extend product development cycles. Stuttgart's industrial corridor hosts engineering centers redesigning sealed hydraulic systems.
Netherlands
Urban contractors in Amsterdam and Rotterdam pilot battery-electric units for noise-restricted construction sites under municipal zero-emission mandates. The country's national environmental regulator enforces air quality standards that accelerate electrification roadmaps. Randstad metropolitan infrastructure projects specify compact equipment for constrained site access.
China
Dual carbon goals and MEE emissions standards force diesel fleet turnover in Yangtze River Delta construction markets. GB standards for off-road machinery dictate powertrain certification requirements. Shanghai's metro expansion and port infrastructure projects sustain demand for high-capacity earthmoving equipment.
Backhoe Loaders Market Vendor Landscape
Concentration sits with diversified heavy equipment conglomerates that leverage captive component manufacturing and telematics platforms. Three strategic archetypes define competitive positioning: vertically integrated engine producers, telematics-integrated fleet managers, and regional specialists serving price-sensitive procurement. Capacity expansion and strategic partnerships dominate competitive moves, with manufacturers securing battery supply agreements and charging infrastructure consortia for electrified portfolios.
Within the diversified conglomerate tier, Caterpillar Inc and Komatsu exemplify scale-driven positioning, while JCB occupies a distinct position through in-house production of powertrain and hydraulic components. These three anchors demonstrate how backward integration into critical subsystems defends margin position against input cost volatility. Regional specialists including Doosan Bobcat and HD Hyundai Construction Equipment serve distinct geographic procurement patterns without replicating full vertical integration.
| Leading Market Players |
|---|
| Komatsu |
| CNH Industrial |
| Caterpillar Inc |
| HD Hyundai Construction Equipment |
| Doosan Bobcat |
| JCB |
| Volvo Construction Equipment |
| John Deere |
| Deere & Company |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification gates both supplier qualification and price tiering simultaneously, restricting engine sourcing to certified producers while creating compliance-cost premiums that stratify municipal procurement budgets from rental fleet economics. Steel and hydraulic component volatility feeds directly into margin compression for assemblers without captive supply, forcing pricing discipline that favors backward-integrated manufacturers.
Pricing Analysis
Volume-discount tiering separates municipal fleet procurement from spot rental transactions, with Texas and Florida public works departments leveraging multi-unit commitments against per-machine spot rates. Price differentiation hinges on EPA Tier 4 Final compliance certification and telematics integration depth, where Komatsu's fleet management platform commands premiums over mechanical alternatives. Cost compression in the standard diesel tier intensifies as Indian rural road programs concentrate volume demand. Rental fleet operators exhibit highest price sensitivity; mining contractors with continuous-duty requirements show lowest.
Supply Chain Analysis
Just-in-time component flows dominate hydraulic valve sourcing from German and Japanese precision manufacturers, while strategic stockpiling of high-strength steel persists among vertically integrated OEMs buffering against commodity swings. Manufacturing concentration centers on India, China, and Germany, with Maharashtra construction clusters and Yangtze River Delta facilities anchoring regional supply. Diesel powertrain sourcing draws from a narrow certified base, creating single-source vulnerability for Tier 4 Final aftertreatment systems. Distribution runs through captive dealer networks for aftermarket parts revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation across Texas and Florida public works departments is shifting buyer power toward direct ownership models, fragmenting traditional rental fleet dominance.
For Market Incumbents: Consolidate captive component manufacturing to defend margins against steel and hydraulic input volatility. Deepen telematics platform investment to shift municipal contracts from unit sales toward performance-based service agreements, neutralizing price pressure from emerging electric entrants. For New Entrants and Emerging Players: Lead with battery-electric platforms targeting California and Netherlands urban contractors facing noise-restricted site mandates. The landscaping segment presents the most penetrable white space, with charging infrastructure partnerships offering differentiated go-to-market positioning against established diesel incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core construction equipment portfolios. Long-term viability hinges on electrification roadmap execution; monitor battery supply agreement announcements as inflection indicators for platform readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell capacity for electric platform scaling against constrained supplier base. |
| Telematics Platform Integration | Enables Komatsu-style performance-based contracts shifting revenue from sales to services. |
| Backward Integration into Hydraulics | Mirrors JCB's sealed-system designs reducing EU F-Gas compliance costs and service intervals. |
| Charging Infrastructure Partnership | Addresses range anxiety barriers limiting electric deployment to fixed-yard municipal operations. |
| Certified Technician Training Program | Closes EPA Tier 4 Final diagnostic skills gap constraining fleet turnover timelines. |
Methodological Framework
Desk research of customs trade databases, EPA certification filings, and BIS equipment standards preceded structured interviews with municipal fleet managers, OEM procurement directors, aftermarket service heads, and rental fleet operators. Primary fieldwork across Texas, Florida, Maharashtra, and Bavaria construction clusters combined with secondary validation from equipment registration data and infrastructure project disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing from industry association reports.
Variance decomposition across product type, powertrain technology, end-use application, and regional procurement patterns shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand curves incorporating EPA Tier 4 Final fleet turnover timelines and India's Pradhan Mantri Gram Sadak Yojana project pipelines. Electric platform adoption curves calibrated against Netherlands and California municipal zero-emission mandate compliance schedules.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure funding authorization or battery cost trajectories would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity input stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Dock Door Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Construction Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Walform Machines Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Portable Rebar Bending Machine Market