
 Self-Drilling Screws Market | 2026-2036
Self-Drilling Screws Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Drilling Screws Market Analytics
Light commercial contractors is reorganizing demand patterns across the self-drilling screws landscape, displacing traditional residential builders as the primary volume purchaser. Hilti Corporation leverages its direct-to-contractor distribution model to sustain premium positioning in structural fastening systems. ITW Construction Products anchors North American supply through its specialized construction channel partnerships. Würth Group competes via dense local branch networks that control last-mile delivery for maintenance and repair operations.
Self-drilling screws integrate hardened drill-bit points with threaded shanks to penetrate metal substrates without pre-drilling, typically manufactured from case-hardened carbon steel or 410 martensitic stainless steel with Rockwell hardness exceeding 50 HRC for point durability. Hex washer head variants dominate commercial construction applications due to superior torque transfer and weather sealing against metal roof panels. Stainless steel material grades command margin premiums in coastal and chemical-exposure environments where galvanized coatings degrade prematurely. PTFE-coated products represent the fastest-growing coating segment, reducing thread friction during high-speed automated installation in automotive assembly and appliance manufacturing.
Federal construction projects in the United States fall under Buy America provisions administered by the Office of Management and Budget, mandating domestic steel content verification that reshapes supplier qualification requirements. The EU Construction Products Regulation enforces CE marking and declared performance under harmonized EN standards for structural fasteners used in load-bearing metal connections. ASTM A510 and ISO 898-1 mechanical property specifications govern tensile strength and ductility classifications that determine product eligibility for engineered building permits. Stakeholders must monitor evolving low-carbon procurement mandates from public infrastructure agencies that will soon require environmental product declarations alongside traditional mechanical certifications.
Market Dynamics
Prefabricated steel construction methods are consolidating procurement authority into specialized contractor networks, compressing traditional distribution layers and elevating specification power toward direct manufacturer relationships.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Building material procurement rules in Germany, France, and the Netherlands now prioritize low-carbon steel formulations and recyclable coating systems for public infrastructure fasteners.
- Automated high-speed assembly lines:Appliance manufacturers and automotive OEMs are specifying PTFE-coated self-drilling screws to reduce thread friction and eliminate pre-assembly lubrication steps.
- Coastal corrosion environments:410 martensitic stainless steel grades with Rockwell hardness exceeding 50 HRC are displacing galvanized carbon steel in marine-adjacent metal roofing installations across Florida and the Gulf Coast.
Market Restraints
- Case-hardened carbon steel input volatility:Scrap metal pricing fluctuations and electric arc furnace capacity constraints in North America create margin compression for mid-tier fastener producers.
- Buy America domestic content verification:Federal construction projects administered by the Office of Management and Budget require steel origin documentation that disqualifies imported substrate materials from qualified supplier lists.
- Hex head torque limitation:Structural fastening in heavy-gauge structural steel applications requires alternative drive systems when standard hex washer heads cannot achieve specified clamp loads.
Strategic Opportunities
- India prefabricated construction acceleration:BIS certification alignment with EN standards for structural fasteners opens specification pathways for CE-marked manufacturers in commercial and industrial building segments.
- Environmental product declaration integration:Public infrastructure agencies in Germany and Austria are mandating EPD documentation alongside mechanical certifications, creating first-mover advantage for verified low-carbon producers.
- Last-mile maintenance networks:Dense local branch configurations for MRO supply are capturing recurring revenue streams from facility management contractors responsible for metal cladding repair cycles.
Industry Challenges
- CE marking harmonization delays:EN 14592 timber-to-metal and EN 14566 metal-to-metal declared performance categories require separate testing protocols that extend product qualification timelines.
- Rockwell hardness consistency:Case-hardening process control for drill-bit points demands capital-intensive heat treatment monitoring systems to prevent point fracture in automated installation environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Drilling Screws Market |
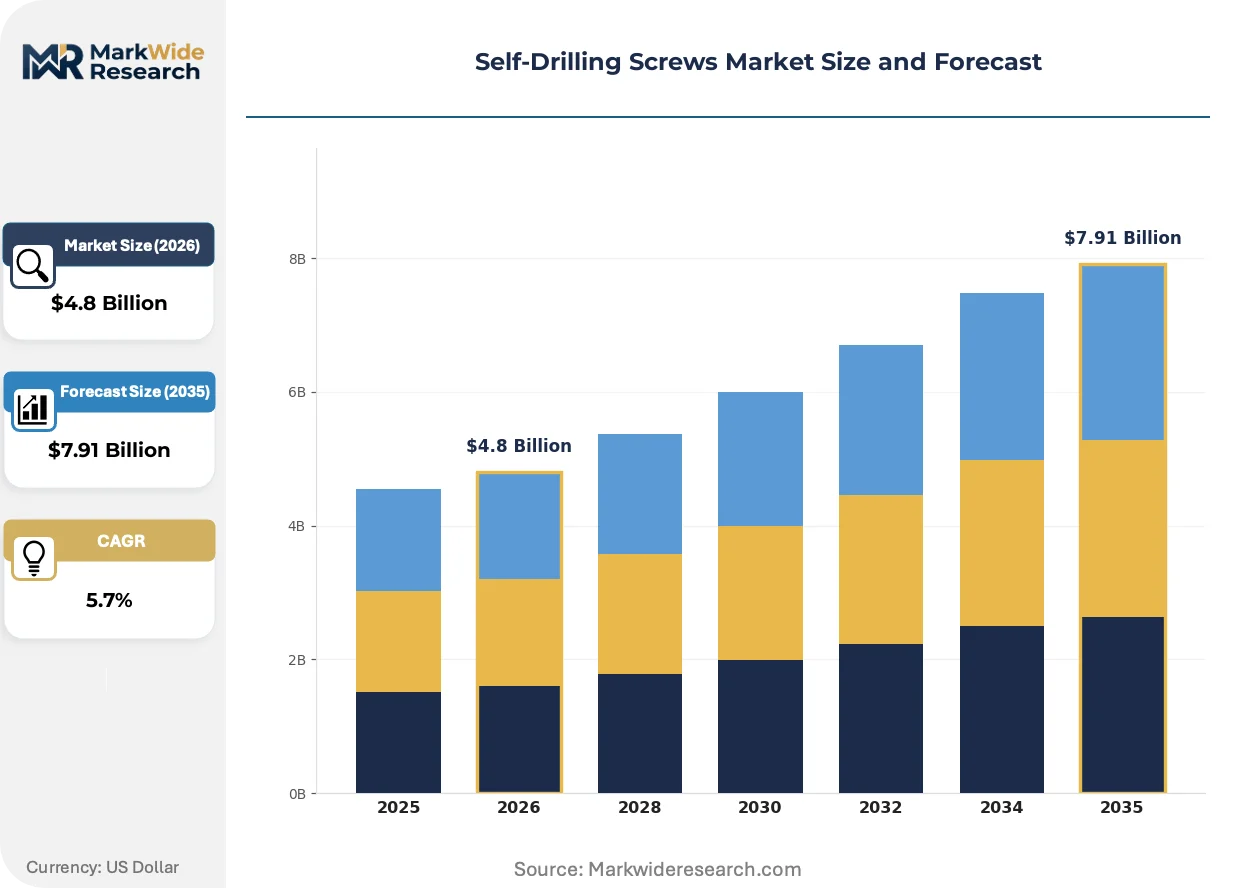
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hex Washer Head, Pan Head, Round Head, Truss Head Material: Steel, Stainless Steel, Aluminum, Titanium Coating Type: Galvanized, Black Oxide, Zinc Plated, PTFE Coated Application: Construction, Automotive, Furniture, Electrical |
| Companies Covered | Hilti Corporation, ITW Construction Products, Fastenal Company, Simpson Strong-Tie Company, Inc., Würth Group, SFS Group, EJOT, Dewalt, Adolf Würth GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Drilling Screws Market Evolving Landscape
Coating chemistry and substrate metallurgy are converging to extend service life in aggressive environments while installation automation drives geometric standardization across regional product lines.
PTFE fluoropolymer coatings are displacing zinc-aluminum and organic polymer alternatives in high-volume automated assembly applications. Appliance manufacturers specify these formulations to eliminate thread galling at installation speeds exceeding 2,500 RPM. The coating migration is compressing price premiums toward parity with conventional galvanized products within three years.
REACH authorization requirements for hexavalent chromium compounds are forcing coating reformulation across European supply chains. Manufacturers serving Germany and Benelux markets have accelerated trivalent chromium and cerium-based passivation development. The regulatory pressure is elevating R&D allocation toward chrome-free alternatives that maintain 1,000-hour salt spray performance.
Direct contractor procurement platforms are consolidating specification authority away from traditional distributor intermediaries. Light commercial roofing contractors in Germany and industrial builders in the US Gulf Coast now issue blanket orders tied to project portfolios rather than spot purchasing. The channel compression is visible most acutely in maintenance and repair segments where inventory carrying costs drive buyers toward vendor-managed stock programs.
Self-Drilling Screws Market Segmentation
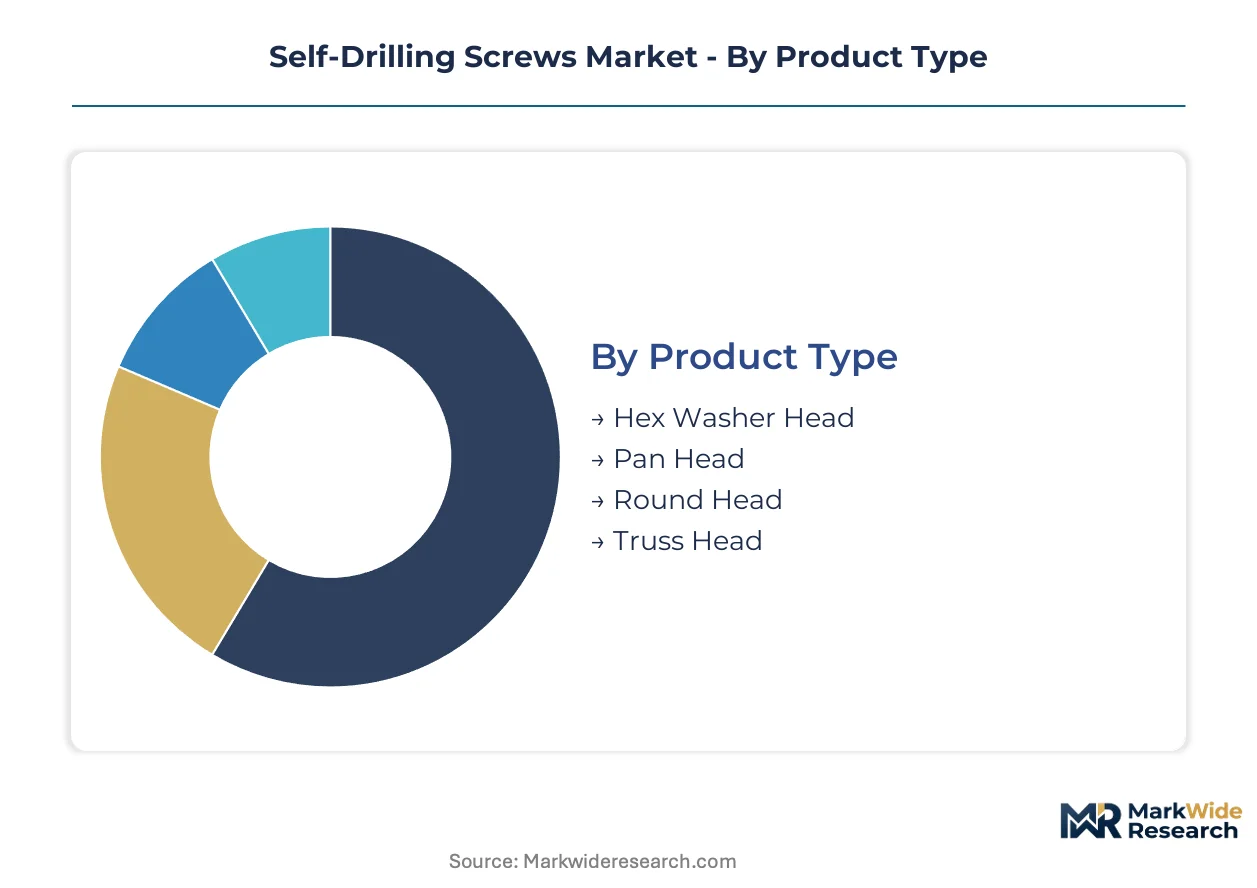
Self-drilling screws demand fragments across four intersecting dimensions where product specification, material grade, and surface treatment each trigger distinct channel pathways and margin profiles. Procurement patterns diverge sharply between structural construction contractors sourcing through direct manufacturer relationships and industrial assemblers purchasing via specialized distribution.
Product Type:
Channel concentration varies by head geometry, with commercial roofing contractors driving volume through specialized construction distributors while furniture and appliance manufacturers source pan and round variants through industrial supply houses.
- Hex Washer Head:Integrates an integrated washer flange for weather sealing and torque distribution across metal roofing panels. Demand concentrates in Germany and the US Gulf Coast where prefabricated steel construction methods dominate commercial building activity and contractors specify hardened points for 18-24 gauge substrates.
- Pan Head:Features a low-profile cylindrical crown with vertical sides for flush seating in thin-gauge materials. Appliance manufacturers in automated assembly environments specify this geometry for cabinet and frame fastening where clearance constraints limit protrusion.
- Round Head:Dome-shaped crown provides decorative finish concealment in visible applications. Furniture producers specify these for exposed joinery where aesthetic integration matters.
- Truss Head:Extra-wide low-profile head distributes clamping load across soft or brittle substrates without surface penetration. Electrical enclosure manufacturers favor this geometry for plastic and composite panel fastening.
By volume, Hex Washer Head leads. By growth pace, Pan Head is ahead.
Material:
Cost tier stratification separates commodity carbon steel from corrosion-resistant alloys, with specification authority shifting toward engineering teams in coastal and chemical-exposure environments.
- Steel:Case-hardened carbon steel formulations dominate procurement economics for interior and dry-environment applications. Galvanized and zinc-plated variants capture standard construction segments where atmospheric corrosion exposure remains limited.
- Stainless Steel:410 martensitic grades with Rockwell hardness exceeding 50 HRC command margin premiums in Florida marine environments and Gulf Coast chemical processing facilities where galvanized coatings degrade prematurely. CE marking requirements under EN 14566 govern structural eligibility.
- Aluminum:Lightweight substrates prevent galvanic corrosion when fastening dissimilar metals. Aerospace and transportation equipment manufacturers specify these for weight-sensitive assemblies.
- Titanium:Exceptional strength-to-weight ratio serves specialized medical device and high-performance sporting equipment applications where material cost is secondary to performance.
Steel captures the volume base. Stainless steel is climbing the fastest on specification upgrades.
Coating Type:
Application environment dictates coating selection, with automated assembly lines driving chemistry innovation while outdoor exposure requirements sustain conventional metallic protection.
- Galvanized:Zinc layer deposition through hot-dip or electroplating processes provides sacrificial corrosion protection for standard construction applications. German and Benelux markets face REACH-driven reformulation pressure.
- Black Oxide:Conversion coating creates decorative matte finish with minimal dimensional change. Tool and equipment manufacturers specify these for internal components where corrosion exposure is negligible.
- Zinc Plated:Electrodeposited zinc with chromate passivation offers economical protection for indoor and low-corrosion environments. Automotive underbody applications sustain demand despite hexavalent chromium regulatory pressure.
- PTFE Coated:Fluoropolymer layer reduces thread friction coefficients below 0.05 for high-speed automated installation exceeding 2,500 RPM. Appliance and automotive OEMs specify these to eliminate pre-assembly lubrication steps.
Galvanized holds the volume position. PTFE coating is gaining share fastest on automation trends.
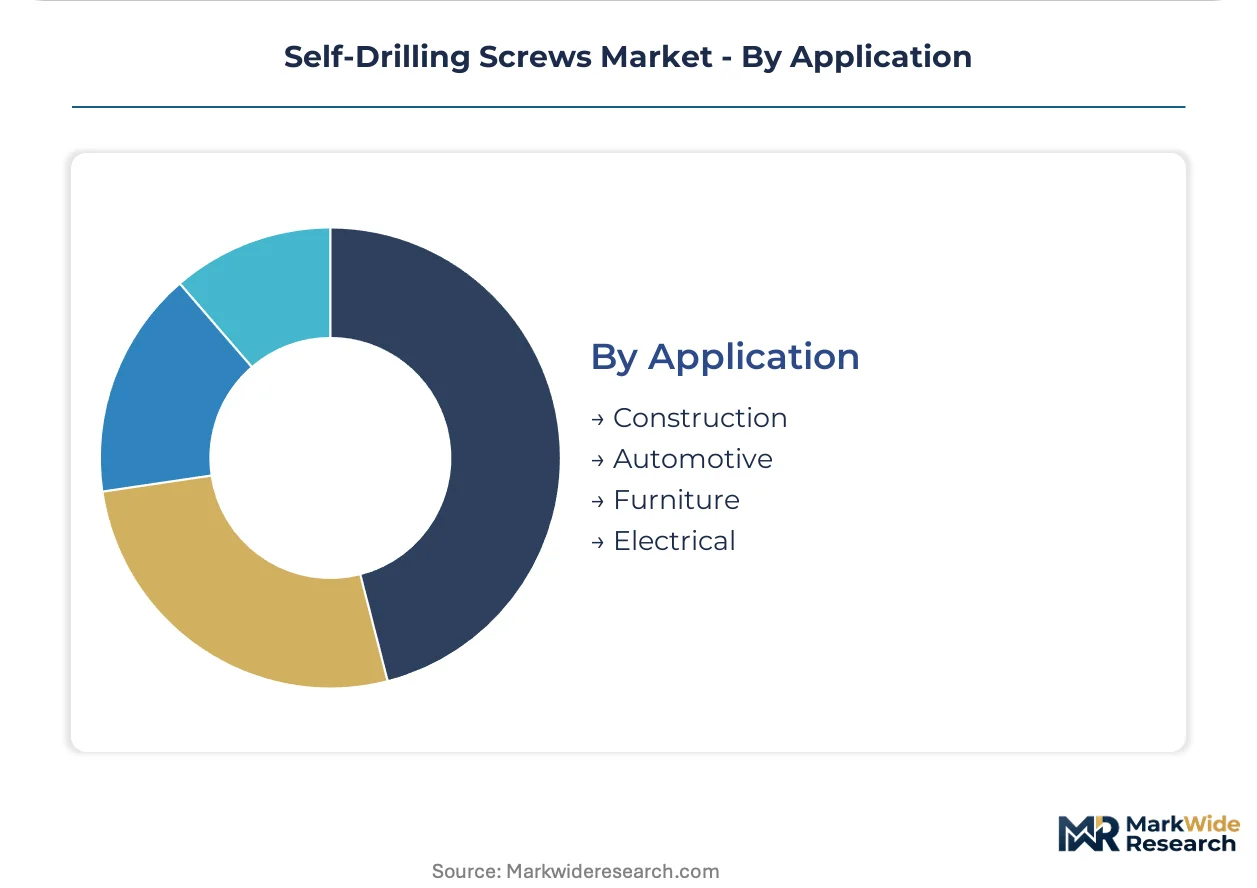
Application:
Customer type fragmentation separates project-based construction procurement from repetitive manufacturing consumption, with inventory velocity and specification stability diverging accordingly.
- Construction:Metal roofing and cladding assembly drives specification for hardened drill points and weather-resistant head geometries. German prefabricated steel methods and US light commercial contractors consolidate procurement authority into specialized networks.
- Automotive:Body-in-white and chassis assembly lines specify PTFE-coated variants for friction reduction. OEM qualification protocols demand extensive validation testing before supplier approval.
- Furniture:Metal frame and cabinet manufacturers prioritize cost efficiency and aesthetic concealment. Pan and round head variants dominate this segment.
- Electrical:Enclosure and panelboard assembly requires grounding continuity and non-conductive finish options. Truss head geometries distribute clamping load across thin-gauge housings.
Construction leads by volume. Automotive is expanding most quickly on coating specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export case-hardened carbon steel fasteners to prefabricated construction sites across the Benelux region. This trade corridor channels specification-grade products toward Dutch and Belgian light commercial contractors.
United States
Light commercial roofing contractors in Florida and the Gulf Coast specify 410 martensitic stainless steel grades for marine-adjacent metal cladding. Buy America provisions administered by the Office of Management and Budget mandate domestic steel content verification for federal infrastructure projects. Houston and Miami industrial clusters concentrate procurement authority among specialized contractor networks serving petrochemical and coastal developments.
Germany
Prefabricated steel construction methods dominate commercial building activity across North Rhine-Westphalia and Bavaria. EU Green Deal embodied carbon requirements push manufacturers toward low-carbon steel formulations and recyclable coating systems. Stuttgart and Düsseldorf engineering clusters drive specification authority toward direct manufacturer relationships for structural fastening systems.
China
Appliance manufacturers in the Yangtze River Delta specify PTFE-coated variants for high-speed automated assembly lines exceeding 2,500 RPM. GB standards and MIIT industrial policy govern mechanical property certifications for structural fasteners. Shanghai and Suzhou manufacturing clusters integrate coating chemistry innovation with export-oriented production for automotive OEM supply chains.
India
BIS certification alignment with EN standards opens specification pathways for CE-marked manufacturers in commercial and industrial building segments. Maharashtra and Gujarat construction authorities enforce structural fastener compliance for prefabricated steel frameworks. Mumbai and Ahmedabad industrial corridors concentrate demand from facility management contractors responsible for metal cladding maintenance cycles.
Netherlands
REACH authorization requirements for hexavalent chromium compounds force coating reformulation across Dutch supply chains serving German export markets. ECHA regulatory pressure elevates R&D allocation toward chrome-free alternatives that maintain salt spray performance. Rotterdam logistics clusters facilitate last-mile distribution for maintenance and repair operations across the Rhine-Ruhr industrial region.
Self-Drilling Screws Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive distribution networks. The vendor base concentrates around construction-focused specialists and broad-line fastener manufacturers with regional density advantages. Three archetypes dominate: premium structural systems providers, volume construction distributors, and industrial supply houses with automated assembly expertise. Competitive moves center on direct contractor platform development and coating chemistry differentiation for corrosion-resistant specifications.
Among European-based specialists, Hilti Corporation, Würth Group, and EJOT exemplify divergent channel strategies. Hilti represents the premium-tier direct-to-contractor model with specification authority concentrated in structural applications. Würth occupies a position anchored in dense local branch networks controlling last-mile delivery for maintenance operations. EJOT sits within the engineering-specialist tier, serving automated assembly requirements across appliance and automotive OEM qualification protocols.
| Leading Market Players |
|---|
| Hilti Corporation |
| ITW Construction Products |
| Fastenal Company |
| Simpson Strong-Tie Company, Inc. |
| Würth Group |
| SFS Group |
| EJOT |
| Dewalt |
| Adolf Würth GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Sixty-day order-to-delivery cycles for case-hardened carbon steel substrates concentrate pricing leverage among German and Chinese mill operators with captive heat treatment capacity, compressing margin buffers for mid-tier fastener producers dependent on spot scrap metal purchases.
Pricing Analysis
PTFE-coated next-generation variants command 15-20% premiums over galvanized current-generation products, while uncoated economy-grade carbon steel anchors the price floor. Three-tier pricing structure across premium stainless steel, standard case-hardened, and economy-grade carbon steel tiers differentiates by corrosion resistance certification and Rockwell hardness consistency. Cost compression in standard galvanized segments is intensifying because electric arc furnace capacity constraints in North America elevate scrap input costs. Light commercial roofing contractors exhibit highest price sensitivity due to project-bid procurement economics, while automotive OEMs prioritize friction-reduction performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of 410 martensitic stainless steel rod stock dominates coastal contractor procurement, contrasting with just-in-timed case-hardened carbon steel flows to interior construction markets. Manufacturing gravity centers on Germany, China, and India, with German producers exporting specification-grade fasteners to Benelux prefabricated construction sites. Raw material feeds draw from electric arc furnace steel mills, zinc coating chemical suppliers, and fluoropolymer resin producers. Tariff exposure on Chinese-origin substrate materials creates qualification risk for suppliers serving US federal projects. Distribution runs through specialized construction distributors with direct-to-contractor platforms capturing specification authority from traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as prefabricated steel construction methods displace conventional building approaches across German and US Gulf Coast commercial development.
For Market Incumbents: Fortify specification-grade positioning by deepening captive heat treatment capacity for Rockwell hardness consistency above 50 HRC, while accelerating chrome-free coating R&D to preempt REACH-driven formulation obsolescence. Channel control through vendor-managed inventory programs defends against direct-to-contractor platform encroachment from specialized distributors. For New Entrants and Emerging Players: Last-mile maintenance network density in India's Maharashtra and Gujarat industrial corridors offers white-space opportunity where incumbent branch coverage remains thin. Target facility management contractors responsible for metal cladding repair cycles with BIS-certified structural fastener portfolios aligned to EN performance standards. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because prefabricated construction procurement authority is compressing traditional distribution layers toward direct manufacturer relationships. Acquisition candidates with CE-marked product portfolios and established automotive OEM qualification protocols capture cross-segment specification leverage. Monitor EU Green Deal low-carbon steel procurement mandate adoption rates across German federal infrastructure agencies as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive Rockwell hardness monitoring secures automated installation qualification for automotive OEM supply chains. |
| Chrome-Free Coating Development | REACH-compliant trivalent chromium and cerium-based passivation maintains 1,000-hour salt spray performance for German export markets. |
| Direct-to-Contractor Platform Launch | Blanket order portfolios tied to light commercial roofing projects displace spot purchasing through traditional distributors. |
| Environmental Product Declaration Certification | EPD documentation alongside mechanical certifications unlocks German and Austrian public infrastructure procurement mandates. |
| India BIS-EN Alignment Investment | Certification harmonization opens specification pathways for CE-marked manufacturers in prefabricated steel construction segments. |
Research Methodology
A spread of perspectives from fastener procurement managers at light commercial contractors, coating chemistry R&D directors, prefabricated steel construction engineering leads, and specialized distribution channel heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC 10-K filings of diversified industrial conglomerates, BIS and CE marking registration databases, and EU Construction Products Regulation harmonized standards documentation. Bottom-up demand modeling across application segments triangulated with top-down steel consumption correlations.
Segmentation dimensions modeled include head geometry variants, material grade tiers, coating chemistry categories, and end-use application clusters across the projection horizon. CAGRs derive from volume-weighted growth rates applied to each segment's baseline consumption, with cross-validation against electric arc furnace steel capacity expansion schedules and prefabricated construction adoption curves in key regional markets.
Forecasts assume regulatory continuity in EU Green Deal embodied carbon mandates and US Buy America domestic content verification; material policy shifts would require re-modeling of supplier qualification pathways and substrate sourcing economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Hydraulic Cylinders Market