
 Europe Manual Resuscitators Market | 2026-2036
Europe Manual Resuscitators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Manual Resuscitators Market Foresight
Equipment leasing and pay-per-use arrangements is tilting competitive dynamics toward firms with strong service networks. Ambu A/S leverages its pan-European distribution infrastructure to capture recurring revenue streams. Laerdal Medical anchors its position through intensive R&D investment in pediatric-specific designs. WEINMANN Emergency Medical Technology GmbH + Co. KG specializes in ruggedized transport configurations for helicopter emergency services.
A manual resuscitator is a hand-held, self-inflating or flow-inflating device constructed from silicone or PVC with a unidirectional valve assembly, designed to deliver positive-pressure ventilation to patients with inadequate spontaneous respiration. The device typically incorporates a non-rebreathing valve, pressure-limiting mechanism, and detachable mask interface rated for clinical reuse or single-patient application. Bag-valve-mask configurations dominate hospital procurement due to established clinician training protocols, while pocket resuscitators are gaining traction among emergency responders seeking compact field-deployable formats. Silicone material segments command premium positioning owing to autoclavability and extended lifecycle performance under repeated sterilization cycles.
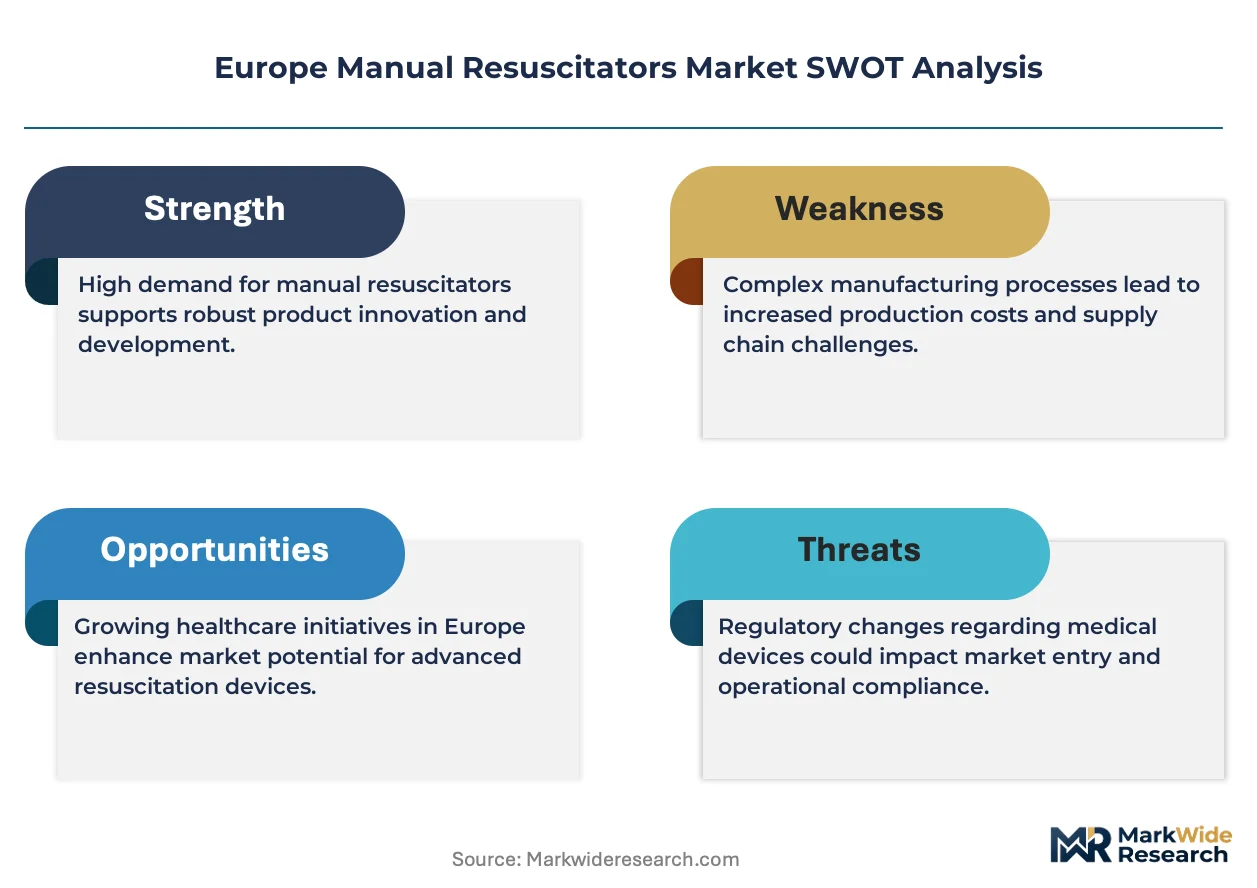
The EU Medical Device Regulation and CE marking framework enforce biocompatibility testing and post-market surveillance obligations that elevate compliance costs for smaller manufacturers. Germany's BfArM and France's ANSM coordinate national vigilance reporting that shapes product recall patterns and design modification priorities across the continent. Stakeholders must monitor evolving harmonized standards for reusable respiratory devices and assess whether in-house sterilization capabilities or disposable pivots offer stronger margin protection under tightening environmental compliance pressures.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product lifecycles and forcing manufacturers to choose between sterilization infrastructure investment and disposable pivots, reshaping competitive economics across the continent.
Growth Catalysts
- Helicopter emergency medical services:Air ambulance fleets in Germany and France are expanding rapid-response capabilities that demand ruggedized, altitude-rated resuscitator configurations with integrated pressure-compensation valves.
- MDR compliance deadlines:The EU Medical Device Regulation's transitional provisions are accelerating hospital procurement of CE-IVDR-certified devices ahead of legacy certificate expiration dates.
- Silicone autoclavability:Reusable silicone components are displacing PVC alternatives in tertiary care centers seeking to reduce single-use waste volumes under national sustainability mandates.
Market Restraints
- Raw material concentration:Medical-grade silicone supply concentrates among German and Belgian specialty chemical producers, exposing manufacturers to input cost volatility and allocation rationing during capacity constraints.
- Technical limitation in pediatric sizing:Existing valve assemblies struggle to deliver precise tidal volumes below 150 mL, limiting safe deployment in neonatal transport scenarios without specialized accessories.
- Regulatory friction from vigilance reporting:France's ANSM and Germany's BfArM coordinate adverse event reporting requirements that extend post-market surveillance timelines and elevate documentation burdens for reusable device portfolios.
Strategic Opportunities
- Eastern European hospital modernization:Polish and Romanian health ministries are channeling EU structural funds into emergency department upgrades, creating procurement windows for mid-tier equipment suppliers.
- Pay-per-use service models:Equipment leasing arrangements are penetrating Nordic ambulance cooperatives, favoring vendors with field-service networks capable of preventive maintenance and rapid component exchange.
- CSRD disclosure alignment:The EU Corporate Sustainability Reporting Directive is compelling healthcare purchasers to document supply chain emissions, advantaging manufacturers with verified lifecycle assessments for reusable product lines.
Industry Challenges
- Biocompatibility testing bottlenecks:Notified body capacity constraints under MDR Article 54 are extending conformity assessment timelines, delaying product launches and freezing R&D roadmaps.
- Sterilization validation complexity:Autoclave cycle qualification for silicone resuscitators requires extensive endotoxin and cytotoxicity testing that strains in-house quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Manual Resuscitators Market |
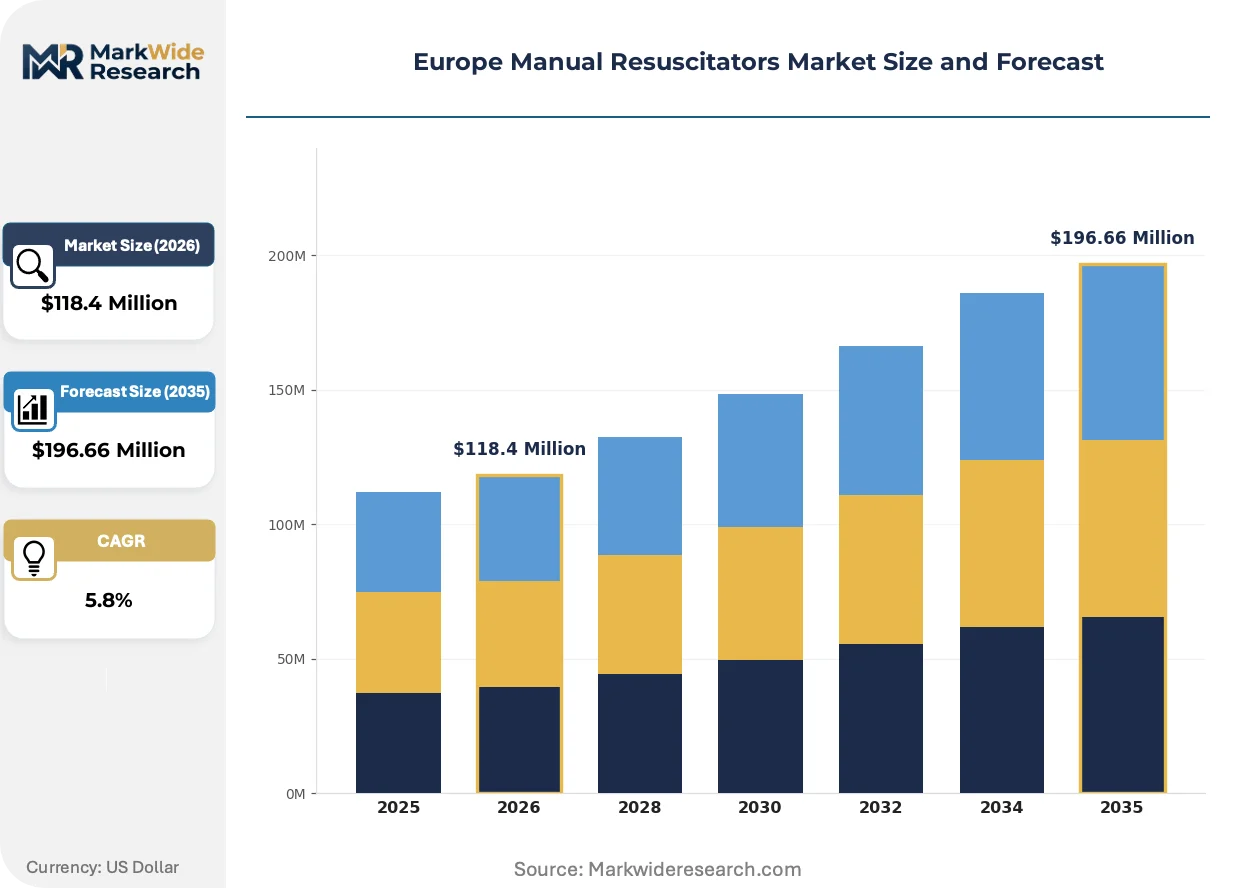
| Market Size in 2026 | $118.4 Million |
| Market Size in 2035 | $196.66 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag-Valve-Mask, Self-Expanding Bag, Pocket Resuscitator, Valve Mask Material: Silicone, PVC, Rubber, Polypropylene Application: Emergency Care, Anesthesia, Transport, Pediatric Care End User: Hospitals, Clinics, Ambulance Services, Emergency Responders |
| Companies Covered | WEINMANN Emergency Medical Technology GmbH + Co. KG, Ambu A/S, Laerdal Medical, HUM Gesellschaft für Homecare und Medizintechnik mbH, Drägerwerk AG & Co. KGaA, Medtronic, Teleflex Incorporated, Medline Industries, Flexicare (Group) Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Manual Resuscitators Market Shifts & Advancements
Connected device architectures and sustainability-driven material transitions are converging to redefine product value propositions, while procurement centralization is compressing vendor margins and elevating service capabilities as differentiation levers.
Integrated pressure sensors with Bluetooth telemetry are digitizing ventilation parameter capture during pre-hospital transport. Air ambulance crews in Alpine regions are piloting these systems to enable real-time clinical handoff documentation. The technology is digitizing quality assurance workflows by automating compliance logging that previously required manual transcription.
MDR Article 10 post-market surveillance obligations are mandating systematic clinical follow-up studies for reusable respiratory devices. Manufacturers must now maintain vigilance databases tracking device performance across sterilization cycles. Class IIa resuscitators face the steepest compliance cost escalation, prompting portfolio rationalization toward higher-margin specialty configurations.
Consolidated purchasing cooperatives are displacing hospital-level procurement autonomy across France and Germany. Regional hospital alliances now negotiate framework agreements specifying preventive maintenance inclusion and technician training certification. The Benelux corridor exhibits the most advanced cooperative purchasing maturity, with shared-service organizations managing equipment lifecycle decisions for multiple emergency medical service jurisdictions.
Europe Manual Resuscitators Market Segmentation
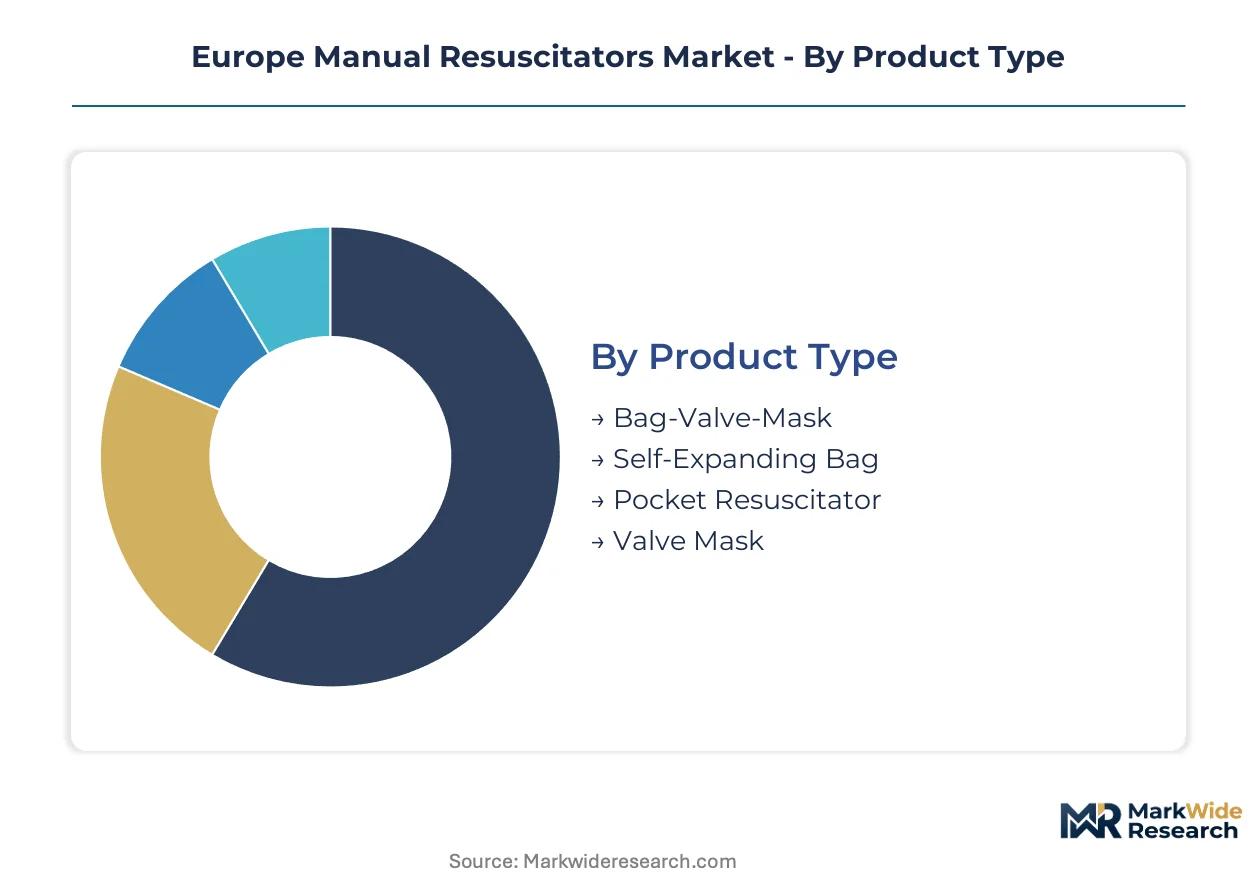
Segmentation in the Europe Manual Resuscitators Market reveals divergent procurement logics across clinical settings. Material autoclavability, transport portability requirements, and end-user sterilization capabilities each create distinct purchasing criteria that manufacturers must address through specialized product configurations.
Product Type:
Application context determines which configuration clinicians deploy — hospital emergency departments favor established training-compatible designs while air ambulance crews prioritize compact, altitude-rated alternatives.
- Bag-Valve-Mask:The dominant configuration incorporates a self-inflating bag, unidirectional valve, and detachable mask interface rated for 40 cm H₂O peak pressure. German and French tertiary hospitals concentrate procurement here due to entrenched clinician training protocols and anesthesia department standardization.
- Pocket Resuscitator:A collapsible, single-patient-use variant weighing under 200 grams that integrates a one-way valve with a flexible face shield. Alpine helicopter emergency services in Switzerland and Austria are rotating toward this format for high-altitude rapid-response kits where every gram determines fuel range.
- Self-Expanding Bag:Compresses flat for storage then re-inflates automatically via internal spring mechanisms. Nordic ambulance cooperatives specify this design for space-constrained vehicle compartments.
- Valve Mask:A streamlined assembly omitting the reservoir bag for direct mouth-to-mask ventilation. Community first-responder programs across rural Spain and Portugal distribute this economy-tier option for layperson emergency intervention.
Bag-Valve-Mask holds installed capacity. Pocket Resuscitator is rotating up the share rankings.
Material:
Cost tier and lifecycle economics split procurement between premium autoclavable options and disposable alternatives — sustainability mandates and sterilization infrastructure availability determine which tier dominates in each national market.
- Silicone:Medical-grade platinum-cured elastomer withstands 500+ steam sterilization cycles without degradation. Belgian and Dutch hospital systems concentrate demand here under national waste-reduction directives that penalize single-use device volumes.
- PVC:Lower-cost polymer suitable for limited-use or single-patient applications. Polish and Romanian emergency departments prioritize this material during EU structural fund modernization waves where upfront capital constraints dominate procurement calculus.
- Rubber:Natural latex formulation offering high elasticity but requiring careful allergy screening. Legacy installations in older Italian public hospitals maintain this material for compatibility with existing sterilization protocols.
- Polypropylene:Rigid thermoplastic deployed primarily for valve housings and connector components rather than the inflation bag itself. Component suppliers across the Czech Republic specialize in precision-molded polypropylene fittings for modular resuscitator assemblies.
Silicone commands the margin premium. PVC is gaining share fastest in Eastern European procurement waves.
Application:
Volume requirements and patient acuity create divergent technical specifications — neonatal precision demands differ fundamentally from mass-casualty field deployment scenarios.
- Emergency Care:Standardized adult and pediatric configurations for emergency department intubation support and cardiac arrest response. French SAMU and German EMS systems specify these units for ground ambulance fleet standardization.
- Pediatric Care:Requires specialized low-volume valve assemblies capable of delivering 50-150 mL tidal volumes with precise pressure control. Swedish and Finnish neonatal transport networks drive specification refinement here.
- Anesthesia:Operating room deployment demands compatibility with volatile anesthetic agents and integrated CO₂ monitoring ports. University hospitals across Denmark and Norway upgrade these configurations during surgical suite renovation cycles.
- Transport:Ruggedized assemblies with pressure-compensation valves for altitude variation and secure mounting brackets. Air ambulance operators in the Bavarian Alps and Pyrenees corridor specify these for helicopter emergency medical services.
Emergency Care holds installed capacity. Transport is climbing the fastest among application segments.
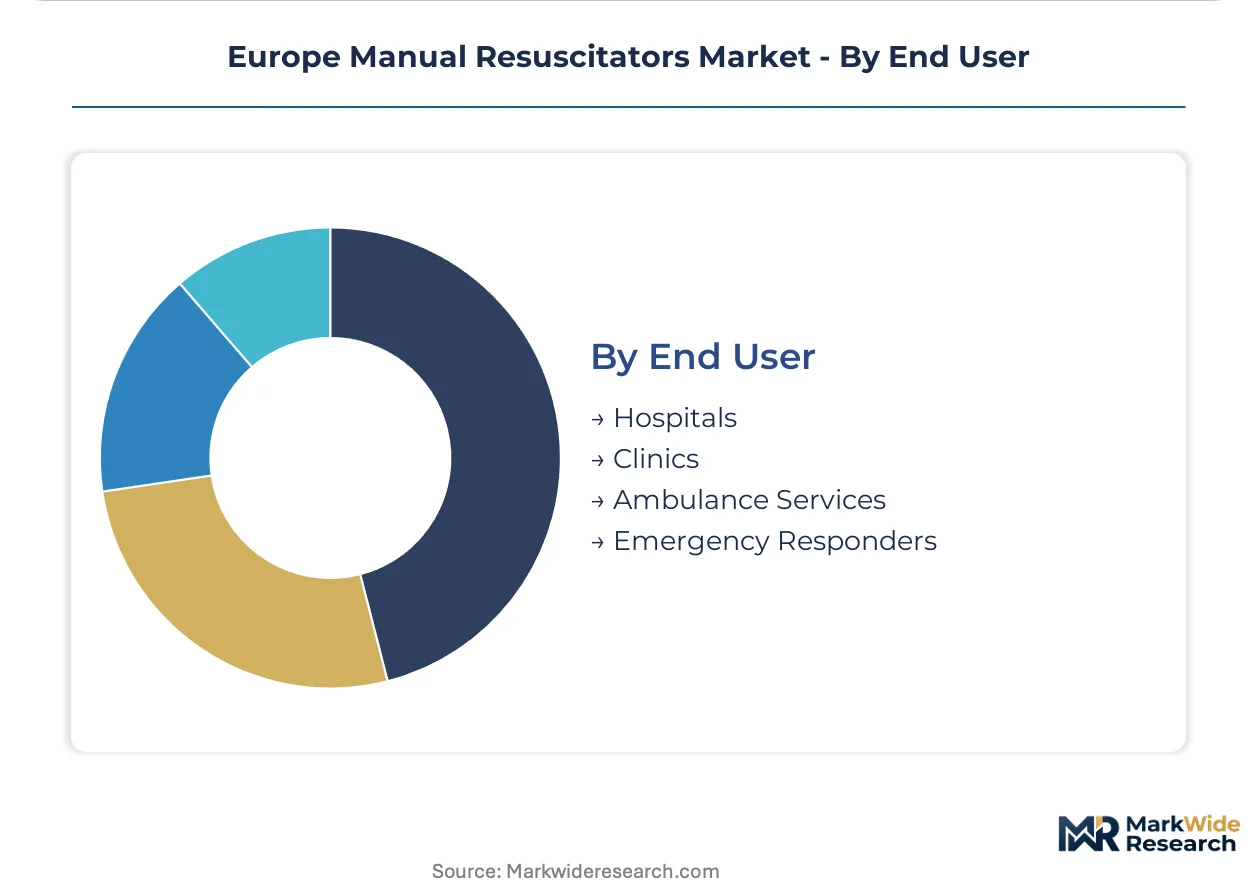
End User:
Customer type determines service model expectations — hospital procurement favors capital equipment with maintenance contracts while ambulance services increasingly demand lease-based arrangements with rapid field support.
- Hospitals:Centralized purchasing departments negotiate framework agreements specifying preventive maintenance inclusion and technician certification programs. German university hospital alliances and French regional hospital groups concentrate procurement volume here.
- Ambulance Services:Ground and air emergency medical services require ruggedized configurations with rapid component exchange capabilities. Scandinavian ambulance cooperatives are piloting pay-per-use leasing models that shift capital burden to vendors.
- Emergency Responders:Fire services, police medical units, and community first-responder programs need compact, intuitive designs requiring minimal training. Rural volunteer organizations across Portugal and Greece prioritize low-cost, disposable-focused procurement.
- Clinics:Outpatient surgical centers and urgent care facilities specify mid-tier configurations balancing reusability with moderate sterilization throughput. Private clinic chains in Spain and Italy represent fragmented but growing procurement nodes.
Hospitals hold installed capacity. Ambulance Services is expanding most quickly through cooperative purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital alliances and French regional hospital groups concentrate procurement authority, while Scandinavian ambulance cooperatives pioneer pay-per-use service models that redistribute capital burdens across the vendor base.
Germany
Bavarian helicopter emergency medical services drive demand for altitude-rated resuscitator configurations with integrated pressure-compensation valves. BfArM coordinates national vigilance reporting that shapes product recall patterns and design modification priorities. The Rhine-Main industrial corridor hosts sterilization equipment manufacturers supplying autoclave infrastructure to tertiary care centers.
France
SAMU emergency medical systems standardize ground ambulance fleet specifications across regional hospital groups. ANSM enforces adverse event documentation requirements that extend post-market surveillance timelines for reusable device portfolios. The Lyon-Grenoble medical technology cluster concentrates pediatric-specific valve assembly development.
Sweden
Neonatal transport networks specify low-volume valve assemblies capable of delivering precise tidal volumes below 150 mL. The country's national pharmaceutical regulator monitors biocompatibility testing compliance under MDR transitional provisions. Stockholm-based emergency medical service jurisdictions pilot equipment leasing arrangements with preventive maintenance inclusion.
Poland
EU structural funds channel capital into emergency department modernization waves where upfront budget constraints dominate procurement calculus. The national pharmaceutical regulator aligns vigilance reporting with EMA harmonized standards. Warsaw and Krakow hospital systems concentrate PVC-focused procurement for single-patient applications.
Netherlands
Benelux shared-service organizations manage equipment lifecycle decisions across multiple emergency medical service jurisdictions. National waste-reduction directives penalize single-use device volumes, accelerating silicone autoclavability adoption. The Eindhoven medical device engineering cluster supplies precision-molded polypropylene fittings for modular resuscitator assemblies.
Europe Manual Resuscitators Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where pan-European distribution infrastructure determines recurring revenue capture. The vendor base organizes around three strategic archetypes: diversified emergency medical technology conglomerates with sterilization service networks, focused resuscitation device specialists with pediatric R&D concentration, and component-integrated manufacturers with captive polymer supply. Competitive moves center on framework agreement consolidation with regional hospital alliances and backward integration into medical-grade silicone compounding.
Among diversified emergency medical technology conglomerates, Drägerwerk AG & Co. KGaA and Medtronic occupy positions anchored by comprehensive anesthesia and respiratory portfolios. WEINMANN Emergency Medical Technology GmbH + Co. KG exemplifies the transport-specialist archetype with ruggedized configurations for helicopter emergency services. Ambu A/S and Laerdal Medical represent the focused resuscitation device specialists competing through intensive R&D investment and pan-European service network density.
| Leading Market Players |
|---|
| WEINMANN Emergency Medical Technology GmbH + Co. KG |
| Ambu A/S |
| Laerdal Medical |
| HUM Gesellschaft für Homecare und Medizintechnik mbH |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Teleflex Incorporated |
| Medline Industries |
| Flexicare (Group) Limited |
| Others |
Supply & Pricing Matrix
The Eindhoven medical device engineering cluster concentrates precision-molded polypropylene fitting production, creating capacity bottlenecks that transmit directly into component pricing power for modular resuscitator assemblies across German and French procurement channels.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate framework agreements between Belgian specialty chemical producers and resuscitator manufacturers. Three-tier pricing structure across premium autoclavable silicone, mid-tier PVC, and economy disposable configurations separates tertiary care centers from budget-constrained Eastern European emergency departments. Pricing pressure stems from MDR compliance cost absorption as notified body capacity constraints extend conformity assessment timelines. Ambulance cooperatives in Scandinavia exhibit lowest price sensitivity due to pay-per-use leasing models that shift capital burden to vendors.
Supply Chain Analysis
Supplier-financing arrangements including 90-day extended payment terms and supply-chain finance facilities have become standard for PVC compound procurement from German and Belgian petrochemical suppliers. Medical-grade silicone concentrates in German and Belgian specialty chemical production, while precision-molded polypropylene fittings source from Czech and Dutch component specialists. Raw material dependencies rest on platinum-cured elastomer, medical-grade PVC resin, and injection-molded valve housings. Single-source vulnerability in silicone compounding creates exposure during capacity allocation rationing. Distribution runs through pan-European medical device distributors and direct hospital alliance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against automated mechanical ventilator miniaturization for pre-hospital transport, as air ambulance fleets evaluate semi-autonomous alternatives that threaten manual resuscitator deployment in high-acuity scenarios.
For Market Incumbents: Entrench position through backward integration into medical-grade silicone compounding to secure input cost stability against Belgian and German specialty chemical allocation rationing. Expand sterilization service networks across French regional hospital groups to capture recurring revenue from MDR-mandated reprocessing validation. Prioritize pediatric-specific valve assembly R&D to defend against transport ventilator substitution in neonatal care segments. For New Entrants and Emerging Players: Polish and Romanian emergency department modernization waves present the most penetrable procurement windows, as EU structural fund capital injections create demand for mid-tier PVC configurations without entrenched vendor relationships. Target ambulance cooperatives in the Baltic states with ruggedized transport configurations featuring integrated pressure-compensation valves. Pursue equipment leasing partnerships with Nordic shared-service organizations to bypass capital equipment procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MDR compliance cost escalation and notified body capacity constraints will force portfolio rationalization among smaller reusable device manufacturers. Acquisition targets include sterilization-validated silicone specialists with established CE-IVDR technical documentation and field-service network density in Alpine helicopter emergency corridors. Monitor BfArM and ANSM coordinated vigilance reporting patterns as early indicators of design modification cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Technical Documentation Investment | Accelerates market access ahead of legacy certificate expiration deadlines under MDR transitional provisions. |
| Sterilization Service Network Expansion | Captures recurring revenue from French and German hospital alliance preventive maintenance requirements. |
| Pediatric Valve Assembly R&D | Addresses technical limitation in sub-150 mL tidal volume delivery for Swedish neonatal transport networks. |
| Pay-per-Use Leasing Model Deployment | Aligns with Nordic ambulance cooperative purchasing consolidation and redistributes capital burden. |
| Silicone Compounding Backward Integration | Insulates margin position against German and Belgian medical-grade elastomer supply concentration. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and air ambulance operations directors, and refined through secondary validation against EMA MDR guidance documents, CE marking databases, hospital procurement records, and national vigilance reporting systems. Bottom-up demand modeling across product type, material, application, and end-user segments was triangulated with top-down market sizing from trade data and regulatory filings.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with volume outputs derived from installed base replacement cycles, fleet expansion in helicopter emergency services, and MDR-driven procurement acceleration. Segmentation dimensions modeled include configuration type, material autoclavability, patient acuity tier, and sterilization infrastructure availability. CAGRs were computed from normalized baseline values and growth phase trajectory analysis. Forecast inputs incorporated EU structural fund disbursement patterns for Eastern European hospital modernization and Alpine air ambulance fleet expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare capital expenditure cycles or medical-grade silicone commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding MDR transitional provision enforcement timing and notified body capacity expansion. Regulatory reinterpretation, supply chain disruption in Belgian specialty chemical production, or technological substitution in pre-hospital ventilation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Cheek Implants Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market