
 Tracheobronchial Stent Grafts Market | 2026-2036
Tracheobronchial Stent Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Tracheobronchial Stent Grafts Market Outlook
A capital-intensity divergence between fully integrated manufacturers and assembly-dependent competitors is unwinding competitive stability in tracheobronchial stent grafts. Boston Scientific Corporation leverages its endoscopy ecosystem to bundle airway stents with imaging and navigation platforms. Taewoong Medical Co., Ltd. anchors its position through specialized metallurgy capabilities in nitinol self-expanding designs. Medtronic competes by extending its vascular stent manufacturing infrastructure into airway applications.
Tracheobronchial stent grafts are implantable tubular devices, typically constructed from nitinol alloys or silicone polymers, designed to maintain patency in compromised central airways following malignant obstruction, post-transplant stenosis, or traumatic injury. Self-expanding nitinol variants dominate procedural volume due to their conformability to irregular airway anatomy and resistance to compression from extrinsic tumors. Balloon-expandable stainless steel segments retain importance in rigid proximal tracheal lesions requiring precise diameter control. Polymer-based stents, particularly silicone Y-configurations, occupy a distinct margin pool in benign stricture management where removability outweighs long-term implantation needs.
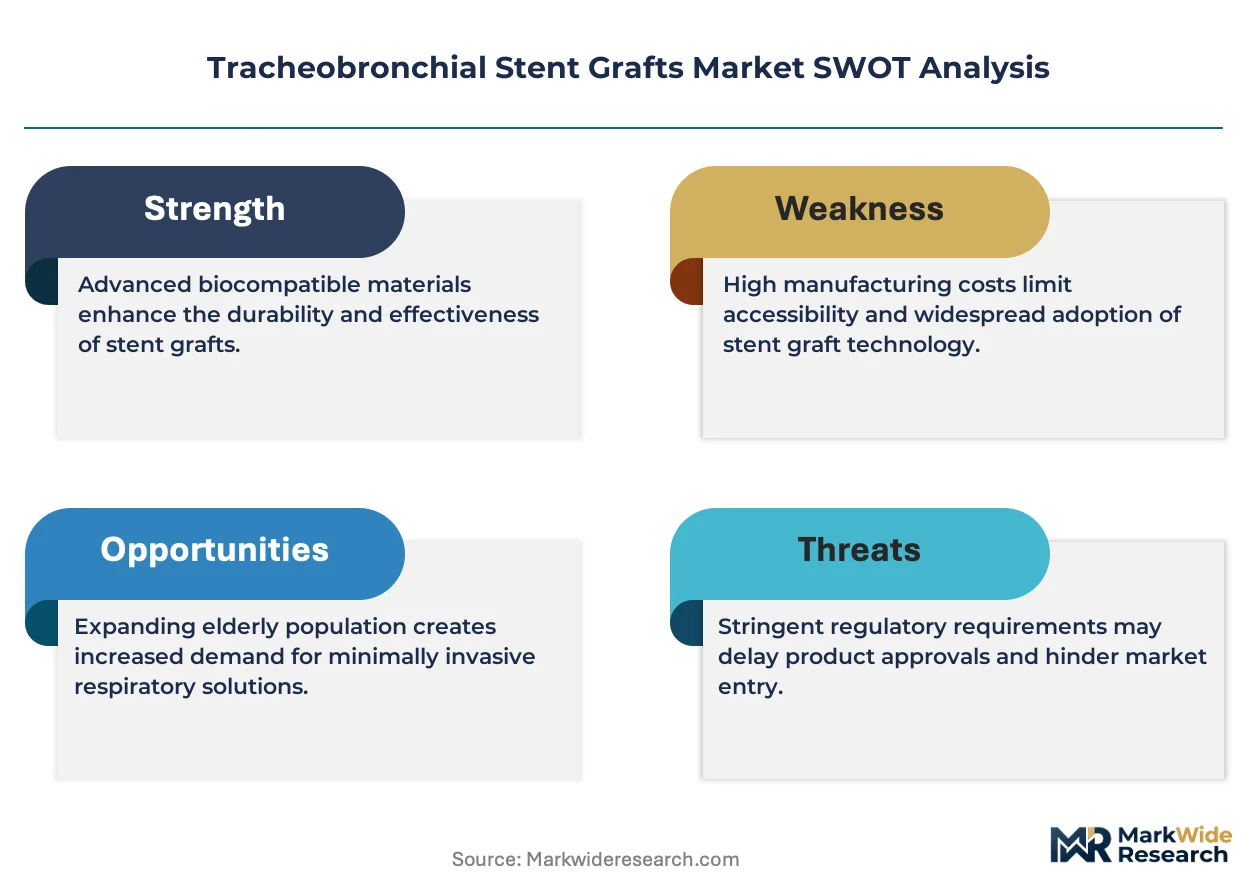
FDA 510(k) clearance pathways and EU MDR Class III designation impose substantial clinical evidence requirements on novel stent graft submissions, elevating barriers for entrants lacking predicate device strategies. ISO 25539-2 standards for endovascular stents are increasingly referenced by notified bodies as surrogate benchmarks for airway stent mechanical performance testing. Japan's PMDA maintains distinct material biocompatibility protocols that delay market entry for manufacturers relying solely on FDA or CE documentation. Stakeholders must monitor evolving reimbursement thresholds for outpatient bronchoscopic stent placement as health technology assessment bodies scrutinize cost-effectiveness against surgical alternatives.
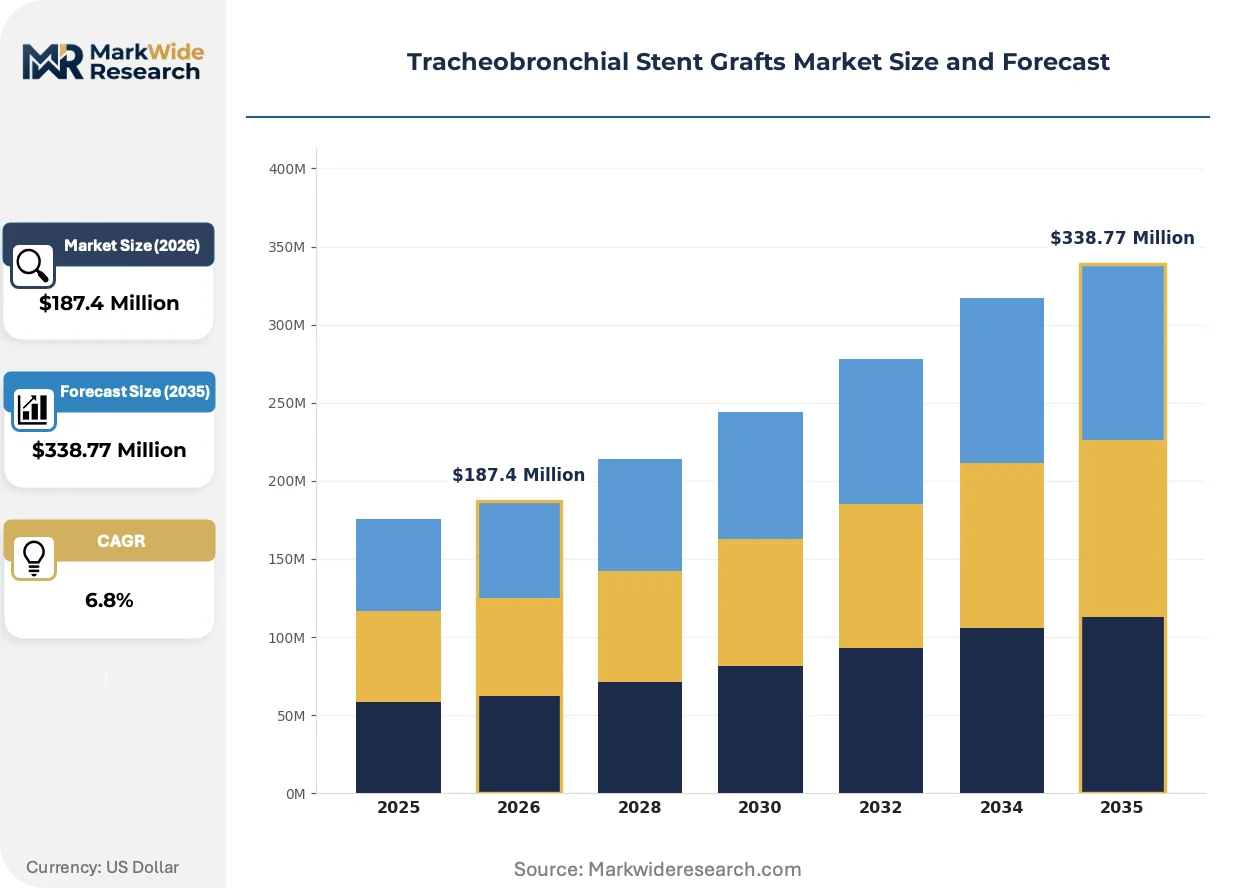
Market Dynamics
Central airway obstruction from lung malignancies is intensifying demand for durable stent solutions, while EU MDR Class III designation and FDA 510(k) pathway revisions are extending clinical validation timelines for new entrants. This regulatory compression is favoring incumbents with predicate device portfolios and established biocompatibility dossiers.
Growth Catalysts
- Japan's aging respiratory patient pool:PMDA reimbursement expansion for outpatient bronchoscopic stenting is accelerating procedural volume in tertiary hospitals.
- Nitinol metallurgy advances:Superelastic alloy processing improvements are enabling thinner-walled self-expanding designs with enhanced conformability to irregular tracheal anatomy.
- FDA breakthrough device designation:Expedited review pathways for drug-eluting airway stents are compressing time-to-market for novel localized therapy platforms.
Market Restraints
- Nitinol raw material concentration:Premium-grade nickel-titanium alloy supply concentrates among a limited set of specialized metallurgical suppliers, creating input cost volatility.
- EU MDR technical documentation burden:Enhanced clinical evidence requirements for implantable devices are extending conformity assessment timelines by 18-24 months for new submissions.
- Surgical reconstruction alternatives:Tracheal resection and primary anastomosis techniques retain preference in proximal lesions amenable to curative intervention.
Strategic Opportunities
- Germany's interventional pulmonology expansion:University hospital network investments in advanced bronchoscopy suites are creating concentrated demand for integrated stent-navigation platforms.
- Biodegradable polymer convergence:Magnesium alloy and polylactic acid stent technologies are opening temporary scaffolding applications in benign stricture management.
- Remote proctoring channels:Telemedicine-enabled physician training programs are reducing geographic barriers to complex stent deployment technique dissemination.
Industry Challenges
- Interventional pulmonology fellowship pipeline:Subspecialty training program capacity constraints are limiting the pool of operators qualified for complex central airway interventions.
- ISO 25539-2 mechanical testing adaptation:Endovascular stent standards applied as surrogate benchmarks for airway devices create validation protocol mismatches requiring custom fixture development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracheobronchial Stent Grafts Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding, Balloon-Expandable, Stainless Steel, Polymer Delivery Mode: Endobronchial, Intravenous, Catheter-Based, Surgical End User: Hospitals, Clinics, Outpatient Facilities, Research Institutions Application: Emergency Care, Palliative Treatment, Surgical Intervention, Diagnostic Procedure |
| Companies Covered | Boston Scientific Corporation, Cook, Micro-Tech (Nanjing) Co., Ltd., Taewoong Medical Co., Ltd., Merit Medical Systems, Inc., Novatech SA, ENDO-FLEX GmbH, Medtronic, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracheobronchial Stent Grafts Market Strategic Shifts
Device miniaturization and localized drug delivery integration are redefining performance benchmarks in airway stenting. Competitive differentiation is shifting from mechanical patency alone toward biocompatibility optimization and procedure ecosystem integration.
Drug-eluting nitinol stents incorporating paclitaxel or sirolimus matrices are displacing bare-metal alternatives in malignant obstruction cases where tumor ingrowth drives restenosis. Interventional pulmonology departments at comprehensive cancer centers are adopting these platforms rapidly despite premium positioning. The technology is displacing repeat bronchoscopic intervention cycles and reducing total cost of care in complex airway oncology.
EU MDR post-market surveillance requirements now mandate systematic registry participation for Class III implantable devices, including tracheobronchial stents. Manufacturers must maintain active implant tracking and periodic safety update reporting throughout device lifecycle. German notified bodies are enforcing these provisions most stringently, prompting portfolio rationalization among smaller competitors lacking pharmacovigilance infrastructure.
Hospital procurement committees are consolidating stent purchasing through value-analysis frameworks that bundle airway devices with bronchoscopy capital equipment. United States health system GPOs are displacing traditional distributor relationships with direct manufacturer contracts tied to navigation platform commitments. This concentration is most visible in multi-hospital integrated delivery networks in Texas and Florida where outpatient bronchoscopy volume justifies capital bundling negotiations.
Tracheobronchial Stent Grafts Market Segmentation
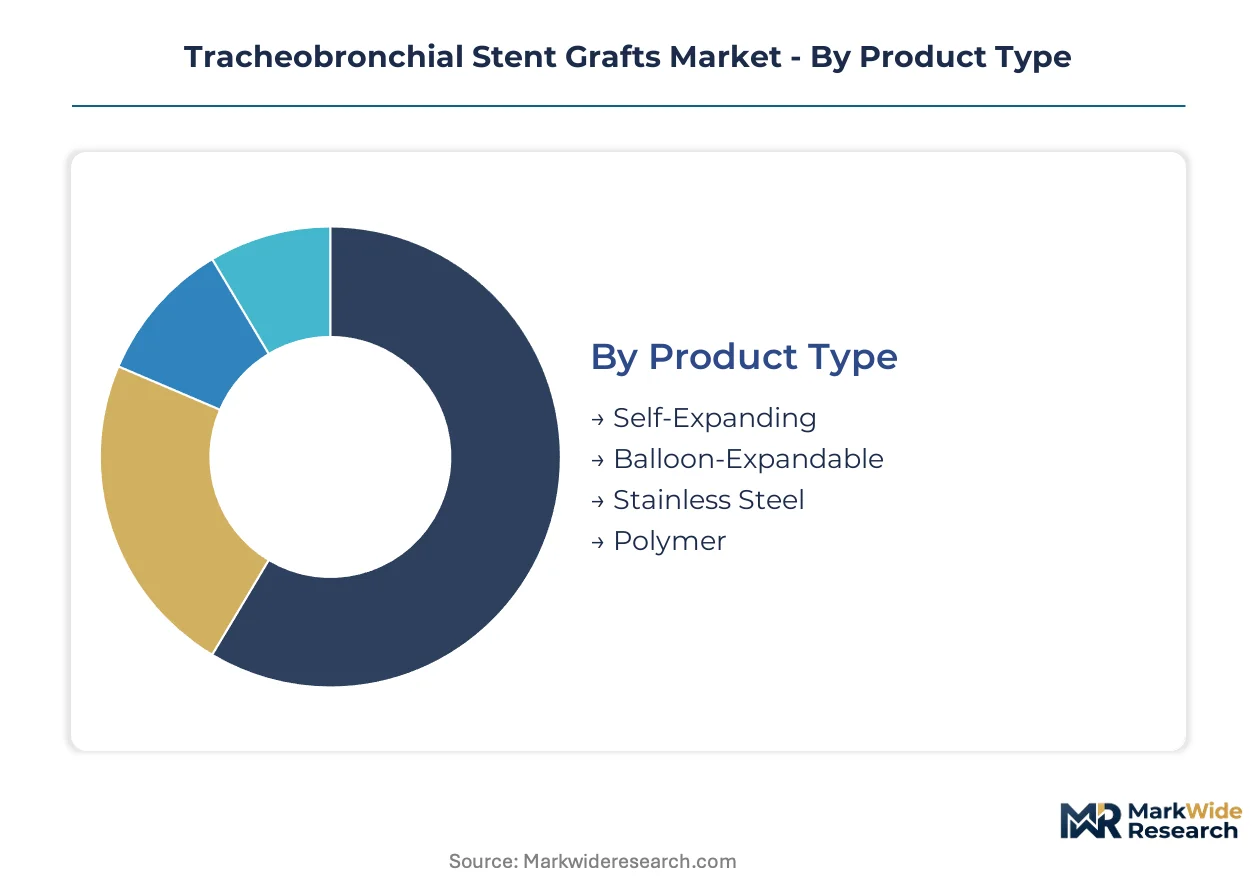
Tracheobronchial stent graft segmentation reveals how clinical requirements fragment procurement decisions across airway obstruction scenarios. Product specifications, deployment methods, and care settings each create distinct margin architectures that manufacturers must navigate.
Product Type:
Margin pools concentrate in self-expanding nitinol platforms where superelastic metallurgy commands premium positioning against commodity alternatives.
- Self-Expanding:Nitinol alloy construction enables conformability to irregular tracheal anatomy without balloon assistance. Tertiary hospitals in Germany and Japan are standardizing these platforms for malignant obstruction cases where tumor compression resistance determines procedural success.
- Balloon-Expandable:Stainless steel segments deliver precise diameter control through inflation-mediated deployment. United States interventional pulmonology programs favor these designs for rigid proximal tracheal lesions requiring exact sizing calibration.
- Stainless Steel:Rigid structural properties suit permanent implantation in anatomically stable airway segments. Cost-sensitive procurement committees in outpatient settings increasingly specify these alternatives.
- Polymer:Silicone and polyurethane formulations enable removability in benign stricture management. Pediatric and transplant centers represent concentrated demand for these temporary scaffolding solutions.
The dominant share belongs to Self-Expanding, while Polymer is closing the gap fastest as removability protocols expand.
Delivery Mode:
Volume concentration tracks bronchoscopic platform penetration, with catheter-based methods capturing procedural share from open surgical alternatives.
- Endobronchial:Flexible bronchoscope-mediated deployment constitutes the standard of care for central airway interventions. Japanese university hospitals are expanding dedicated interventional pulmonology suites to accommodate rising procedural volume.
- Catheter-Based:Sheath delivery systems enable precise positioning through tortuous airway anatomy. United States comprehensive cancer centers are adopting these platforms for distal lesion access beyond rigid bronchoscope reach.
- Intravenous:Vascular access routes support hybrid procedures combining airway and pulmonary vascular intervention. Specialized thoracic surgery units in Germany maintain limited adoption for complex multi-compartment pathologies.
- Surgical:Open placement through tracheotomy or thoracotomy retains indication for combined resection and reconstruction. Declining utilization reflects minimally invasive technique maturation across tertiary referral networks.
Endobronchial methods hold the installed base advantage, though Catheter-Based approaches are expanding most quickly through navigation platform integration.
End User:
Purchasing authority fragmentation creates divergent contract structures across integrated delivery networks and independent specialty practices.
- Hospitals:Inpatient reimbursement frameworks and capital equipment bundling dominate procurement decisions. United States health system GPOs in Texas and Florida are consolidating stent purchasing through value-analysis committees.
- Outpatient Facilities:Ambulatory surgery centers exploit procedure migration from inpatient settings under expanded reimbursement codes. German outpatient bronchoscopy networks are capturing share through same-day discharge protocols.
- Clinics:Pulmonology and thoracic surgery practices maintain limited inventory for urgent stenting scenarios. Geographic concentration in metropolitan Japan supports dedicated interventional pulmonology clinic models.
- Research Institutions:Academic medical centers drive investigational device exemption trials and registry participation. FDA breakthrough device designation pathways channel novel stent technologies through these sites.
Hospitals retain the volume concentration, yet Outpatient Facilities are climbing the fastest as reimbursement shifts favor ambulatory procedural settings.
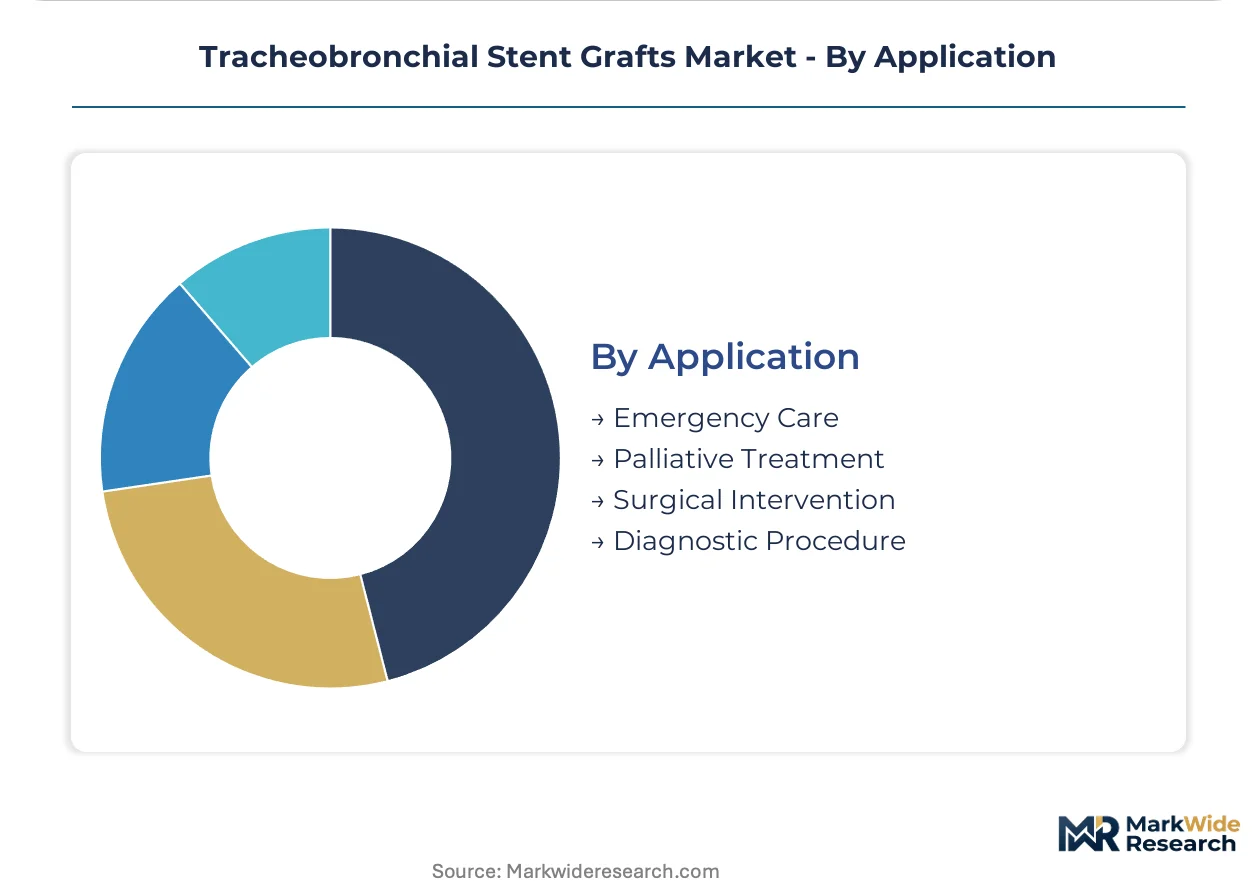
Application:
Clinical indication severity determines stent specification requirements and replacement frequency, with malignant obstruction commanding durable platform investment.
- Palliative Treatment:Symptom relief in unresectable malignancy drives repeat intervention cycles and stent exchange protocols. Drug-eluting platforms are displacing bare-metal alternatives in United States comprehensive cancer centers.
- Emergency Care:Acute airway compromise requires immediate patency restoration without sizing optimization. Japanese tertiary emergency departments maintain rapid-access stent inventories for traumatic and iatrogenic obstructions.
- Surgical Intervention:Perioperative and post-anastomotic stenting supports tracheal reconstruction outcomes. German thoracic surgery referral networks specify temporary polymer designs for anastomotic protection.
- Diagnostic Procedure:Stent placement facilitates tissue sampling or bronchoscopic assessment in complex airway anatomy. Limited volume concentrates in academic medical center research protocols.
Palliative Treatment commands the revenue concentration, while Emergency Care is gaining share fastest through emergency department interventional pulmonology program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium positioning against cost-calibrated procurement in the United States, reflecting divergent reimbursement architectures for interventional pulmonology procedures.
United States
Comprehensive cancer centers in Houston and New York Metro drive concentrated demand for drug-eluting nitinol platforms. FDA 510(k) pathway revisions are extending clinical validation timelines for novel stent submissions. Texas Medical Center anchors the nation's largest interventional pulmonology fellowship pipeline.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are standardizing self-expanding nitinol designs for malignant obstruction cases. EU MDR Class III designation imposes systematic registry participation mandates throughout device lifecycle. The Eindhoven-Düsseldorf corridor concentrates European bronchoscopy capital equipment manufacturing.
Japan
PMDA reimbursement expansion for outpatient bronchoscopic stenting is accelerating procedural volume in Tokyo and Osaka tertiary hospitals. Japan's distinct material biocompatibility protocols delay market entry for manufacturers relying solely on FDA documentation. Kansai region university hospitals maintain the Asia-Pacific's most advanced interventional pulmonology training infrastructure.
China
NMPA regulatory harmonization efforts are streamlining Class III implantable device approvals for domestic manufacturers in Shanghai and Beijing. Central hospital procurement reforms are consolidating stent purchasing through provincial volume-based tendering. Yangtze River Delta medical device clusters are scaling nitinol metallurgy capabilities for airway applications.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex airway interventions at London and Manchester thoracic surgery referral centers. MHRA post-Brexit regulatory divergence from EU MDR is creating parallel conformity assessment requirements. The Oxford-Cambridge-London golden triangle drives biodegradable polymer stent research programs.
Tracheobronchial Stent Grafts Market Competitive Environment
Concentration sits with diversified medical device conglomerates possessing predicate device portfolios and established biocompatibility dossiers. The vendor base stratifies across three tiers: fully integrated platform providers, specialized metallurgy specialists, and assembly-dependent regional fabricators. Strategic archetypes include endoscopy ecosystem bundlers, nitinol processing specialists, and vascular-to-airway manufacturing extenders. Dominant competitive moves encompass navigation platform bundling negotiations and backward integration into superelastic alloy supply.
Among diversified platform providers, Boston Scientific Corporation and Medtronic occupy positions leveraging endoscopy ecosystem breadth. Taewoong Medical Co., Ltd. exemplifies the specialized metallurgy archetype through its nitinol self-expanding design concentration. These three anchors represent distinct competitive vectors: platform integration, materials science depth, and manufacturing infrastructure extension.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook |
| Micro-Tech (Nanjing) Co., Ltd. |
| Taewoong Medical Co., Ltd. |
| Merit Medical Systems, Inc. |
| Novatech SA |
| ENDO-FLEX GmbH |
| Medtronic |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German university hospital networks and nitinol alloy processors lock in supply access while anchoring price visibility for self-expanding stent platforms. These arrangements insulate procurement committees from spot-market volatility in nickel-titanium feedstock while compressing margins for assembly-dependent competitors lacking captive metallurgy capabilities.
Pricing Analysis
Configured-to-order pricing for patient-specific stent geometries commands a substantial premium over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA breakthrough designation status, ISO 25539-2 testing completeness, and bundled navigation platform commitments. Pricing pressure stems from GPO consolidation in United States integrated delivery networks, particularly Texas and Florida health systems. Outpatient surgery centers exhibit acute price sensitivity, while comprehensive cancer centers prioritize clinical performance metrics over unit cost.
Supply Chain Analysis
Inventory buffers for nitinol wire stock extend lead times when Japanese or German metallurgical suppliers face capacity constraints. Premium-grade nickel-titanium alloy production concentrates in Japan, Germany, and the United States, with device assembly clustering in South Korea and China for cost-calibrated procurement tiers. Supply chain risk centers on single-source dependency for superelastic alloy formulations with PMDA-compliant biocompatibility documentation. Distribution runs through specialized medical device distributors in Europe and direct manufacturer contracts via GPOs in North American hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system GPO consolidation in the United States and university hospital network procurement centralization in Germany, fragmenting pricing leverage for smaller manufacturers without platform bundling capabilities.
For Market Incumbents: Secure backward integration into nitinol alloy supply through long-term offtake agreements with Japanese or German metallurgical processors, insulating against raw material concentration risk. Deepen hospital system partnerships by bundling stent platforms with bronchoscopy navigation capital equipment, defending installed base share from emerging competitors lacking ecosystem breadth. Prioritize EU MDR technical documentation investment to extend predicate device advantages as conformity assessment timelines lengthen. For New Entrants and Emerging Players: Remote proctoring and telemedicine-enabled physician training represent underserved service layers where incumbents under-invest. Concentrate initial penetration on biodegradable polymer stents for benign stricture management in pediatric and transplant centers, segments where removability protocols outweigh brand loyalty. Pursue FDA breakthrough device designation pathways to compress regulatory timelines against established competitors with extensive predicate portfolios. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with drug-eluting stent platforms and systematic registry participation infrastructure, generating sustained post-market surveillance income streams. Viability over extended horizons favors targets with in-house nitinol processing capabilities and established PMDA biocompatibility dossiers. Monitor FDA 510(k) pathway revision announcements as inflection indicators for regulatory barrier shifts affecting entrant economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Systematic registry participation mandates in Germany extend incumbent data advantages over new submissions. |
| Navigation Platform Bundling | United States GPO consolidation in Texas and Florida rewards integrated bronchoscopy ecosystem providers. |
| Biodegradable Polymer R&D | Magnesium alloy and polylactic acid platforms open temporary scaffolding applications in benign stricture management. |
| Remote Proctoring Infrastructure | Telemedicine-enabled training reduces geographic barriers to complex stent deployment technique dissemination. |
| Backward Integration into Nitinol Supply | Captive metallurgy capabilities insulate against premium-grade nickel-titanium alloy input cost volatility. |
Study Parameters
Operator-level perspectives from interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA reimbursement bulletins, and hospital procurement contract filings. Bottom-up procedural volume estimates triangulated with top-down manufacturer capacity assessments across self-expanding, balloon-expandable, and polymer stent categories.
Sensitivity analysis tested forecast robustness against regulatory timeline variations, nitinol alloy price volatility, and reimbursement code expansion scenarios across the projection horizon. Segmentation modeling incorporated product type, delivery mode, end user, and application dimensions alongside geography-specific regulatory cluster effects. CAGRs derived from installed base growth, replacement cycle frequencies, and technology substitution rates for drug-eluting versus bare-metal platforms. Procedure migration from inpatient to ambulatory settings and interventional pulmonology fellowship pipeline capacity informed utilization assumptions.
Underlying assumptions cover EU MDR conformity assessment timeline stability, PMDA reimbursement expansion continuity, and nitinol alloy supply concentration persistence, with deviation risk concentrated in regulatory pathway revisions and health system procurement consolidation accelerants. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Snare Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Embryo Transfer Catheters Market