
 Global Cardiac Prosthetic Devices Market | 2026-2036
Global Cardiac Prosthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Prosthetic Devices Market Foresight
Remote monitoring subscription services is pivoting how cardiac prosthetic vendors capture lifetime value from each implant. Abbott Laboratories leverages its proprietary connectivity infrastructure to sustain recurring revenue streams across its pacemaker installed base. Edwards Lifesciences anchors its competitiveness in transcatheter valve platforms through specialized manufacturing scale in Irvine, California. Medtronic navigates pricing pressures by dominating the service-contract layer for ventricular assist device maintenance.
Cardiac prosthetic devices encompass implantable and transcatheter systems engineered from pyrolytic carbon, biological tissues, and titanium alloys to replace or assist native heart structures, typically functioning within physiological parameters of 60-180 beats per minute and pressure gradients below 20 mmHg. Their primary commercial purpose centers on restoring hemodynamic competence in patients with valvular dysfunction, conduction abnormalities, or terminal heart failure. Bioprosthetic heart valves command the deepest margin pools due to tissue-processing complexity and premium pricing in valve repair applications. Leadless pacemakers represent the fastest-expanding technology segment, displacing traditional transvenous systems in electrophysiology clinics seeking reduced complication profiles. Mechanical valves retain entrenched positions in emerging cardiac surgery centers where long-term durability outweighs anticoagulation burdens.
The FDA's breakthrough device program and the European Medicines Agency's MDR framework jointly shape product development timelines, with EMA's stricter clinical-evidence requirements extending CE-marking durations for novel bioprosthetic platforms. Japan's Ministry of Health, Labour and Welfare imposes supplementary reimbursement reviews that filter which programmable cardiac resynchronization therapy devices reach national health insurance listings. Stakeholders must weigh regulatory capital requirements against the accelerating shift toward rechargeable and wireless technologies that promise to redefine patient monitoring economics.
Market Dynamics
Wireless telemetry integration is compressing the service-contract layer for cardiac prosthetic vendors, forcing incumbents to restructure recurring revenue models around real-time patient data streams rather than episodic device sales.
Growth Catalysts
- Leadless pacemaker platforms:Electrophysiology clinics in Germany are prioritizing transcatheter delivery systems that eliminate lead-related complications. The FDA's breakthrough device designation accelerates commercial pathways for these implantable units.
- EMA MDR clinical-evidence pathways:Stricter European safety frameworks paradoxically reward early movers with durable CE-marking advantages. Bioprosthetic valve manufacturers investing in longitudinal outcome databases capture preferential reimbursement positioning.
- Japan's metropolitan cardiac centers:Aging patient corridors in Tokyo and Osaka are driving capital expenditure toward wireless monitoring infrastructure. The Ministry of Health, Labour and Welfare's supplementary reimbursement reviews favor programmable cardiac resynchronization therapy systems.
Market Restraints
- Pyrolytic carbon supply concentration:Specialized graphite suppliers in Japan and the United States control substrate feedstock for mechanical valve housings. Any disruption to these dual-source nodes propagates through the tier-one device manufacturing base.
- Anticoagulation burden persistence:Mechanical valves require lifelong warfarin therapy, limiting addressable populations in markets with fragmented cardiology follow-up infrastructure. Patient compliance gaps in emerging cardiac surgery centers constrain volume expansion.
- Biological tissue processing complexity:Bovine and porcine pericardial sourcing faces batch-to-batch variability that extends quality-assurance timelines. Tissue bank certification standards in Europe and North America add fixed cost layers that resist scale economies.
Strategic Opportunities
- Rechargeable ventricular assist devices:Transcutaneous power transfer eliminates driveline infection vectors that currently drive rehospitalization. Japanese and South Korean health technology assessment bodies are piloting reimbursement carve-outs for these next-generation systems.
- Remote monitoring subscription unbundling:Device vendors can decouple hardware from connectivity services, creating standalone SaaS revenue pools. Cardiac surgery centers in the United States are negotiating multi-year telemetry contracts independent of implant procurement.
- ISO 14155 harmonization:Global clinical-investigation standards are converging, reducing redundant trial designs for bioprosthetic platforms. Manufacturers can leverage single-study protocols across FDA, EMA, and PMDA submissions.
Industry Challenges
- Electrophysiology specialist scarcity:Leadless pacemaker implantation demands catheter-navigation expertise that outpaces fellowship training throughput. Academic medical centers in Germany and the United States are competing for the same limited talent pool.
- Legacy system integration friction:Wireless monitoring platforms must interface with hospital IT architectures that still rely on proprietary pacemaker programmer protocols. Interoperability certification timelines add six to nine months to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Prosthetic Devices Market |
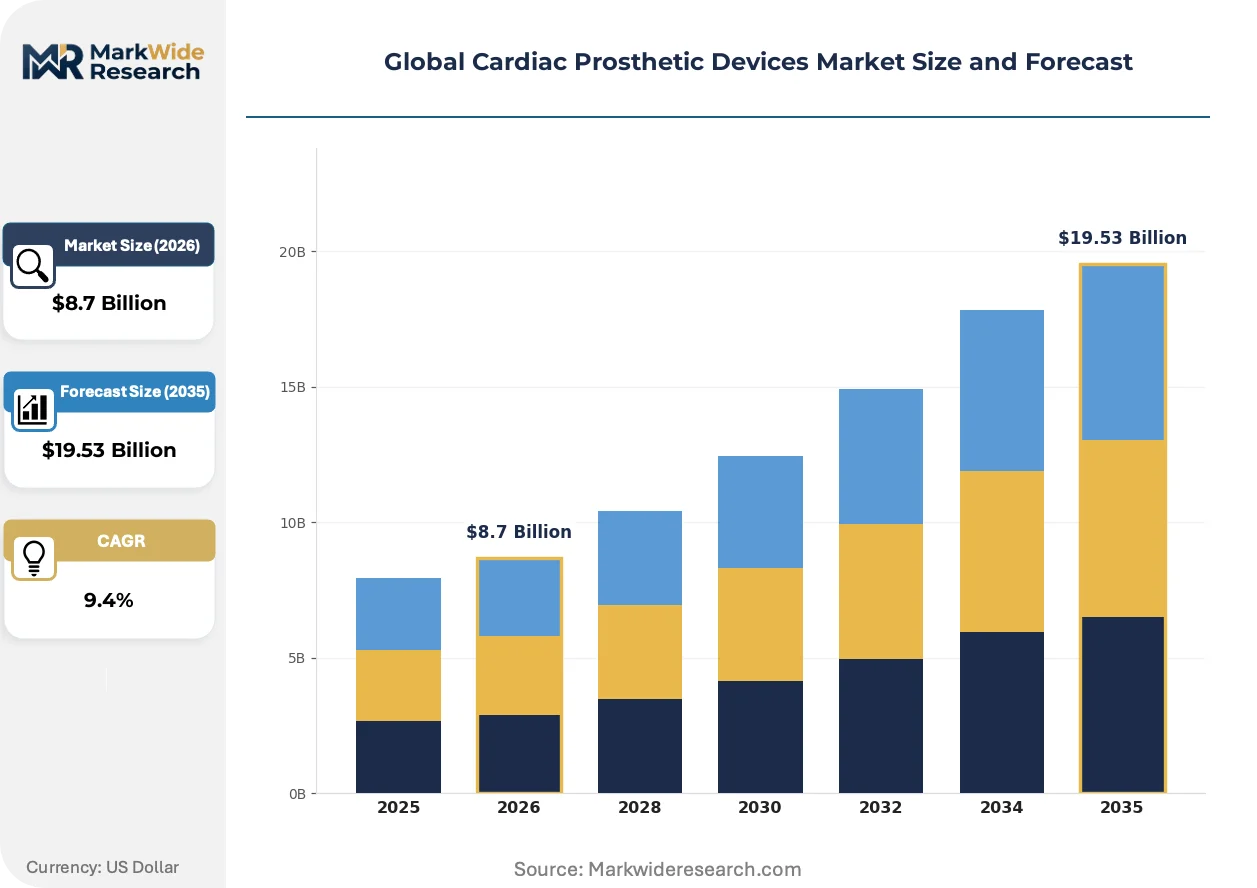
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
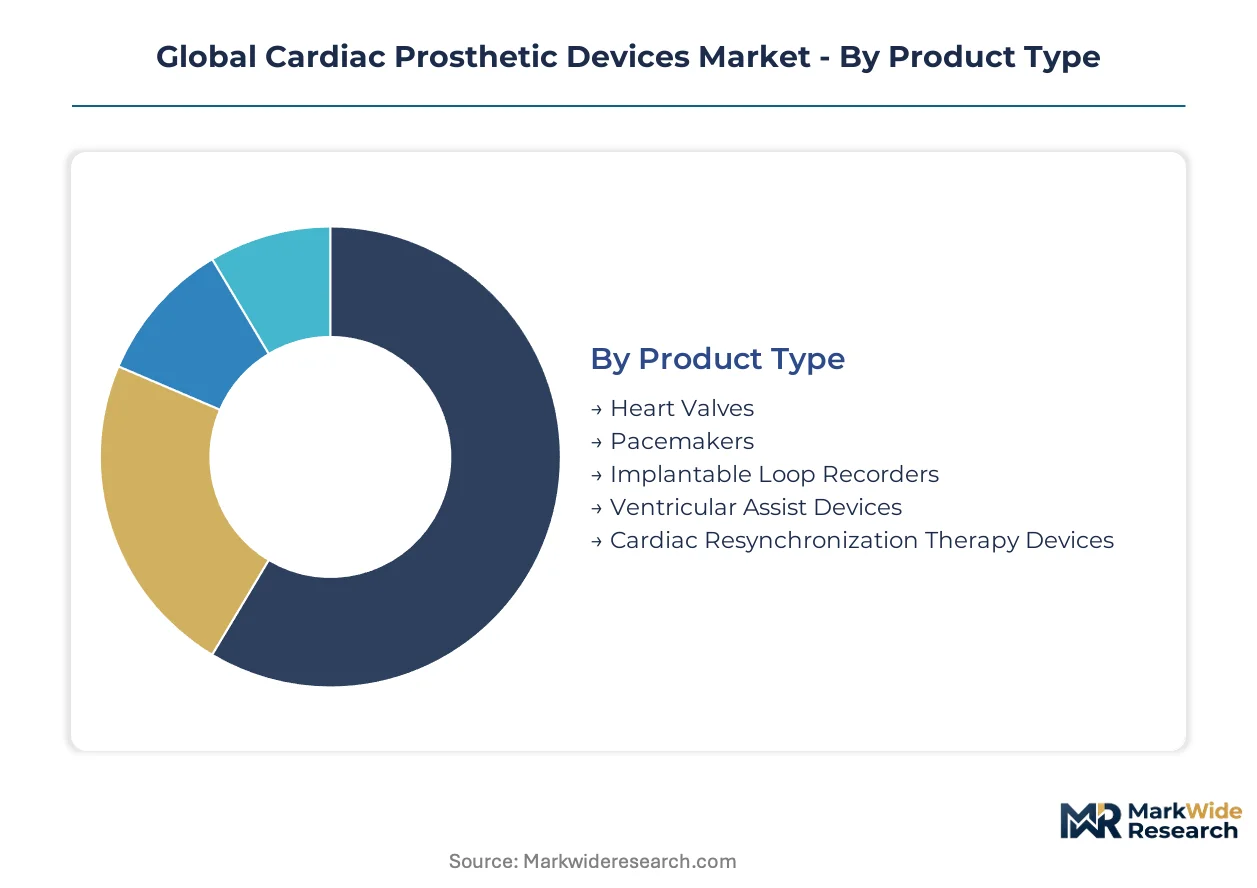
| Segmentation | Product Type: Heart Valves, Pacemakers, Implantable Loop Recorders, Ventricular Assist Devices, Cardiac Resynchronization Therapy Devices Technology: Bioprosthetic, Mechanical, Leadless, Wireless, Rechargeable, Programmable Application: Arrhythmia Management, Valve Repair, Heart Failure Support, Cardiac Monitoring, Rhythm Control End User: Cardiac Surgery Centers, Electrophysiology Clinics, Specialized Cardiology Hospitals, Diagnostic Laboratories, Rehabilitation Facilities |
| Companies Covered | Abbott Laboratories, Medtronic plc, Edwards Lifesciences Corporation, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, LivaNova, Lepu Medical Technology (Beijing) Co., Ltd, Meril Life Sciences, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Prosthetic Devices Market Shifts & Advancements
Connectivity architectures are fragmenting the traditional cardiac device value chain, enabling new entrants to capture data-layer margins previously monopolized by implant manufacturers. This structural shift rewards platform-agnostic software vendors while pressuring hardware-centric incumbents.
Leadless pacemaker technology is decentralizing electrophysiology service delivery away from high-volume tertiary centers. Community hospitals in the United States are acquiring catheter-lab capabilities previously restricted to academic institutions. This geographic diffusion is compressing patient travel burdens and redistributing procedure volumes across smaller metropolitan markets.
The European Medicines Agency's MDR framework is extending clinical-evidence requirements for novel bioprosthetic valves. Manufacturers must now submit ten-year durability data rather than five-year benchmarks. Transcatheter aortic valve platforms face the steepest compliance ramps, with several products delayed in CE-marking queues pending supplementary follow-up studies.
Hospital procurement committees are unbundling device selection from long-term service agreements. Cardiac surgery centers in Japan now negotiate hardware and telemetry contracts through separate vendor relationships. This purchasing bifurcation is most visible in metropolitan Tokyo, where three-tier contract structures separate implant vendors from remote monitoring specialists.
Global Cardiac Prosthetic Devices Market Segmentation
Cardiac prosthetic vendors configure their product portfolios around distinct clinical workflows and reimbursement pathways. Segment boundaries reflect where capital expenditure decisions cluster and where regulatory approvals create addressable market tiers.
Product Type:
Purchasing committees prioritize clinical outcome metrics and total cost of ownership when allocating capital across implant categories.
- Heart Valves:Engineered from pyrolytic carbon, biological tissues, or titanium alloys to replace native valvular structures. German specialized cardiology hospitals and Japanese cardiac surgery centers concentrate demand here, driven by aging populations requiring transcatheter aortic valve replacement.
- Pacemakers:Implantable pulse generators delivering electrical stimulation at 60-180 beats per minute. Leadless variants are displacing traditional transvenous systems in United States electrophysiology clinics seeking reduced lead-related complication profiles.
- Implantable Loop Recorders:Subcutaneous devices capturing extended cardiac rhythm data.
- Ventricular Assist Devices:Mechanical pumps supporting terminal heart failure patients.
- Cardiac Resynchronization Therapy Devices:Biventricular pacemakers restoring coordinated contraction.
Volume sits with Heart Valves; growth tilts toward Leadless Pacemakers.
Technology:
Material science capabilities and power management architectures differentiate competitive positioning across technology tiers.
- Bioprosthetic:Processed bovine or porcine tissues forming valve leaflets with hemodynamic profiles mimicking native anatomy. EMA MDR ten-year durability requirements favor manufacturers with longitudinal outcome databases.
- Mechanical:Pyrolytic carbon and titanium constructs offering lifelong durability. Emerging cardiac surgery centers in markets with fragmented follow-up infrastructure favor these despite anticoagulation burdens.
- Leadless:Self-contained pacemaker units delivered via catheter.
- Wireless:Telemetry-enabled platforms transmitting patient data.
- Rechargeable:Transcutaneous power transfer eliminating battery replacement surgeries.
- Programmable:Software-configurable parameter sets.
Bioprosthetic commands the deepest margin pools; Rechargeable platforms are climbing the fastest.
Application:
Procedure reimbursement codes and clinical evidence requirements shape where manufacturers direct product development resources.
- Arrhythmia Management:Rhythm correction through electrical intervention or pharmacological pacing. United States electrophysiology clinics and German specialized cardiology hospitals drive procedure volumes for implantable solutions.
- Valve Repair:Structural restoration of regurgitant or stenotic valves. Japanese metropolitan cardiac centers concentrate capital expenditure here, with Tokyo and Osaka facilities upgrading to transcatheter delivery platforms.
- Heart Failure Support:Mechanical circulatory assistance for end-stage patients.
- Cardiac Monitoring:Continuous rhythm surveillance and event detection.
- Rhythm Control:Restoration of normal sinus electrical patterns.
Valve Repair captures the largest revenue concentration; Arrhythmia Management shows the steepest expansion trajectory.
End User:
Facility certification tiers and physician specialization depth determine product qualification and procurement pathways.
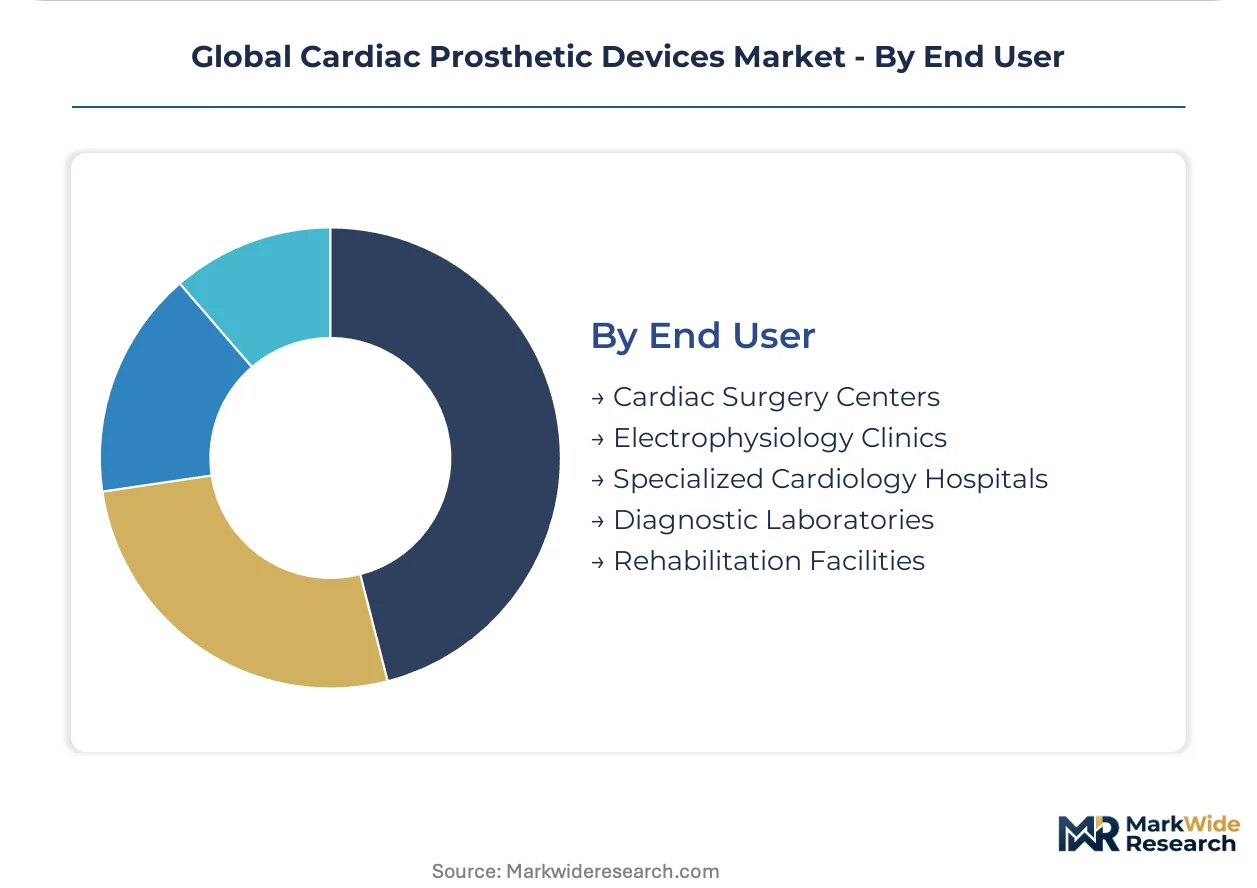
- Cardiac Surgery Centers:Tertiary facilities performing open and minimally invasive structural interventions. Japan's aging metropolitan corridors concentrate demand, with centers negotiating separate hardware and telemetry contracts.
- Electrophysiology Clinics:Specialized units focusing on rhythm disorders and device implantation. Community hospitals in the United States are acquiring catheter-lab capabilities previously restricted to academic institutions.
- Specialized Cardiology Hospitals:Dedicated cardiovascular disease treatment facilities.
- Diagnostic Laboratories:Pre-implant assessment and post-procedure monitoring services.
- Rehabilitation Facilities:Post-acute care and device patient management.
Cardiac Surgery Centers anchor installed base value; Electrophysiology Clinics are gaining share fastest through geographic diffusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Japan, and the United States, while consumption tilts toward aging corridors in Japan and metropolitan clusters in Germany and the United States where cardiac surgery infrastructure is expanding.
United States
Community hospitals are acquiring catheter-lab capabilities previously restricted to academic medical centers, redistributing leadless pacemaker procedures across smaller metropolitan markets. The FDA's breakthrough device designation accelerates commercial pathways for novel implantable systems. Boston and the Research Triangle anchor electrophysiology training pipelines that feed national specialist demand.
Germany
Specialized cardiology hospitals in Munich and Heidelberg are expanding electrophysiology departments to accommodate complex transcatheter valve procedures. EMA MDR ten-year durability requirements favor manufacturers with longitudinal outcome databases established before stricter frameworks took effect. The Baden-Württemberg medical technology corridor concentrates bioprosthetic valve processing expertise.
Japan
Aging patient corridors in Tokyo and Osaka are driving capital expenditure toward wireless monitoring infrastructure for cardiac resynchronization therapy systems. PMDA supplementary reimbursement reviews filter which programmable devices reach national health insurance listings. The Kansai region's cardiac surgery centers are negotiating separate hardware and telemetry contracts, bifurcating traditional vendor relationships.
China
Domestic manufacturers are scaling bioprosthetic tissue processing capabilities to reduce import dependence for valve repair applications. NMPA regulatory pathways are harmonizing with international standards, though clinical-evidence requirements remain more stringent for foreign entrants. The Yangtze River Delta medical device cluster is attracting venture capital for rechargeable ventricular assist device development.
Switzerland
Swissmedic maintains streamlined approval pathways for breakthrough cardiac devices, positioning Geneva and Zurich as regulatory launch pads for European market entry. Precision manufacturing heritage in the Lake Geneva region supports pyrolytic carbon component sourcing for mechanical valve housings. Basel's pharmaceutical-industrial complex is cross-pollinating tissue engineering expertise into bioprosthetic platforms.
Global Cardiac Prosthetic Devices Market Competitive Landscape
Top-tier vendors anchor the premium implant segment, while mid-scale specialists and regional fabricators occupy differentiated technology tiers. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with connectivity infrastructure, pure-play cardiovascular specialists with manufacturing scale, and emerging regional champions with cost-optimized production. Consolidation pressures favor M&A activity targeting telemetry capabilities and backward integration into biological tissue processing.
Within the diversified conglomerate tier, Abbott Laboratories and Medtronic plc exemplify platform-agnostic connectivity strategies that extract recurring revenue from installed device bases. Edwards Lifesciences Corporation occupies a position representing specialized manufacturing scale in transcatheter valve platforms. Among Asia-Pacific entrants, Lepu Medical Technology (Beijing) Co., Ltd and MicroPort Scientific Corporation sit within the regional champion archetype, leveraging domestic regulatory familiarity and cost-optimized production to capture share in price-sensitive procurement environments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Edwards Lifesciences Corporation |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| LivaNova |
| Lepu Medical Technology (Beijing) Co., Ltd |
| Meril Life Sciences |
| MicroPort Scientific Corporation |
| Others |
Supply & Pricing Matrix
Electrophysiology specialist concentration in the Research Triangle and Baden-Württemberg corridor creates labor-cost differentials that widen pricing-tier spreads between premium catheter-lab installations and standard community hospital deployments.
Pricing Analysis
Cost-down pressure on bioprosthetic valve tiers accelerates because EMA MDR ten-year durability requirements force manufacturers to absorb extended clinical-trial overhead. Three-tier pricing structure across premium, standard, and economy levels separates transcatheter platforms with longitudinal databases from mechanical valves with simpler certification pathways. Price differentiation traces to tissue-processing certification grade and after-sales telemetry bundling. Japanese cardiac surgery centers exhibit highest price sensitivity due to bifurcated hardware-telemetry procurement, while German specialized cardiology hospitals prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta medical device cluster are reshaping sourcing patterns for biological tissue processing equipment. Pyrolytic carbon substrate concentrates in Japanese and United States dual-source nodes, while bovine and porcine pericardial tissue banks anchor in European and North American certification jurisdictions. Raw material dependencies rest on specialized graphite suppliers, tissue bank certification standards, and titanium alloy feedstock. Single-source vulnerability propagates through tier-one manufacturing bases during batch-to-batch variability events. Distribution runs through hospital procurement committees negotiating separate vendor relationships for implants and monitoring services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from wireless telemetry unbundling will eliminate hardware-centric vendors lacking connectivity infrastructure, compressing the vendor base toward platform-agnostic data-layer specialists.
For Market Incumbents: Acquire telemetry software capabilities to capture recurring revenue streams previously monopolized by standalone connectivity vendors. Abbott Laboratories and Medtronic plc exemplify this defensive posture through proprietary infrastructure sustaining service-contract layers. Backward integration into biological tissue processing secures margin pools against emerging regional champions with cost-optimized production. Dominating the rechargeable ventricular assist device maintenance layer insulates against pricing pressure from Japanese and South Korean health technology assessment pilots. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass incumbent GPO contracting advantages in United States community hospital electrophysiology expansion. White-space targets concentrate in leadless pacemaker catheter-lab capabilities for metropolitan markets below 500,000 population. Reimbursement carve-out pilot programs in Japan and South Korea for transcutaneous power transfer systems present the most penetrable entry vector. Partner with academic medical center training pipelines to overcome electrophysiology specialist scarcity constraining procedure volume growth. For Investors and Strategic Acquirers: Re-rating potential sits with bioprosthetic tissue processing specialists given EMA MDR durability database requirements extending CE-marking timelines for competitors. Long-term viability favors manufacturers with established longitudinal outcome repositories spanning ten-year follow-up protocols. Acquisition target archetypes include pure-play cardiovascular specialists with manufacturing scale in transcatheter platforms but underdeveloped telemetry SaaS revenue. Watch for FDA breakthrough device designation announcements as inflection indicators for leadless pacemaker commercial acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercial pathways for leadless pacemakers in United States electrophysiology clinics. |
| CE Marking Pathway Investment | Ten-year durability databases secure preferential reimbursement positioning under EMA MDR frameworks. |
| Hospital System Partnership | Tokyo and Osaka cardiac centers negotiate bifurcated hardware-telemetry contracts reshaping vendor relationships. |
| Software Companion Development | Remote monitoring subscription unbundling creates standalone SaaS revenue pools independent of implant sales. |
| Reimbursement Strategy | PMDA supplementary reviews filter programmable cardiac resynchronization therapy devices reaching national insurance listings. |
Research Methodology
Independent corroboration across hospital purchasing committees, biomedical engineers, GPO contracts managers, and electrophysiology specialists underwrites the qualitative findings in this study. Primary interviews with clinicians and regulatory affairs leads at specialized cardiology hospitals in Germany, Japan, and the United States combined with secondary validation from FDA filings, EMA MDR submission databases, PMDA reimbursement listings, and hospital procurement records. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensure cross-verified outputs.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and technology mix shifts. Segmentation dimensions modeled include product type, material technology tier, application workflow, and end-user facility certification level. CAGRs derive from procedure volume projections, implant penetration curves, and reimbursement pathway maturation timelines. Industry-specific forecast inputs incorporate electrophysiology specialist training throughput and wireless telemetry platform adoption rates.
Inputs from regulatory submission databases and hospital capital expenditure records were available through the study window; gaps in longitudinal bioprosthetic durability data introduce uncertainty bands around ten-year outcome projections. Forecasts reflect assumptions regarding EMA MDR enforcement consistency and PMDA reimbursement review timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Integration Systems Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Intubation Accessories Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Intubation Tubes Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Global Transcranial Magnetic Stimulators Market