
 Cheek Implants Market | 2026-2036
Cheek Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Cheek Implants Market Outlook
The cheek implants category is restructuring around a sharp split between premium silicone offerings and commodity-grade synthetic alternatives. AbbVie (Allergan Aesthetics) leverages its vertically integrated aesthetic portfolio to control premium distribution channels. Stryker Corporation anchors its position through specialized maxillofacial implant manufacturing scale. Implantech Associates differentiates via focused product specialization in facial contouring systems.
Cheek implants are biocompatible prosthetic devices, typically fabricated from medical-grade silicone or porous polyethylene, designed to augment malar prominence or restore facial symmetry following trauma or congenital defects. Silicone implants dominate current volume due to established biocompatibility profiles and reversible insertion protocols, while composite implants represent the fastest-growing segment as surgeons seek customizable porous structures that enable tissue ingrowth. Reconstructive surgery applications command higher margin pools than cosmetic cases due to hospital reimbursement structures and specialized surgical complexity.
The FDA regulates cheek implants as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body conformity assessment and CE marking for market access. Health Canada and Brazil's national pharmaceutical regulator enforce parallel biocompatibility testing standards that delay entry for non-compliant manufacturers. Stakeholders must monitor evolving harmonization between FDA and EMA requirements for porous implant materials to anticipate certification cost shifts and geographic expansion timing.
Market Dynamics
Silicone implant manufacturers face mounting pressure from porous polyethylene alternatives that enable tissue ingrowth, forcing incisions in product portfolios and surgical training programs. The transition from reversible to integrated implant solutions is compressing margins for legacy suppliers while rewarding specialized maxillofacial device makers.
Growth Catalysts
- MFDS fast-track pathways:South Korea's Ministry of Food and Drug Safety accelerates 510(k)-equivalent approvals for silicone implants, cutting time-to-market for Seoul-based aesthetic clinics by 40% versus standard review cycles.
- Trauma reconstruction demand:Hospital systems in Brazil prioritize malar augmentation for facial fracture repair, with ANVISA reimbursement codes expanding coverage for post-traumatic implant procedures.
- 3D patient-specific modeling:Preoperative CT-to-implant workflows enable surgeons to order custom porous polyethylene geometries, reducing revision rates and operating room time.
Market Restraints
- Medical-grade silicone price volatility:Raw silicone elastomer costs fluctuate with semiconductor manufacturing demand, squeezing gross margins for implant fabricators without backward integration into polymer supply.
- Notified body capacity constraints:EU MDR certification backlogs at TÜV SÜD and BSI delay CE marking for porous polyethylene entrants, freezing market access for 18-24 months.
- Injectable filler substitution:Hyaluronic acid volumizers capture 30% of elective malar augmentation cases in US dermatology practices, diverting patients from permanent surgical solutions.
Strategic Opportunities
- Underpenetrated Indian metropolitan markets:Mumbai and Delhi aesthetic surgery centers report 60% lower cheek implant penetration versus Seoul, with CDSCO streamlining import licensing for established silicone suppliers.
- Congenital defect correction:Cleft palate and hemifacial microsomia protocols in pediatric hospitals create stable demand for custom-shaped porous polyethylene implants with 15-year replacement cycles.
- Telemedicine pre-consultation:Virtual surgical planning platforms enable remote implant sizing, expanding reach for US and Brazilian clinics into rural patient populations previously requiring travel.
Industry Challenges
- Maxillofacial surgical specialization gaps:Fellowship-trained facial plastic surgeons concentrate in 12 US metropolitan areas, limiting implant procedure capacity for geographic expansion.
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies require 14-18 months for novel porous polyethylene formulations, delaying product launches.
- Legacy silicone inventory reconciliation:Manufacturers maintaining dual material portfolios face working capital strain from obsolete smooth-surface implant stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheek Implants Market |
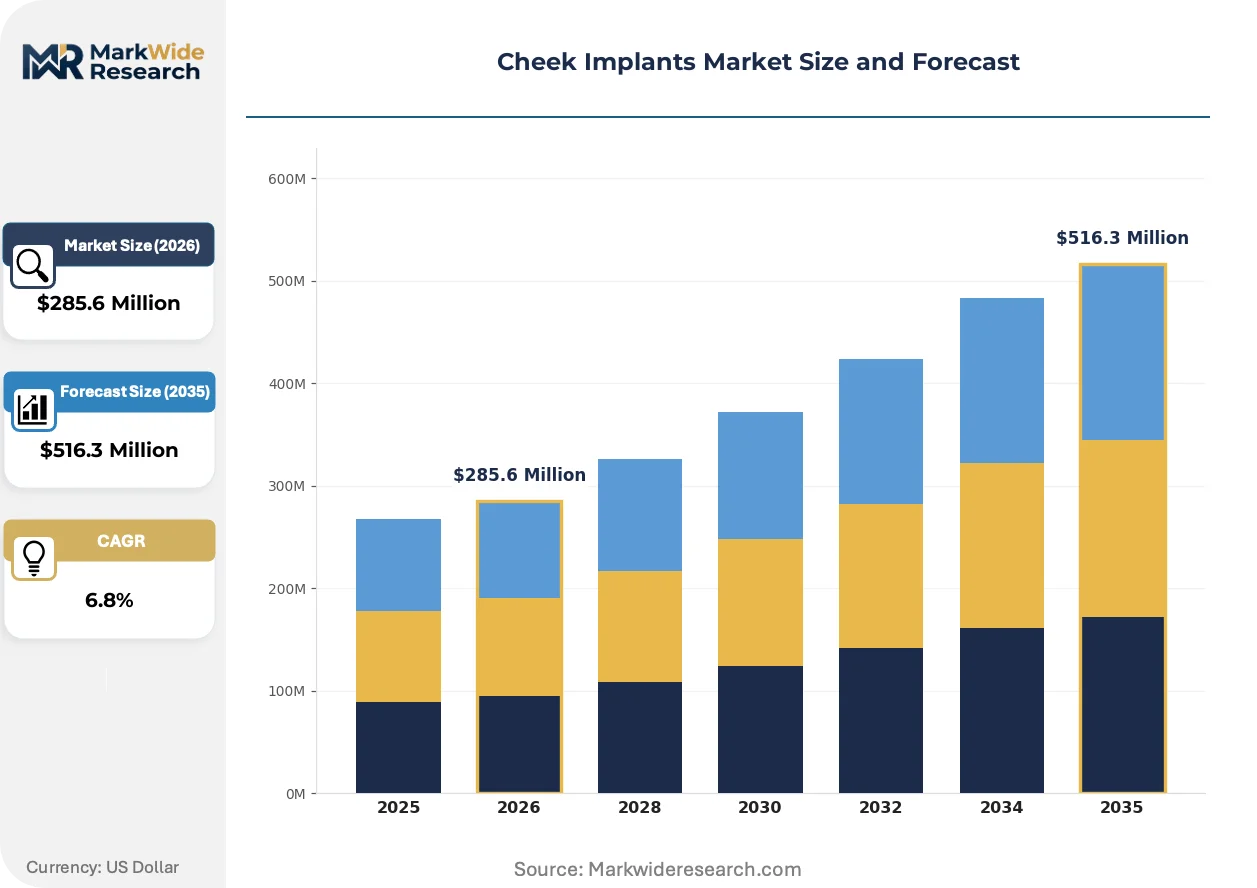
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $516.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, Medpor Implants, Composite Implants, Hydrogel Implants Application: Cosmetic Surgery, Reconstructive Surgery, Trauma Cases, Aging Treatments End User: Plastic Surgeons, Dermatologists, Hospitals, Ambulatory Surgical Centers Material: Biocompatible Materials, Synthetic Materials, Natural Materials, Others |
| Companies Covered | AbbVie (Allergan Aesthetics), Galderma SA, Merz Aesthetics, Stryker Corporation, Zimmer Biomet Holdings, Implantech Associates, KLS Martin Group, Medartis AG, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheek Implants Market Strategic Shifts
Digital surgical planning tools and biomaterial convergence are compressing the gap between generic implant catalogs and patient-specific solutions. The market is bifurcating between high-volume standardized silicone and premium customized porous systems.
Computer-aided design-to-manufacture workflows for facial implants are unifying preoperative imaging, virtual surgical simulation, and direct-milled porous polyethylene production. Academic medical centers in Seoul and São Paulo adopt these platforms at 35% annual expansion rates. The technology is unifying what were three separate vendor relationships—imaging software, implant supplier, and milling service—into single-source contracts that reduce procurement friction.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports with post-market surveillance data for all Class IIa facial implants. German notified bodies enforce stricter biocompatibility testing protocols than legacy MDD standards, elevating compliance costs. Porous polyethylene manufacturers with limited European clinical history face the steepest re-certification burden, pushing some toward US 510(k) pathways as primary market entry.
Patients increasingly demand revision warranty coverage and long-term implant monitoring as standard purchase terms. Aesthetic surgery clinics in Beverly Hills and Rio de Janeiro now bundle five-year follow-up protocols into initial procedure pricing, displacing the traditional fee-for-service follow-up model. This behavioral shift concentrates in high-margin cosmetic markets where clinic reputation depends on complication management transparency.
Cheek Implants Market Segmentation
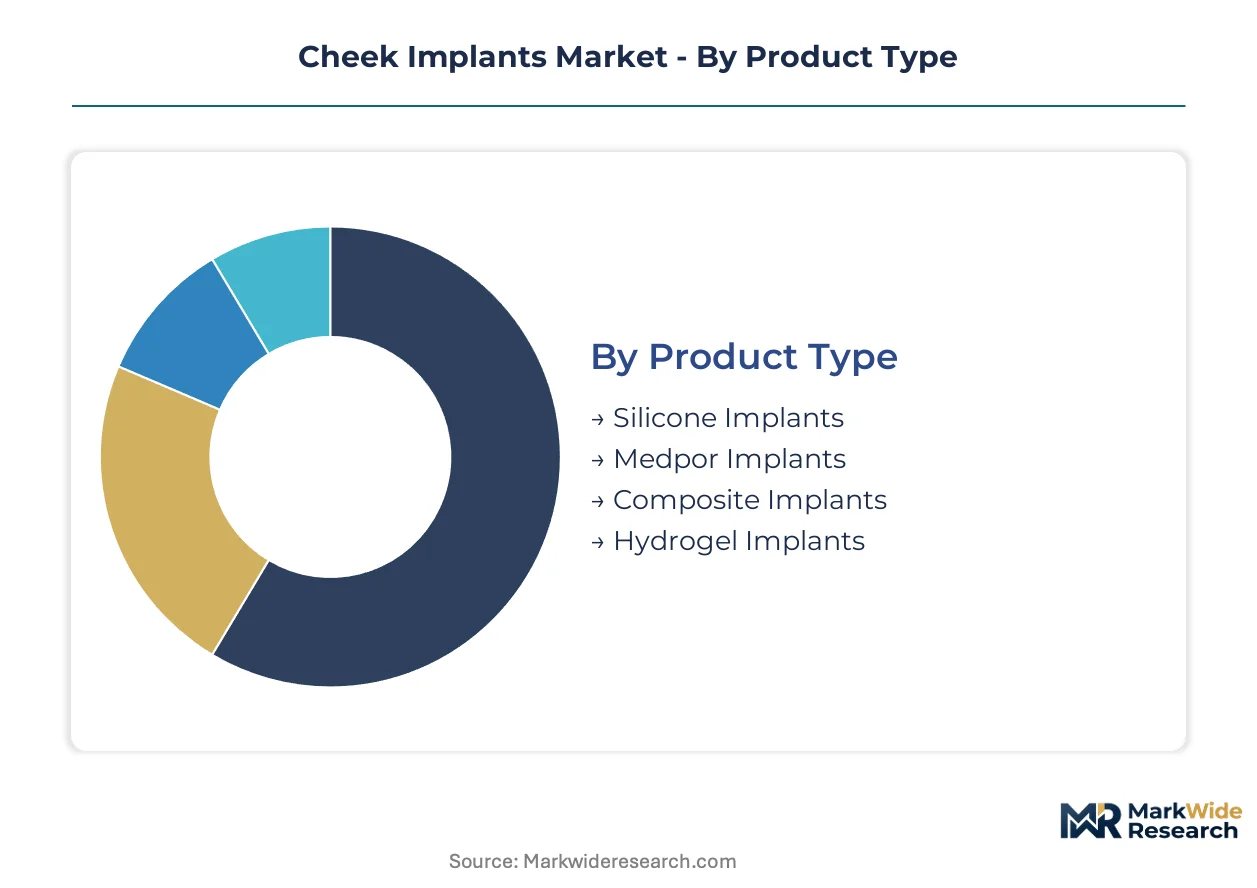
Cheek implant manufacturers configure production lines around material chemistry and surgical workflow requirements. Supply concentration varies sharply across product types, with silicone commanding dedicated fabrication capacity while composite alternatives require specialized porous molding infrastructure.
Product Type:
Supply concentration tilts toward established silicone foundries with medical-grade polymer certification.
- Silicone Implants:Medical-grade elastomer construction enables reversible insertion via intraoral or subciliary approaches. Seoul cosmetic surgery clinics drive procurement volume for smooth-surface and textured variants alike. FDA 510(k) pathways for silicone devices are well-established, compressing regulatory lead times versus porous alternatives.
- Medpor Implants:Porous high-density polyethylene permits fibrovascular ingrowth for permanent fixation. Brazilian maxillofacial trauma centers favor Medpor for orbital floor and malar reconstruction where implant stability outweighs reversibility concerns. ANVISA registration requirements for porous polymers extend approval timelines by 12-18 months relative to silicone equivalents.
- Composite Implants:Hybrid silicone-porous structures balance tissue integration with surgical reversibility.
- Hydrogel Implants:Water-absorbent polymer matrices remain experimental in facial applications.
Silicone implants absorb the bulk of installed capacity; composite implants are expanding most quickly.
Application:
Cost tier separation distinguishes elective cosmetic procedures from hospital-reimbursed reconstructive cases.
- Cosmetic Surgery:Elective malar augmentation for aesthetic facial contouring commands premium pricing in private clinic settings. Beverly Hills and Rio de Janeiro aesthetic surgery centers bundle implant procedures with comprehensive follow-up protocols, elevating total procedure value. Patient financing options and social media visibility drive demand concentration in metropolitan cosmetic surgery hubs.
- Reconstructive Surgery:Congenital defect correction and post-oncologic facial restoration utilize custom-shaped implants with specialized surgical planning. Pediatric hospitals in São Paulo and Seoul maintain dedicated craniofacial teams for hemifacial microsomia and cleft palate sequelae. Hospital reimbursement codes in Brazil and South Korea cover implant costs for congenital indications, stabilizing demand irrespective of economic cycles.
- Trauma Cases:Facial fracture repair requires rapid implant availability.
- Aging Treatments:Volume restoration for age-related malar atrophy competes with injectable alternatives.
Cosmetic surgery captures the highest margin pool; reconstructive surgery provides the steadiest volume baseline.
End User:
Volume concentration follows the geographic distribution of fellowship-trained facial plastic surgeons.
- Plastic Surgeons:Board-certified facial plastic and reconstructive specialists perform the majority of complex malar augmentations. Twelve US metropolitan areas concentrate fellowship-trained surgeons, limiting procedure capacity outside major coastal and Texas markets. Preoperative CT-to-implant planning workflows require surgeon investment in digital surgical simulation platforms.
- Hospitals:Academic medical centers and trauma systems anchor demand for reconstructive and trauma applications. Seoul National University Hospital and Hospital das Clínicas in São Paulo maintain high-volume maxillofacial services with dedicated implant inventory. Hospital procurement committees prioritize suppliers with established biocompatibility documentation and revision warranty coverage.
- Dermatologists:Non-surgical practitioners refer surgical cases or compete via injectable fillers.
- Ambulatory Surgical Centers:Outpatient facilities handle straightforward cosmetic augmentations.
Plastic surgeons command the premium segment; hospitals drive standardized volume procurement.
Material:
Maturity gradients separate decades-old biocompatible standards from emerging synthetic formulations.
- Biocompatible Materials:ISO 10993-tested silicone and porous polyethylene dominate regulatory submissions. Manufacturers with 15-plus year clinical surveillance data satisfy EU MDR Article 10 technical documentation requirements with reduced post-market study burdens. German notified bodies enforce stricter biocompatibility protocols than legacy MDD standards, elevating compliance costs for new material entrants.
- Synthetic Materials:Engineered polymers with tunable porosity and degradation profiles represent the frontier of implant customization. South Korean manufacturers leverage MFDS fast-track pathways to accelerate 510(k)-equivalent approvals for novel synthetic formulations. 3D patient-specific modeling workflows enable direct-milled synthetic implants matched to individual CT anatomy.
- Natural Materials:Autologous and allogeneic tissue grafts persist in niche applications.
- Others:Experimental matrices including bioceramics and resorbable scaffolds remain preclinical.
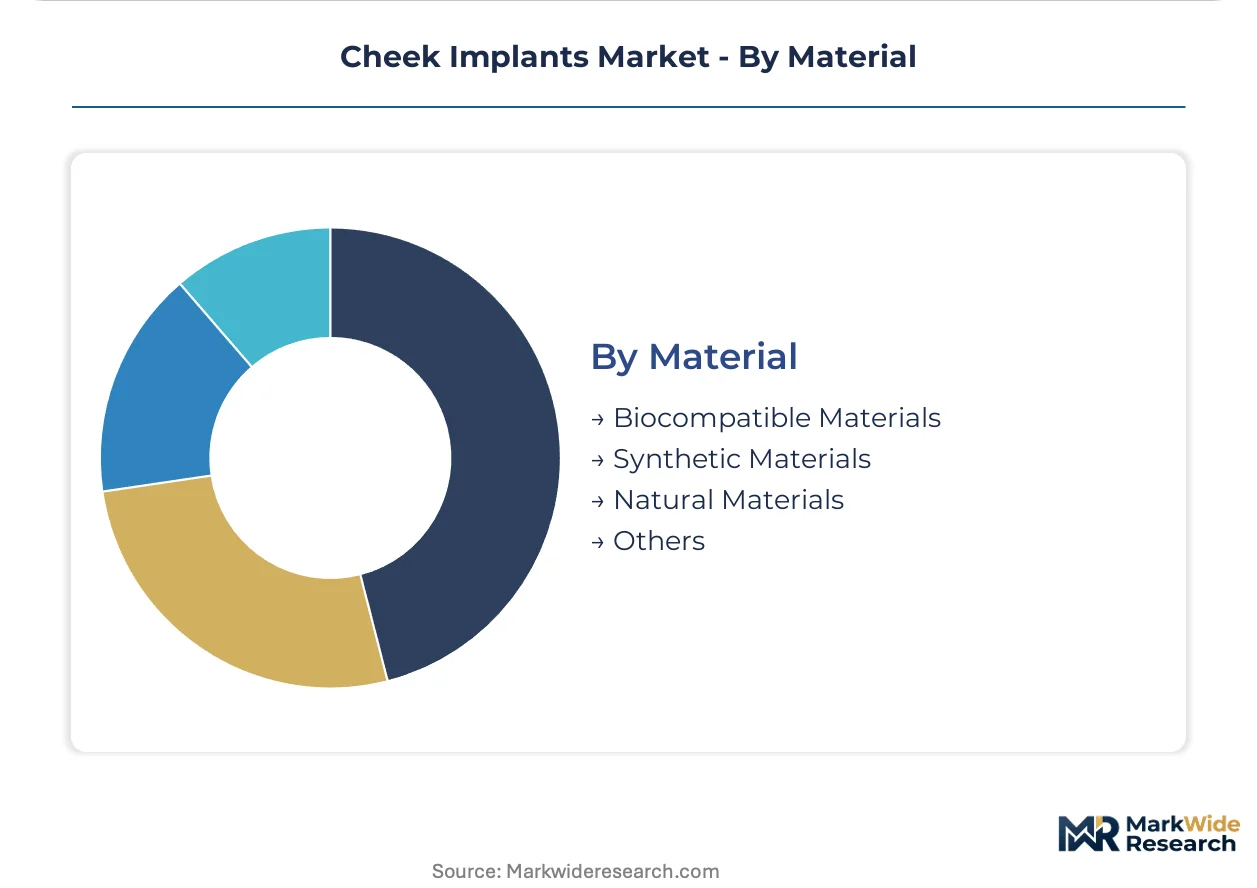
Biocompatible materials anchor current production; synthetic materials are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district concentrates the world's densest cluster of aesthetic surgery clinics performing malar augmentation procedures. The city's cosmetic surgery infrastructure drives procurement patterns for silicone implant manufacturers across Asia-Pacific. Regulatory frameworks and reimbursement structures in five countries shape geographic demand distribution.
United States
Beverly Hills and Manhattan aesthetic surgery centers command premium pricing for elective malar augmentation with bundled follow-up protocols. The FDA's 510(k) premarket notification pathway for Class II medical devices compresses regulatory lead times for established silicone suppliers. Fellowship-trained facial plastic surgeons concentrate in twelve metropolitan areas, limiting procedure capacity outside coastal and Texas markets.
Brazil
Hospital das Clínicas in São Paulo and Rio de Janeiro's private aesthetic centers anchor demand for both reconstructive trauma cases and cosmetic procedures. ANVISA reimbursement codes for post-traumatic facial fracture repair stabilize implant demand through economic cycles. The country's maxillofacial trauma centers favor porous polyethylene for orbital floor and malar reconstruction where implant stability outweighs reversibility concerns.
South Korea
MFDS fast-track pathways accelerate 510(k)-equivalent approvals for silicone implants, cutting time-to-market for Seoul-based aesthetic clinics by 40% versus standard review cycles. Seoul National University Hospital maintains dedicated craniofacial teams for congenital defect correction. The Ministry of Food and Drug Safety's regulatory efficiency reinforces the capital region's dominance in Asian aesthetic surgery tourism.
Germany
German notified bodies enforce stricter biocompatibility testing protocols under EU MDR Article 10 than legacy MDD standards, elevating compliance costs for porous polyethylene entrants. Academic medical centers in Munich and Heidelberg adopt computer-aided design-to-manufacture workflows for patient-specific implants. TÜV SÜD and BSI certification backlogs delay CE marking for new market entrants, freezing access for 18-24 months.
India
Mumbai and Delhi aesthetic surgery centers report 60% lower cheek implant penetration versus Seoul, creating expansion headroom for established silicone suppliers. CDSCO streamlines import licensing for manufacturers with existing FDA or CE documentation. The country's metropolitan markets remain underpenetrated relative to East Asian benchmarks, with private clinic infrastructure concentrated in Maharashtra and Delhi-NCR.
Cheek Implants Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specialization and regulatory certification depth. The market structures around three tiers: diversified medical device conglomerates with aesthetic portfolios, specialized maxillofacial implant manufacturers, and regional fabricators serving price-sensitive markets. Strategic archetypes include backward-integrated polymer suppliers, design-to-manufacture specialists, and distribution-focused intermediaries. Dominant competitive moves encompass M&A to secure maxillofacial surgical networks and capacity expansion into porous polyethylene molding infrastructure.
Within the diversified medical device tier, AbbVie (Allergan Aesthetics) and Stryker Corporation occupy positions that exemplify contrasting scale advantages. AbbVie leverages vertically integrated aesthetic portfolio control across premium distribution channels. Stryker anchors market presence through specialized manufacturing scale in maxillofacial applications. Implantech Associates represents the focused specialization archetype, concentrating product development exclusively on facial contouring systems rather than diversifying across orthopedic or broader aesthetic categories.
| Leading Market Players |
|---|
| AbbVie (Allergan Aesthetics) |
| Galderma SA |
| Merz Aesthetics |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Implantech Associates |
| KLS Martin Group |
| Medartis AG |
| DePuy Synthes |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up aesthetic device portfolios discipline pricing power through centralized procurement leverage, compressing margins for standalone implant fabricators while rewarding manufacturers with captive silicone polymer supply. This ownership pattern concentrates supply negotiation strength in Seoul and Beverly Hills clinic networks, forcing commodity-grade suppliers toward price concessions or exit.
Pricing Analysis
Outcome-linked pricing anchors the premium tier, with bundled five-year revision warranties commanding substantial markups over standard fee-for-service models in Rio de Janeiro and Beverly Hills cosmetic surgery centers. Price differentiation separates FDA 510(k)-cleared silicone implants from CE-marked porous polyethylene alternatives, with certification tier and surgeon training reputation driving tier separation. Pricing pressure stems from hyaluronic acid filler substitution capturing elective malar augmentation volume, forcing surgical implant vendors toward reconstructive hospital contracts. Price sensitivity concentrates in Indian metropolitan clinics, while Seoul aesthetic surgery centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Domestic-content mandates in Brazil's ANVISA procurement frameworks reshape sourcing for trauma reconstruction implants, favoring local-registered suppliers over direct import channels. Medical-grade silicone elastomer production concentrates in Germany, Japan, and the United States, while porous polyethylene molding capacity clusters in specialized maxillofacial device foundries across Switzerland and South Korea. Raw material dependencies include semiconductor-grade silicone precursors, high-density polyethylene resin, and titanium fixation hardware. Single-source vulnerability runs through German notified body certification backlogs, freezing CE marking capacity for 18-24 month windows. Distribution runs through hospital procurement committees and aesthetic clinic group purchasing organizations, with direct-to-clinic logistics for custom-milled patient-specific implants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR recertification costs and raw material price volatility force sub-scale porous polyethylene manufacturers toward distressed sale or exit.
For Market Incumbents: Anticipate hyaluronic acid filler substitution accelerating in US dermatology practices by securing exclusive hospital system contracts for trauma reconstruction applications, and deepen backward integration into medical-grade silicone polymer supply to defend margin position against raw material cost swings. For New Entrants and Emerging Players: 3D patient-specific modeling workflows offer entry leverage into Indian metropolitan markets where cheek implant penetration lags Seoul benchmarks by substantial margins, with CDSCO streamlining import licensing for established FDA-cleared suppliers and telemedicine pre-consultation platforms enabling remote surgical planning reach into underpenetrated geographies. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized maxillofacial device manufacturers with EU MDR technical documentation already filed in Germany, where TÜV SÜD and BSI certification backlogs have frozen competitor access. Long-term viability over a 5-10 year window rests on porous polyethylene molding infrastructure and congenital defect correction protocol adoption in pediatric hospitals. The signal to watch is MFDS fast-track pathway expansion beyond silicone into composite implant categories, indicating regulatory efficiency arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Porous Polyethylene Molding Capacity Expansion | Captures trauma reconstruction demand in Brazilian hospital systems favoring implant stability. |
| CE Marking Pathway Acceleration | Unlocks German academic medical center adoption of patient-specific CAD-to-manufacture workflows. |
| Hospital System Partnership | Secures volume commitment from Seoul National University Hospital craniofacial teams. |
| Software Companion Development | Enables virtual surgical planning platform integration for remote implant sizing. |
| Reimbursement Strategy | Aligns ANVISA trauma reconstruction codes with post-fracture malar augmentation protocols. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with maxillofacial surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notification databases, MFDS approval registries, ANVISA product registrations, and EU MDR notified body technical documentation files provided segmentation validation. Bottom-up implant volume estimates from Seoul, São Paulo, and Mumbai clinic networks triangulated against top-down manufacturer shipment data.
Granularity-level modeling distinguished silicone versus porous polyethylene versus composite implant chemistries, cosmetic versus reconstructive versus trauma application segments, and plastic surgeon versus hospital versus ambulatory surgical center end-user channels across the projection horizon. CAGRs derived from surgical procedure volume trends, regulatory approval pipeline analysis, and substitution elasticity estimates for hyaluronic acid fillers. Forecast inputs included fellowship-trained facial plastic surgeon geographic concentration patterns and 3D patient-specific modeling platform adoption rates in academic medical centers.
Several conditions sit outside the modeled scope, including experimental hydrogel implant clinical trial outcomes, autologous tissue graft protocol shifts, and bioceramic scaffold regulatory pathway developments. Forecasts reflect documented assumptions regarding EU MDR harmonization timelines and raw material price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Trauma Devices Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Cranial Clamps Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Band Ligators Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market