
 Manual Resuscitators Market | 2026-2036
Manual Resuscitators Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Resuscitators Market Intelligence
Critical care nursing shortages across OECD health systems is unwinding capacity expansion in emergency departments and intensive care wards. Ambu A/S leverages its silicone bag manufacturing expertise to sustain dominant positions in European ambulance supply chains. Medtronic anchors North American hospital purchasing through integrated critical care portfolios spanning ventilation and resuscitation workflows. Laerdal Medical differentiates via simulation training ecosystems that bind resuscitator hardware to institutional education contracts.
A manual resuscitator is a hand-powered, positive-pressure ventilation device comprising a self-inflating or flow-inflating bag, unidirectional valve assembly, and patient interface mask or connector, typically manufactured from medical-grade silicone, PVC, or thermoplastic elastomer and designed to deliver tidal volumes between 150 mL and 1600 mL depending on patient class. Its primary commercial purpose is to provide immediate respiratory support during cardiac arrest, anesthesia induction, or transport when mechanical ventilators are unavailable or impractical. Adult resuscitators occupy the largest revenue pool given universal deployment across emergency departments, though neonatal variants represent the fastest-growing segment as premature birth protocols tighten in low-resource settings. Self-inflating technology leads unit volume due to oxygen-source independence, while flow-inflating designs command premium placement in anesthesia suites where precise tidal control matters.
FDA 510(k) clearance pathways shape product entry timelines for US manufacturers, while EU MDR technical documentation requirements are elevating compliance costs for silicone component suppliers seeking CE marking renewal. India's CDSCO medical device rules now mandate BIS certification for imported resuscitation equipment, redirecting procurement toward domestic assembly partnerships. Stakeholders must monitor how WHO emergency care device prequalification standards evolve, as alignment with these specifications increasingly determines eligibility for ministry of health tenders across priority markets.
Market Dynamics
Critical care nursing shortages across OECD health systems is unwinding capacity expansion in emergency departments and intensive care wards, forcing hospitals to prioritize equipment that reduces operator skill dependency and accelerates training cycles.
Growth Catalysts
- India's National Health Mission:Directives from the country's health ministry are expanding procurement of self-inflating units for emergency medical services teams across state-level ambulance fleets.
- Sub-Saharan infant mortality programs:Ministries of health are prioritizing neonatal resuscitator deployment as premature birth protocols tighten in low-resource clinical settings.
- Silicone component advances:Medical-grade elastomer improvements are extending bag durability and reducing sterilization degradation rates in high-cycle hospital environments.
Market Restraints
- EU MDR compliance elevation:Technical documentation requirements for CE marking renewal are compressing margins for silicone component suppliers serving European manufacturers.
- PVC feedstock volatility:Petrochemical input cost swings are destabilizing pricing for disposable resuscitator variants in price-sensitive procurement channels.
- Single-use plastic restrictions:Environmental regulations in multiple jurisdictions are threatening volume economics for PVC-based emergency equipment lines.
Strategic Opportunities
- WHO prequalification alignment:Emergency care device standards increasingly determine ministry of health tender eligibility across priority African and South Asian markets.
- Simulation training bundling:Hardware-education contract integration is opening institutional accounts previously locked by standalone equipment vendors.
- Domestic assembly partnerships:India's CDSCO BIS certification mandate for imports is redirecting procurement toward local manufacturing joint ventures.
Industry Challenges
- FDA 510(k) pathway duration:Clearance timelines for novel valve designs are extending product entry schedules and consuming R&D runway.
- Critical care skills compression:Nursing workforce attrition is elevating training burden for resuscitator operation in understaffed emergency departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Resuscitators Market |
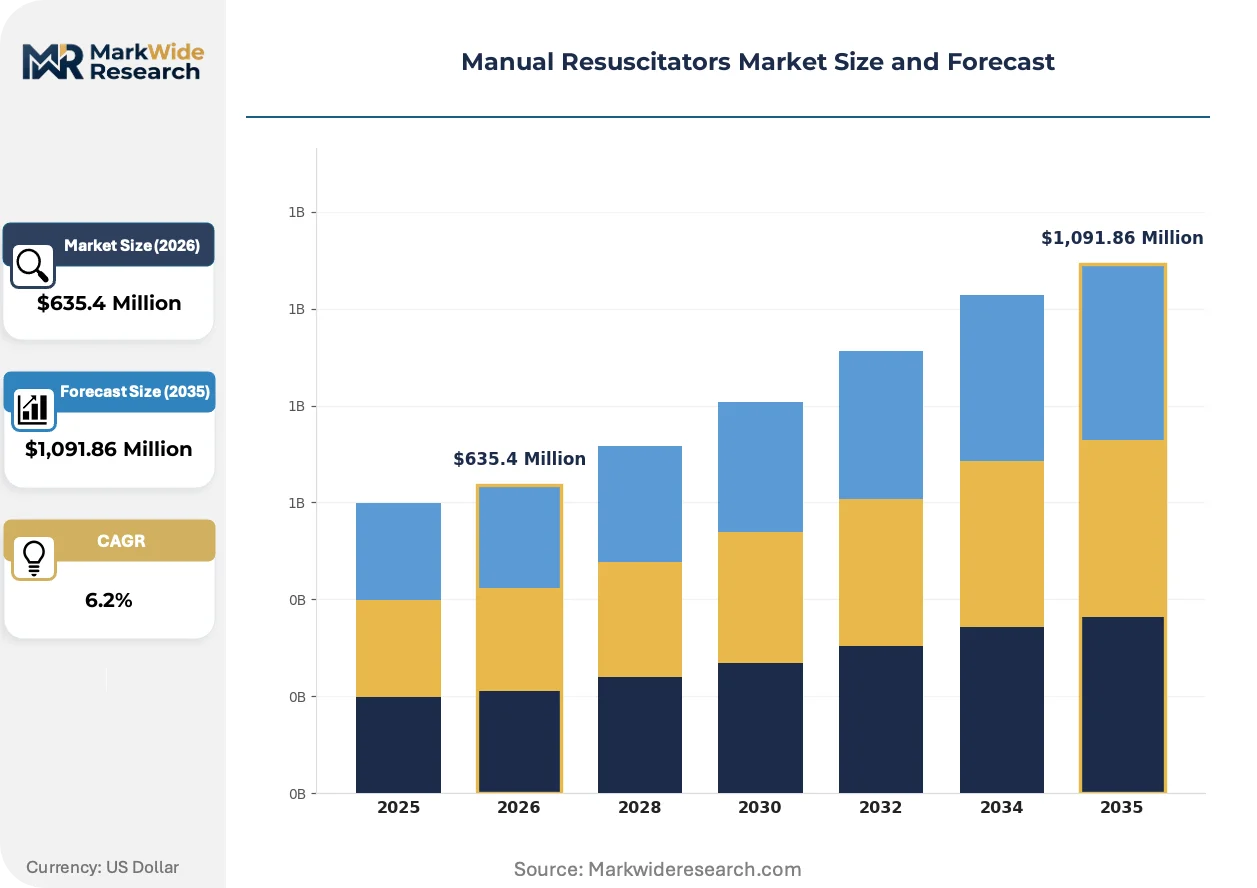
| Market Size in 2026 | $635.4 Million |
| Market Size in 2035 | $1,091.86 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Resuscitators, Pediatric Resuscitators, Neonatal Resuscitators, Multi-Patient Resuscitators Technology: Self-Inflating, Flow-Inflating, Standalone, Bag-Valve-Mask Application: Emergency Medical Services, Anesthesia, Critical Care, Ambulance Services End User: Hospitals, Emergency Response Teams, Clinics, Home Care Providers |
| Companies Covered | Vyaire Medical, Medline Industries, Ambu A/S, WEINMANN Emergency Medical Technology GmbH + Co. KG, HUM GmbH, Laerdal Medical, Medtronic, ResMed Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Resuscitators Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization pressures are actively reshaping competitive positioning in manual resuscitation equipment, with durability standards and training integration emerging as primary differentiation vectors.
Silicone elastomer formulations are decomposing the historical PVC-dominant cost structure in reusable resuscitator segments. Ambulance services in Germany and France are accelerating adoption of silicone bag variants despite 40-60% unit price premiums. The technology is decomposing replacement cycle economics by extending functional lifespan from hundreds to thousands of sterilization cycles.
EU MDR technical documentation requirements are compressing supplier bases for European manufacturers seeking CE marking renewal. Silicone component vendors without notified body relationships are exiting the market, concentrating qualified supply among elastomer specialists with established quality management systems. Neonatal resuscitator variants face the steepest compliance cost escalation due to higher biocompatibility testing thresholds.
Institutional procurement patterns are fragmenting as hospital systems unbundle resuscitator hardware from traditional anesthesia suite equipment packages. Group purchasing organizations in the United States are creating standalone emergency equipment categories that bypass integrated critical care portfolio discounts. This disintermediation is most visible in academic medical centers with dedicated simulation training budgets seeking direct manufacturer relationships.
Manual Resuscitators Market Segmentation
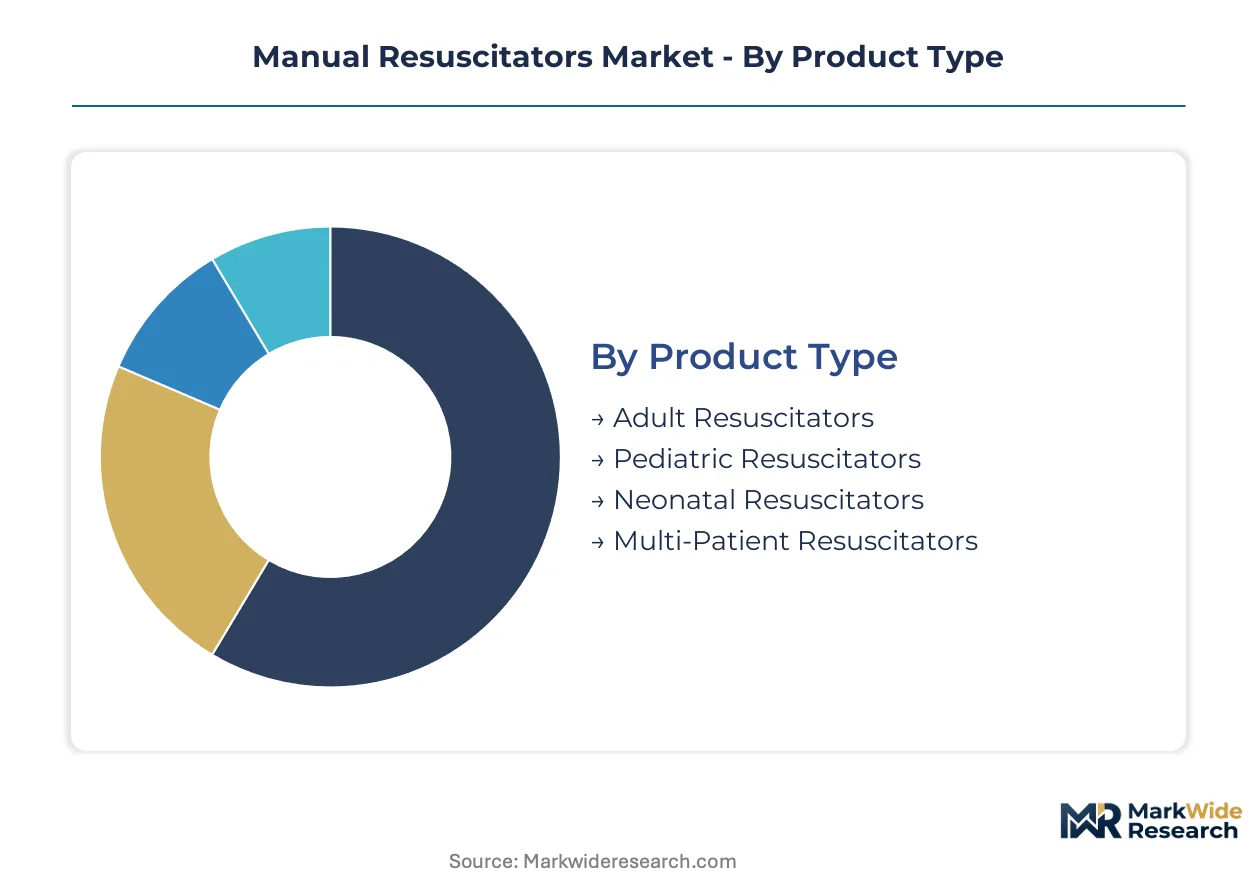
Manual resuscitator procurement patterns diverge sharply across patient class and deployment setting, with regulatory thresholds for neonatal biocompatibility and EMS durability standards creating distinct commercial entry barriers for each segment cluster.
Product Type:
FDA 510(k) clearance timelines and EU MDR biocompatibility testing burdens stratify competitive intensity across patient-class variants, with neonatal units facing the steepest documentation requirements.
- Adult Resuscitators:These devices deliver tidal volumes between 400 mL and 1600 mL through silicone or PVC bag assemblies designed for cardiac arrest and anesthesia induction protocols. Emergency departments in the United States and Germany account for the dominant procurement volume, driven by universal deployment mandates for crash cart readiness.
- Neonatal Resuscitators:Precision-engineered for 150 mL to 240 mL tidal delivery with pressure-limited valve systems to prevent barotrauma in premature infants. Ministries of health in Kenya, Nigeria, and Ethiopia are prioritizing deployment through infant mortality reduction initiatives, making this the fastest-expanding patient-class segment.
- Pediatric Resuscitators:Intermediate-volume devices bridging adult and neonatal specifications for patients aged one to twelve years.
- Multi-Patient Resuscitators:Modular systems with interchangeable patient interface connectors for flexible deployment across age categories.
Adult resuscitators handle the majority of throughput; neonatal resuscitators are gaining share fastest.
Technology:
Cost tier differentiation separates oxygen-source-dependent designs from standalone emergency units, with price premiums of 40-60% for flow-inflating variants reflecting precision control requirements.
- Self-Inflating:Elastomer bags with internal re-expansion mechanisms eliminate dependency on compressed oxygen sources, enabling deployment in field conditions without pipeline infrastructure. India's National Health Mission is directing state ambulance fleets toward this technology under emergency medical services expansion directives.
- Flow-Inflating:Anesthesia suite designs requiring continuous oxygen or air supply deliver precise tidal volume control through reservoir bag systems. German and French hospital purchasing favors these units despite premium pricing, as sterilization cycle durability extends functional lifespan.
- Standalone:Portable units integrating oxygen reservoir and delivery mechanism for transport scenarios.
- Bag-Valve-Mask:Simplified manual compression systems for basic life support training and emergency responder certification.
Self-inflating technology commands the volume base; flow-inflating designs capture the margin premium.
Application:
Customer workflow integration determines specification requirements, with anesthesia suites demanding precision control and emergency services prioritizing rapid deployment reliability.
- Emergency Medical Services:Field-deployed units require impact-resistant construction and rapid sterilization turnaround for high-cycle reuse. State-level procurement in India under the National Health Mission is concentrating demand for self-inflating variants with extended temperature tolerance.
- Anesthesia:Operating room integration demands precise tidal volume calibration and compatibility with anesthesia machine breathing circuits. EU MDR technical documentation requirements for CE marking renewal are compressing supplier bases serving European manufacturers in this application.
- Critical Care:Intensive care ward backup systems for mechanical ventilator failure scenarios.
- Ambulance Services:Transport-specific designs emphasizing compact storage and rapid access configuration.
Emergency medical services generates the highest unit velocity; anesthesia commands the steepest price realization.
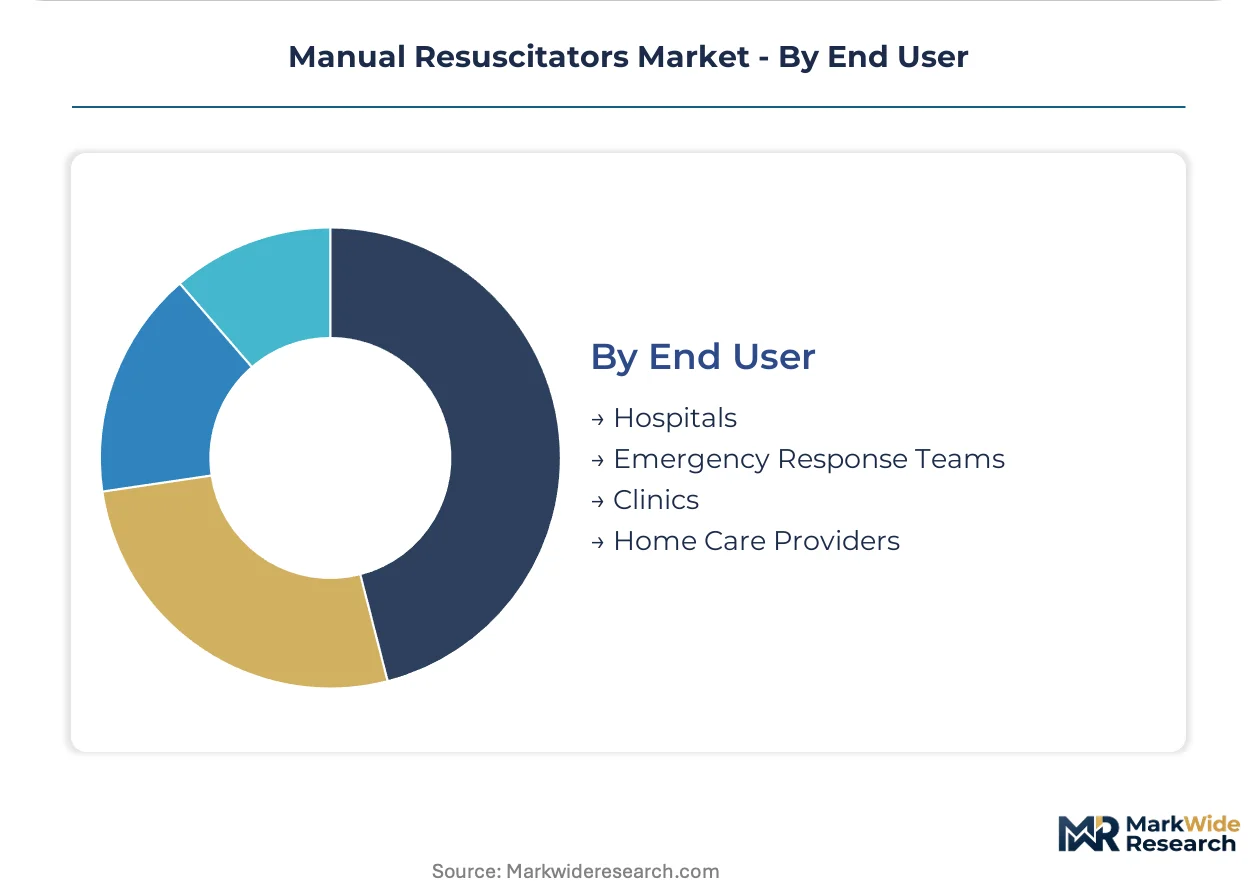
End User:
Procurement authority concentration varies by facility scale, with hospital systems leveraging group purchasing organization leverage against fragmented clinic purchasing.
- Hospitals:Integrated health systems in the United States are unbundling resuscitator procurement from traditional anesthesia equipment packages, creating standalone emergency equipment categories. Academic medical centers with dedicated simulation training budgets are pursuing direct manufacturer relationships outside GPO frameworks.
- Emergency Response Teams:Municipal and regional ambulance services prioritize self-inflating durability for oxygen-independent field deployment. CDSCO BIS certification mandates for imported equipment are redirecting Indian procurement toward domestic assembly partnerships.
- Clinics:Outpatient facilities with limited critical care infrastructure.
- Home Care Providers:Rare deployment for palliative respiratory support with trained caregiver oversight.
Hospitals anchor procurement value; emergency response teams are expanding most quickly on unit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price realization in German anesthesia suites runs 40-60% above Indian state ambulance procurement, creating a bifurcated margin structure across developed and emerging health systems. This asymmetry redirects manufacturing investment toward dual-product strategies serving premium precision markets alongside high-volume emergency deployments.
United States
Emergency departments drive adult resuscitator volume through universal crash cart mandates, while academic medical centers pursue direct manufacturer relationships outside group purchasing frameworks. FDA 510(k) clearance pathways shape product entry timelines for domestic manufacturers. Greater Boston and the Pacific Northwest host simulation training ecosystems that bind hardware procurement to institutional education contracts.
Germany
Anesthesia suites in Bavaria and North Rhine-Westphalia command premium pricing for flow-inflating designs with extended sterilization durability. EU MDR technical documentation requirements compress supplier bases for CE marking renewal. The Eindhoven-adjacent industrial corridor across the Dutch border supplies silicone component expertise to German manufacturers seeking elastomer quality management systems.
India
State-level ambulance fleets under the National Health Mission expand procurement of self-inflating units for oxygen-independent field deployment. CDSCO BIS certification mandates redirect imported equipment toward domestic assembly partnerships. Maharashtra and Gujarat host emerging manufacturing joint ventures serving both government tenders and export channels to sub-Saharan markets.
Kenya
Ministry of health programs prioritize neonatal resuscitator deployment as infant mortality reduction initiatives tighten premature birth protocols. WHO emergency care device prequalification standards determine eligibility for ministry tenders. Nairobi anchors East African distribution networks supplying equipment to Ethiopia and Nigeria through regional procurement consortia.
France
Ambulance services accelerate silicone bag adoption despite unit price premiums, driven by replacement cycle economics favoring durability over disposable alternatives. ANSM regulatory oversight aligns with EU MDR harmonization pressures. The Île-de-France region concentrates hospital system purchasing authority for integrated critical care portfolios spanning ventilation and resuscitation workflows.
Manual Resuscitators Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with silicone elastomer specialists commanding premium positioning against PVC-dominant volume manufacturers. The market exhibits tiered concentration: integrated critical care portfolios anchor North American hospital purchasing, while standalone emergency equipment vendors compete on price in government procurement channels. Three archetypes dominate: simulation-training bundlers, materials-science verticalists, and regional assembly partners. M&A activity concentrates in silicone component supply chains, while strategic partnerships proliferate around domestic assembly mandates in emerging markets.
Within the integrated portfolio tier, Medtronic and Laerdal Medical occupy positions exemplifying divergent strategic vectors—one anchoring hospital system contracts through critical care breadth, the other binding hardware to education ecosystems. Ambu A/S represents the materials-science verticalist archetype, with A/S suffix signaling Danish corporate structure and silicone manufacturing heritage sustaining European ambulance supply chain dominance. Among emergency technology specialists, WEINMANN Emergency Medical Technology GmbH + Co. KG exemplifies German GmbH + Co. KG structuring focused on field-deployable designs.
| Leading Market Players |
|---|
| Vyaire Medical |
| Medline Industries |
| Ambu A/S |
| WEINMANN Emergency Medical Technology GmbH + Co. KG |
| HUM GmbH |
| Laerdal Medical |
| Medtronic |
| ResMed Inc. |
| Teleflex Incorporated |
| Others |
Cost & Logistics Intelligence
Silicone elastomer substitution for PVC feedstocks is simultaneously shifting component sourcing toward German and Danish specialty chemical corridors while compressing margin structures for disposable-variant manufacturers dependent on petrochemical pricing cycles. This material transition rewards suppliers with in-house elastomer compounding capabilities and penalizes assemblers locked into volatile PVC spot markets.
Pricing Analysis
German anesthesia suites command 40-60% price premiums over Indian state ambulance procurement, creating bifurcated margin structures across developed and emerging health systems. Three-tier pricing structure across premium, standard, and economy levels separates flow-inflating precision units from basic self-inflating emergency variants. Cost compression in the PVC-disposable tier is intensifying because of environmental regulation threats and feedstock volatility. Emergency response teams in sub-Saharan Africa exhibit highest price sensitivity; academic medical centers in the United States and Germany demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone dominates procurement behavior among European manufacturers confronting EU MDR compliance deadlines, while Asian assemblers favor just-in-time PVC sourcing to minimize working capital exposure. Component concentration centers on Germany, Denmark, and India for elastomer expertise; China and Malaysia for molded plastic subassemblies. Raw material dependencies rest on medical-grade silicone polymers, PVC resins, and precision valve elastomers. Single-source vulnerability in notified body relationships for CE marking creates regulatory chokepoints. Distribution runs through hospital group purchasing organizations in North America and ministry tenders in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified silicone component suppliers with established quality management systems represent a narrowing bottleneck, constraining European manufacturers' product refresh cycles and elevating acquisition premiums for elastomer specialists.
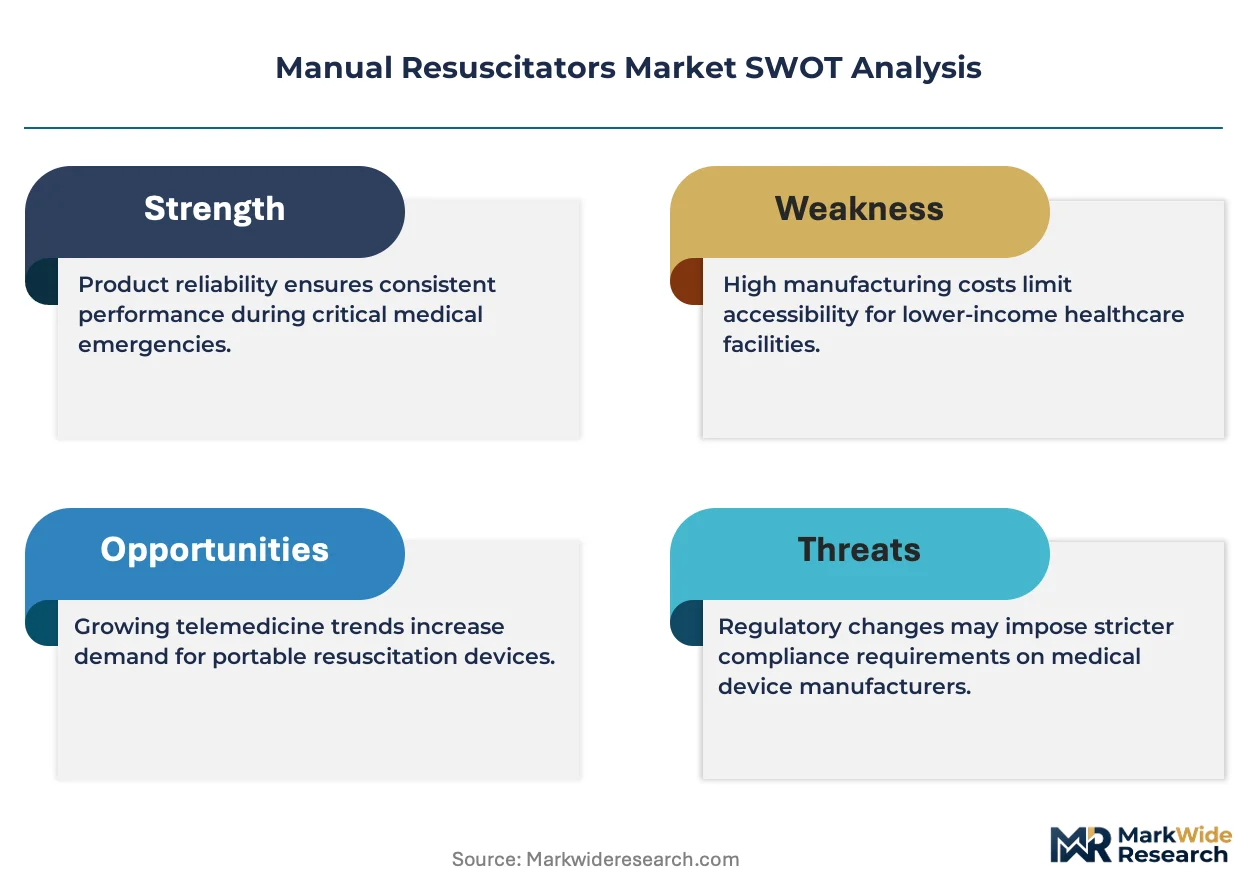
For Market Incumbents: Shield margin positions in European anesthesia suites by deepening backward integration into medical-grade silicone compounding before EU MDR compliance deadlines eliminate second-source options. Prioritize certification investment for neonatal biocompatibility tiers to defend against emerging Asian assemblers targeting WHO prequalification pathways. For New Entrants and Emerging Players: Differentiate on simulation-training bundling to bypass entrenched group purchasing organization lock-in at academic medical centers. Target India's domestic assembly partnership requirements under CDSCO BIS mandates as the most penetrable regulatory entry point. Pursue direct institutional relationships with emergency medical services directors seeking operator-skill-reduction features. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed silicone component specialists facing exit pressure from EU MDR compliance cost escalation. Five-to-ten year viability favors targets with captive elastomer supply and established notified body relationships over pure-play assemblers. Watch WHO emergency care device prequalification standard revisions as inflection indicator for African and South Asian tender eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Elastomer Backward Integration | Captive supply of medical-grade polymers insulates margins from PVC feedstock volatility and EU MDR supplier compression. |
| Domestic Assembly Partnership | CDSCO BIS certification compliance unlocks Indian National Health Mission procurement and sub-Saharan export channels. |
| Simulation Training Ecosystem Binding | Hardware-education contract integration secures institutional loyalty outside group purchasing organization frameworks. |
| WHO Prequalification Alignment | Compliance with emergency care device standards determines ministry of health tender eligibility across priority African markets. |
| Neonatal Biocompatibility Certification | Extended sterilization durability and pressure-limited valve systems command premium placement in infant mortality reduction programs. |
Research Approach
A spread of perspectives from emergency medical services procurement directors, hospital biomedical engineers, silicone component suppliers, group purchasing organization contract managers, and ministry of health equipment officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CDSCO medical device registration records, and WHO emergency care device prequalification rosters. Bottom-up unit demand modeling and top-down healthcare expenditure allocation triangulated market sizing.
Segmentation dimensions modeled span patient class, technology type, application setting, and end-user facility scale across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes against healthcare infrastructure investment trajectories. Forecast inputs incorporate nursing workforce attrition rates affecting equipment utilization intensity and regulatory pathway duration estimates for novel valve designs.
Decision-makers should treat outputs as directional under assumptions of stable EU MDR enforcement timelines and continued National Health Mission funding continuity; material deviation would warrant model refresh. Revision becomes warranted when WHO prequalification standards or CDSCO import certification requirements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Rapid Infuser Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Global Medical Implants Market
Medical Devices
Global Glucometer Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
3D Printing Medical Devices Market