
 Europe Machine Tools Market | 2026-2036
Europe Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Tools Market Intelligence
Carbon fiber reinforced polymer is expanding its presence in aerospace structural components, forcing machine tool builders to adapt spindle speeds and thermal management systems. DMG Mori leverages its integrated automation portfolio to capture high-mix, low-volume aerospace contracts. Sandvik AB anchors its position through advanced tooling solutions that extend cutting tool life in difficult-to-machine alloys. Trumpf Group specializes in laser-based additive-subtractive hybrid systems for complex part geometries.
Europe machine tools encompass power-driven equipment that shapes metal or other rigid materials through cutting, grinding, shearing, or electrical discharge processes, typically achieving tolerances of ±0.001 mm in precision configurations. CNC technology dominates new equipment sales as manufacturers pursue unmanned operation and real-time process optimization. Milling machines command the largest product type share due to versatility across automotive powertrain and aerospace structural applications. Precision machining applications generate the highest margin pools, particularly in medical implant and turbine blade production where surface finish requirements exceed Ra 0.4 µm.
The EU Machinery Directive and CE marking framework mandate comprehensive risk assessment and safety integration, elevating compliance costs for non-European suppliers. Germany's KBA and France's ANSM enforce sector-specific certification protocols that shape product development cycles for automotive and medical device manufacturing equipment. Stakeholders must monitor how the EU AI Act intersects with autonomous process control systems, as adaptive machining algorithms face emerging transparency and validation requirements that could reshape R&D priorities across European production technology vendors.
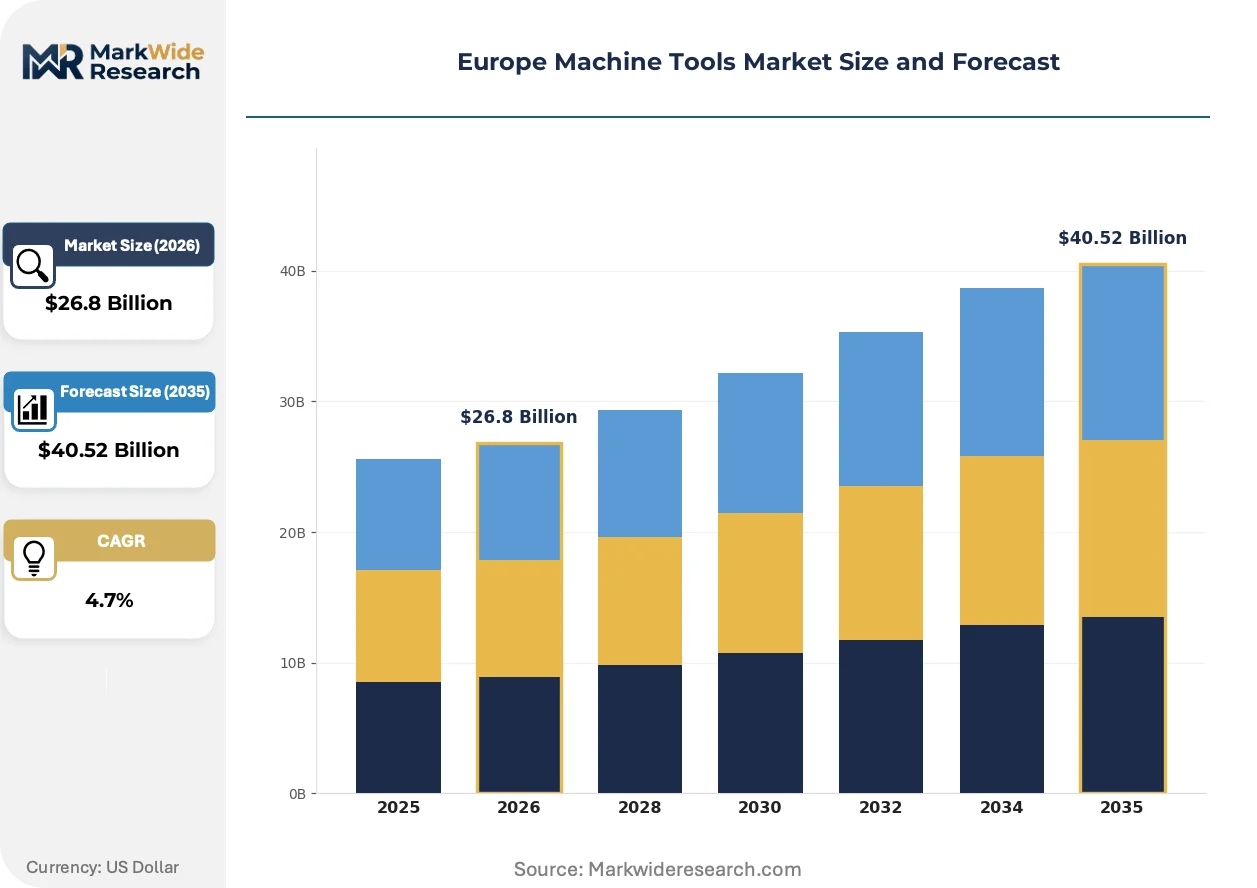
Market Dynamics
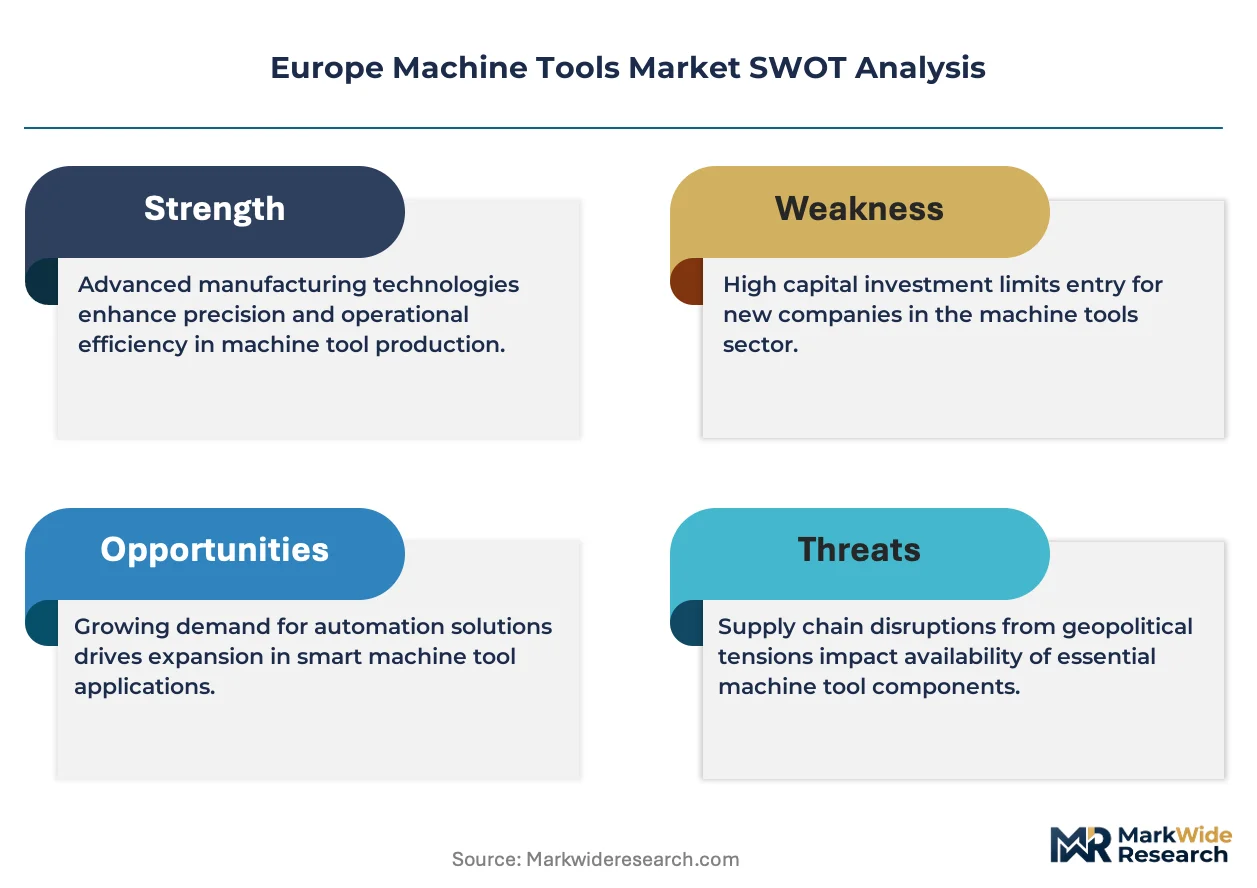
Carbon fiber reinforced polymer penetration in aerospace airframes is forcing European machine tool builders to redesign thermal management architectures and spindle speed ranges, compressing product development cycles and elevating R&D intensity across Baden-Württemberg and Bavaria industrial clusters.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements and comprehensive risk assessment protocols are accelerating replacement demand for legacy equipment across German automotive suppliers and French medical device manufacturers.
- Five-axis machining center demand:Aerospace structural component complexity is pulling multi-axis configurations into high-mix, low-volume production environments, particularly for titanium and nickel-based superalloy workpieces.
- Baden-Württemberg industrial cluster concentration:Stuttgart-region machine tool builders benefit from proximity to Mercedes-Benz, Porsche, and Bosch procurement headquarters, enabling rapid prototype-to-production cycles.
Market Restraints
- Energy cost volatility:German industrial electricity pricing above €0.25/kWh is compressing operating margins for energy-intensive grinding and electrical discharge machining operations.
- Control system supply concentration:Dependency on Siemens and Heidenhain CNC architectures creates vulnerability to semiconductor component lead time fluctuations.
- Skilled machinist scarcity:German metalworking trades face 15,000+ unfilled positions, constraining output capacity for precision configurations requiring ±0.001 mm tolerances.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Automotive OEMs are diversifying machining capacity eastward, creating demand for mid-tier CNC lathes and machining centers with localized service networks.
- EU AI Act adaptive machining pathways:Transparent algorithm validation frameworks for autonomous process control systems will favor early-moving vendors with documented decision-audit capabilities.
- Laser-based additive-subtractive hybrid systems:Convergence of directed energy deposition with five-axis milling is opening complex part geometries previously impossible through conventional subtractive methods alone.
Industry Challenges
- CE marking timeline compression:Notified body backlogs for machinery safety certification are extending product launch windows by 4-8 months for non-European suppliers.
- Legacy PLC integration friction:Brownfield facilities in France and Italy struggle to retrofit 1990s-era machine tools with Industry 4.0 data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Tools Market |
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $40.52 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathes, Milling Machines, Drilling Machines, Grinding Machines Technology: CNC, Hydraulic, Electric, Pneumatic End User: Aerospace, Automotive, Construction, Electronics Application: Precision Machining, Production Machining, Maintenance, Prototyping |
| Companies Covered | Haas Automation, Sandvik AB, DMG Mori, Bystronic Laser, Yamazaki Mazak Corporation, Trumpf Group, Okuma Corporation, FANUC Corporation, Grob-Werke, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Tools Market Strategic Shifts & Innovations
Machine tool architectures are fragmenting into configurable subsystems as aerospace and medical device manufacturers demand production flexibility without dedicated capital for each part family, compressing the traditional monolithic equipment model.
Digital twin technology is modularizing machine tool development workflows, enabling Stuttgart-based builders to simulate thermal deformation and cutting force dynamics before physical prototype construction. Aerospace tier-one suppliers in Toulouse and Hamburg are adopting these virtual commissioning platforms to compress fixture validation cycles. The technology is modularizing the traditional sequential design-manufacture-test sequence into parallel workstreams that collapse time-to-market for new equipment configurations.
France's ANSM is tightening medical device manufacturing equipment validation protocols, requiring documented process capability studies for implant-grade surface finish production. German KBA automotive safety mandates are extending similar traceability requirements to powertrain machining operations. Precision grinding and honing equipment categories face the steepest compliance burden, with vendors investing in embedded metrology systems to satisfy real-time quality documentation demands.
Service contract unbundling is fragmenting the traditional bundled maintenance model across European machine tool installed bases. German automotive suppliers now separate predictive maintenance subscriptions from spare parts procurement, pressuring OEMs to demonstrate ROI through measurable uptime improvements rather than fixed-fee coverage. This purchasing pattern shift is most pronounced in Bavaria's high-volume powertrain operations, where internal maintenance capabilities have matured sufficiently to support selective outsourcing decisions.
Europe Machine Tools Market Segmentation
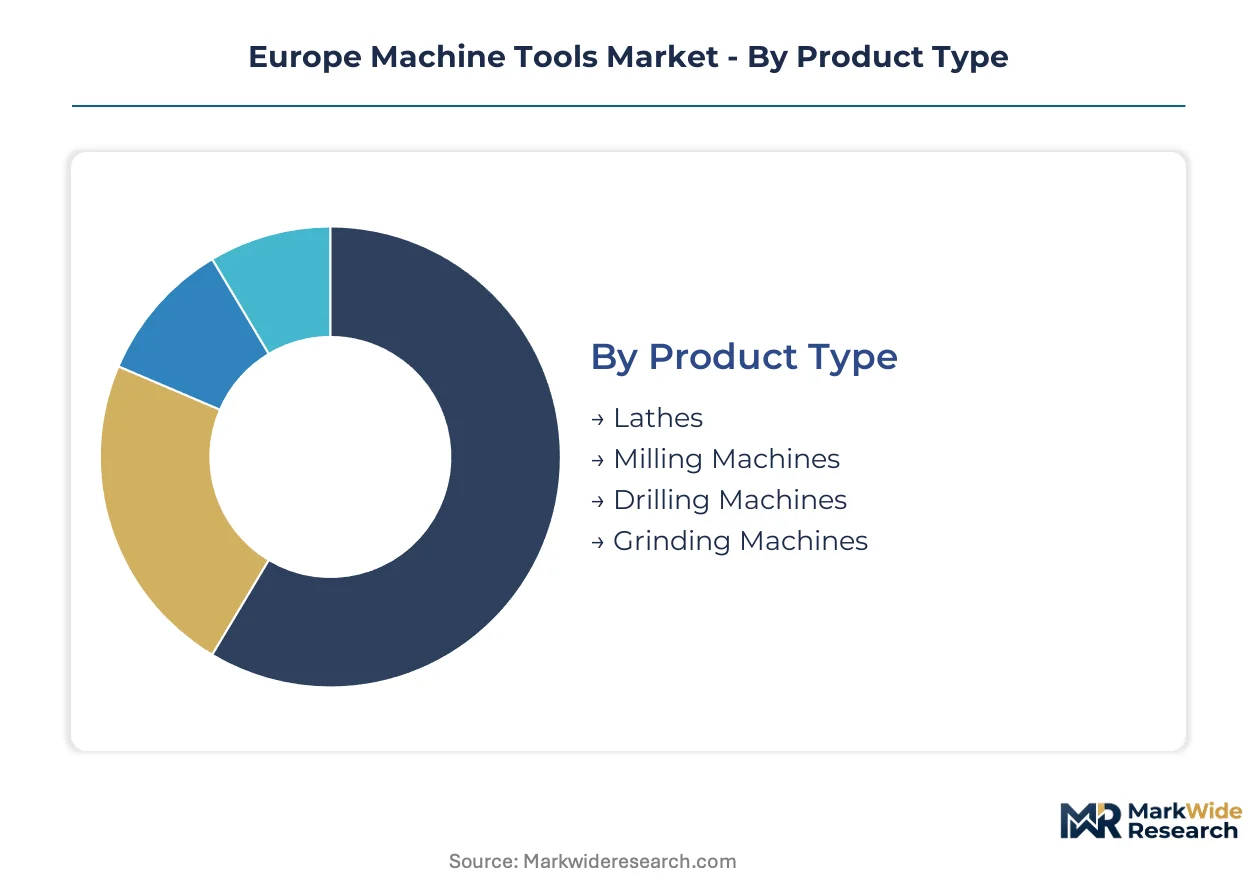
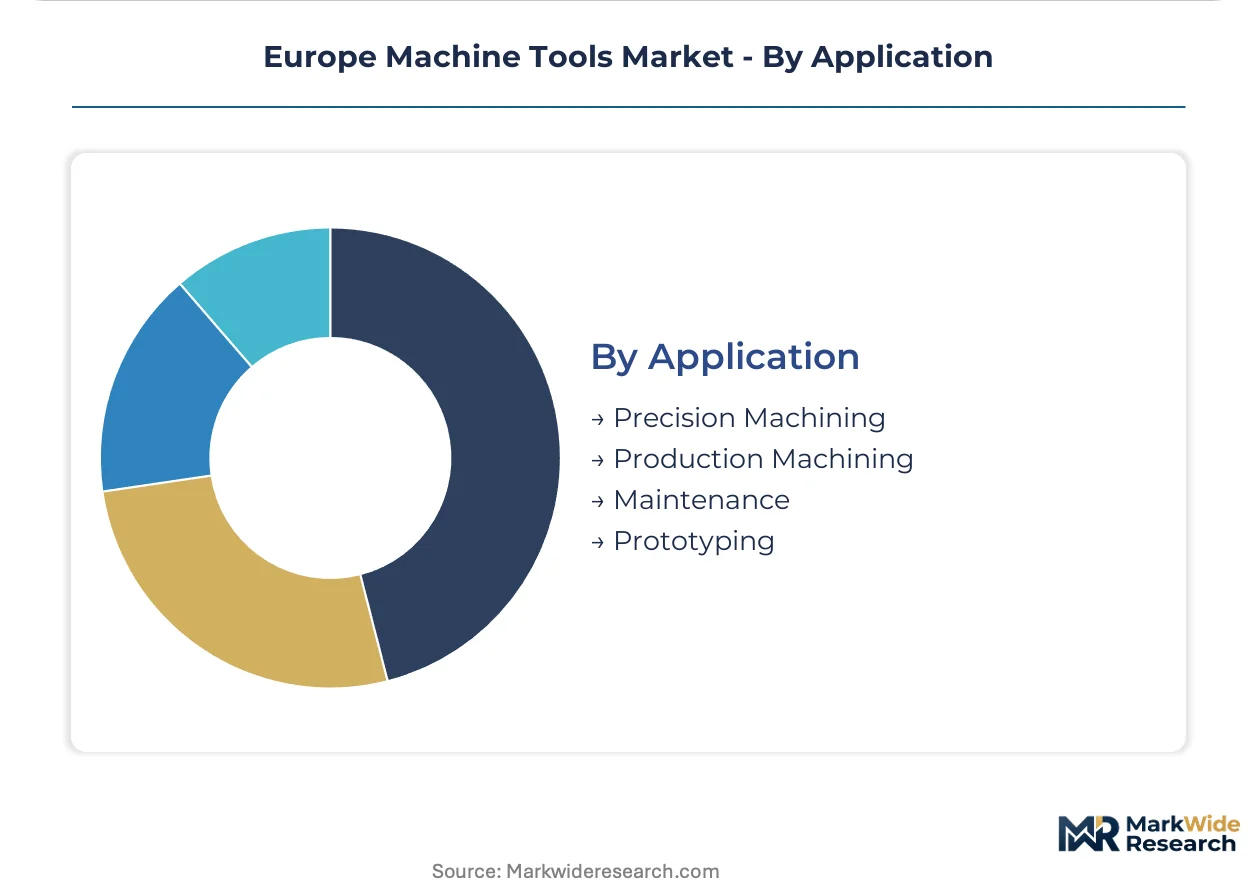
European machine tool procurement patterns diverge sharply across capital intensity tiers, with aerospace-grade five-axis configurations demanding 3-5x the upfront investment of standard automotive lathes. Segmentation reveals how Baden-Württemberg and Bavaria industrial clusters concentrate spending in precision-capable categories while Eastern European expansion favors mid-tier productivity equipment.
Product Type:
Milling machines and grinding machines extract the steepest capital commitments, with multi-axis configurations requiring integrated thermal management and spindle systems that dominate equipment budgets.
- Milling Machines:Five-axis machining centers achieve ±0.001 mm tolerances through synchronized rotary tables and high-speed spindles exceeding 20,000 RPM. Demand concentrates in Germany's aerospace tier-one suppliers around Hamburg and Toulouse-region airframe manufacturers, pulled by titanium and nickel-based superalloy structural component programs.
- Grinding Machines:Precision surface and cylindrical configurations incorporate in-process gauging and adaptive dressing systems for medical implant surface finishes below Ra 0.4 µm. French ANSM validation protocols and German KBA traceability mandates are elevating embedded metrology requirements across Stuttgart-region medical device and powertrain operations.
- Lathes:CNC turning centers with live tooling and Y-axis capabilities bridge traditional subtractive boundaries for mid-volume automotive shaft production.
- Drilling Machines:Deep-hole and gun-drilling configurations serve specialized aerospace landing gear and hydraulic cylinder applications with length-to-diameter ratios exceeding 20:1.
Most installed capacity flows through Milling Machines. Expansion is steepest in Grinding Machines.
Technology:
Control architecture selection determines interoperability depth with factory MES layers and long-term upgrade pathways across brownfield European facilities.
- CNC:Computer numerical control dominates new equipment sales through unmanned operation capability and real-time process optimization algorithms. Siemens and Heidenhain architectures anchor German automotive supplier procurement specifications, though EU AI Act transparency requirements are reshaping adaptive machining validation protocols.
- Electric:Servo-driven actuation delivers positioning repeatability below 5 µm for medical device micromachining cells in Switzerland and Netherlands.
- Hydraulic:High-force forming and heavy-duty turning applications persist in Polish and Czech Republic automotive component forging operations.
- Pneumatic:Low-cost clamping and auxiliary axis positioning supports secondary automation in Italian and Spanish job shop environments.
CNC systems carry the largest installed base. Electric configurations are gaining share fastest in precision-focused segments.
End User:
Customer concentration patterns align with regional industrial specialization, from Stuttgart automotive headquarters to Toulouse aerospace engineering centers.
- Automotive:Powertrain machining operations in Bavaria and Baden-Württemberg drive demand for high-volume turning and milling centers with sub-60-second chip-to-chip times. Mercedes-Benz, Porsche, and Bosch procurement headquarters maintain direct supplier development relationships with regional machine tool builders.
- Aerospace:Structural component complexity is pulling multi-axis configurations into high-mix, low-volume production environments for titanium airframe and turbine blade applications.
- Electronics:Miniaturization trends in semiconductor packaging and connector manufacturing favor micromachining centers with spindle speeds above 40,000 RPM.
- Construction:Heavy equipment hydraulic cylinder and structural steel component production utilizes large-format boring mills and gantry configurations.
Automotive accounts for the largest equipment installed base. Aerospace is expanding most quickly in five-axis and hybrid additive-subtractive categories.
Application:
Process maturity requirements separate commodity production environments from validated medical and aerospace manufacturing cells.
- Precision Machining:Medical implant and turbine blade production demands surface finish capabilities below Ra 0.4 µm with documented process capability studies. France's ANSM and German KBA enforcement of sector-specific certification protocols shapes equipment specification development cycles.
- Production Machining:High-volume automotive powertrain operations prioritize OEE metrics and predictive maintenance integration over absolute precision.
- Prototyping:Rapid fixture validation and first-article inspection compression favor digital twin-enabled virtual commissioning platforms adopted by Hamburg and Toulouse tier-one suppliers.
- Maintenance:Repair and overhaul operations in established manufacturing bases utilize retrofitted legacy equipment with selective Industry 4.0 sensor augmentation.
Production Machining holds the dominant installed capacity position. Precision Machining carries the steepest expansion trajectory driven by medical and aerospace validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's Stuttgart industrial cluster anchors European machine tool demand, with Mercedes-Benz, Porsche, and Bosch procurement headquarters driving precision equipment specifications across the continent.
Germany
Bavaria and Baden-Württemberg industrial clusters absorb the majority of five-axis machining center procurement for aerospace structural components. The KBA enforces automotive safety mandates that extend traceability requirements to powertrain machining operations. Hamburg's aerospace tier-one suppliers are adopting digital twin-enabled virtual commissioning platforms to compress fixture validation cycles.
France
Toulouse-region airframe manufacturers are pulling multi-axis configurations into high-mix, low-volume production environments for titanium structural components. ANSM validation protocols require documented process capability studies for implant-grade surface finish production. Île-de-France medical device manufacturers are investing in precision grinding equipment with embedded metrology systems.
Italy
Emilia-Romagna's automotive component suppliers are retrofitting legacy equipment with Industry 4.0 data exchange protocols to satisfy OEM traceability requirements. CE marking timeline compression from notified body backlogs is extending product launch windows for imported machinery. Lombardy job shops favor pneumatic auxiliary axis positioning for secondary automation in mid-volume production.
Switzerland
Swiss medical device micromachining cells in the Jura arc demand servo-driven electric actuation delivering positioning repeatability below 5 µm. Swissmedic oversight of implant manufacturing equipment shapes specification development for precision surface grinding systems. Geneva-region manufacturers are unbundling service contracts to separate predictive maintenance subscriptions from spare parts procurement.
Poland
Automotive OEMs are diversifying machining capacity eastward, creating demand for mid-tier CNC lathes with localized service networks. EU Machinery Directive compliance costs elevate entry barriers for non-European suppliers seeking CE marking certification. Silesian automotive component forging operations persist with hydraulic high-force forming equipment for heavy-duty turning applications.
Europe Machine Tools Market Key Industry Players
Portfolio diversification dominates the current landscape as established builders expand from subtractive-only offerings into additive-subtractive hybrid configurations. The vendor base organizes around three strategic archetypes: integrated automation specialists, advanced tooling solution providers, and laser-based hybrid system developers. M&A activity and strategic partnerships represent the primary competitive moves, with builders acquiring software capabilities for digital twin deployment and service network expansion.
Among Germany-based fabricators, DMG Mori and Trumpf Group exemplify contrasting strategic positions within the premium equipment tier. DMG Mori occupies a position representing integrated automation portfolio depth, while Trumpf Group anchors the laser-based additive-subtractive hybrid system segment. Sandvik AB sits within the advanced tooling solutions archetype, extending cutting tool life capabilities that complement primary equipment procurement decisions across European aerospace and medical device manufacturing cells.
| Leading Market Players |
|---|
| Haas Automation |
| Sandvik AB |
| DMG Mori |
| Bystronic Laser |
| Yamazaki Mazak Corporation |
| Trumpf Group |
| Okuma Corporation |
| FANUC Corporation |
| Grob-Werke |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists across Baden-Württemberg and Bavaria anchor supply-side discipline, translating generational balance-sheet conservatism into selective capacity expansion and premium pricing power for five-axis configurations serving Mercedes-Benz and Porsche procurement headquarters.
Pricing Analysis
Input-cost pass-through from semiconductor component shortages and rare-earth magnet volatility is compressing margins for CNC control system integrators dependent on Siemens and Heidenhain architectures. Three-tier pricing structure across premium aerospace-grade, standard automotive-volume, and economy mid-tier equipment separates CE-marked precision configurations from non-certified alternatives. Pricing pressure stems from energy-intensive grinding operations facing German industrial electricity rates above €0.25/kWh. Tier-one automotive suppliers in Bavaria exhibit lowest price sensitivity due to embedded metrology requirements, while Polish automotive component forgers drive hardest bargain on mid-tier lathe procurement.
Supply Chain Analysis
EU Machinery Directive local-content rules and CE marking mandates are reshaping sourcing patterns toward Baden-Württemberg and Bavaria machine tool builders with notified body relationships. Supply concentration rests on Germany, Switzerland, and Japan for high-speed spindle systems, linear motion guides, and precision ball screws. Rare-earth permanent magnets for servo motors and specialized bearing steels draw from concentrated Asian refining capacity. Single-source vulnerability in CNC control architecture creates exposure to semiconductor lead time fluctuations. Distribution runs through direct OEM procurement relationships for large aerospace contracts and regional distributor networks for mid-tier job shop equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe machine tools constitute a late-cycle quality story as aerospace structural component complexity and ANSM medical device validation protocols shift procurement toward premium precision configurations with documented process capability studies.
For Market Incumbents: Extend digital twin-enabled service portfolios to capture unbundled predictive maintenance subscriptions separating from spare parts procurement in Bavaria powertrain operations. Deepen backward integration into embedded metrology systems to satisfy KBA traceability mandates and ANSM surface finish documentation requirements. Counter Trumpf Group laser-hybrid encroachment through accelerated additive-subtractive R&D partnerships with Hamburg aerospace tier-one suppliers. For New Entrants and Emerging Players: Digital channel partnerships with Polish and Czech Republic automotive OEMs offer lowest-friction entry path for mid-tier CNC lathe penetration. Target Silesian forging operations and Emilia-Romagna retrofit markets where legacy PLC integration friction creates white-space for Industry 4.0 data exchange protocol specialists. Lead with localized service network guarantees rather than equipment specification parity. For Investors and Strategic Acquirers: Valuations sit cheapest among Swiss and Italian precision grinding specialists with ANSM-validated medical device equipment portfolios and dormant aerospace certification pathways. Five-to-ten year viability hinges on EU AI Act adaptive machining algorithm validation capabilities. Watch CE marking timeline compression at notified bodies as inflection signal for import-substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Additive-Subtractive Hybrid System Development | Captures complex titanium airframe geometries impossible through conventional milling alone for Toulouse manufacturers. |
| Embedded Metrology Integration | Satisfies ANSM process capability documentation for Jura arc medical implant surface finishes below Ra 0.4 µm. |
| Digital Twin Platform Deployment | Compresses fixture validation cycles for Hamburg aerospace tier-one suppliers adopting virtual commissioning. |
| CE Marking Notified Body Partnership | Accelerates product launch windows for non-European suppliers facing 4-8 month certification backlogs. |
| Localized Service Network Expansion | Secures Polish and Czech Republic automotive OEM procurement specifications requiring rapid response capabilities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and notified body certification specialists against secondary validation through customs data, EU Machinery Directive enforcement records, SEC filings of listed equipment vendors, and production statistics from Stuttgart-region industry associations. Bottom-up equipment shipment tallies by product category and top-down macroeconomic absorption models triangulated to convergence.
Comparable-period anchoring tied projection assumptions to historical reference periods spanning pre-pandemic baselines through current industrial cycle positioning. Segmentation modeling incorporated product type, control technology, end-use industry, application maturity, and regional industrial cluster concentration dimensions. CAGRs derived from logistic diffusion curves fitted to capital equipment replacement cycles and technology adoption S-curves. Forecast inputs included aerospace program ramp schedules, automotive powertrain electrification capex plans, and medical device regulatory pathway timelines.
The model assumes a particular technology adoption path; alternative pathways for autonomous process control systems under EU AI Act transparency requirements would alter the outlook. Forecasts reflect documented assumptions regarding energy cost trajectories, semiconductor supply normalization, and skilled machinist labor market tightness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Post Drivers Market
Tools
Fatigue Testing Machine Market
Tools
Rotary Hammer Drill Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Power Nibbler Market
Tools
Digital Laser Levels Market
Tools
Drain Cleaning Equipment Market
Tools
Drill Set Market
Tools
Surface Planer Market
Tools
Woodpecker Tools Market
Tools
Global Zero Point Clamping System Market
Tools
Automotive Torque Tools Market
Tools
Structural Wood Screws Market
Tools
Gear Honing Machines Market
Tools
End Mill Holder Market
Tools
Woodworking Power Tools Market