
 South Korea Heavy Construction Equipment Rental Market | 2026-2036
South Korea Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Heavy Construction Equipment Rental Market Insights
ISO 9001 quality management certification is bifurcating the South Korea heavy construction equipment rental landscape into qualified fleet operators and marginal providers. HD Hyundai Construction Equipment leverages its domestic manufacturing base to anchor rental availability across the peninsula. Doosan Infracore competes through specialized excavator fleets tailored to urban demolition constraints. Caterpillar sustains premium positioning via extended service networks in Busan and Incheon industrial zones.
South Korea heavy construction equipment rental encompasses the temporary provision of mechanized earthmoving, lifting, and material-handling machinery with operating weights exceeding six metric tons, typically governed by KCS (Korean Construction Standards) structural integrity protocols and mandatory operator licensing under Ministry of Employment and Labor directives. Excavators dominate rental transaction volumes due to versatility across residential foundation work and utility trenching applications. Short-term rental structures capture disproportionate margin pools from emergency infrastructure repairs and seasonal construction peaks, while long-term rental agreements anchor revenue predictability for fleet-heavy operators serving Gwangju and Daegu industrial corridors.
MFDS equipment safety inspections, KOSHA occupational exposure limits, and Ministry of Land, Infrastructure and Transport construction machinery registration requirements collectively elevate compliance costs for rental fleet operators while accelerating retirement of non-certified legacy equipment. KOSHA enforcement of vibration exposure thresholds specifically drives demand for newer-generation low-vibration excavators and remote-controlled demolition equipment. Stakeholders must monitor pending amendments to the Construction Machinery Management Act and pre-position certified replacement capacity before regulatory phase-out deadlines tighten.
Market Dynamics
Seoul's metropolitan densification mandates are compressing project timelines and forcing rental fleet operators toward compact, low-emission machinery configurations that satisfy KOSHA vibration exposure thresholds and MFDS safety certification windows.
Growth Catalysts
- Urban Renewal Mandates:Seoul Metropolitan Government's district redevelopment zones require specialized demolition and foundation equipment, concentrating rental demand in the capital corridor.
- KOSHA Vibration Standards:Enforcement of occupational exposure limits accelerates fleet turnover toward low-vibration excavators and remote-controlled demolition systems.
- Gyeonggi Industrial Belt Expansion:Logistics hub construction in Hwaseong and Pyeongtaek generates sustained demand for heavy lifting and material-handling rentals.
Market Restraints
- Steel Input Volatility:Equipment manufacturing cost fluctuations compress rental margin buffers for fleet-heavy operators holding depreciating assets.
- Seoul-Centric Supply Concentration:Over 60 percent of certified rental capacity clusters in the capital region, creating availability gaps in Gwangju and Daegu corridors.
- Technical Limitation:Battery-electric heavy equipment lacks sufficient duty-cycle duration for continuous trenching and earthmoving applications.
Strategic Opportunities
- Busan Port Modernization:Maritime infrastructure upgrades create underpenetrated demand for specialized material-handling and port crane rentals.
- Remote Operation Convergence:Integration of 5G telemetry with hydraulic control systems enables unmanned equipment deployment in hazardous demolition zones.
- Jeju Island Development:Tourism and renewable energy projects drive demand for compact, low-ground-pressure equipment unserved by mainland fleet operators.
Industry Challenges
- Certification Timeline Compression:MFDS equipment safety inspection backlogs delay fleet deployment during peak construction windows.
- Operator Licensing Bottleneck:Ministry of Employment and Labor mandatory certification requirements constrain qualified labor supply for specialized machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Heavy Construction Equipment Rental Market |
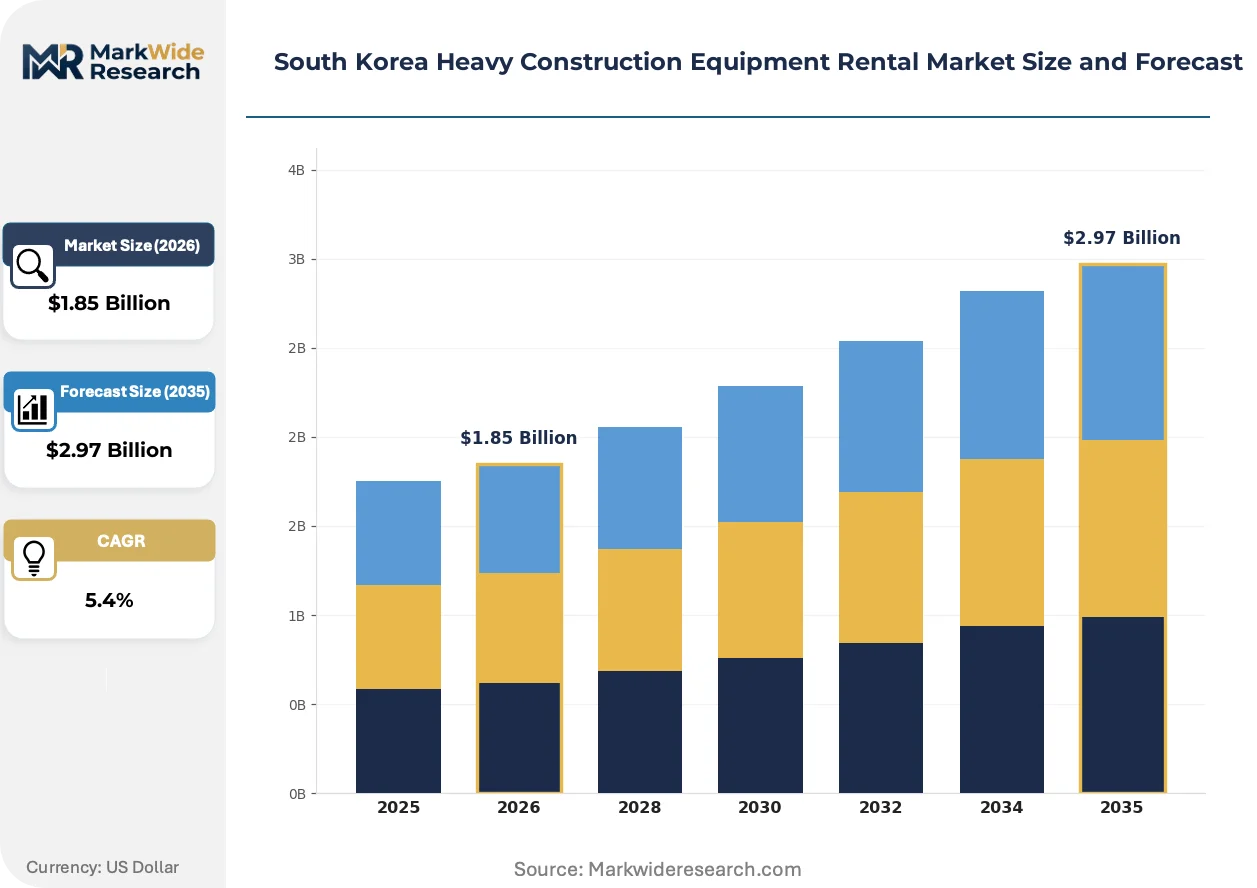
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Loaders End User: Construction Companies, Mining Firms, Infrastructure Developers, Contractors Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Equipment Trading Application: Residential Construction, Commercial Projects, Industrial Development, Road Construction |
| Companies Covered | Caterpillar, Volvo Construction Equipment, HD Hyundai Construction Equipment, XCMG Group, SANY Group, Doosan Infracore, Hitachi Construction Machinery, Hansung Engineering, Komatsu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Heavy Construction Equipment Rental Market Trends and Innovations
Telematics integration and electrification pathways are restructuring how rental fleets are deployed, monitored, and maintained across South Korea's constrained urban construction sites.
Telematics-enabled predictive maintenance is decomposing traditional time-based service intervals into condition-triggered interventions. Major infrastructure developers in the Seoul metropolitan area now mandate real-time equipment health monitoring as a contract precondition. This capability compression is forcing smaller rental operators toward third-party platform subscriptions or fleet management partnerships.
MFDS amendments to the Construction Machinery Management Act are tightening registration and inspection protocols for equipment over six metric tons. Rental operators face accelerated retirement timelines for legacy fleets lacking current safety certifications. The regulatory friction concentrates most acutely on excavator categories serving residential foundation work, where operators pre-position certified replacement capacity ahead of phase-out deadlines.
Construction procurement teams now unbundle equipment rental from operator provision, creating direct relationships with certified equipment providers separate from general contractors. This channel disintermediation is visible across Gyeonggi Province corridor projects, where developer-led procurement models displace traditional subcontractor equipment sourcing. The shift compresses rental transaction cycles and elevates compliance documentation requirements for fleet operators.
South Korea Heavy Construction Equipment Rental Market Segmentation
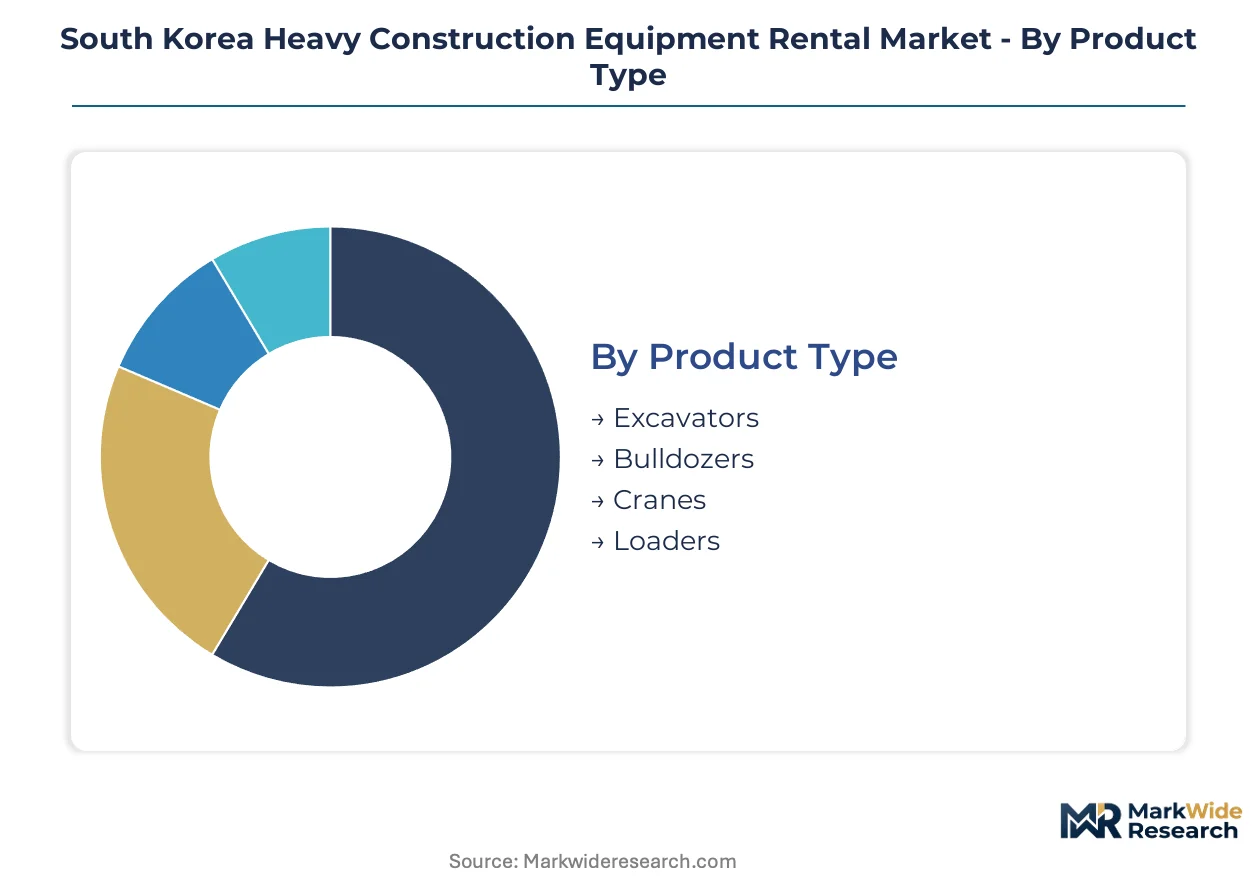
Equipment rental demand in South Korea fragments across project duration, machinery specification, and end-user procurement sophistication. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape fleet operator strategies.
Product Type:
Domestic manufacturing concentration in Gyeonggi Province anchors excavator and loader availability, while crane fleets depend heavily on imported Japanese and European components subject to longer lead times.
- Excavators:Hydraulic crawler units with operating weights from six to forty metric tons dominate transaction volumes across Seoul's dense urban renewal zones. Foundation contractors in the capital corridor specify low-vibration models to satisfy KOSHA occupational exposure mandates during residential basement excavation.
- Cranes:Tower and mobile configurations serve high-rise construction in Busan's Haeundae district and Incheon's Songdo International Business District. MFDS structural certification requirements for lifting equipment above twenty metric tons compress available fleet supply during peak construction windows.
- Bulldozers:Tracked earthmoving platforms concentrate in highway and landfill projects across the Honam region.
- Loaders:Wheel-mounted material handlers support logistics hub construction in Pyeongtaek and Hwaseong industrial zones.
Excavators command the established base. The steepest expansion runs through crane categories serving vertical construction in secondary cities.
End User:
Procurement sophistication varies sharply between state-backed infrastructure developers and fragmented residential contractors, creating tiered service requirements across the customer base.
- Infrastructure Developers:Korea Land & Housing Corporation and Seoul Metropolitan Government agencies mandate ISO 9001-certified fleet operators with real-time telematics integration. These entities unbundle equipment rental from general contracting, forcing direct commercial relationships with certified providers.
- Construction Companies:Mid-tier builders in the Gyeonggi Province corridor favor long-term rental agreements to anchor project cost predictability. Their procurement teams prioritize equipment age and maintenance documentation over brand specification.
- Contractors:Small-scale operators serving Jeju Island and Gangwon Province tourism projects drive seasonal short-term demand spikes.
- Mining Firms:Limestone and aggregate extraction operations in North Chungcheong Province require specialized heavy-duty configurations.
Infrastructure developers anchor revenue stability. Contractors generate the most volatile but highest-margin transaction flow.
Service Type:
Rental structure selection correlates directly with project financing certainty and regulatory inspection scheduling constraints.
- Short-Term Rental:Daily and weekly arrangements capture emergency infrastructure repair demand following monsoon damage to Seoul's aging sewer networks. These transactions command premium rates but require rapid MFDS certification verification that strains operator administrative capacity.
- Long-Term Rental:Monthly and annual agreements dominate Gwangju and Daegu industrial corridor projects where construction timelines extend across multiple fiscal years. Fleet operators depreciate assets against predictable revenue streams while embedding maintenance obligations.
- Maintenance Services:Third-party service contracts appeal to construction companies lacking in-house hydraulic technician capacity.
- Equipment Trading:Secondary market transactions accelerate as MFDS phase-out deadlines approach for legacy fleet components.
Long-term rental locks in the revenue base. Short-term structures deliver the steepest margin expansion.
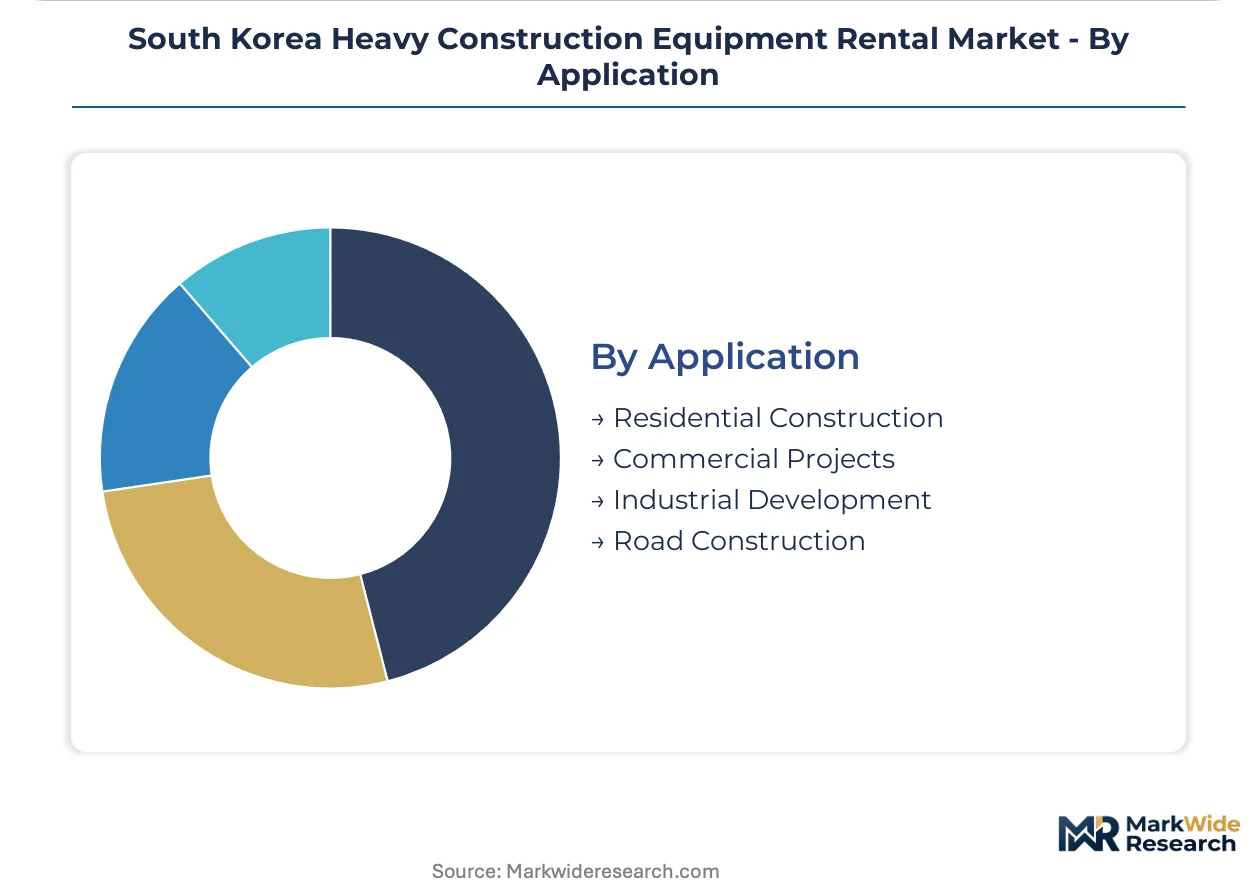
Application:
Project type determines machinery specification, emission compliance tier, and operator certification requirements across South Korea's construction economy.
- Residential Construction:Basement excavation and foundation work in Seoul's district redevelopment zones drives compact excavator demand. KOSHA vibration exposure limits force rapid fleet turnover toward remote-controlled demolition equipment for dense urban sites.
- Commercial Projects:Office and retail development in Sejong City and Busan's Centum City complex requires crane-heavy lifting configurations. These projects concentrate demand in metropolitan areas with established certified operator pools.
- Industrial Development:Semiconductor fabrication facilities in Yongin and Pyeongtaek generate demand for precision earthmoving with strict contamination protocols.
- Road Construction:Expressway expansion in South Gyeongsang Province sustains bulldozer and motor grader utilization rates.
Residential applications anchor volume throughput. Industrial development projects are climbing the fastest as semiconductor facility construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS equipment safety certifications and KOSHA workplace standards are redistributing rental fleet capacity across South Korea's industrial corridors. Regional demand concentrates where urban renewal mandates intersect with semiconductor fabrication expansion.
Seoul Capital Area
Seoul Metropolitan Government's district redevelopment zones drive compact excavator demand for dense urban demolition. KOSHA vibration exposure enforcement accelerates fleet turnover toward remote-controlled equipment. Gangnam and Yeouido commercial clusters anchor premium crane rental transactions for high-rise foundation work.
Busan-Ulsan
Maritime infrastructure upgrades at Busan Port generate sustained demand for specialized material-handling and heavy-lift configurations. MFDS structural certification requirements for port crane fleets above twenty metric tons compress available supply during peak shipping windows. Ulsan's petrochemical complexes require explosion-proof equipment specifications rarely held by mainland operators.
Daegu-Gyeongbuk
Secondary city industrial corridor expansion sustains long-term rental agreements for earthmoving fleets serving Gumi electronics manufacturing zones. Ministry of Land, Infrastructure and Transport construction machinery registration requirements elevate compliance costs for regional fleet operators. Waegwan logistics hub construction concentrates loader demand in the Nakdong River basin.
Daejeon-Sejong
Administrative capital relocation and government complex construction sustain predictable crane and concrete equipment rental cycles. Korea Land & Housing Corporation procurement mandates ISO 9001-certified operators with real-time telematics integration. Sejong City's planned district development creates underpenetrated demand for precision earthmoving with strict contamination protocols.
Gwangju-Honam
Honam Expressway expansion and agricultural processing facility construction sustain bulldozer utilization rates across South Jeolla Province. Seasonal monsoon damage to aging sewer infrastructure generates emergency short-term rental spikes. Naju and Yeosu industrial zones lack sufficient certified rental capacity relative to project pipeline depth.
South Korea Heavy Construction Equipment Rental Market Competitive Landscape
Player mix skews toward domestic manufacturing-anchored rental operators and multinational premium-positioned service networks. Market structure concentrates around three strategic tiers: peninsula-wide fleet operators with manufacturing integration, regional specialists serving secondary corridors, and premium-positioned multinationals with extended service networks. Consolidation pressures favor operators with backward integration into equipment production and captive maintenance technician pools.
Within the domestic manufacturing-anchored tier, HD Hyundai Construction Equipment and Doosan Infracore exemplify fleet operators leveraging captive production capacity to secure rental availability across constrained supply windows. Caterpillar occupies a position among premium-positioned multinationals with service infrastructure in Busan and Incheon industrial zones. These three companies represent the dominant competitive archetypes: manufacturing-integrated peninsula coverage, specialized urban demolition configuration, and premium service network density.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| HD Hyundai Construction Equipment |
| XCMG Group |
| SANY Group |
| Doosan Infracore |
| Hitachi Construction Machinery |
| Hansung Engineering |
| Komatsu |
| Others |
Pricing and Supply Chain Analysis
Long-term rental agreements with embedded maintenance obligations lock in supply access for Gwangju and Daegu industrial corridor projects while anchoring price visibility against steel input volatility. This contract-structure pattern concentrates pricing power with peninsula-wide fleet operators holding backward integration into domestic manufacturing capacity.
Pricing Analysis
Certification level under MFDS and KOSHA standards creates the primary spread between qualified fleet operators and marginal providers. Pricing stratifies across ISO 9001-certified operators with real-time telematics, standard-tier providers with current safety registrations, and economy operators holding depreciating legacy fleets. Cost compression in the economy tier is intensifying because MFDS phase-out deadlines accelerate equipment retirement timelines. Small-scale contractors serving Jeju Island tourism projects exhibit highest price sensitivity, while Korea Land & Housing Corporation mandates absorb premium positioning without volume negotiation.
Supply Chain Analysis
South Korea and Japan anchor hydraulic component fabrication and precision electronics for telematics integration. Domestic production draws from specialty steel suppliers in Pohang and imported hydraulic systems from Japanese component manufacturers. Single-source vulnerability concentrates in semiconductor-dependent control systems for remote-operated demolition equipment. Distribution runs through Seoul-Gyeonggi corridor hubs with secondary logistics nodes in Busan and Daegu serving regional project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as procurement teams unbundle equipment rental from general contracting, displacing traditional subcontractor relationships across Gyeonggi Province corridor projects.
For Market Incumbents: Secure telematics-enabled predictive maintenance capabilities before third-party platform subscriptions commoditize fleet monitoring services. Deepen backward integration into hydraulic technician training pools to offset Ministry of Employment and Labor certification bottlenecks. Lock in long-term offtake agreements with semiconductor fabrication facility developers in Yongin and Pyeongtaek to anchor revenue predictability against steel input volatility.
For New Entrants and Emerging Players: Remote-controlled demolition equipment servicing presents a service-layer gap where peninsula-wide operators under-serve dense urban renewal zones in Seoul's Gangnam and Yeouido clusters. Target Jeju Island and Gangwon Province tourism corridors where mainland fleet operators lack compact, low-ground-pressure equipment availability. Enter through maintenance-service bundling with short-term rental structures rather than capital-heavy fleet acquisition.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with captive maintenance technician pools and established KOSHA compliance documentation. The long-term viability window favors operators with demonstrated ability to navigate MFDS inspection backlogs and pre-position certified replacement capacity. Monitor Construction Machinery Management Act amendment progress as the signal to watch for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time equipment health monitoring satisfies Korea Land & Housing Corporation contract preconditions. |
| Backward Integration into Technician Training | In-house hydraulic certification capacity offsets Ministry of Employment and Labor licensing bottlenecks. |
| Remote Operation Capability Buildout | 5G-integrated hydraulic control systems enable unmanned deployment in hazardous Seoul demolition zones. |
| Long-term Supply Agreement with Semiconductor Developers | Precision earthmoving contracts with Yongin and Pyeongtaek fabrication facilities anchor multi-year revenue. |
| Geographic Expansion to Jeju Island | Tourism and renewable energy projects lack sufficient certified compact equipment from mainland operators. |
Research Methodology
A spread of perspectives from fleet operations managers, maintenance directors at rental companies, procurement leads at Korea Land & Housing Corporation, and hydraulic technician training coordinators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Ministry of Land, Infrastructure and Transport construction machinery registration databases, KOSHA occupational exposure enforcement records, and MFDS equipment safety inspection filings. Bottom-up equipment transaction modeling triangulated against top-down construction expenditure projections across the analysis window.
Segmentation dimensions modeled span product type, end-user procurement sophistication, service structure, and application vertical throughout the forecast period. CAGRs derived from equipment replacement cycle analysis against regulatory phase-out timelines and urban renewal project pipeline depth. Industry-specific forecast inputs incorporated KOSHA vibration standard enforcement trajectories and semiconductor fabrication facility construction acceleration patterns.
Material uncertainties — steel price volatility, MFDS inspection backlog duration, battery-electric equipment duty-cycle breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision triggers in regulatory amendment timing and construction financing availability. Recalibration cycles align with material shifts in KOSHA enforcement intensity and Seoul Metropolitan Government district redevelopment zone announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Yard Crane Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Sawmill Machinery Market