
 Digital Laser Levels Market | 2026-2036
Digital Laser Levels Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Laser Levels Market Insights
Multi-source procurement among tool distributors is expanding as construction supply houses diversify beyond single-brand laser level portfolios. Bosch leverages its sensor manufacturing depth to anchor premium self-leveling lines across European retail channels. DEWALT competes through battery-platform integration with its cordless power tool ecosystem. Hilti sustains direct-to-contractor sales models that dominate commercial infrastructure accounts in North America.
Digital laser levels are electro-optical instruments that project visible or infrared reference beams with angular accuracy typically rated at plus or minus fractions of a degree, used to establish horizontal, vertical, or graded planes across construction and surveying workflows. Self-leveling units now lead product category volume due to operator time savings on large commercial sites, while rotary laser configurations capture the highest margin pools in specialized roadwork grading applications. Semiconductor laser diode technology displaces legacy helium-neon sources across mid-tier price bands, though solid-state architectures still dominate precision structural engineering contracts where thermal stability matters most.
FCC emission limits govern laser classification and maximum permissible exposure for devices sold in the United States, while CE marking under EU machinery directives mandates interlock and warning-label standards for European distribution. OSHA construction safety regulations indirectly drive replacement cycles by requiring documented calibration traceability on federally funded projects. Stakeholders must monitor how emerging quantum cascade laser research reshapes long-range land survey capabilities and whether ANSI tolerance updates force hardware refresh decisions among contractor fleets.
Market Dynamics
Semiconductor laser diodes are compressing price-performance curves across mid-tier digital laser level segments while ANSI tolerance tightening forces hardware refresh cycles among contractor fleets. This dual pressure rewards manufacturers with captive sensor production and punishes pure-play assemblers dependent on external diode sourcing.
Growth Catalysts
- OSHA calibration mandates:Federally funded construction projects in the United States now require documented traceability for leveling instruments, accelerating replacement demand among commercial contractors.
- Self-leveling automation:Civil engineering firms in Germany are adopting rotary units that eliminate manual grade-setting, reducing crew time on foundation layout by half.
- Green building codes:LEED certification requirements across multiple jurisdictions specify precision grading for stormwater management, embedding laser-level accuracy into environmental compliance workflows.
Market Restraints
- Diode supply concentration:GaN-based semiconductor laser production clusters in East Asian foundries, exposing mid-tier manufacturers to single-source fragility.
- Helium-neon legacy lock-in:Precision structural engineering contracts still specify HeNe sources for thermal stability, fragmenting R&D investment across incompatible architectures.
- CE machinery directive costs:European interlock and warning-label compliance adds fixed certification overhead that disproportionately burdens sub-$500 price bands.
Strategic Opportunities
- Battery-platform convergence:Cordless power tool ecosystems are creating captive demand for cross-compatible laser level attachments among residential renovation contractors.
- Roadwork digitization:Machine control integration with motor grader fleets is opening rotary laser margin pools in transportation infrastructure maintenance.
- Quantum cascade R&D:Long-range land survey applications are attracting defense and geospatial investment that will eventually cascade into commercial construction instruments.
Industry Challenges
- Optical calibration expertise:Field service networks lack technicians trained in interferometer-based accuracy verification, extending warranty resolution timelines.
- Multi-standard compliance:Simultaneous FCC emission limits, CE machinery directives, and emerging state-level laser safety laws force SKU proliferation without volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Laser Levels Market |
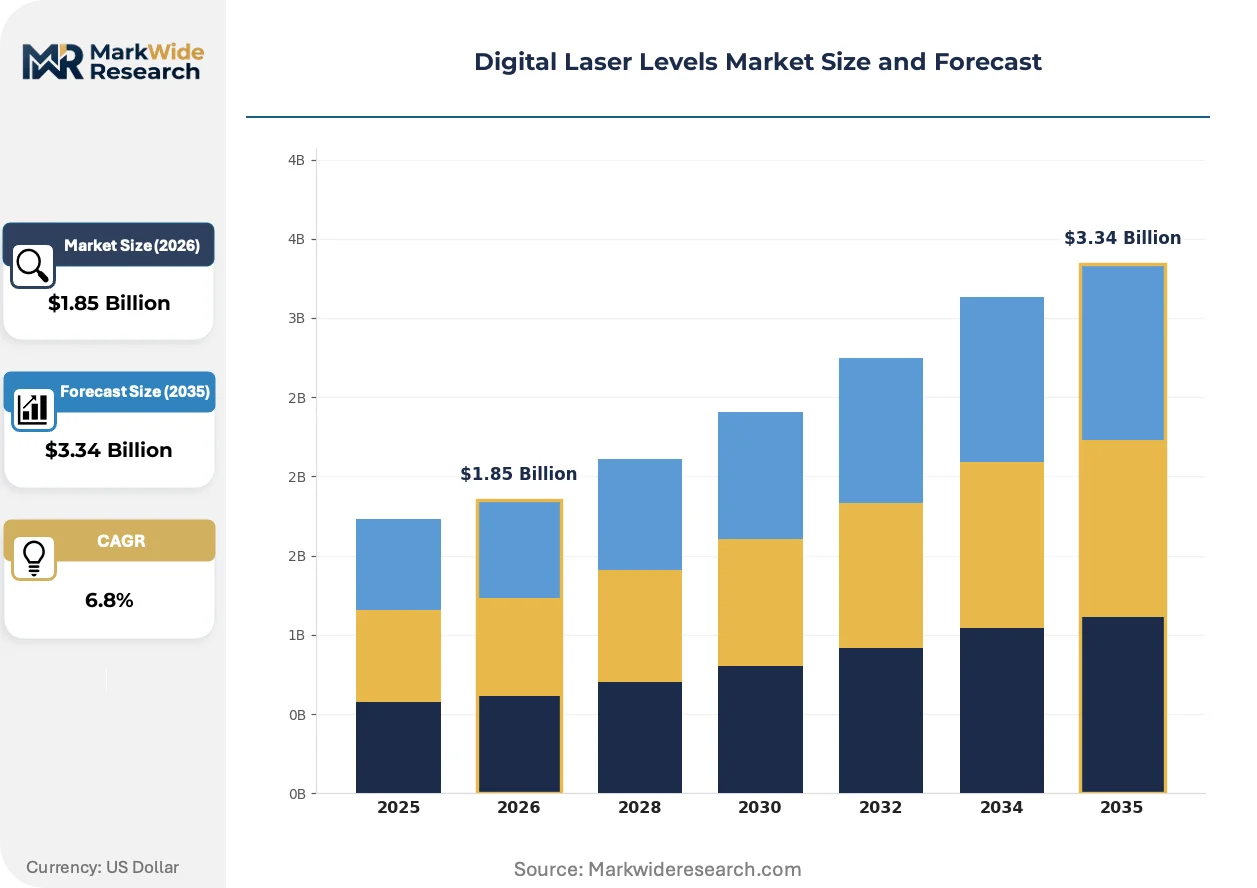
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Leveling, Manual, Cross Line, Rotary, Pipe Laser, Line Laser Technology: Laser Diode, Helium-Neon, Solid-State, Semiconductor, Fiber Laser, Quantum Cascade Application: Construction Surveying, Interior Alignment, Roadwork Grading, Land Survey, Structural Engineering, Site Planning End User: General Contractors, Surveyors, Civil Engineers, Builders, Infrastructure Developers, Architectural Firms |
| Companies Covered | Bosch, DEWALT, Leica Geosystems, Spectra Precision, Topcon, Hilti, Huepar, Milwaukee, Makita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Laser Levels Market Trends and Innovations
Active alignment between sensor miniaturization and jobsite connectivity protocols is compressing the feature gap between professional and prosumer laser level tiers. This convergence is destabilizing traditional price stratification while creating new service-attachment revenue models.
Semiconductor laser diode arrays are rewriting the cost structure of self-leveling instruments by replacing gas-discharge sources with solid-state alternatives that require no warm-up stabilization. Residential contractors in North American renovation markets are adopting these units for interior finish work where thermal drift tolerance is relaxed. The technology is rewriting procurement patterns by enabling battery-powered portability that helium-neon architectures cannot match.
OSHA construction safety regulations are tightening documented calibration intervals for instruments used on federally funded infrastructure, creating compliance-driven replacement cycles independent of equipment failure rates. Commercial general contractors in the United States are responding by consolidating fleet purchases with vendors offering certified recertification programs. The regulatory pressure is most acute among unionized trades where apprenticeship training mandates specify instrument accuracy thresholds.
Direct-to-contractor sales models are displacing traditional construction supply house distribution for premium rotary laser configurations used in commercial infrastructure. Hilti's captive salesforce model in North America is capturing specification authority from project engineers before bids are released. This channel shift is most visible in transportation and utility verticals where project-based procurement concentrates buying power among a handful of prime contractors.
Digital Laser Levels Market Segmentation
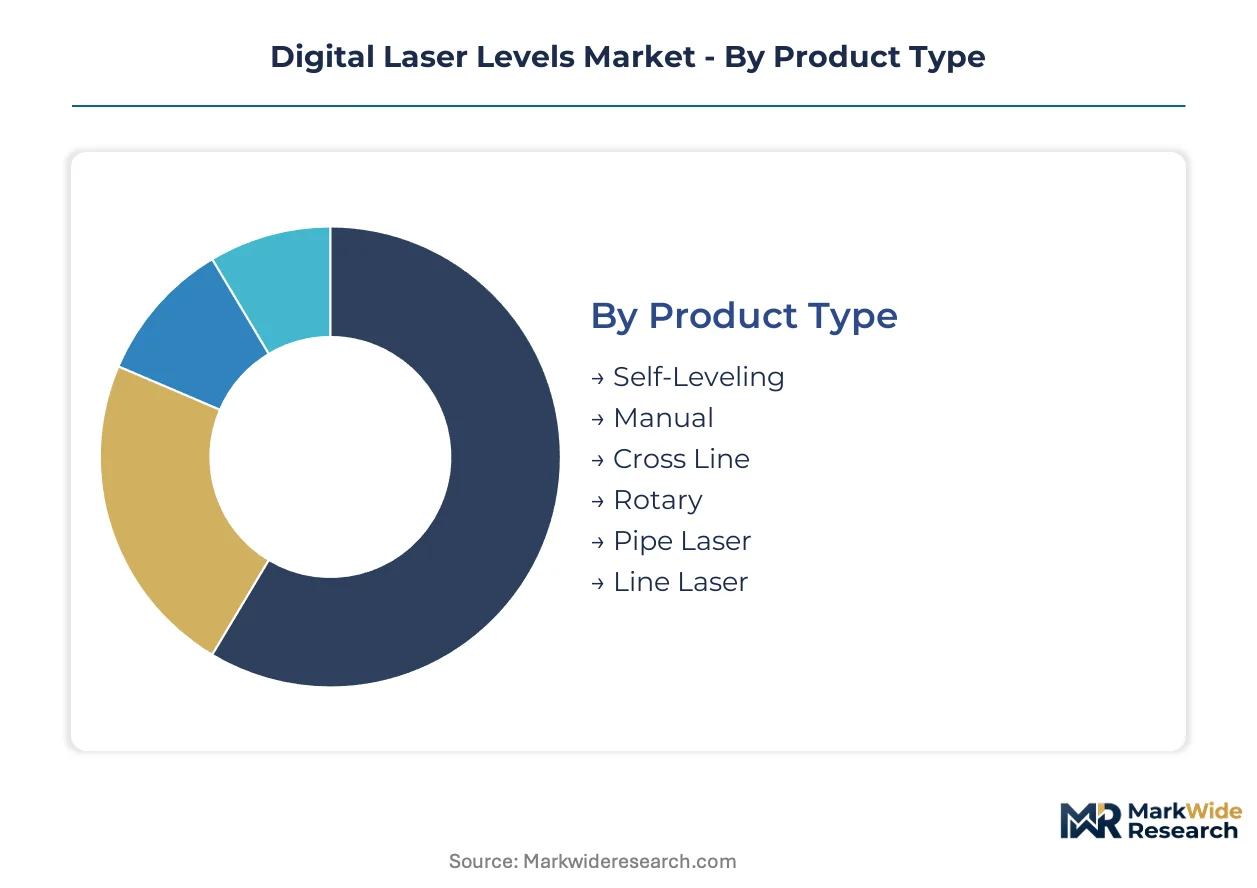
Digital laser level procurement patterns diverge sharply between high-volume residential renovation and precision commercial infrastructure. Understanding where specification authority concentrates across product tiers, technologies, and end-user workflows reveals which segments command margin premiums versus those that compete on replacement velocity.
Product Type:
Self-leveling units dominate unit volume while rotary configurations capture the highest margin pools in specialized roadwork applications.
- Self-Leveling:Pendulum-based or electronic servo mechanisms automatically establish horizontal and vertical reference planes within seconds of setup. German civil engineering firms specify these for foundation layout where crew time minimization outweighs acquisition cost. Demand concentrates among commercial general contractors facing OSHA-mandated calibration documentation on federally funded projects.
- Rotary:Spinning beam projectors cast 360-degree horizontal planes visible across hundreds of meters for machine control integration. North American transportation infrastructure maintenance contracts specify rotary units for motor grader fleet compatibility. These configurations sustain the steepest price premiums due to optical component precision and thermal stabilization requirements.
- Manual:Bubble-vial assisted instruments requiring operator adjustment for grade establishment. Budget-conscious residential renovation contractors in price-sensitive markets retain these for interior finish work where tolerance requirements remain relaxed.
- Cross Line:Fixed 90-degree beam intersection for interior wall alignment and cabinetry installation. Residential kitchen and bath specialists favor these for compact form factors and battery-powered portability.
- Pipe Laser:Specialized grade projection for underground utility alignment and sewer line installation. Municipal infrastructure contractors specify these for gravity-fed drainage system compliance with local building codes.
- Line Laser:Single or multiple fixed beam projection for basic leveling tasks. Entry-level residential DIY channels move volume here, though professional adoption lags due to accuracy limitations versus self-leveling alternatives.
Today's leader: Self-Leveling. Tomorrow's challenger: Rotary.
Technology:
Semiconductor architectures are displacing legacy gas-discharge sources across mid-tier price bands while solid-state platforms retain specification lock-in for precision structural engineering.
- Semiconductor:Gallium nitride and indium phosphide diode arrays deliver instant-on operation without thermal stabilization delays. North American residential renovation markets are shifting procurement toward these battery-compatible platforms. The technology enables cordless portability that helium-neon architectures cannot match, compressing price-performance curves for interior finish contractors.
- Solid-State:Nd:YAG and similar crystal-based sources maintain beam coherence across temperature extremes. Precision structural engineering contracts in Germany and Switzerland still specify these for thermal stability on long-duration measurement campaigns. The segment commands premium pricing due to limited supplier base and specialized optical fabrication requirements.
- Laser Diode:Discrete semiconductor emitters in visible red or green wavelengths for general construction applications. Mid-tier manufacturers source these from East Asian foundries, exposing supply chains to concentration risk.
- Helium-Neon:Gas-discharge tubes producing highly coherent 632.8nm red output. Legacy specification persistence in metrology-grade contracts sustains niche demand despite bulk and power consumption disadvantages.
- Fiber Laser:Rare-earth-doped fiber amplification for high-power industrial alignment tasks. Heavy civil infrastructure applications requiring kilometer-range visibility specify these, though commercial construction adoption remains limited.
- Quantum Cascade:Inter-subband semiconductor transitions enabling mid-infrared wavelengths for atmospheric penetration. Defense and geospatial R&D investment is advancing these toward future land survey commercialization.
Semiconductor platforms are climbing the fastest; solid-state retains specification authority where thermal drift tolerance tightens.
Application:
Construction surveying commands the broadest end-user base while roadwork grading concentrates buying power among infrastructure prime contractors with machine control integration requirements.
- Construction Surveying:Foundation layout, elevation transfer, and building footprint establishment for commercial and residential structures. General contractors across the United States specify self-leveling rotary units to meet documented calibration traceability requirements on federally funded projects. OSHA tightening of tolerance verification intervals is accelerating replacement cycles independent of equipment failure rates.
- Roadwork Grading:Sub-base preparation, asphalt paving, and drainage slope establishment for transportation infrastructure. German civil engineering firms are adopting machine control-integrated rotary lasers that eliminate manual grade-setting, reducing crew time by half on highway maintenance contracts.
- Interior Alignment:Wall framing, ceiling grid installation, and finish carpentry reference plane projection. Residential renovation contractors favor cross-line and line laser configurations for compact portability in confined spaces.
- Land Survey:Boundary determination, topographic mapping, and geodetic control network establishment. Surveyors specify long-range rotary or pipe laser configurations depending on terrain and vegetation density.
- Structural Engineering:Deformation monitoring, load testing alignment, and precision assembly verification. Swiss and German precision engineering culture drives adoption of solid-state and helium-neon sources for thermal stability on critical infrastructure projects.
- Site Planning:Pre-construction staking, utility location marking, and erosion control layout. Infrastructure developers specify these for stormwater management compliance with LEED certification requirements across multiple United States jurisdictions.
Roadwork grading is expanding most quickly; construction surveying maintains the deepest installed base.
End User:
General contractors control the largest procurement volume while civil engineers concentrate specification authority for premium rotary configurations in transportation infrastructure.
- General Contractors:Commercial and residential construction firms managing full-project delivery. United States-based commercial general contractors are consolidating fleet purchases with vendors offering certified recertification programs to satisfy OSHA calibration mandates on federally funded infrastructure. Unionized trades with apprenticeship accuracy thresholds drive replacement velocity.
- Civil Engineers:Transportation, utility, and environmental infrastructure design and oversight professionals. German civil engineering firms specify self-leveling rotary units for foundation layout automation, eliminating manual grade-setting crew time. Specification authority concentrates here for premium configurations before project bidding.
- Surveyors:Licensed land measurement professionals conducting boundary and topographic work. Long-range visibility requirements favor rotary and pipe laser configurations with solid-state thermal stability for extended field campaigns.
- Builders:Residential construction specialists focused on single-family and multi-family housing. Battery-platform compatibility with cordless power tool ecosystems is driving cross-brand attachment purchases.
- Infrastructure Developers:Public-private partnership entities financing transportation, utility, and environmental projects. LEED stormwater precision grading requirements are embedding laser-level accuracy into environmental compliance workflows.
- Architectural Firms:Design professionals specifying construction tolerances and verification methods. Growing involvement in construction administration phases is expanding instrument specification influence beyond traditional engineering channels.
Civil engineers set the specification agenda; general contractors execute the procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering culture anchors the strongest regional demand concentration for self-leveling rotary units among civil engineering firms.
United States
OSHA calibration mandates on federally funded infrastructure projects drive documented traceability requirements for commercial general contractors. FCC emission limits govern laser classification and maximum permissible exposure for devices sold nationwide. Unionized trades in Chicago and New York Metro concentrate replacement velocity where apprenticeship training mandates specify instrument accuracy thresholds.
Germany
Civil engineering firms specify self-leveling rotary units to eliminate manual grade-setting crew time on foundation layout. CE marking under EU machinery directives mandates interlock and warning-label standards for European distribution. Baden-Württemberg's precision manufacturing clusters sustain specification authority for thermal-stabilized solid-state architectures in structural engineering contracts.
China
Residential construction volume and infrastructure renewal programs generate broad demand for battery-compatible semiconductor diode platforms. GB standards and MIIT regulations shape product certification requirements for domestic distribution. Yangtze River Delta manufacturing bases concentrate mid-tier laser diode sourcing for regional tool assemblers.
Japan
METI industrial standards and JIS certification requirements maintain strict tolerance specifications for professional-grade instruments. Kanto region construction technology adoption centers drive integration between laser leveling and machine control systems. Tokyo-based contractors prioritize thermal stability specifications for high-rise structural alignment workflows.
United Arab Emirates
Transportation infrastructure megaprojects and LEED-certified commercial developments embed precision grading into environmental compliance workflows. Dubai's municipal building codes specify stormwater management accuracy thresholds that mandate laser-level verification. Abu Dhabi-based infrastructure developers consolidate procurement among prime contractors with certified recertification program capabilities.
Digital Laser Levels Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cordless power tool ecosystem integration. The vendor base spans German precision engineering houses, North American construction tool conglomerates, and East Asian electronics specialists. Three strategic archetypes dominate: sensor-manufacturing integrators leveraging captive diode production, battery-platform ecosystem players capturing residential renovation channels, and direct-to-contractor sales organizations targeting commercial infrastructure accounts. Competitive moves concentrate on strategic partnerships for machine control integration and portfolio diversification into roadwork grading applications.
Among German-based precision instrument specialists, Leica Geosystems and Hilti exemplify the direct-to-contractor archetype with specification authority capture in transportation and utility verticals. Bosch anchors the sensor-integration tier through European retail channel penetration. DEWALT occupies the battery-platform convergence position within North American residential renovation markets. Spectra Precision represents the machine control integration specialist archetype for roadwork grading applications.
| Leading Market Players |
|---|
| Bosch |
| DEWALT |
| Leica Geosystems |
| Spectra Precision |
| Topcon |
| Hilti |
| Huepar |
| Milwaukee |
| Makita |
| Others |
Pricing and Supply Chain Analysis
Commercial general contractors consolidating fleet purchases under OSHA calibration mandates concentrate buying power among vendors offering certified recertification programs, anchoring a contract-based pricing model where documented traceability commands premium positioning over unit economics.
Pricing Analysis
GaN semiconductor laser diode costs pass through to mid-tier instrument pricing with variable lag depending on captive versus outsourced sourcing arrangements. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and after-sales service bundling. Cost compression in the sub-$500 economy tier intensifies because CE machinery directive compliance adds fixed overhead without volume scaling. Residential renovation contractors exhibit highest price sensitivity, while transportation infrastructure prime contractors prioritize thermal stability specifications over acquisition cost.
Supply Chain Analysis
Refurbishment flows for rotary laser configurations create secondary supply channels that extend equipment lifecycle and pressure new-unit pricing in the standard tier. East Asian foundries in Taiwan, South Korea, and China concentrate gallium nitride semiconductor laser production, exposing mid-tier assemblers to single-source fragility. Optical component fabrication draws from rare-earth mineral processing and precision glass manufacturing inputs. Distribution runs through construction supply houses diversifying beyond single-brand portfolios alongside direct-to-contractor sales organizations capturing specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA workplace safety guidelines function as a regulatory compounder, with documented calibration traceability mandates on federally funded infrastructure projects generating replacement demand independent of equipment failure rates.
For Market Incumbents: Deepen captive sensor production capabilities to insulate margin structures from GaN diode supply concentration in East Asian foundries. Expand certified recertification program coverage to capture fleet consolidation among commercial general contractors facing unionized trade apprenticeship accuracy thresholds. Fortify specification authority in transportation infrastructure through early engineer engagement before project bidding releases.
For New Entrants and Emerging Players: Launch via battery-platform ecosystem integration targeting residential renovation contractors in North American markets where cordless power tool compatibility drives cross-brand attachment purchases. Prioritize semiconductor diode-based cross-line configurations for interior finish work where thermal drift tolerance remains relaxed. Exploit CE machinery directive compliance gaps in the sub-$500 economy tier through simplified interlock architectures.
For Investors and Strategic Acquirers: Construction tool conglomerates with captive distribution networks are the most active acquirer in this space, seeking sensor-manufacturing depth to anchor premium self-leveling lines. Long-term viability hinges on quantum cascade laser commercialization timelines for geospatial and defense spillover into land survey applications. Monitor ANSI tolerance update cycles as hardware refresh inflection indicators among contractor fleet replacement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Control Integration | Rotary laser configurations capture margin pools in German highway maintenance contracts through motor grader fleet compatibility. |
| Backward Integration into Diode Sourcing | Captive GaN semiconductor production insulates Bosch and Hilti from East Asian foundry concentration risk. |
| Certified Recertification Program Expansion | OSHA calibration mandates drive commercial general contractors toward vendors offering documented traceability services. |
| Battery-Platform Ecosystem Convergence | DEWALT and Milwaukee capture residential renovation demand through cordless power tool cross-compatibility. |
| Quantum Cascade R&D Investment | Defense and geospatial funding advances mid-infrared wavelengths toward future land survey commercialization. |
Research Methodology
Bottom-up construction surveying and roadwork grading modeling reconciled against top-down semiconductor laser diode production tracking forms the analytical core of this study. Primary interviews with commercial general contractor procurement directors, civil engineering firm specification leads, construction supply house category managers, and aftermarket service technicians combined with secondary validation against FCC emission filings, OSHA regulatory updates, CE machinery directive documentation, and customs trade data for optical instrument classifications. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map GaN semiconductor laser diode supply through optical component fabrication to finished instrument assembly across product type, technology architecture, application workflow, and end-user procurement authority dimensions. CAGRs derive from segment-level replacement velocity modeling incorporating regulatory compliance cycle timing and machine control integration adoption curves. Forecast inputs include unionized trade apprenticeship training mandates and LEED certification jurisdiction expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ANSI tolerance threshold revisions or East Asian foundry supply disruptions. Practitioners should monitor OSHA calibration mandate enforcement intensity and quantum cascade laser defense funding allocation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hydraulic Tools Market
Tools
US Chalk Reel and Line Market
Tools
Riveting Tools Market
Tools
Edge Banders Market
Tools
Machine Tools Market
Tools
Surface Planer Market
Tools
Welding Products Market
Tools
Power Tool Accessories Market
Tools
Mortiser Market
Tools
Gas Cutting Machine Market
Tools
Core Shooter Machine Market
Tools
Tile Cutter Market
Tools
Press Machine Market
Tools
Wood Router Market
Tools
Rebar Cutter Market
Tools
Woodworking Router Bits Market