
 Diamond Core Drilling Market | 2026-2036
Diamond Core Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Core Drilling Market Analysis
Multi-source procurement for synthetic diamond matrices is realigning how tier-one contractors secure consumable supply. Sandvik leverages captive synthetic diamond production to control bit quality and delivery timelines across Scandinavian mining districts. Boart Longyear anchors its position through vertical integration into wireline drilling services, bundling equipment with operational contracts. Epiroc competes by specializing in automated drill rig integration, reducing labor exposure in deep-hole applications.
Diamond core drilling employs hollow cylindrical bits impregnated with industrial-grade synthetic or natural diamond crystals bonded to steel bodies, typically operating at rotational speeds of 300-1,200 RPM with water or synthetic mud flushing to extract intact rock cores for assay. The technique serves mineral exploration, geotechnical investigation, and concrete structure assessment by preserving subsurface material integrity for laboratory analysis. Wet core bits dominate revenue contribution where water access permits continuous operation, while dry core bits expand fastest in urban construction zones with discharge restrictions. Directional drilling technology captures premium pricing in deep mineral targets, though conventional rotary methods still occupy the majority of installed rig hours across developing mining belts.
OSHA silica permissible exposure limits and EU REACH restrictions on cobalt-tungsten carbide binders are forcing reformulation of bit matrix chemistries and accelerating wet system retrofits. EPA stormwater discharge rules for drilling mud affect environmental compliance costs at US exploration sites, while ISO 18758-1 testing protocols for rock drilling equipment shape product certification requirements in export markets. Stakeholders must monitor synthetic diamond supply concentration and evolving mine safety automation mandates to calibrate capital deployment and R&D prioritization.
Market Dynamics
Resource nationalism in copper-gold jurisdictions is fragmenting equipment procurement rules, forcing contractors to rebuild supply relationships around local content mandates and joint venture structures rather than traditional vendor-direct purchasing.
Growth Catalysts
- Deep mineral exploration:Australian and Canadian mining houses are expanding budgets for deposits below 500 meters, requiring specialized wireline-capable rigs and impregnated diamond bits rated for extreme depth.
- Silica exposure limits:OSHA's reduced permissible exposure levels and EU directives on respirable crystalline silica are accelerating wet drilling system retrofits across surface and underground operations.
- Synthetic diamond matrices:Advances in high-pressure high-temperature synthesis are improving bit durability in hard-rock formations, extending run lengths and reducing trip frequency in Scandinavian mining districts.
Market Restraints
- Cobalt-tungsten carbide binder restrictions:EU REACH regulations on cobalt compounds are forcing costly reformulation of bit matrix chemistries, compressing margins for consumable manufacturers.
- Water access constraints:Arid-zone exploration in Chile's Atacama and Australia's Pilbara limits wet system deployment, constraining addressable market for premium impregnated bits.
- Synthetic diamond supply concentration:Production of industrial-grade synthetic crystals clusters among a limited set of producers, creating vulnerability to supply disruption and price volatility.
Strategic Opportunities
- Urban geotechnical investigation:Dry core drilling systems with vacuum-assisted dust collection are penetrating densely built environments in Singapore and Dubai where water discharge faces strict municipal limits.
- Automated rig integration:Remote-operated drill rigs with real-time telemetry are reducing labor exposure in deep-hole applications, opening contracts with safety-conscious tier-one miners.
- Indonesia's downstream push:Resource nationalism policies are creating openings for local assembly partnerships and technology transfer arrangements to satisfy domestic content requirements.
Industry Challenges
- Skilled driller shortage:Experienced core drillers capable of managing deviation in deep directional holes are retiring faster than training programs replace them, constraining operational expansion.
- ISO 18758-1 certification timelines:Extended testing protocols for rock drilling equipment are delaying product launches in export markets, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Core Drilling Market |
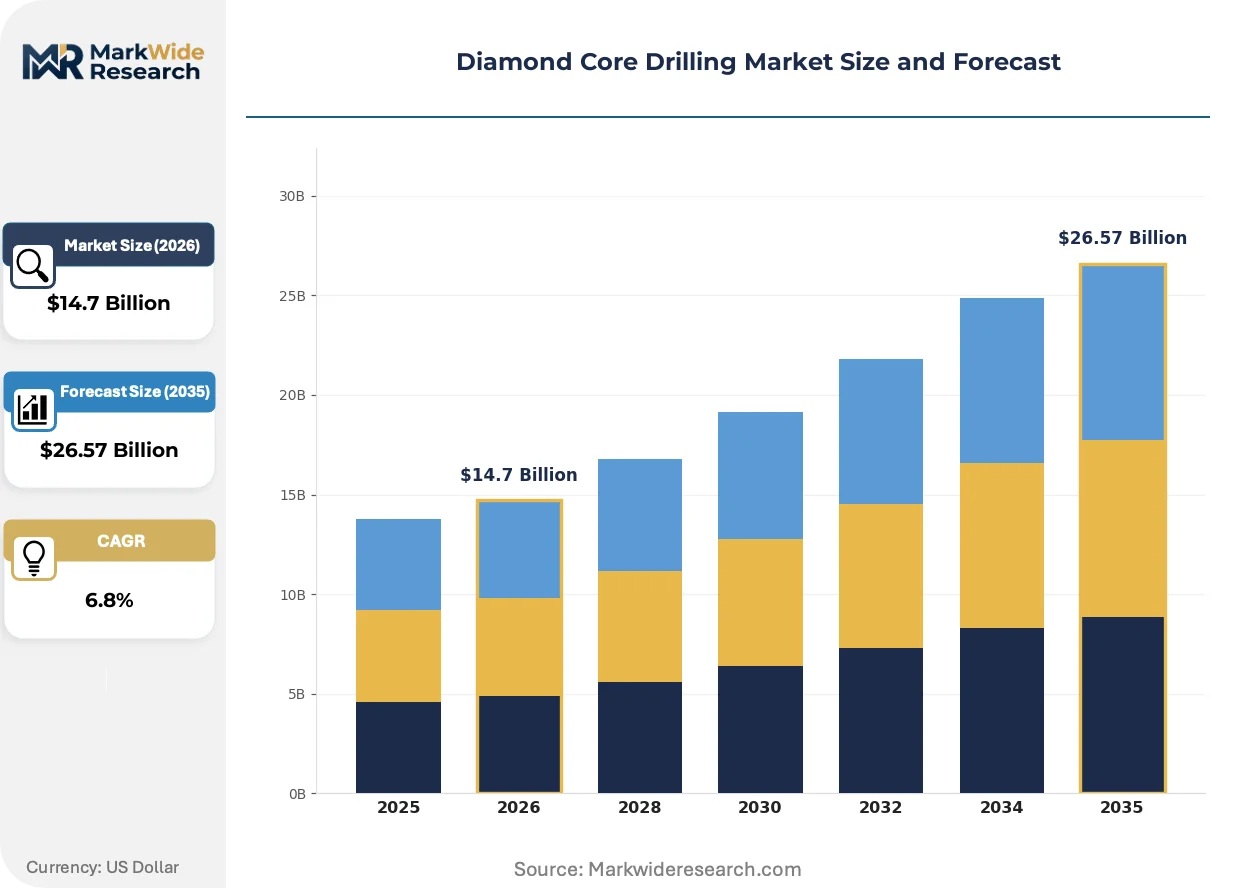
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Core Bits, Dry Core Bits, Diamond Wire Saws, Core Barrel Assemblies Application: Mining, Construction, Geotechnical, Environmental End User: Contractors, Mining Companies, Oil & Gas Firms, Research Institutions Technology: Conventional Drilling, Directional Drilling, Automated Drilling, Hybrid Systems |
| Companies Covered | Sandvik, Hilti Corporation, Boart Longyear, Tyrolit Group, Husqvarna, Schlumberger, Epiroc, Norton Abrasives, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Core Drilling Market Emerging Trajectories
Automation and environmental compliance are converging to reshape how drilling contractors deploy capital, with technology choices increasingly filtered through regulatory risk rather than pure performance metrics.
Telematics-enabled drill rig monitoring is decentralizing maintenance scheduling and fleet management decisions from central engineering offices to site-level supervisors. Tier-one contractors in Chile and Canada are adopting these systems fastest, driven by remote site logistics and labor cost pressures. Real-time vibration and torque data is compressing unplanned downtime by enabling condition-based bit replacement rather than fixed-interval pulls.
EU REACH restrictions on cobalt-tungsten carbide binders are forcing wholesale reformulation of bit matrix chemistries toward nickel-iron alternatives. Manufacturers serving European exploration markets are absorbing R&D costs to maintain certification, while redirecting legacy cobalt-containing inventory to jurisdictions with less stringent chemical registration requirements. The transition is most disruptive for impregnated bit producers with limited materials science capabilities.
Service unbundling is fragmenting traditional equipment-plus-consumables contracts as mining houses separate rig procurement from operational drilling services. Major exploration programs in Indonesia and Peru are now tendering these elements independently, favoring specialized drillers with owned rigs over integrated vendors. This pattern is compressing margins on bundled offerings while creating openings for pure-play consumable suppliers with technical field support capabilities.
Diamond Core Drilling Market Segmentation
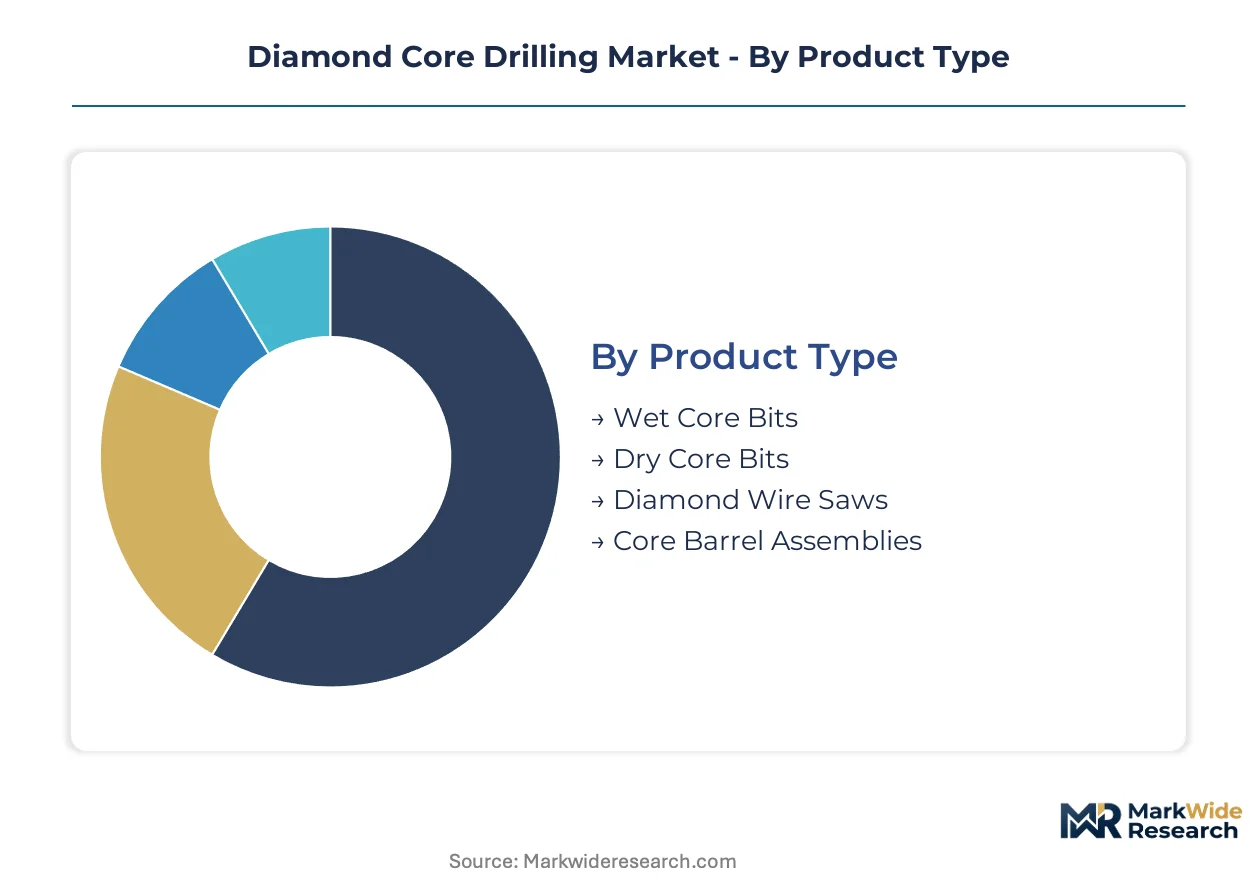
Diamond core drilling equipment fragments across four critical dimensions that determine procurement patterns and margin structures. Product type and application splits reveal where synthetic diamond supply concentration shapes competitive advantage, while technology and end-user categories expose automation adoption gaps and service bundling opportunities.
Product Type:
Supply concentration in industrial-grade synthetic diamond production concentrates competitive advantage among manufacturers with captive crystal synthesis or long-term offtake agreements.
- Wet Core Bits:Hollow cylindrical bits using water or synthetic mud flushing dominate revenue in mining belts with reliable water access. Australian and Canadian exploration programs drive demand for impregnated variants rated below 500 meters depth, where OSHA silica limits accelerate wet system deployment.
- Dry Core Bits:Vacuum-assisted dust collection systems penetrate Singapore and Dubai construction zones where municipal discharge restrictions block wet alternatives. Urban geotechnical investigation in dense built environments propels this segment, though bit life compression in abrasive formations constrains total cost economics.
- Diamond Wire Saws:Continuous loop cutting systems for concrete demolition and dimension stone extraction.
- Core Barrel Assemblies:Wireline-retrievable inner tube systems enabling rapid core recovery without full rod pulls.
Today's leader: Wet Core Bits. Tomorrow's challenger: Dry Core Bits.
Application:
Cost tier stratification separates capital-intensive mining deployments from price-sensitive construction and environmental monitoring contracts.
- Mining:Deep mineral exploration below 500 meters consumes premium impregnated bits and wireline-capable rigs. Chilean copper-gold porphyry belts and Indonesian resource nationalism policies reshape equipment procurement toward local content-compliant vendors.
- Construction:Structural concrete assessment and renovation drilling favors dry systems with rapid bit change mechanisms. Dubai and Singapore municipal discharge limits accelerate vacuum-assisted dust capture adoption in high-rise environments.
- Geotechnical:Subsurface investigation for foundation design and slope stability analysis.
- Environmental:Contaminated site characterization and groundwater monitoring with low-impact drilling protocols.
Mining commands premium pricing and longest contract tenors. Construction exhibits steepest expansion trajectory in dry system penetration.
End User:
Customer type determines whether procurement favors bundled equipment-service contracts or separated rig and consumable sourcing.
- Contractors:Independent drilling operators increasingly unbundle rig ownership from operational services, compressing margins on integrated vendor offerings while opening pure-play consumable supply relationships.
- Mining Companies:Tier-one miners in Australia and Canada prioritize automated rig integration to reduce labor exposure in deep-hole applications, driving telemetry-enabled fleet management adoption.
- Oil & Gas Firms:Geothermal and stratigraphic test programs with specialized coring requirements.
- Research Institutions:Academic and governmental geological surveys with intermittent, specification-driven procurement.
Contractors fragment purchasing power across decentralized decision nodes. Mining Companies consolidate specification authority at corporate engineering level.
Technology:
Maturity gradients separate proven conventional methods from emerging automated and directional capabilities capturing premium pricing.
- Conventional Drilling:Rotary methods with fixed toolface control occupy majority of installed rig hours across developing mining belts, though deviation management limitations constrain deep target precision.
- Directional Drilling:Steerable bottom-hole assemblies with real-time survey capability command premium pricing in deep mineral targets where geological intersection accuracy determines project economics.
- Automated Drilling:Remote-operated rigs with telemetry-enabled condition monitoring reduce labor exposure and unplanned downtime through vibration-based bit replacement scheduling.
- Hybrid Systems:Configurations combining conventional reliability with selective automation for rod handling and breakout functions.
Conventional Drilling anchors volume. Automated Drilling climbs the fastest as labor cost pressures and safety mandates converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining districts anchor exploration equipment demand through deep porphyry copper-gold targets below 500 meters. Canadian Arctic and Sudbury Basin operations drive wireline-capable rig procurement. Chilean resource nationalism policies reshape vendor relationships across the Andean copper belt.
Australia
Western Australia's Pilbara and Eastern Goldfields host expanded exploration budgets for iron ore and gold deposits beneath 500 meters. Safe Work Australia's crystalline silica exposure standards accelerate wet drilling retrofits across surface operations. Queensland's Mount Isa belt concentrates impregnated diamond bit demand from tier-one contractors.
Canada
Ontario's Sudbury Basin and Quebec's Abitibi greenstone belt consume premium wireline core barrel assemblies for nickel-copper targets. Health Canada's workplace hazardous materials regulations align with provincial silica limits in underground environments. British Columbia's Golden Triangle attracts automated rig deployment for remote site efficiency.
Chile
Atacama Desert copper porphyries face water access constraints that limit wet system penetration despite silica exposure rules. The country's national mining regulator enforces local content mandates that fragment traditional vendor-direct procurement. Antofagasta Region contractors rebuild supply relationships around joint venture structures.
Indonesia
Grasberg and Batu Hijau copper-gold operations drive demand for directional drilling capability in complex ore bodies. Ministry of Energy and Mineral Resources domestic content requirements create openings for local assembly partnerships. Sumbawa and Sulawesi exploration camps concentrate equipment procurement authority with safety-conscious multinational miners.
United States
Nevada's Carlin-type gold deposits and Arizona porphyry copper belts sustain exploration rig hours through metal price cycles. OSHA's reduced permissible silica exposure limits force wet system upgrades across Southwestern surface operations. Colorado and Idaho geothermal projects expand core drilling scope beyond traditional mineral targets.
Diamond Core Drilling Market Vendor Landscape
Global majors compete with regional champions across equipment fabrication and consumable supply chains. The vendor base clusters around three tiers: diversified mining equipment conglomerates with captive synthetic diamond production, specialized drilling contractors with backward-integrated bit manufacturing, and pure-play consumable suppliers with technical field support networks. Strategic moves concentrate on geographic expansion through local content partnerships and technology licensing for automated rig integration.
Among Scandinavian-based mining equipment specialists, Sandvik occupies a position exemplifying captive synthetic diamond synthesis for matrix quality control. Epiroc and Atlas Copco represent the automation-forward archetype, with Epiroc anchoring the telemetry-enabled rig segment. Boart Longyear sits within the integrated drilling services tier, bundling equipment with operational contracts across copper-gold jurisdictions. These three companies illustrate how competitive positioning fragments across upstream material control, midstream automation, and downstream service bundling.
| Leading Market Players |
|---|
| Sandvik |
| Hilti Corporation |
| Boart Longyear |
| Tyrolit Group |
| Husqvarna |
| Schlumberger |
| Epiroc |
| Norton Abrasives |
| Atlas Copco |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between wet-system impregnated bits and dry-system vacuum bits splits procurement budgets across Australian mining camps and Singapore construction zones, with each tier demanding distinct synthetic diamond quality grades and water-access logistics that reshape both supplier margins and distributor footprints.
Pricing Analysis
Input-cost pass-through from synthetic diamond crystal production runs through bit matrix pricing, with HPHT synthesis energy costs and cobalt-tungsten carbide binder reformulation expenses under EU REACH compressing margins for consumable manufacturers serving European exploration markets. Pricing stratifies across premium impregnated bits rated below 500 meters, standard wireline-capable assemblies, and economy-grade dry bits for urban geotechnical work. Cost compression in the mid-tier segment is intensifying because mining houses unbundle rig procurement from consumable supply, forcing pure-play bit suppliers to absorb field support costs. Contractors exhibit highest price sensitivity due to decentralized purchasing authority, while tier-one miners prioritize performance guarantees over unit economics.
Supply Chain Analysis
ISO 18758-1 certification requirements gate market entry for rock drilling equipment exports, forcing extended testing timelines that delay revenue recognition for manufacturers lacking established compliance pathways. Synthetic diamond crystal production concentrates in China, Russia, and select Scandinavian facilities, while bit matrix fabrication clusters in Germany, Sweden, and Australia. Raw material dependencies span industrial-grade synthetic diamonds, nickel-iron binder alloys replacing restricted cobalt formulations, and tungsten carbide substrates. Single-source vulnerability in HPHT synthesis capacity creates exposure to energy price shocks and export licensing disruptions. Distribution runs through authorized dealer networks anchored to mining district service hubs, with direct procurement relationships dominating tier-one miner contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
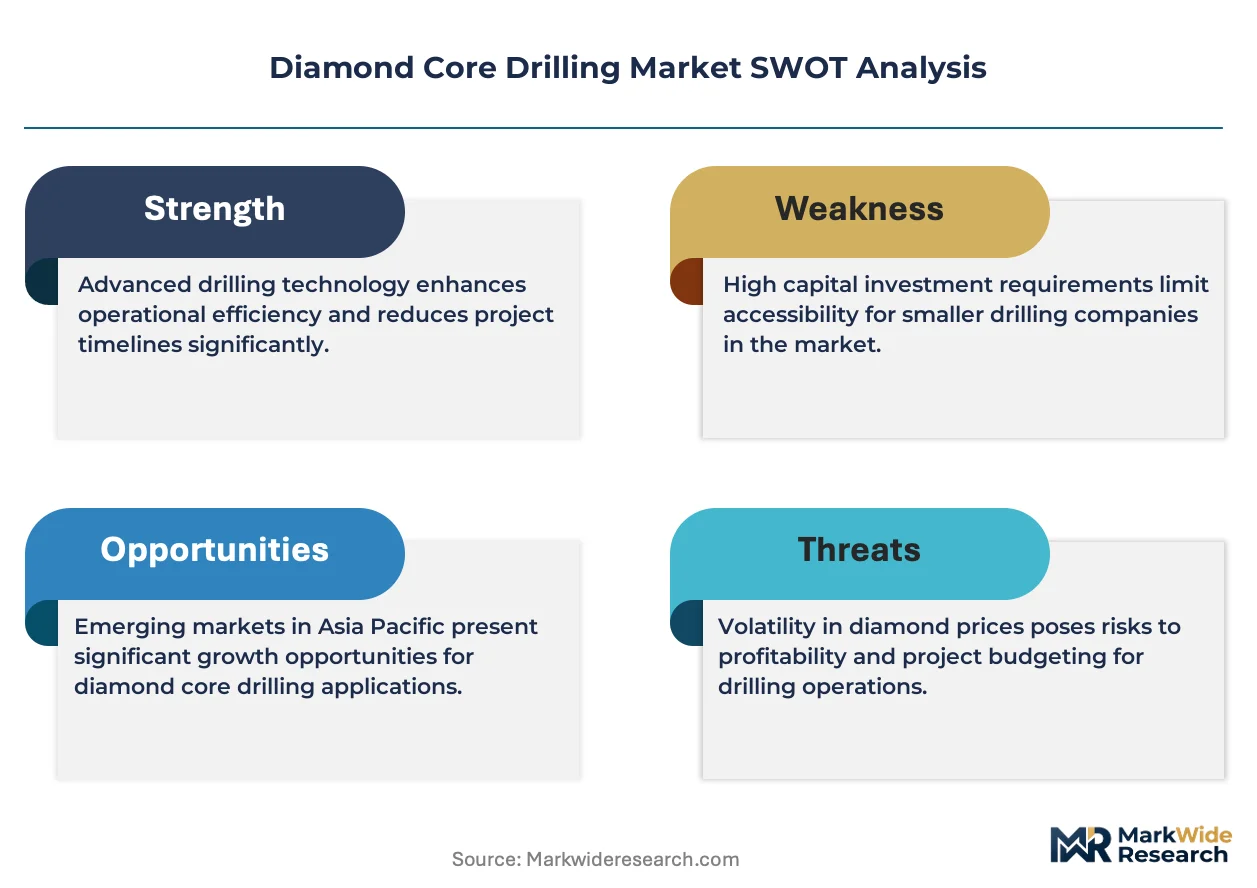
Margin expansion opportunities concentrate in automated rig integration and synthetic diamond captive supply, as labor cost pressures and REACH compliance expenses simultaneously compress competitor economics and reward scale.
For Market Incumbents: Anchor market position through backward integration into synthetic diamond synthesis or long-term offtake agreements with HPHT producers, defending against pure-play consumable suppliers gaining technical field support capabilities. Prioritize certification investment in ISO 18758-1 testing protocols to extend compliance moats against delayed-entrant competitors. Channel control through authorized dealer networks in Chilean and Indonesian mining districts preserves pricing power as resource nationalism fragments direct vendor relationships. For New Entrants and Emerging Players: OSHA's reduced silica permissible exposure limits in the United States open a window for wet-system retrofit specialists and vacuum-assisted dust capture technology providers serving Southwestern surface operations. Target urban geotechnical investigation in Dubai and Singapore where municipal discharge restrictions block wet alternatives and incumbent presence remains limited. A go-to-market angle anchored to rapid-deployment dry core systems with localized technical support bypasses capital-intensive rig manufacturing barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where materials science capabilities intersect with regulatory compliance infrastructure, particularly among impregnated bit producers struggling with cobalt-tungsten carbide reformulation costs. Acquisition targets with captive synthetic diamond supply or established ISO 18758-1 certification pathways offer defensive positioning through supply security and export market access. The signal to watch is tier-one miner unbundling velocity—accelerated separation of rig procurement from operational services indicates pure-play consumable supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Synthesis | Captive HPHT production secures bit quality and insulates margin from crystal supply volatility in concentrated producer markets. |
| Automated Rig Telemetry Integration | Real-time vibration monitoring reduces unplanned downtime and opens contracts with safety-conscious Australian and Canadian miners. |
| Local Assembly Partnership in Indonesia | Domestic content compliance satisfies Ministry of Energy and Mineral Resources requirements for Grasberg and Batu Hijau suppliers. |
| Cobalt-Free Matrix Chemistry Development | Nickel-iron binder reformulation maintains EU market access under REACH restrictions while redirecting legacy inventory to less stringent jurisdictions. |
| Dry System Vacuum Dust Capture Expansion | Singapore and Dubai municipal discharge limits accelerate penetration in high-rise geotechnical investigation with rapid bit change mechanisms. |
Methodological Framework
Multiple input streams — structured interviews with drilling contractors and mining house engineering directors, technical discussions with bit matrix R&D leads, and validation against aftermarket service heads — were reconciled with secondary data from customs trade records, SEC filings of listed mining equipment suppliers, and ISO certification registries. Bottom-up rig hour estimates across Chilean, Australian, Canadian, Indonesian, and US mining districts were cross-checked against top-down exploration budget allocations reported by major mining houses. Primary fieldwork concentrated on wireline-capable rig deployments and consumable procurement patterns in deep porphyry copper-gold targets.
Historical rig utilization trends were cross-referenced against panel input from fleet managers and site supervisors to calibrate penetration assumptions for automated and directional drilling technologies across the projection horizon. Segmentation modeling captured product type splits between wet and dry core bits, application tiers across mining and construction, technology gradients from conventional to automated systems, and end-user distinctions between contractors and mining companies. CAGRs were derived from equipment replacement cycles, exploration budget elasticity to metal prices, and regulatory compliance retrofit timelines. Industry-specific forecast inputs included synthetic diamond supply capacity expansion, silica exposure limit enforcement trajectories, and resource nationalism policy implementation rates.
Revisions become necessary when synthetic diamond supply disruptions, accelerated REACH enforcement, or abrupt shifts in copper-gold exploration economics materialize beyond modeled scenarios. Forecasts reflect assumptions regarding water access constraints in Chile's Atacama, skilled driller availability in Canadian Arctic operations, and Indonesian domestic content phase-in schedules. A model refresh is warranted upon material change in tier-one miner procurement unbundling velocity or OSHA silica enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
China Power Tools Market
Tools
Lathe Machines Market
Tools
Garden Digging Tools Market
Tools
Workholding Tools Market
Tools
Handheld Blower Market
Tools
Measuring Wheels Market
Tools
Brazing Torch Market
Tools
Tile Saw Market
Tools
Saw Blades Market
Tools
Global Tools Storage Products Market
Tools
Drill Set Market
Tools
MIG Guns Market
Tools
Global Flange Fasteners Market
Tools
Portable Rolling Toolbox Market
Tools
Machining Centers Market
Tools
Orbital Recip Saw Market