
 Fatigue Testing Machine Market | 2026-2036
Fatigue Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fatigue Testing Machine Market Analysis
Preventive maintenance and calibration subscription services is consolidating around equipment fleets in high-utilization testing environments. MTS Systems Corporation leverages its servo-hydraulic installed base to anchor long-term service contracts across North American aerospace labs. ZwickRoell GmbH & Co. KG sustains competitive positioning through German-engineered precision and direct channel control in European automotive certification. Instron (Illinois Tool Works) dominates electromechanical segments with extensive field service networks that reduce customer downtime.
A fatigue testing machine applies cyclic loading to materials and components to characterize failure thresholds under repeated stress, typically operating at frequencies from 0.01 Hz to 100 Hz with load capacities spanning 1 kN to 5,000 kN depending on frame architecture. These systems validate structural integrity for safety-critical applications where fracture mechanics data determines component lifecycle ratings. Servo-hydraulic systems command premium positioning in aerospace and rail applications where multi-axial load simulation addresses complex stress states. Electromechanical platforms occupy expanding share in consumer electronics and academic settings where lower force ranges and cleaner operation align with benchtop workflows. Research institutions represent a concentrated margin pool as grant-funded installations prioritize precision and software flexibility over capital cost minimization.
FAA airworthiness directives and EU Machinery Directive compliance requirements shape equipment specifications for structural validation in commercial aviation and rail transport. ISO 1099 and ASTM E466 define standardized test protocols that manufacturers must embed in control software to maintain cross-border market access. Japan's METI industrial standards and Germany's KBA type-approval processes add national layers that influence regional product configurations. Stakeholders must monitor evolving battery-electric vehicle platform requirements where chassis fatigue validation protocols are diverging from internal combustion architectures.
Market Dynamics
Composite airframe certification requirements from the FAA and EU Machinery Directive are forcing aerospace manufacturers to expand multi-axial fatigue testing programs, restructuring equipment procurement priorities toward servo-hydraulic platforms capable of simulating complex stress states.
Growth Catalysts
- EU Machinery Directive compliance mandates:Tightened validation protocols for structural components in commercial aviation and rail transport are mandating upgraded testing infrastructure across European certification labs.
- Japan's METI industrial standards:National type-approval processes for automotive and rail components are driving precision equipment upgrades in Japanese engineering clusters.
- Battery-electric vehicle chassis validation:Diverging fatigue protocols for electric platforms versus internal combustion architectures are creating new testing demand from automotive OEMs.
Market Restraints
- High-purity hydraulic fluid costs:Servo-hydraulic system operation depends on specialized fluid formulations with volatile petrochemical input pricing.
- German precision component concentration:Critical load cell and sensor supply chains cluster in southern German manufacturing regions, creating geographic vulnerability.
- Electromechanical force range limitations:Benchtop electromechanical platforms cannot replicate the multi-axial stress states required for aerospace certification.
Strategic Opportunities
- Indian automotive testing expansion:Domestic OEMs establishing local certification facilities present untapped demand for mid-range electromechanical systems.
- Digital twin integration:Convergence of physical testing hardware with real-time simulation software is enabling predictive maintenance service models.
- Subscription calibration services:High-utilization aerospace labs are unbundling maintenance contracts from capital purchases, creating recurring revenue streams.
Industry Challenges
- Multi-physics simulation expertise shortage:Integration of thermal, mechanical, and electrical loading protocols requires specialized firmware engineering talent that remains scarce.
- ISO 1099 certification timelines:Cross-border market access depends on embedded control software validation that extends product development cycles.
- Legacy electromechanical fleet compatibility:Retrofitting existing Instron and ZwickRoell installations with modern data acquisition modules creates integration friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatigue Testing Machine Market |
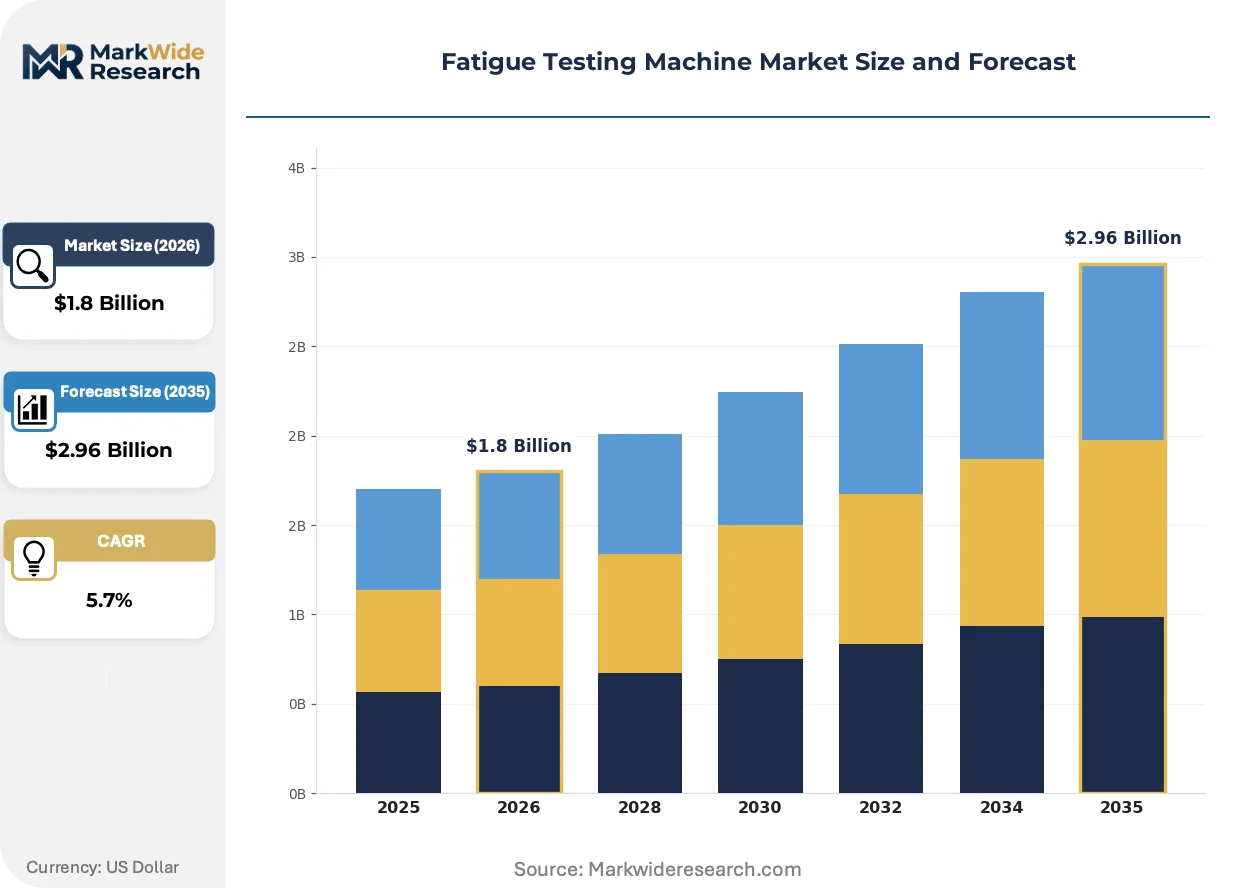
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Servo-hydraulic Application: Aerospace, Automotive, Rail, Consumer Electronics End User: Manufacturers, Research Institutions, Quality Control Labs, Academic Institutions Technology: Static, Dynamic, Cyclic, Multi-Axial |
| Companies Covered | Shimadzu Corporation, Tinius Olsen Testing Machine Company, MTS Systems Corporation, Nidec-SHIMPO, ADMET Inc., Instron (Illinois Tool Works), TA Instruments, Magtrol, ZwickRoell GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatigue Testing Machine Market Emerging Trajectories
Digital instrumentation and cloud-connected diagnostics are compressing equipment commissioning timelines while enabling remote monitoring of distributed testing fleets across multi-site aerospace programs.
Multi-axial load simulation technology is expanding into commercial aviation certification workflows. Boeing and Airbus tier-one suppliers are adopting six-degree-of-freedom servo-hydraulic rigs to replicate combined bending-torsion-pressure loading. This capability is expanding into smaller airframe component manufacturers who previously relied on uniaxial testing.
REACH substance restrictions on hydraulic fluid formulations are forcing equipment manufacturers to qualify bio-based alternatives. The EU Green Deal's industrial emissions targets are pressuring testing labs to eliminate petroleum-derived fluids from their operations. German KBA type-approval bodies are prioritizing equipment vendors with certified sustainable fluid compatibility.
Research institutions are consolidating procurement through shared national facility networks. Grant-funded universities in the United States are pooling capital budgets through NSF-backed regional testing centers rather than acquiring individual benchtop units. This concentration is visible across Massachusetts and California engineering clusters where centralized high-capacity systems serve multiple principal investigators.
Fatigue Testing Machine Market Segmentation
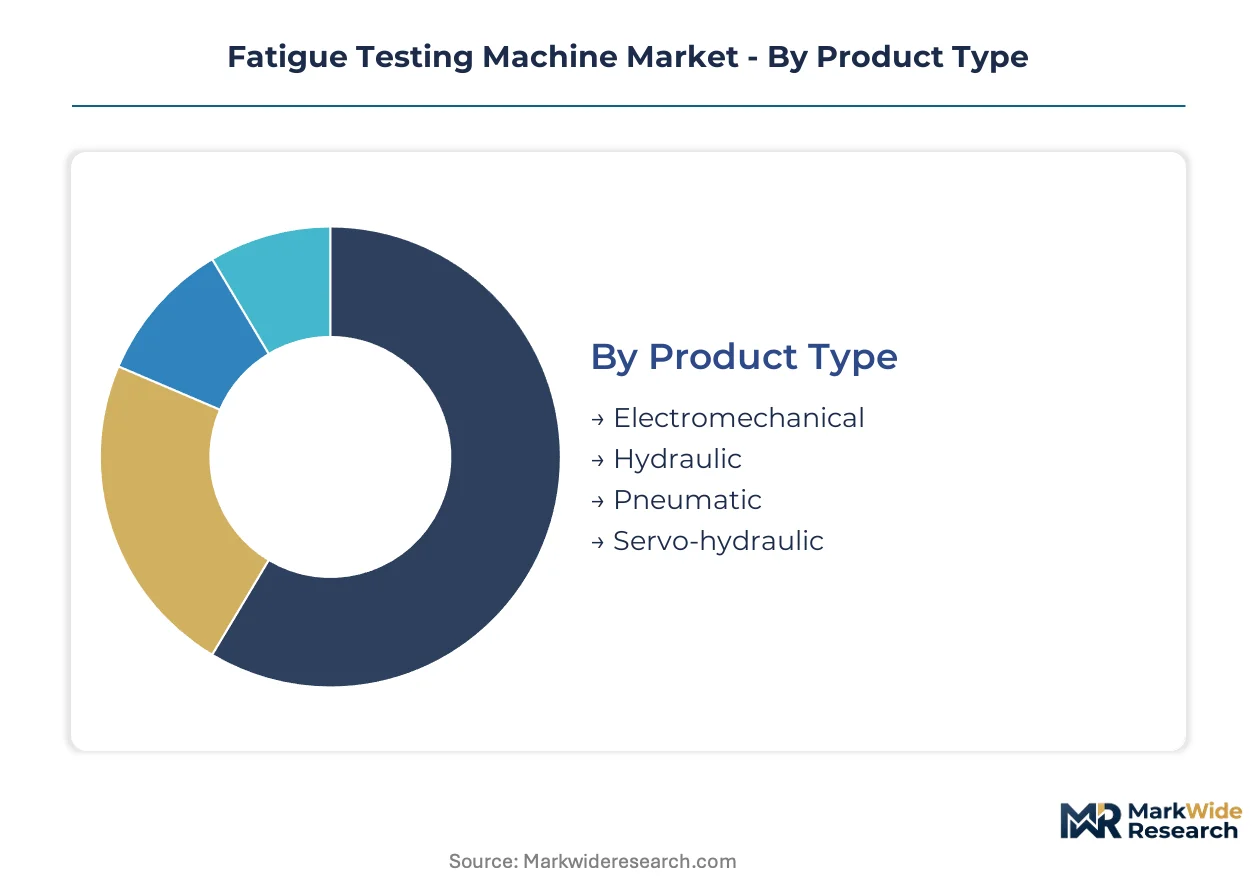
Fatigue testing equipment selection hinges on load capacity requirements, frequency ranges, and certification complexity. Buyers in aerospace and rail prioritize multi-axial servo-hydraulic systems for FAA and EU Machinery Directive compliance, while automotive and electronics sectors balance capital constraints against throughput needs.
Product Type:
Capital intensity and operational precision separate procurement patterns across equipment categories.
- Servo-hydraulic:Delivers force capacities exceeding 2,500 kN with closed-loop control for multi-frequency waveform replication. Boeing and Airbus tier-one suppliers in Germany and the United States anchor procurement for composite airframe certification programs.
- Electromechanical:Employs ball-screw or linear motor actuation for clean, low-noise operation below 100 kN. Japanese automotive OEMs and U.S. consumer electronics manufacturers favor these systems for benchtop quality assurance workflows.
- Hydraulic:Open-loop hydraulic actuation serves high-force applications where precision feedback adds unnecessary cost. Found in Indian and Brazilian metal foundries for basic structural component validation.
- Pneumatic:Compressed air systems address low-force, high-frequency cycling needs below 10 kN. Packaging and textile manufacturers in Italy and Vietnam deploy these for material flex testing.
Volume sits with electromechanical platforms; growth tilts toward servo-hydraulic systems.
Application:
Regulatory stringency and failure consequence severity dictate equipment specification tiers.
- Aerospace:FAA airworthiness directives and EASA certification protocols mandate multi-axial load simulation for wing spars, fuselage sections, and landing gear assemblies. German KBA and U.S. FAA validation requirements force equipment upgrades across European and North American testing labs.
- Automotive:Chassis, suspension, and powertrain components require fatigue validation under ISO 1099 protocols. Battery-electric vehicle platforms in Japan and South Korea are diverging test specifications from internal combustion architectures.
- Rail:EN 12663 and UIC standards govern bogie frame and wheelset testing. French SNCF and German Deutsche Bahn procurement specifications drive demand for high-capacity servo-hydraulic rigs.
- Consumer Electronics:Hinge, connector, and flex-cable cycling demands high-frequency, low-force platforms. Shenzhen and Taipei manufacturing clusters prioritize compact electromechanical systems with rapid changeover capability.
Revenue concentrates in aerospace certification; expansion is accelerating fastest in automotive electrification testing.
End User:
Funding mechanisms and utilization rates create divergent purchasing behaviors across customer types.
- Manufacturers:OEMs and tier suppliers operate high-utilization testing fleets requiring 24/7 availability. Japanese automotive and U.S. aerospace producers favor comprehensive service contracts over transactional maintenance.
- Research Institutions:Grant-funded universities prioritize software flexibility and precision over capital efficiency. NSF-backed regional centers in Massachusetts and California consolidate procurement through shared facility networks.
- Quality Control Labs:Third-party certification bodies serve multiple industry clients with standardized test protocols. German TÜV and U.S. UL facilities require embedded ISO 1099 and ASTM E466 compliance in control software.
- Academic Institutions:Undergraduate engineering programs balance pedagogical needs against limited capital budgets. Indian Institute of Technology campuses and Brazilian federal universities represent emerging demand for entry-level electromechanical systems.
Installed base dominance rests with manufacturers; research institutions command premium pricing tolerance.
Technology:
Load complexity and simulation fidelity define competitive positioning across technical approaches.
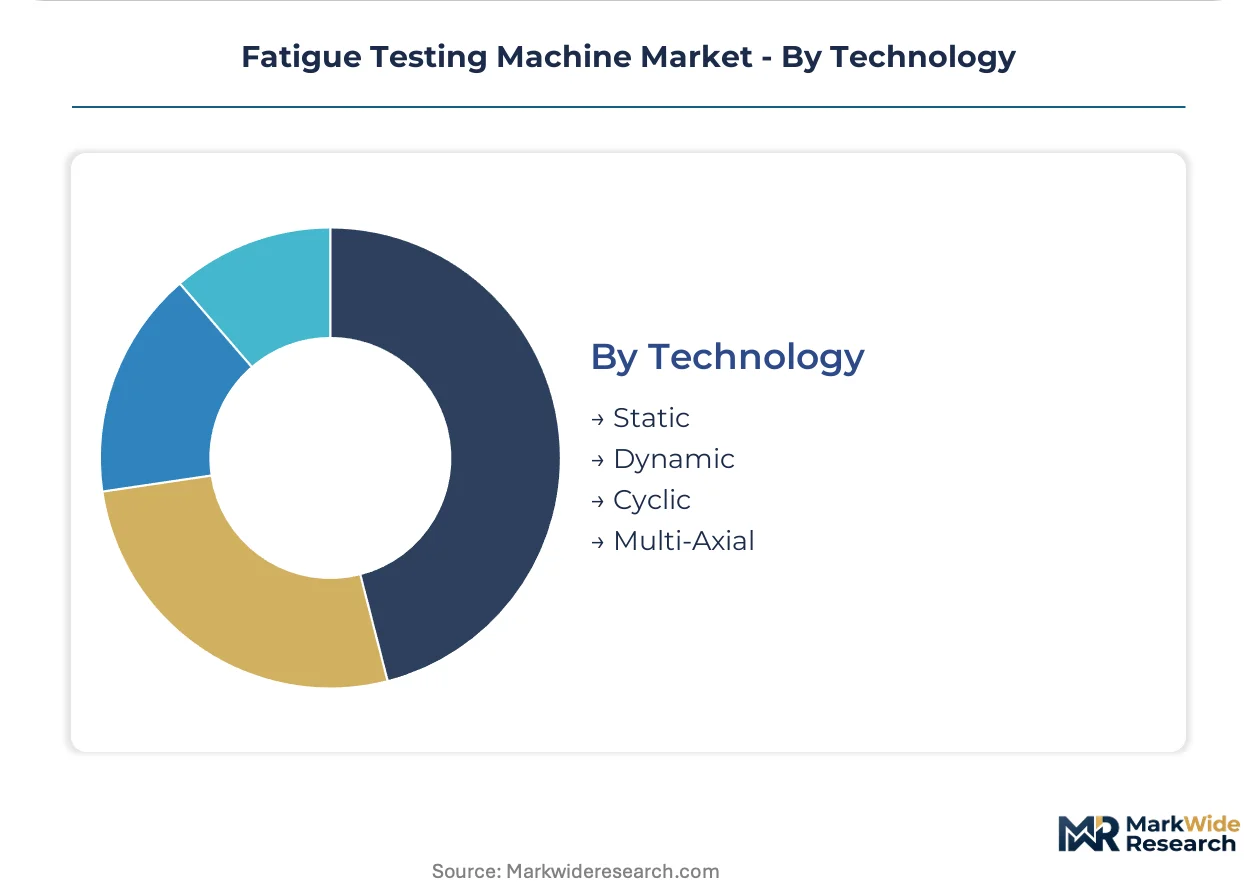
- Multi-Axial:Simultaneous application of tension, compression, torsion, and bending loads through six-degree-of-freedom actuation. Airbus A350 and Boeing 787 certification programs in France and the United States require these capabilities for composite structure validation.
- Dynamic:Real-time adaptive control adjusts loading profiles based on specimen response. German automotive OEMs employ these systems for road-load data replication in durability testing.
- Cyclic:Repetitive sinusoidal or haversine waveform application at fixed frequencies. Standard configuration for ISO 1099 compliance across European rail and automotive certification.
- Static:Monotonic load application to failure for baseline material characterization. Foundational capability in academic materials science curricula worldwide.
Multi-axial systems capture the steepest expansion trajectory; cyclic platforms retain the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision engineering clusters across Germany, Japan, and the United States, while consumption spreads through aerospace certification hubs and automotive testing centers in these same markets. The mismatch between concentrated supply and distributed demand shapes procurement logistics and service contract structures.
United States
FAA airworthiness directives drive multi-axial fatigue testing demand from Boeing and Airbus tier-one suppliers. The FAA mandates upgraded validation protocols for composite airframe certification. Massachusetts and California engineering clusters host NSF-backed regional testing centers that consolidate grant-funded university procurement.
Germany
KBA type-approval processes and EU Machinery Directive compliance force automotive and rail component manufacturers to maintain high-capacity servo-hydraulic rigs. REACH substance restrictions on hydraulic fluids pressure labs to adopt bio-based alternatives. Bavaria and Baden-Württemberg precision manufacturing regions anchor load cell and sensor supply chains.
Japan
METI industrial standards govern automotive and rail component type-approval, requiring precision equipment upgrades across domestic engineering clusters. Battery-electric vehicle platform divergence from internal combustion architectures creates new chassis validation protocols. Toyota and Honda supplier networks in Aichi and Kanagawa prefectures drive electromechanical system demand.
India
Domestic automotive OEMs establishing local certification facilities generate untapped demand for mid-range electromechanical fatigue testing systems. The BIS national standards body aligns with ISO 1099 protocols for cross-border market access. Indian Institute of Technology campuses in Maharashtra and Tamil Nadu represent emerging demand for entry-level academic systems.
France
EASA certification requirements and SNCF procurement specifications drive demand for high-capacity servo-hydraulic rigs in rail and aerospace applications. The EU Green Deal's industrial emissions targets pressure testing labs to eliminate petroleum-derived hydraulic fluids. Île-de-France and Auvergne-Rhône-Alpes regions host Airbus supply chain testing facilities.
Fatigue Testing Machine Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fatigue testing machine market. Equipment manufacturers with captive servo-hydraulic actuator production maintain cost advantages against assembly-focused competitors. The market structure separates into three archetypes: integrated precision engineering houses, electromechanical specialists, and regional system integrators. Consolidation pressure favors M&A activity among mid-tier automation suppliers, while technology licensing agreements spread multi-axial control software capabilities.
Among German-engineered precision houses, ZwickRoell GmbH & Co. KG occupies a position exemplifying direct channel control in European automotive certification. MTS Systems Corporation represents the integrated servo-hydraulic archetype with extensive North American aerospace lab presence. Instron, operating within Illinois Tool Works, anchors the electromechanical segment through field service network scale. These three entities collectively illustrate the geographic and technological segmentation governing competitive positioning.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Tinius Olsen Testing Machine Company |
| MTS Systems Corporation |
| Nidec-SHIMPO |
| ADMET Inc. |
| Instron (Illinois Tool Works) |
| TA Instruments |
| Magtrol |
| ZwickRoell GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions on hydraulic fluid formulations gate both qualified supply and premium-tier pricing access, forcing equipment manufacturers to qualify bio-based alternatives while labs absorbing compliance costs face margin compression that feeds back into supplier selection criteria favoring vendors with certified sustainable fluid compatibility.
Pricing Analysis
Cost-down pressure on mid-range electromechanical systems accelerates because Indian domestic OEMs establishing local certification facilities prioritize capital efficiency over precision specifications. Three-tier pricing structure across premium, standard, and economy levels separates servo-hydraulic aerospace platforms from automotive-grade electromechanical units from entry-level academic benchtop systems. Price differentiation hinges on ISO 1099 embedded software certification and multi-axial load simulation capability. Research institutions demonstrate lowest price sensitivity due to grant-funded procurement prioritizing precision over capital cost minimization.
Supply Chain Analysis
EU Green Deal industrial emissions certification gates supplier qualification for European testing labs seeking bio-based hydraulic fluid compatibility. Critical load cell and sensor production clusters in Germany, Japan, and the United States anchor component supply. Manufacturing draws from high-purity hydraulic fluid formulations, precision-machined actuator housings, and closed-loop control electronics. Single-source vulnerability concentrates in southern German sensor manufacturing regions. Distribution runs through direct channel relationships with aerospace certification labs and automotive OEM procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive servo-hydraulic actuator production determines cost positioning against assembly-focused competitors.
For Market Incumbents: Lock in long-term service contract anchoring across North American aerospace labs to defend against emerging digital-twin platform entrants. Deepen backward integration into precision load cell manufacturing to reduce exposure to German supply chain concentration. Prioritize firmware engineering talent acquisition to address multi-physics simulation expertise scarcity threatening product development timelines. For New Entrants and Emerging Players: Cloud-connected diagnostics platforms offer the most penetrable entry vector for mid-tier automation suppliers seeking to unbundle maintenance from capital purchases. Target Indian automotive testing expansion where domestic OEM certification facility buildouts generate demand for mid-range electromechanical systems without incumbent service contract lock-in. Pursue technology licensing agreements for multi-axial control software capabilities rather than proprietary development. For Investors and Strategic Acquirers: Consolidation of U.S. university procurement through NSF-backed regional testing centers is the leading indicator that grant-funded installation concentration will favor equipment vendors with software flexibility and shared-facility service models. Five-to-ten year viability favors integrated precision engineering houses with captive actuator production over asset-light designers. Watch for battery-electric vehicle platform divergence from internal combustion architectures as inflection signal for chassis validation protocol disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Actuator Manufacturing | Captive servo-hydraulic production secures cost advantages against assembly-focused competitors in aerospace certification. |
| Digital Twin Platform Integration | Convergence with real-time simulation software enables predictive maintenance subscription models for high-utilization labs. |
| Bio-based Hydraulic Fluid Qualification | REACH-compliant fluid compatibility gates European market access under EU Green Deal industrial emissions targets. |
| Multi-axial Control Software Licensing | Technology agreements spread six-degree-of-freedom capabilities to smaller airframe component manufacturers. |
| Regional Testing Center Partnership | NSF-backed facility networks in Massachusetts and California consolidate grant-funded university procurement concentration. |
Methodological Framework
SEC filings, FAA airworthiness directive databases, and EU Machinery Directive compliance registries formed the secondary backbone, cross-referenced with primary interviews involving aerospace certification lab directors, automotive OEM test engineers, servo-hydraulic equipment procurement managers, and university materials science department heads. Bottom-up equipment shipment analysis triangulated against top-down aerospace and automotive capital expenditure patterns.
Historical trendline analysis of servo-hydraulic and electromechanical platform shipments informed base-year calibration across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application sector, end-user funding mechanism, and load simulation technology complexity. CAGRs derived from regression analysis of equipment replacement cycles and regulatory-mandated upgrade timelines incorporated battery-electric vehicle platform divergence and composite airframe certification expansion as industry-specific demand drivers.
The model holds under stable FAA and EASA regulatory frameworks; deviation in EU Machinery Directive enforcement intensity or REACH substance restriction scope would shift equipment procurement priority rankings. Forecasts reflect assumptions regarding grant funding continuity for research institution installations and aerospace production ramp schedules. A model refresh is warranted upon material change in battery-electric vehicle chassis validation protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Masonry Cleaners Market
Tools
Floor Saw Market
Tools
Digital Laser Levels Market
Tools
Global Electric Portable Drill Market
Tools
Portable Grinders Market
Tools
Industrial Ladder Market
Tools
Machine Bench Vices Market
Tools
Portable Rolling Toolbox Market
Tools
Wood Floor Grinding Machine Market
Tools
Spindle Shaper Market
Tools
Sand Control Tools Market
Tools
Cordless Impact Wrench Market
Tools
Press Machine Market
Tools
Ripper Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Edge Banders Market