
 Used Machine Tools Market | 2026-2036
Used Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Used Machine Tools Market Insights
A capital-intensity divergence between full-service rebuilders and asset brokers is redrawing competitive boundaries in used machine tools. DMG Mori leverages factory-certified refurbishment programs to sustain premium pricing on second-life vertical machining centers. Mazak Corporation anchors its used equipment channel through direct factory buyback schemes that control resale quality. Haas Automation competes on volume throughput, operating high-velocity remarketing of trade-in lathes through its North American dealer network.
Used machine tools comprise previously operated metal-cutting and metal-forming equipment, typically encompassing lathes with swing capacities from 12 to 60 inches, milling machines with XYZ travels exceeding 40 inches, and grinding machines holding tolerances within 0.0002 inches, all restored to production-ready condition for subtractive manufacturing operations. CNC technology commands the deepest resale value pools due to controller upgradeability and programmable repeatability, while manual equipment occupies shrinking but persistent demand among custom fabricators and maintenance shops where job complexity does not justify automation investment. Metal fabrication and automotive component manufacturing represent the most liquid application segments, with aerospace part production generating narrower but higher-margin refurbishment opportunities due to traceability and certification requirements.
The US Environmental Protection Agency enforces Clean Air Act standards that affect coolant disposal and surface coating emissions from machine tool rebuilding operations, while OSHA mandates lockout/tagout protocols that reshape reconditioning workflows. Germany's Federal Institute for Occupational Safety and Health (BAuA) and Japan's Ministry of Economy, Trade and Industry (METI) both maintain equipment safety certification frameworks that buyers treat as de facto market access filters. Stakeholders must monitor how evolving carbon border adjustments and extended producer responsibility schemes alter the economics of cross-border used equipment trade versus domestic refurbishment.
Market Dynamics
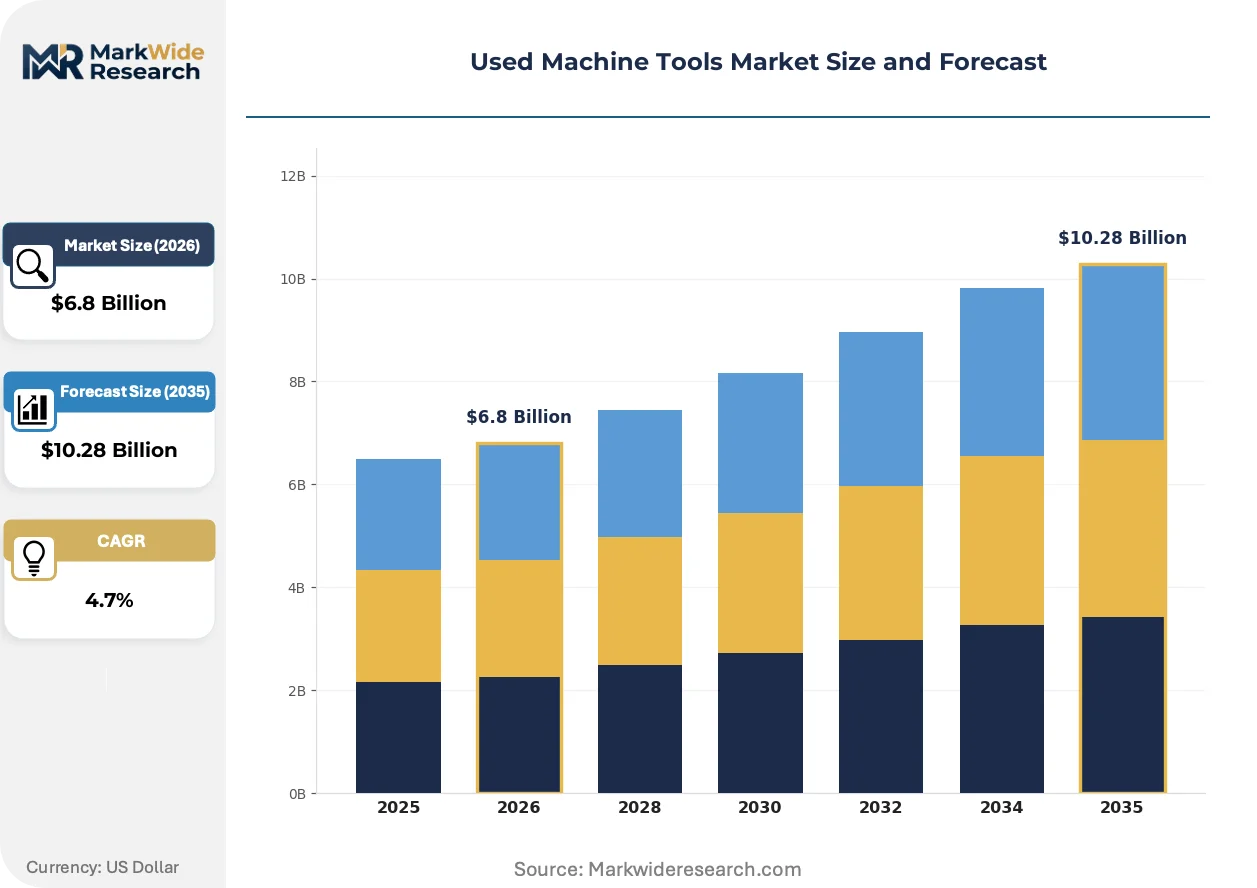
Capital efficiency pressures are compressing replacement cycles for subtractive manufacturing equipment, with tier-1 automotive suppliers now sourcing factory-refurbished CNC assets to preserve liquidity while maintaining tolerance specifications. This structural shift is redrawing competitive boundaries between full-service rebuilders and high-velocity asset brokers.
Growth Catalysts
- Germany's BImSchG Energy Audit Mandate:Industrial buyers face documented power profile requirements that favor verified pre-owned machines with traceable energy consumption histories over uncertified new alternatives.
- Yangtze River Delta Precision Engineering Cluster:Chinese manufacturers source late-model used lathes and grinding centers to bridge capacity gaps without triggering capital expenditure approval thresholds.
- CNC Controller Upgradeability:Programmable repeatability and retrofit-compatible control architectures sustain deeper resale value pools compared to fixed-automation alternatives.
Market Restraints
- Coolant Disposal Compliance Burden:US EPA Clean Air Act standards impose surface coating emission controls and hazardous waste protocols that inflate reconditioning facility operating costs.
- Certification Timeline Friction:Japan's METI equipment safety frameworks and Germany's BAuA certification requirements create multi-month approval windows that delay revenue recognition for cross-border transactions.
- Manual Equipment Demand Contraction:Custom fabricators and maintenance shops represent shrinking addressable market segments as job complexity thresholds increasingly justify automation investment.
Strategic Opportunities
- Aerospace Traceability Requirements:Narrow but high-margin refurbishment pools exist for used machine tools supporting AS9100-certified part production with full documentation chains.
- Extended Producer Responsibility Schemes:Evolving carbon border adjustments in the European Union may alter economics to favor domestic refurbishment over transoceanic used equipment trade.
- Direct Factory Buyback Channels:OEM-controlled resale quality programs create premium positioning opportunities distinct from independent dealer networks.
Industry Challenges
- Rebuild Technician Skill Scarcity:Specialized competencies in spindle remanufacturing and geometric accuracy restoration are concentrating among aging workforce cohorts with limited apprenticeship pipeline replenishment.
- Legacy Control Integration Complexity:Retrofitting pre-2000 machine architectures with modern servo systems requires proprietary interface development that fragments standardization efforts.
- Cross-Border Documentation Gaps:Inconsistent maintenance record standards between source and destination jurisdictions complicate warranty underwriting and buyer risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Machine Tools Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathes, Milling Machines, Drilling Machines, Grinding Machines, Boring Machines, Shaping Machines Technology: CNC, Hydraulic, Mechanical, Pneumatic, Electric Servo, Manual Application: Metal Fabrication, Automotive Component Manufacturing, Aerospace Part Production, Shipbuilding, Tool & Die Making, Electronics Assembly End User Industry: Small-Scale Workshops, Tier-1 Suppliers, Heavy Machinery Assemblers, Precision Engineering Firms, Maintenance Service Providers, Custom Fabricators |
| Companies Covered | DMG Mori, Mazak Corporation, Haas Automation, Okuma Corporation, Makino Inc., TRUMPF Inc., DN Solutions, JTEKT Corporation, HYUNDAI WIA CORP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Machine Tools Market Trends and Innovations
Digital thread technologies are penetrating refurbishment workflows, enabling predictive maintenance handoffs from first to second equipment life. This convergence is compressing information asymmetries between sellers and buyers while elevating quality verification standards.
Retrofit control packages incorporating edge computing architectures are miniaturizing footprint requirements for legacy machine tool frames. Tier-2 automotive stampers adopt these systems aggressively to avoid greenfield facility investments. The technology is miniaturizing the capital commitment threshold for precision machining capability deployment.
EU CSRD disclosure requirements now capture Scope 3 emissions from capital equipment procurement, extending carbon accounting to used machine tool sourcing decisions. Industrial buyers in Germany and France must document embodied carbon in second-life assets. Metal-cutting equipment categories face the steepest compliance documentation burdens.
Outcome-based utilization contracts are displacing traditional ownership transfers in North American dealer channels. Job shops in Michigan and Ohio now lease refurbished vertical machining centers with bundled maintenance and productivity guarantees. This model concentrates most visibly among high-mix, low-volume contract manufacturers serving defense and medical device end-uses.
Used Machine Tools Market Segmentation
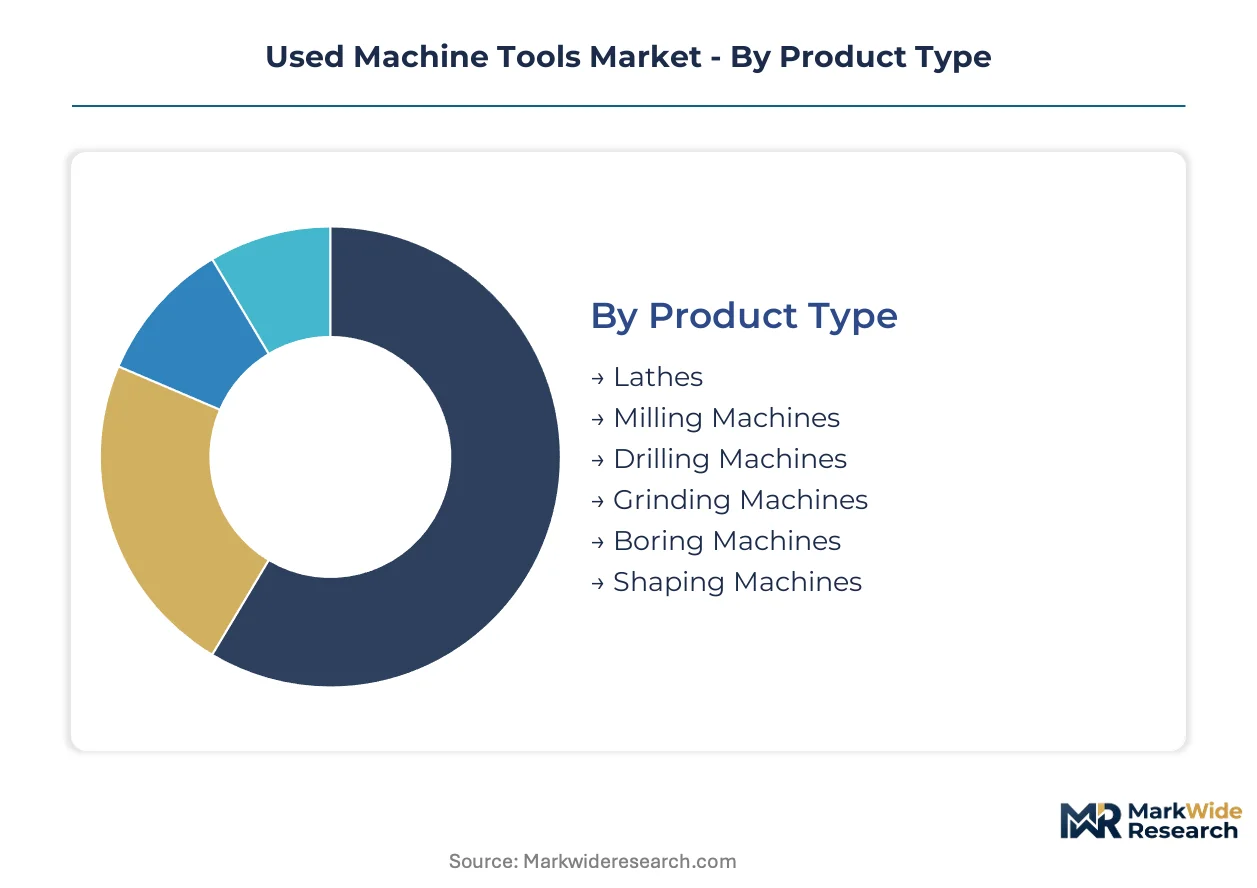
Segmentation in used machine tools reveals divergent sourcing patterns between domestic refurbishment channels and cross-border equipment flows. Understanding these splits enables suppliers to align inventory positioning with regional regulatory requirements and buyer capital constraints.
Product Type:
Domestic trade concentrates in large-swing lathes and bed-type milling machines where transport economics favor local sourcing. Export-led segments center on compact CNC machining centers and precision grinding equipment where containerization costs represent smaller share of asset value.
- Lathes:Swing capacities from 12 to 60 inches dominate secondary market liquidity. German precision engineering firms source late-model slant-bed configurations from domestic rebuilders to satisfy BImSchG energy audit documentation requirements.
- Milling Machines:Vertical machining centers with XYZ travels exceeding 40 inches retain deepest resale value pools due to controller upgradeability. China's Yangtze River Delta manufacturers import refurbished bed mills from Japan and Taiwan to bridge capacity gaps without triggering capital expenditure thresholds.
- Drilling Machines:Radial and multi-spindle configurations serve maintenance shops and small-scale fabricators with lower automation requirements.
- Grinding Machines:Cylindrical and surface grinders holding tolerances within 0.0002 inches command aerospace-certified refurbishment premiums.
- Boring Machines:Horizontal boring mills with 4-inch-plus spindle bores address heavy machinery assemblers in shipbuilding and energy equipment sectors.
- Shaping Machines:Niche demand persists among custom gear manufacturers and legacy equipment maintenance operations.
Lathes command the established base. The steepest expansion runs through milling machines.
Technology:
Cost tier stratification separates premium CNC retrofit programs from economy manual equipment channels. Controller architecture determines refurbishment complexity and margin structure across technology categories.
- CNC:Programmable repeatability and servo retrofit compatibility sustain premium pricing. Tier-1 automotive suppliers in Michigan and Ohio lease refurbished units with bundled productivity guarantees under outcome-based utilization contracts.
- Hydraulic:Power unit rebuilds and seal replacement cycles define secondary market viability. Metal fabricators in India's Pune-Ahmedabad corridor source reconditioned hydraulic presses for stamping operations with predictable duty cycles.
- Mechanical:Gear-driven spindles and manual feed mechanisms occupy shrinking but persistent demand among job shops where part complexity does not justify automation investment.
- Pneumatic:Clamping and rapid traverse systems in drilling and tapping applications serve high-mix, low-volume contract manufacturers.
- Electric Servo:Direct-drive ball screw configurations enable precision positioning without hydraulic infrastructure. Japanese machine tool rebuilders specialize in servo retrofit packages for legacy frame integration.
- Manual:Custom fabricators and maintenance shops in Mexico's Querétaro aerospace cluster retain demand for manually operated engine lathes and surface grinders for prototype and repair work.
CNC technology anchors revenue concentration. Electric servo retrofits are gaining share fastest through controller miniaturization trends.
Application:
Customer type mapping shows tier-1 suppliers driving CNC demand while small workshops sustain manual equipment channels. Application mix determines certification burden and documentation requirements.
- Metal Fabrication:Plasma cutting tables, press brakes, and ironworkers constitute the most liquid secondary market segment. US job shops in Ohio and Pennsylvania source refurbished fabricating equipment through dealer networks with rapid turnaround requirements.
- Automotive Component Manufacturing:Powertrain machining and chassis component production demand AS9100-traceable refurbishment with full documentation chains. German OEMs specify factory-certified rebuild programs for stamping press and machining center procurement.
- Aerospace Part Production:Narrow but high-margin refurbishment pools require spindle remanufacturing and geometric accuracy restoration to tight tolerances.
- Shipbuilding:Large-format boring mills and gantry machining centers serve Korean and Chinese shipyards through specialized heavy equipment brokers.
- Tool & Die Making:Jig grinders and wire EDM units support mold manufacturing clusters in China's Guangdong province.
- Electronics Assembly:Precision drilling and routing equipment addresses PCB fabrication and semiconductor packaging equipment supply chains.
Metal fabrication commands the established base. Aerospace part production shows the steepest margin expansion through certification premiums.
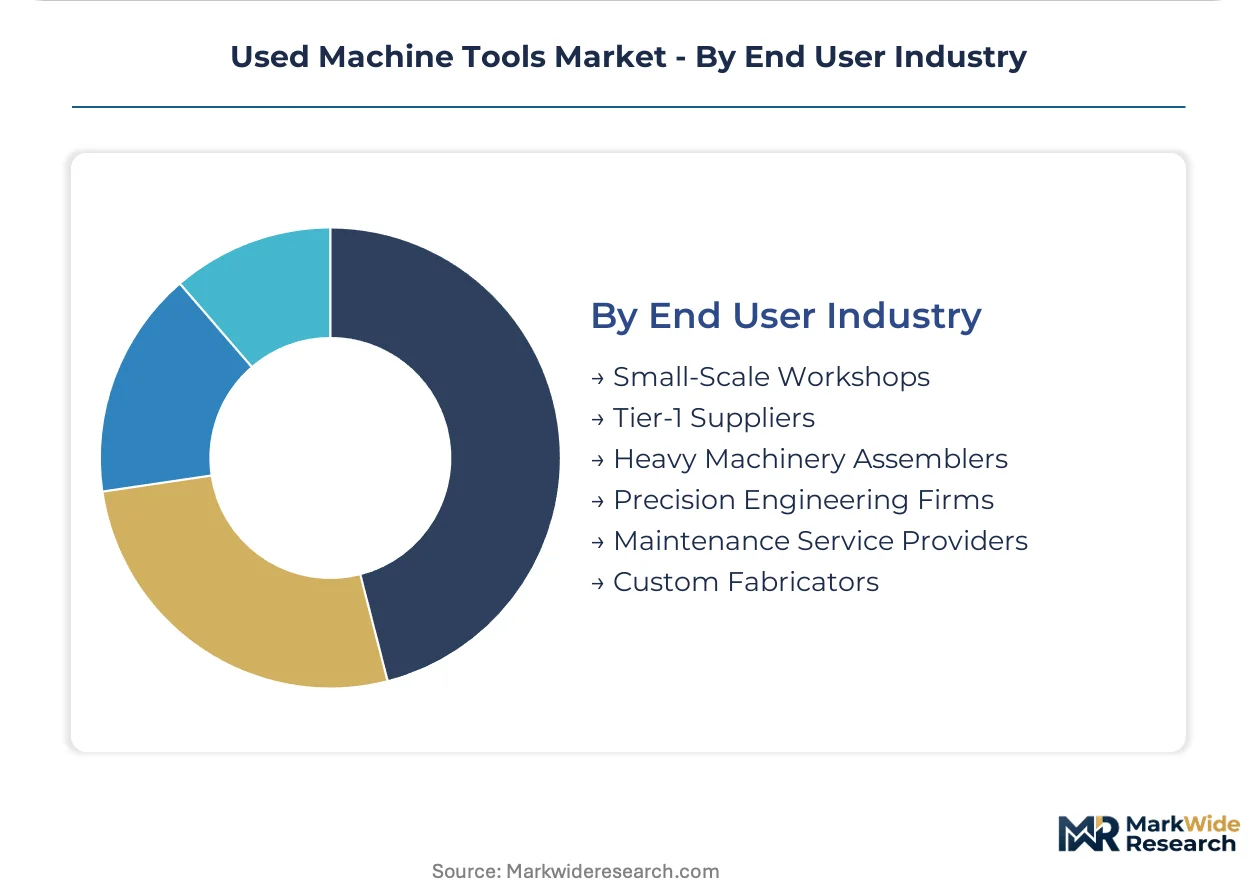
End User Industry:
Volume concentration sits with heavy machinery assemblers and tier-1 suppliers purchasing multiple units annually. Margin concentration concentrates among precision engineering firms requiring documented accuracy verification.
- Small-Scale Workshops:Single-machine purchases dominate this price-sensitive segment. Indian maintenance shops in Coimbatore and Rajkot source manually operated lathes from domestic auction houses with minimal documentation requirements.
- Tier-1 Suppliers:Capital efficiency pressures compress replacement cycles for subtractive manufacturing equipment. Automotive stampers in Mexico's Bajío region adopt retrofit control packages to avoid greenfield facility investments.
- Heavy Machinery Assemblers:Mining equipment and construction machinery manufacturers in Brazil's São Paulo state procure large-format boring mills through direct factory buyback channels.
- Precision Engineering Firms:Medical device and defense contractors in Switzerland's Jura arc demand full metrology reports and spindle vibration analysis for used equipment acceptance.
- Maintenance Service Providers:Mobile repair operations favor compact, transportable milling and drilling configurations with rapid setup capabilities.
- Custom Fabricators:Architectural metalwork and specialty vehicle builders in Italy's Emilia-Romagna region source hybrid manual-CNC equipment for prototype-to-production flexibility.
Tier-1 suppliers command the established base. Precision engineering firms deliver the steepest margin expansion through documentation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German refurbishment channels where factory-certified rebuilds command premiums, while Chinese buyers in the Yangtze River Delta exploit arbitrage on late-model Japanese and Taiwanese imports. This asymmetry shapes cross-border flow patterns and margin structures across the used machine tools trade.
Germany
Tier-1 automotive suppliers source factory-refurbished CNC assets to preserve liquidity while maintaining tolerance specifications. The Federal Emissions Control Act (BImSchG) mandates energy audits for industrial equipment, pushing buyers toward verified pre-owned machines with documented power profiles. Precision engineering firms in Baden-Württemberg and Bavaria dominate procurement of slant-bed lathes with traceable energy consumption histories.
United States
Job shops in Michigan and Ohio lease refurbished vertical machining centers under outcome-based utilization contracts with bundled maintenance guarantees. The Environmental Protection Agency enforces Clean Air Act standards affecting coolant disposal and surface coating emissions from rebuilding operations. Defense and medical device contract manufacturers in the Midwest concentrate demand for high-mix, low-volume precision machining capacity.
China
Manufacturers in the Yangtze River Delta manufacturing corridor source late-model used lathes and grinding centers to bridge capacity gaps without triggering capital expenditure approval thresholds. The Ministry of Ecology and Environment (MEE) monitors industrial energy consumption under dual carbon goals, creating documentation preferences for pre-owned equipment with verified efficiency profiles. Precision engineering clusters in Jiangsu and Zhejiang provinces drive import flows from Japan and Taiwan.
Japan
Machine tool rebuilders specialize in servo retrofit packages for legacy frame integration, exporting refurbished equipment throughout Asia. The Ministry of Economy, Trade and Industry (METI) maintains equipment safety certification frameworks that buyers treat as de facto market access filters. Nagoya-area reconditioning facilities concentrate expertise in spindle remanufacturing and geometric accuracy restoration for aerospace-certified applications.
Mexico
Automotive stampers in the Bajío region adopt retrofit control packages to avoid greenfield facility investments while serving North American OEM supply chains. The Secretariat of Economy administers equipment import regulations that favor documented refurbishment standards from certified sources. Querétaro's aerospace cluster retains demand for manually operated engine lathes and surface grinders for prototype and repair work alongside CNC capacity.
Used Machine Tools Market Competitive Landscape
Concentration sits with full-service rebuilders operating factory-certified refurbishment programs. The vendor base splits between premium-tier rebuilders commanding quality premiums and high-velocity asset brokers competing on transaction speed. Three archetypes dominate: OEM-controlled resale channels, independent dealer networks, and specialized heavy equipment brokers. Competitive moves center on direct factory buyback schemes and geographic expansion of certified refurbishment capacity.
Among Japanese-origin machine tool manufacturers, DMG Mori and Mazak Corporation exemplify the OEM-controlled resale archetype through factory buyback and certified rebuild programs. Haas Automation occupies a position within the high-velocity remarketing tier, leveraging North American dealer network density for trade-in volume throughput. Okuma Corporation and Makino Inc. represent precision-focused rebuilders concentrating on aerospace-certified refurbishment with full documentation chains.
| Leading Market Players |
|---|
| DMG Mori |
| Mazak Corporation |
| Haas Automation |
| Okuma Corporation |
| Makino Inc. |
| TRUMPF Inc. |
| DN Solutions |
| JTEKT Corporation |
| HYUNDAI WIA CORP |
| Others |
Pricing and Supply Chain Analysis
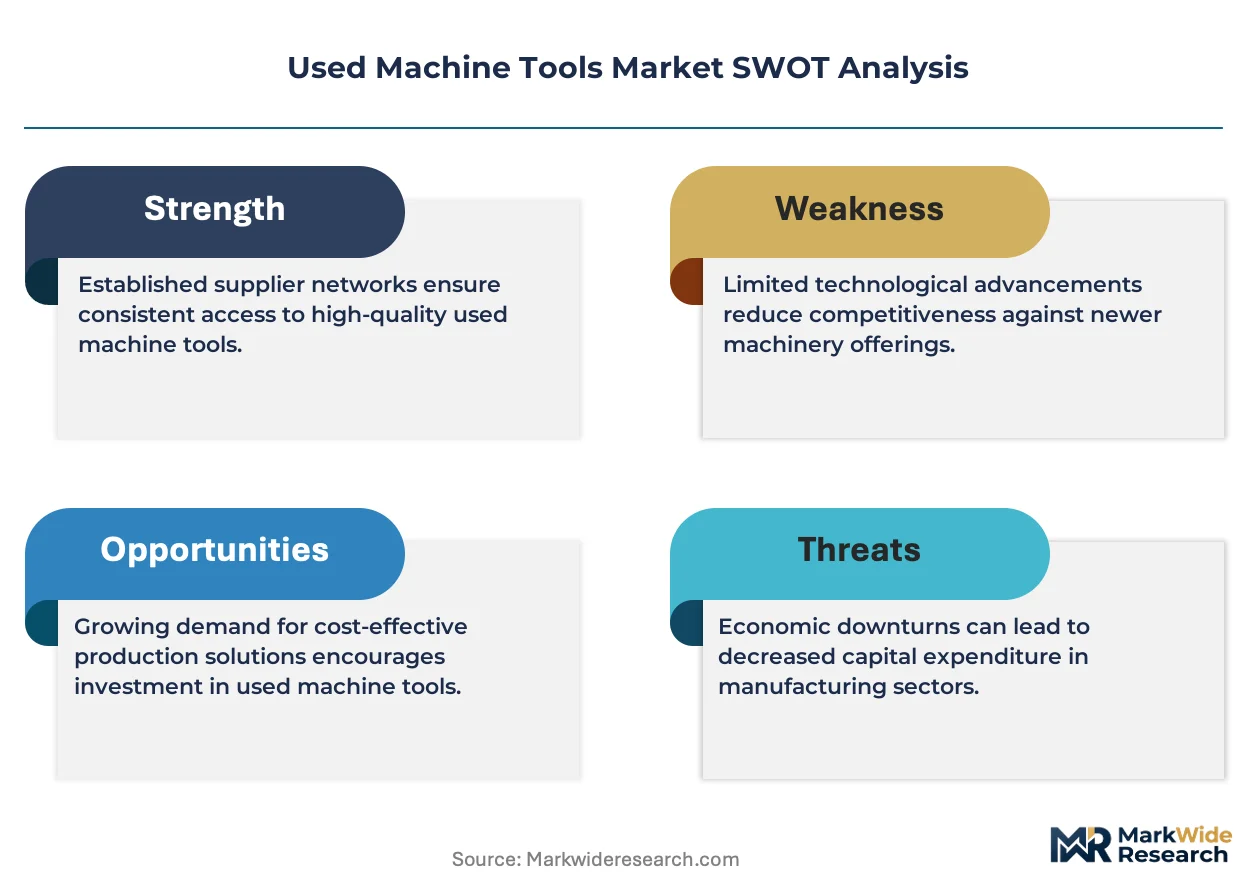
Factory-certified refurbishment replacing independent dealer reconditioning simultaneously redraws supply geography toward OEM-controlled channels and compresses pricing premiums on undocumented used equipment. German tier-1 automotive suppliers now pay documented-power-profile premiums for BImSchG-compliant slant-bed lathes while Chinese buyers in the Yangtze River Delta exploit arbitrage on late-model Japanese imports without certification overhead.
Pricing Analysis
The customization-premium spread between factory-configured CNC retrofits and standard used equipment runs wide. Pricing stratifies across factory-certified rebuilds, dealer-reconditioned units, and auction-sourced as-is machines. Cost compression in the as-is tier intensifies as energy audit documentation requirements concentrate buyer preference upward. Small-scale workshops in India's Coimbatore cluster exhibit highest price sensitivity, while Swiss precision engineering firms in the Jura arc accept substantial premiums for full metrology documentation.
Supply Chain Analysis
Spindle remanufacturing capacity chokepoints in Japan's Nagoya region and Germany's Baden-Württemberg cluster constrain global refurbishment throughput. Supply concentrates in Japan, Germany, and Taiwan for precision grinding equipment, while the United States and China dominate large-format milling machine availability. The supply chain rests on cast iron bed castings, ball screw assemblies, and servo motor controllers. Single-source vulnerability in proprietary CNC controller architectures fragments standardization. Distribution runs through OEM direct buyback channels, independent dealer networks, and specialized heavy equipment brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital efficiency pressures fragmenting procurement authority across tier-1 automotive suppliers and precision engineering firms create white-space openings for specialized refurbishment services and documentation-intensive resale channels.
For Market Incumbents: Shield factory-certified rebuild margins by tightening direct buyback control over late-model trade-ins before independent dealers capture resale flow. Invest in spindle remanufacturing capacity additions in Germany and Japan where aging technician cohorts threaten service quality. Certification investment in AS9100-traceable refurbishment workflows defends positioning against emerging aerospace-focused reconditioning specialists. For New Entrants and Emerging Players: Lead with servo retrofit packages for pre-2000 machine frames in Mexico's Bajío automotive stamping corridor, where greenfield avoidance priorities outrun OEM delivery timelines. Target India's Pune-Ahmedabad metal fabrication cluster with reconditioned hydraulic presses for predictable-duty-cycle stamping operations. Pursue direct partnerships with Japanese machine tool rebuilders for technology transfer rather than independent capability buildout. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-focused rebuilders with documented metrology capabilities over high-velocity asset brokers. Long-term viability hinges on captive technician pipeline development and proprietary controller interface libraries. Acquisition targets should demonstrate established relationships with METI or BAuA certification bodies. Watch for carbon border adjustment implementation tightening as the inflection signal favoring domestic refurbishment over transoceanic trade.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Certified Refurbishment Program Expansion | DMG Mori and Mazak leverage direct buyback control to sustain premium positioning against independent dealers. |
| Servo Retrofit Package Development | Japanese rebuilders miniaturize controller footprints to unlock legacy frame value without greenfield investment. |
| Energy Audit Documentation Integration | German BImSchG compliance creates defensible pricing tiers for verified power profile equipment. |
| Technician Apprenticeship Pipeline Investment | Spindle remanufacturing and geometric accuracy restoration competencies concentrate among aging workforce cohorts. |
| Outcome-Based Utilization Contract Rollout | Michigan and Ohio job shops lease refurbished vertical machining centers with bundled productivity guarantees. |
Research Methodology
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads and secondary validation through customs trade data, SEC equipment manufacturer filings, and regional industrial production databases anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across product type, technology tier, application, and end-user industry dimensions.
Sensitivity analysis on controller upgrade cost curves and energy audit compliance thresholds shapes the analytical framework across the projection horizon. Segmentation modeling incorporates machine type, CNC versus manual technology, aerospace versus automotive versus fabrication application, and tier-1 supplier versus small workshop end-user splits. CAGRs derive from equipment replacement cycle compression rates and capital expenditure approval threshold dynamics in key manufacturing corridors. Forecast inputs include technician workforce demographics and evolving extended producer responsibility scheme coverage.
The analysis sits within stated boundaries; outcomes outside sustained capital efficiency pressures and stable cross-border trade policy would require recalibration. Forecasts reflect documented assumptions regarding energy audit adoption rates and certification timeline standardization. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and technician pipeline replenishment rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market