
 Digital Twin-Enabled Structural Health Monitoring Test Platforms Market | 2026-2036
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market Insights
Aftermarket service revenue is fragmenting across hardware-software boundaries as vendors reposition for recurring platform licensing. Siemens leverages its industrial software heritage to dominate digital twin modeling for energy generation clients. National Instruments sustains R&D intensity in sensor fusion architectures for aerospace engineering applications. Trimble competes through geographic dominance in infrastructure management across North American bridge monitoring deployments.
Digital twin-enabled structural health monitoring test platforms integrate physical asset replicas with real-time sensor streams to simulate stress, fatigue, and failure modes before physical manifestation. These systems typically operate at sampling rates exceeding 1 kHz for vibration analysis and employ IoT Integration to synchronize edge devices with cloud-based analytics engines. Cloud-Based platform types are capturing expanding margin pools as transportation OEMs shift capital expenditure to operational expenditure models, while AI Analytics represents the fastest-growing technology segment as pattern recognition replaces threshold-based alerting in wind turbine inspections. Edge Computing configurations remain mature in aircraft structural analysis where latency constraints override cloud economics.
The FAA mandates structural integrity reporting for commercial aviation fleets, compelling aerospace engineering firms to adopt certified digital twin platforms for continuous airworthiness demonstration. EASA aligns with FAA requirements through its own certification memoranda, while the EU AI Act imposes risk-classification obligations on automated decision systems embedded in railway track evaluation workflows. Stakeholders must monitor evolving interoperability standards between national rail regulators and platform vendors as cross-border infrastructure digitization accelerates.
Market Dynamics
The convergence of AI Analytics with edge computing architectures is compressing decision latency in structural monitoring workflows, compelling platform vendors to reconfigure hardware-software integration strategies around real-time inference requirements.
Growth Catalysts
- FAA Structural Integrity Mandates:Commercial aviation operators must demonstrate continuous airworthiness through certified digital twin systems, creating compliance-driven procurement cycles for predictive maintenance platforms.
- EU AI Act Risk Classification:Automated decision systems in railway infrastructure evaluation face mandatory conformity obligations, accelerating platform certification investments across European track networks.
- Wind Turbine Inspection Automation:Pattern recognition algorithms are displacing threshold-based alerting in offshore wind assets, driving sensor fusion platform deployments with sub-millisecond synchronization requirements.
Market Restraints
- High-Precision Sensor Cost Volatility:MEMS accelerometer and fiber optic strain gauge supply concentrates in East Asian foundries, exposing platform OEMs to input cost fluctuations and dual-sourcing constraints.
- CE Marking Certification Friction:Critical infrastructure platforms face extended conformity assessment timelines under EU machinery directives, delaying revenue recognition for non-European vendors.
- Physics-Based Simulation Substitution:Reduced-order modeling techniques in academic research settings threaten to commoditize core digital twin functionality for lower-complexity bridge and building applications.
Strategic Opportunities
- Underpenetrated Brazilian Infrastructure:ANVISA regulatory alignment with international medical device standards creates pathway for platform vendors to repurpose aerospace-certified systems for dam and hydroelectric monitoring.
- 5G-Enabled Edge Orchestration:Ultra-reliable low-latency communication standards are converging with containerized analytics runtimes, enabling distributed structural monitoring without fiber backhaul investments.
- US IRA Clean Energy Tax Credits:Domestic content requirements for wind and solar asset qualification are incentivizing localized platform assembly and sensor calibration facility development.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Platform vendors compete for computational mechanics specialists capable of integrating thermal, mechanical, and electromagnetic domain models within unified twin architectures.
- Legacy SCADA Integration Complexity:Brownfield industrial sites operate decades-old data acquisition infrastructure with proprietary protocols, forcing expensive middleware development for digital twin connectivity.
- Cross-Border Certification Timeline Compression:Divergent national rail regulator interoperability standards in Europe fragment platform homologation efforts, extending sales cycles for cross-border infrastructure projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Twin-Enabled Structural Health Monitoring Test Platforms Market |
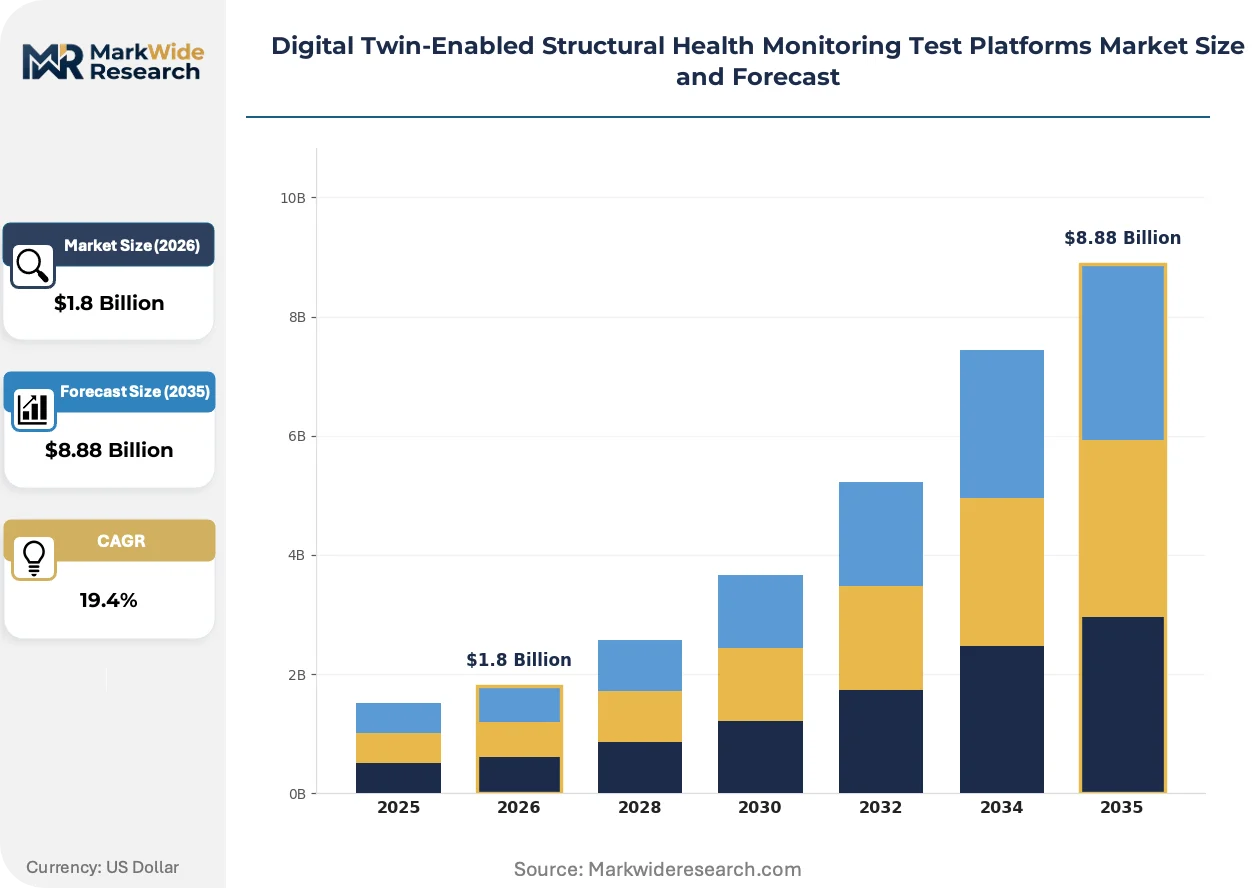
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premises, Hybrid Systems, Edge Computing Technology: Sensor Fusion, AI Analytics, IoT Integration, Digital Twin Modeling Application: Bridge Monitoring, Aircraft Structural Analysis, Wind Turbine Inspections, Railway Track Evaluation End User Industry: Transportation OEMs, Aerospace Engineering, Energy Generation, Infrastructure Management |
| Companies Covered | Siemens, Trimble, Yokogawa Electric, National Instruments, Hottinger Brüel & Kjær, Geocomp, Geokon, Luna Innovations, Nova Metrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market Trends and Innovations
Computational architectures are fragmenting across latency-sensitive and analytics-intensive use cases, forcing vendors to maintain parallel development tracks rather than unified platform strategies.
Federated learning frameworks are hybridizing centralized model training with localized edge inference, preserving data sovereignty for sensitive infrastructure operators while enabling collective pattern recognition across distributed asset fleets. Railway authorities in Germany and France are piloting these architectures for track geometry monitoring, compressing anomaly detection cycles from weeks to hours without transmitting raw sensor data across jurisdictional boundaries.
The EU AI Act's high-risk system obligations are reshaping documentation and audit trail requirements for automated structural assessment tools. Platform vendors must now maintain algorithmic transparency registers and human-in-the-loop override capabilities for railway track evaluation workflows, with EASA-aligned certification memoranda extending these requirements into commercial aviation predictive maintenance contracts.
Capital deployment preferences are rotating from perpetual licensing toward consumption-based platform access, particularly among transportation OEMs managing variable fleet sizes. Cloud-Based configurations with metered analytics processing are displacing on-premise installations in North American bridge monitoring programs, though aircraft structural analysis retains Edge Computing dominance due to inflight connectivity constraints and FAA airworthiness data locality requirements.
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market Segmentation
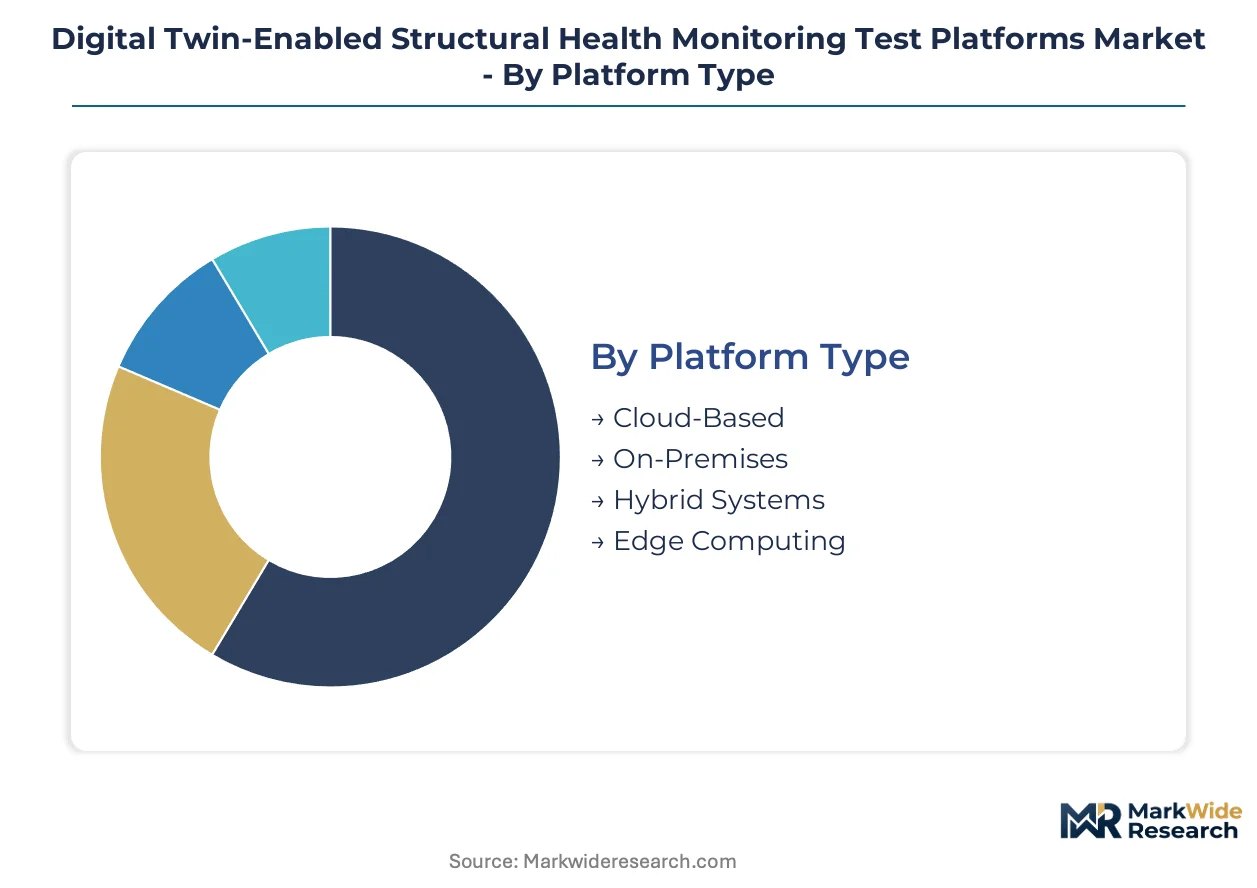
Structural health monitoring test platforms fragment across deployment architectures, analytical technologies, physical asset types, and purchaser industries. Each dimension carries distinct procurement logic, certification requirements, and margin profiles that reshape vendor positioning strategies.
Platform Type:
Deployment cost tiers separate capital-intensive perpetual installations from recurring operational expenditure models.
- Cloud-Based:Metered analytics processing with elastic compute scaling supports variable fleet sizes. Transportation OEMs in Germany and France are migrating bridge monitoring programs to these configurations to convert fixed infrastructure costs into usage-based expenditures aligned with maintenance seasonality.
- Edge Computing:Localized inference engines operating below 10 millisecond latency serve aircraft structural analysis where FAA airworthiness data locality requirements prohibit cloud transmission. Inflight connectivity constraints and continuous certification audits reinforce on-asset processing dominance.
- On-Premises:Dedicated hardware installations persist in nuclear and hydroelectric facilities with air-gapped security mandates.
- Hybrid Systems:Partitioned workloads route vibration analysis to edge nodes while aggregating trend analytics through cloud gateways.
Edge Computing commands the established base in aviation. The steepest expansion runs through Cloud-Based configurations as infrastructure operators abandon perpetual licensing.
Technology:
Analytical maturity determines integration complexity and specialist labor requirements across implementation phases.
- AI Analytics:Pattern recognition algorithms displace threshold-based alerting in offshore wind turbine inspections. Pattern libraries trained on North Sea asset degradation models now transfer to Baltic installations, compressing commissioning timelines for Danish and German operators.
- Sensor Fusion:Sub-millisecond synchronization of MEMS accelerometers, fiber optic strain gauges, and acoustic emission detectors generates unified stress field visualizations. Railway authorities in France deploy these architectures for track geometry anomaly detection.
- IoT Integration:Protocol translation layers connect legacy SCADA infrastructure to modern twin architectures.
- Digital Twin Modeling:Physics-based simulation kernels require computational mechanics specialists capable of multiphysics integration.
Digital Twin Modeling anchors current revenue concentration. AI Analytics is gaining share fastest as automated assessment displaces manual inspection cycles.
Application:
Physical asset criticality and failure consequence severity shape procurement authority and certification stringency.
- Aircraft Structural Analysis:Continuous airworthiness demonstration mandates under FAA and EASA regulations compel commercial aviation operators to maintain certified digital twin systems with complete audit trails. Sampling rates exceeding 1 kHz for vibration analysis support fatigue life prediction.
- Wind Turbine Inspections:Offshore installations in the North Sea and Baltic regions drive automated blade assessment demand. Sub-millimeter crack detection through computer vision reduces technician helicopter deployments.
- Bridge Monitoring:North American state transportation departments deploy fiber optic sensing across aging suspension infrastructure.
- Railway Track Evaluation:EU AI Act high-risk system obligations impose documentation requirements on automated track assessment workflows.
Aircraft Structural Analysis sustains premium pricing through regulatory compulsion. Wind Turbine Inspections shows the steepest volume trajectory as renewable asset fleets expand.
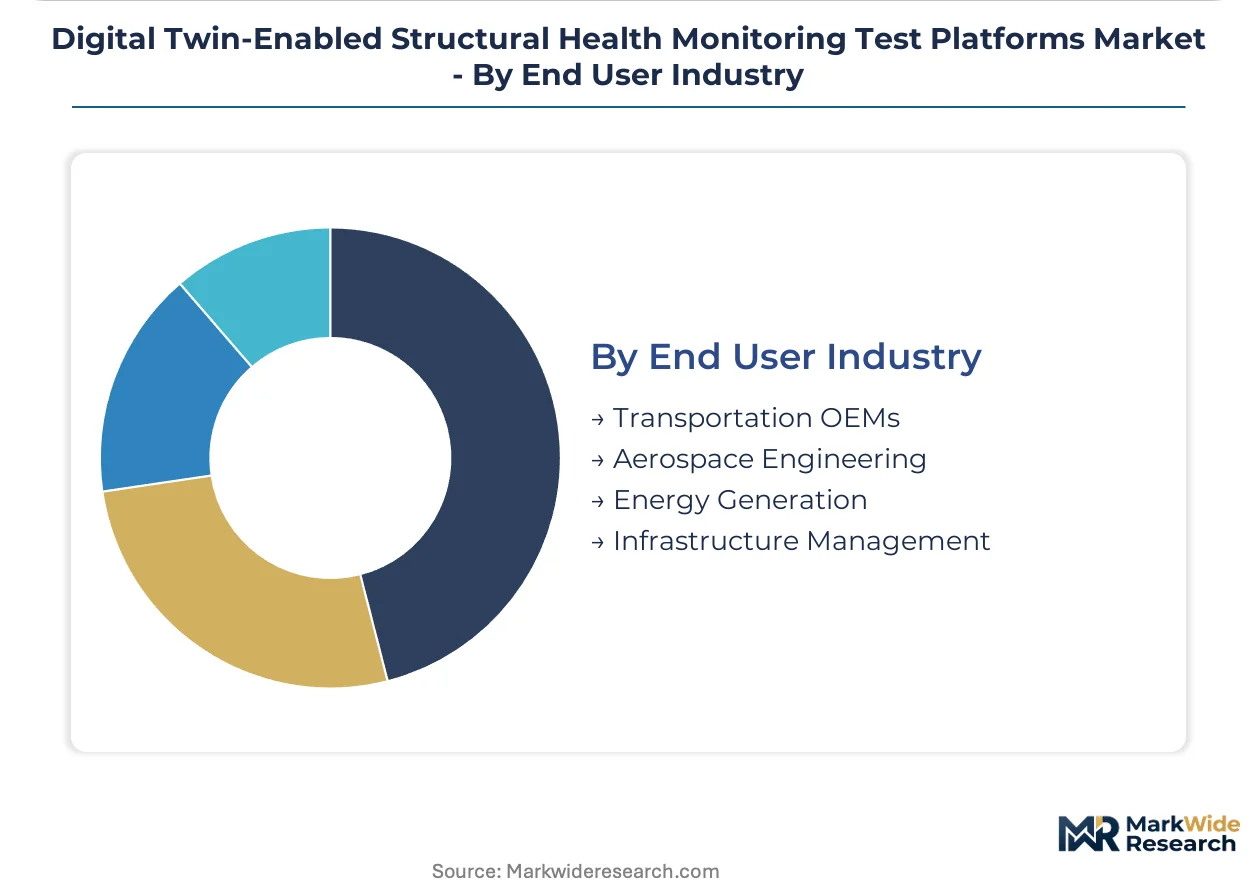
End User Industry:
Customer technical sophistication and internal engineering capacity determine platform customization depth and service attachment rates.
- Aerospace Engineering:Firms such as Airbus and Boeing tier-one suppliers maintain dedicated digital twin engineering groups. These organizations demand API access for custom algorithm integration and resist vendor-managed service models.
- Transportation OEMs:Variable fleet sizes and seasonal maintenance windows favor consumption-based platform access with metered processing.
- Energy Generation:Siemens anchors industrial deployment across German turbine fleets with integrated software-hardware bundles.
- Infrastructure Management:Public sector procurement cycles and federal funding dependencies extend sales timelines.
Aerospace Engineering retains the deepest platform penetration. Transportation OEMs demonstrate the most rapid procurement model transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German industrial operators absorb premium pricing for certified platforms, while Brazilian infrastructure agencies prioritize cost-efficient configurations amid budget constraints.
United States
FAA structural integrity mandates drive commercial aviation procurement cycles for predictive maintenance platforms. The IRA clean energy tax credits incentivize domestic sensor calibration facilities for wind asset operators. Texas and California host concentrated renewable energy clusters where platform vendors establish localized assembly operations.
Germany
Siemens anchors industrial digital twin deployment across energy generation and transportation infrastructure. EU AI Act risk-classification obligations accelerate platform certification investments for railway track evaluation workflows. Bavaria and North Rhine-Westphalia concentrate R&D activity for multiphysics simulation talent development.
China
Dual carbon goals and offshore wind expansion generate demand for automated blade inspection systems. GB standards and MIIT regulations shape domestic platform interoperability requirements. Yangtze River Delta manufacturing clusters produce MEMS accelerometers for regional sensor fusion architectures.
France
Railway authorities pilot federated learning frameworks for track geometry monitoring without cross-border data transmission. EASA-aligned certification memoranda extend EU AI Act documentation requirements into aviation maintenance contracts. Île-de-France hosts aerospace engineering firms demanding API access for custom algorithm integration.
Brazil
ANVISA regulatory alignment with international standards creates pathways for aerospace-certified system repurposing in dam monitoring. Federal infrastructure investment programs prioritize cost-efficient bridge sensing deployments. São Paulo and Minas Gerais concentrate hydroelectric asset operators evaluating digital twin platforms.
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market Competitive Landscape
Industrial software conglomerates and precision instrumentation specialists split the market between integrated platform bundles and component-level sensor fusion architectures. Siemens leverages its automation heritage to dominate energy sector deployments, while National Instruments sustains R&D intensity in aerospace applications. The competitive landscape rewards backward integration into sensor manufacturing and strategic partnerships with regulatory certification bodies.
Within the industrial software tier, Siemens exemplifies the vertically integrated archetype through captive digital twin modeling capabilities. National Instruments and Trimble occupy distinct positioning vectors—National Instruments represents the measurement-specialist archetype with sensor fusion heritage, while Trimble anchors the infrastructure-focused geographic concentration model. Yokogawa Electric and Hottinger Brüel & Kjær sit within the precision instrumentation tier, exemplifying component-scale specialization rather than platform-scale integration.
| Leading Market Players |
|---|
| Siemens |
| Trimble |
| Yokogawa Electric |
| National Instruments |
| Hottinger Brüel & Kjær |
| Geocomp |
| Geokon |
| Luna Innovations |
| Nova Metrix |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision MEMS foundries across Taiwan and South Korea is compressing sensor module availability, forcing platform OEMs to absorb input cost volatility while passing selective premiums to buyers with FAA-mandated compliance deadlines.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers now generate lifetime value exceeding initial hardware sales. Pricing stratifies across premium, standard, and economy tiers based on certification grade—FAA/EASA-aligned platforms command substantial premiums over CE-marked infrastructure configurations—and geographic delivery cost differentials. Cost compression in economy-tier bridge monitoring systems is intensifying because Brazilian and Southeast Asian buyers prioritize capital efficiency over predictive analytics depth. Transportation OEMs with variable fleet sizes demonstrate highest price sensitivity, while aerospace engineering firms absorb premiums for continuous airworthiness demonstration capabilities.
Supply Chain Analysis
Contract manufacturing for fiber optic strain gauges concentrates in Yangtze River Delta facilities, with MEMS accelerometer packaging anchored in Taiwanese OSAT networks. Supply draws from East Asian semiconductor foundries, German precision optics specialists, and North American FPGA suppliers. Single-source vulnerability in high-precision sensor substrates exposes platform vendors to allocation risk during capacity crunches. Distribution runs through direct OEM relationships for aviation-certified systems, while infrastructure deployments utilize systems integrators with regional calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act risk-classification mandates are accelerating platform certification investments, creating a regulatory inflection that favors vendors with pre-positioned conformity infrastructure.
For Market Incumbents: Pre-empt commoditization threats from reduced-order modeling academic research by deepening backward integration into sensor manufacturing and securing exclusive calibration facility partnerships in Texas and Bavaria. Anchor defensibility through FAA/EASA certification moats that delay non-compliant entrants from accessing commercial aviation procurement cycles. For New Entrants and Emerging Players: Brazilian hydroelectric dam monitoring offers accessible entry with repurposable aerospace-certified architectures and ANVISA-aligned regulatory pathways. Target cost-efficient bridge sensing deployments through federal infrastructure programs in São Paulo state, leveraging 5G-enabled edge orchestration to bypass fiber backhaul investments that burden incumbent platform economics. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform vendors with captive sensor manufacturing and established certification body relationships. Long-term viability hinges on regulatory compliance automation capabilities rather than hardware differentiation alone. Monitor EU AI Act implementation timelines as the critical inflection signal for certification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Body Partnership | FAA and EASA memoranda alignment accelerates platform homologation for cross-border aviation contracts. |
| Sensor Manufacturing Integration | Captive MEMS accelerometer production insulates margins from East Asian foundry allocation volatility. |
| Federated Learning Deployment | German and French railway pilots demonstrate data-sovereignty-compliant pattern recognition without raw sensor transmission. |
| 5G Edge Orchestration | Ultra-reliable low-latency standards enable distributed structural monitoring without fiber infrastructure investments. |
| Consumption-Based Platform Launch | Metered analytics processing aligns transportation OEM procurement with seasonal maintenance budget cycles. |
Research Methodology
Initial hypotheses were tested against primary input from aerospace engineering procurement directors, railway authority technology officers, wind farm maintenance supervisors, and digital twin software architects and refined through secondary validation against FAA airworthiness directives, EASA certification memoranda, EU AI Act regulatory texts, and SEC filings from industrial automation conglomerates. Bottom-up segment sizing triangulated with top-down market construction across platform type, analytical technology, physical asset application, and end-user industry dimensions.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation spanning deployment architecture, AI analytics maturity, aircraft structural analysis versus wind turbine inspection applications, and aerospace engineering versus transportation OEM customer archetypes. CAGRs derived from regression against historical platform adoption curves, regulatory mandate implementation schedules, and renewable asset fleet expansion trajectories. Forecast inputs incorporated sensor fusion R&D intensity patterns and cloud infrastructure capex disclosures from hyperscaler partners.
Practitioners should monitor EU AI Act enforcement granularity and FAA certification timeline compression for early signals of platform vendor consolidation or margin restructuring. Quarterly review of MEMS foundry utilization rates and cross-border rail regulator interoperability standardization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Concrete Market