
 Europe Indoor Farming Market | 2026-2036
Europe Indoor Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Indoor Farming Market Intelligence
Project finance and equipment leasing is narrowing the capital barrier for new entrants in European indoor agriculture. Infarm Holding GmbH leverages its modular vertical farm units to secure shelf space with major grocery retailers across Germany and France. Signify N.V. dominates the horticultural LED segment, sustaining technical leadership through spectral tuning patents that optimize crop photomorphogenesis. Priva anchors the climate control software layer, competing on integration depth with greenhouse automation systems.
Europe indoor farming denotes the soilless cultivation of crops within enclosed environments using hydroponic, aeroponic, or aquaponic systems, typically employing artificial LED lighting with photosynthetic photon flux densities exceeding 200 µmol/m²/s to achieve year-round production independent of external weather conditions. The technology serves commercial food producers, research institutions, and residential growers seeking supply chain resilience and pesticide reduction. Hydroponics occupies the largest installed base due to lower technical complexity and proven nutrient delivery economics, while aeroponics represents the fastest-expanding technology segment as precision misting systems improve water-use efficiency and accelerate harvest cycles. LED Lighting commands the dominant margin pool because semiconductor component costs continue declining while spectral customization commands premium pricing from commercial operators.
The EU Green Deal and F-Gas Regulation are mandating transitions to low-global-warming-potential climate systems, directly reshaping capital expenditure planning for controlled-environment agriculture operators. EFSA guidelines on novel food safety and national organic certification standards determine market access for produce claiming soil-free cultivation credentials. REACH compliance for nutrient solutions and growing substrates adds ongoing regulatory monitoring obligations. Stakeholders must track evolving national implementation timelines for EU-wide sustainability mandates and assess how carbon border adjustments affect imported input costs.
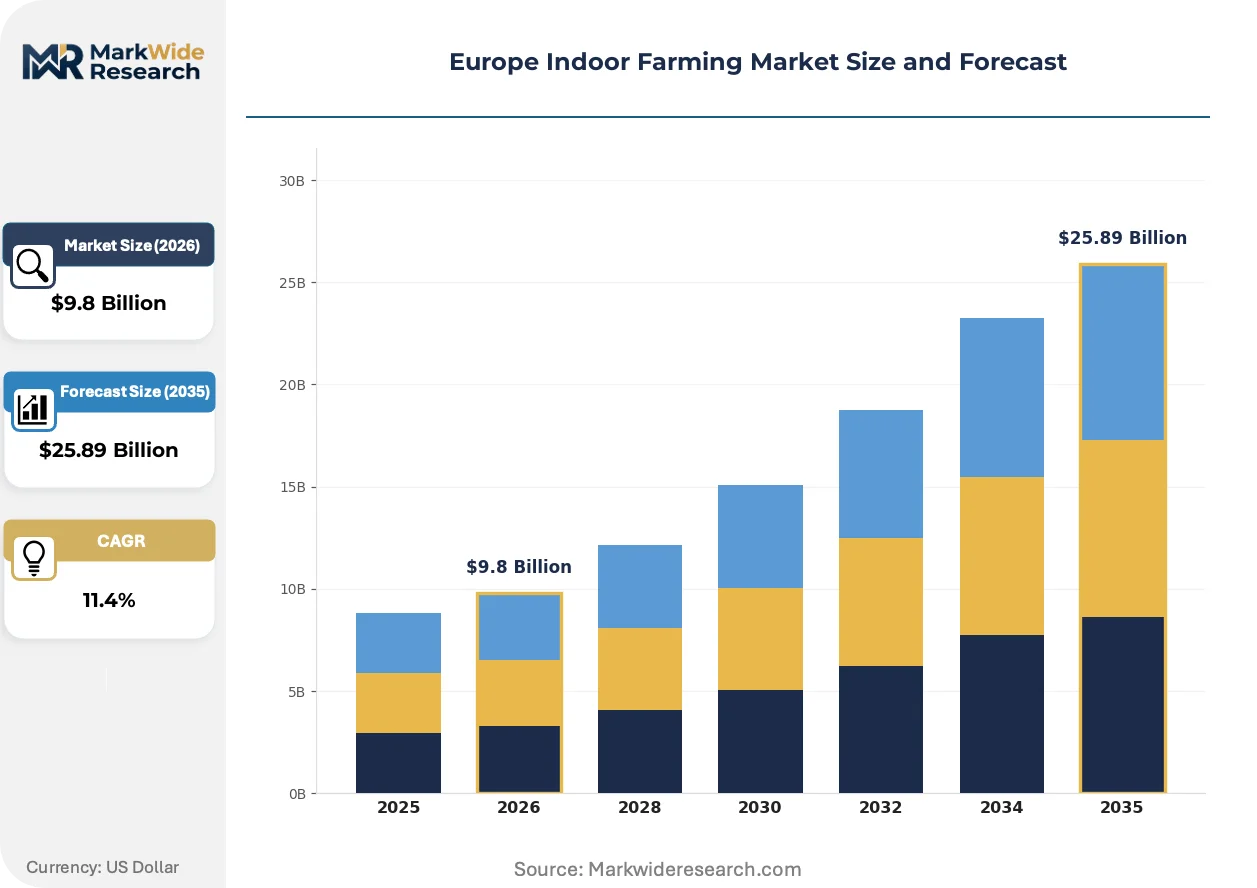
Market Dynamics
The EU F-Gas Regulation is forcing controlled-environment agriculture operators to replace high-GWP refrigerants with climate-friendly alternatives, compressing capital cycles and reshaping equipment procurement priorities across Dutch, German, and French growing clusters.
Growth Catalysts
- Restaurant hyperlocal sourcing:Urban foodservice operators in Paris, Berlin, and Amsterdam now specify zero-mile greens in procurement contracts, pulling supply from city-adjacent vertical farms.
- EU Green Deal carbon accounting:Mandatory Scope 3 disclosure requirements for food retailers are elevating soil-free cultivation as a verifiable low-carbon sourcing option.
- Horticultural LED cost curves:Semiconductor manufacturing scale in Asia-Pacific is driving photosynthetic fixture prices downward, improving project IRRs for European operators.
Market Restraints
- Energy input volatility:German and Italian electricity pricing swings compress operating margins for climate-controlled facilities running 18-hour photoperiods.
- Climate hardware supply concentration:Precision HVAC and dehumidification systems for sealed growing environments source predominantly from Dutch and Belgian engineering firms, creating single-geography dependency.
- Nutrient solution REACH compliance:ECHA substance authorization timelines extend 18-24 months for novel hydroponic formulations, delaying product launches.
Strategic Opportunities
- Polish and Romanian greenfield development:Lower land and labor costs in Eastern European member states attract Dutch agri-tech expertise for export-oriented production.
- Pharmaceutical-grade botanicals:EMA GMP certification pathways for controlled-environment grown active pharmaceutical ingredients open premium pricing tiers.
- Retail channel direct integration:Modular farm-in-store deployments with French and German grocery chains collapse distribution layers and capture full retail margin.
Industry Challenges
- Controlled-environment agronomy talent scarcity:European universities produce insufficient graduates combining plant physiology, data science, and mechanical systems expertise to staff expanding operations.
- Organic certification ambiguity:Divergent national implementations of EU organic standards for soilless cultivation create market access friction for cross-border produce sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Indoor Farming Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Herbs, Flowers Technology: Hydroponics, Aeroponics, Aquaponics, LED Lighting End User: Retailers, Restaurants, Wholesalers, Home Growers Application: Commercial, Residential, Research, Educational |
| Companies Covered | Infarm Holding GmbH, Signify N.V., Priva, Jones Food Company Ltd., LettUs Grow, Intelligent Growth Solutions, Bridge Greenhouses Ltd., KUBO Group, GrowUp Farms Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Indoor Farming Market Strategic Shifts & Innovations
Spectral engineering and automation architectures are compressing production economics while regulatory pressure on climate systems accelerates equipment refresh cycles across European growing operations.
Dynamic LED spectrum tuning is collapsing the photoperiod optimization problem for leafy green cultivars. Dutch research stations and commercial operators now deploy fixtures adjusting red:far-red ratios in real-time based on plant developmental stage. This capability compresses harvest cycles by 8-12% for butterhead lettuce and enables simultaneous multi-crop programming within single facility footprints.
The F-Gas Regulation is mandating refrigerant transitions in climate-controlled agriculture, prohibiting new installations using R404A and R507A with GWP values exceeding 2500. German and Danish greenhouse engineering firms are accelerating heat pump and CO2 transcritical system deployments. Operators in the Netherlands face 2027 phase-out deadlines for existing high-GWP inventory, compressing capex planning horizons.
Buyer consolidation among German and French retail grocery banners is reshaping supplier contracting terms. Edeka, Carrefour, and Auchan now demand multi-year volume commitments with price escalation clauses tied to energy indices. This concentration forces vertical farm operators to secure long-dated power purchase agreements or on-site generation assets to meet margin targets under fixed-price produce contracts.
Europe Indoor Farming Market Segmentation
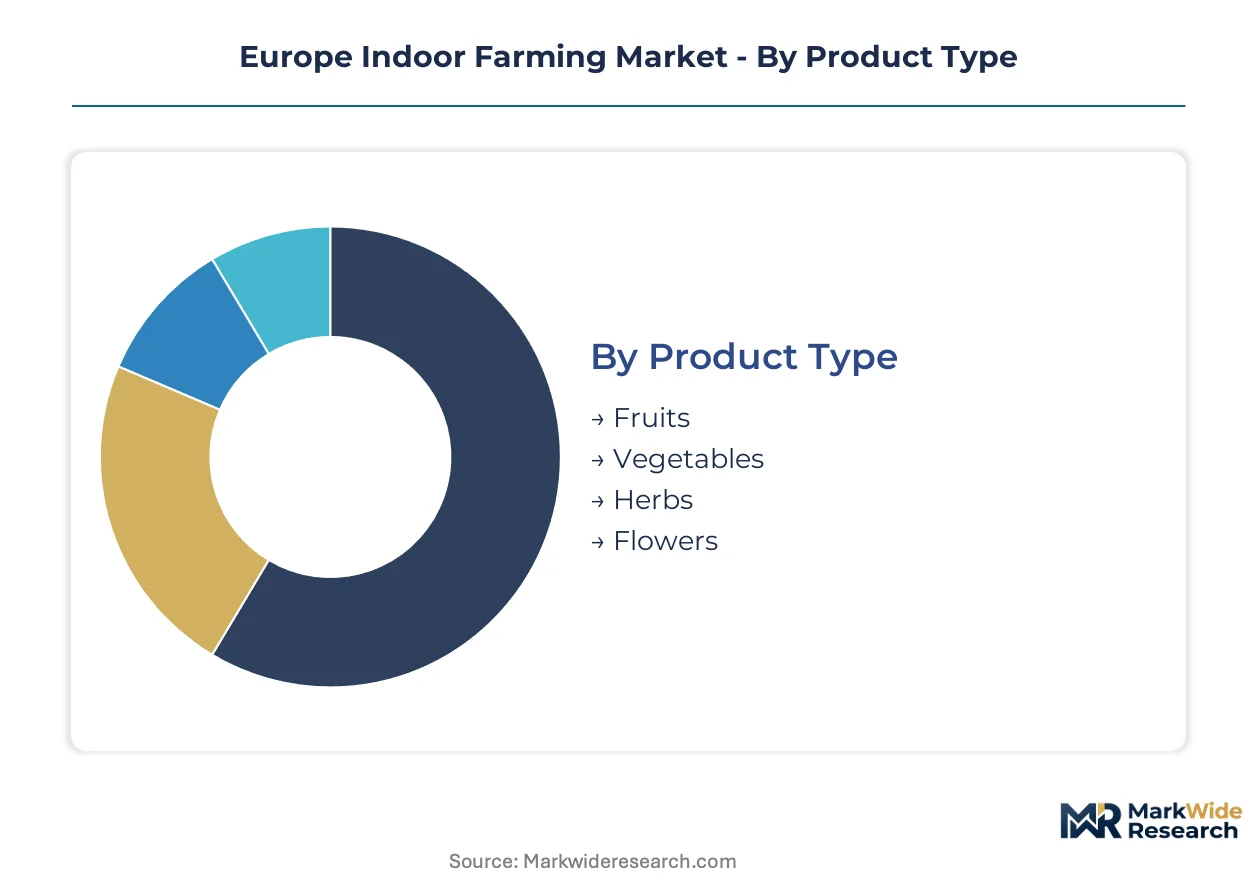
Segmentation in European indoor farming reveals how technology choices and customer channels reshape capital deployment and service intensity. Each dimension carries distinct margin profiles, regulatory exposure, and aftermarket requirements that determine operator viability.
Product Type:
After-sales intensity varies sharply across crop categories, with high-turnover leafy greens demanding continuous technical support while perennial botanicals require minimal intervention.
- Vegetables:Leafy greens and microgreens dominate Dutch and German commercial installations, with butterhead lettuce and baby spinach commanding premium pricing from Berlin and Paris restaurant procurement teams. Service contracts focus on nutrient calibration and harvest-cycle optimization.
- Herbs:Basil, cilantro, and specialty varieties drive the highest margin per square meter in retail-integrated vertical farms, though volatile essential oil content demands precise spectral tuning. Operators in the Netherlands cluster around Wageningen agri-tech corridors to access breeding expertise.
- Fruits:Strawberries and compact tomato cultivars occupy greenhouse retrofits across Belgium and Spain, with extended crop cycles reducing annual service touchpoints.
- Flowers:Ornamental and pharmaceutical-grade botanicals serve research institutions and cosmetic extractors, requiring GMP-compliant climate documentation.
By volume, Vegetables leads. By growth pace, Herbs is ahead.
Technology:
Capital intensity and operating cost structures diverge dramatically across cultivation systems, with implications for financing structures and equipment refresh cycles.
- LED Lighting:Photosynthetic fixtures with dynamic spectrum control anchor every modern installation, with semiconductor cost declines improving project economics. Dutch engineering firms dominate spectral patent portfolios.
- Hydroponics:Nutrient film technique and deep water culture systems constitute the largest installed base across French and German commercial operations due to proven reliability and lower technical barriers.
- Aeroponics:Precision misting systems achieve superior water-use efficiency and accelerated harvest cycles, though nozzle maintenance and pressure calibration demand specialized technician networks concentrated in the Netherlands.
- Aquaponics:Integrated fish-and-plant systems serve educational and research installations in Denmark and Sweden, with biological complexity limiting commercial scale-up.
By installed base, Hydroponics dominates. By expansion trajectory, Aeroponics climbs the fastest.
End User:
Customer concentration and contract structures determine working capital needs, with consolidated retail banners extracting favorable terms while fragmented home growers pay premium prices.
- Restaurants:Urban foodservice operators in Amsterdam, Paris, and Berlin specify zero-mile greens in procurement contracts, pulling supply from city-adjacent vertical farms with just-in-time logistics.
- Retailers:Edeka, Carrefour, and Auchan demand multi-year volume commitments with energy-indexed pricing, forcing operators to secure long-dated power purchase agreements.
- Wholesalers:Traditional produce distributors serve as overflow channels for seasonal capacity, though margin compression limits strategic priority.
- Home Growers:Compact countertop systems target affluent urban consumers in London and Munich, with subscription nutrient services generating recurring revenue.
By contract value, Retailers command the largest commitments. By margin percentage, Home Growers retain the most.
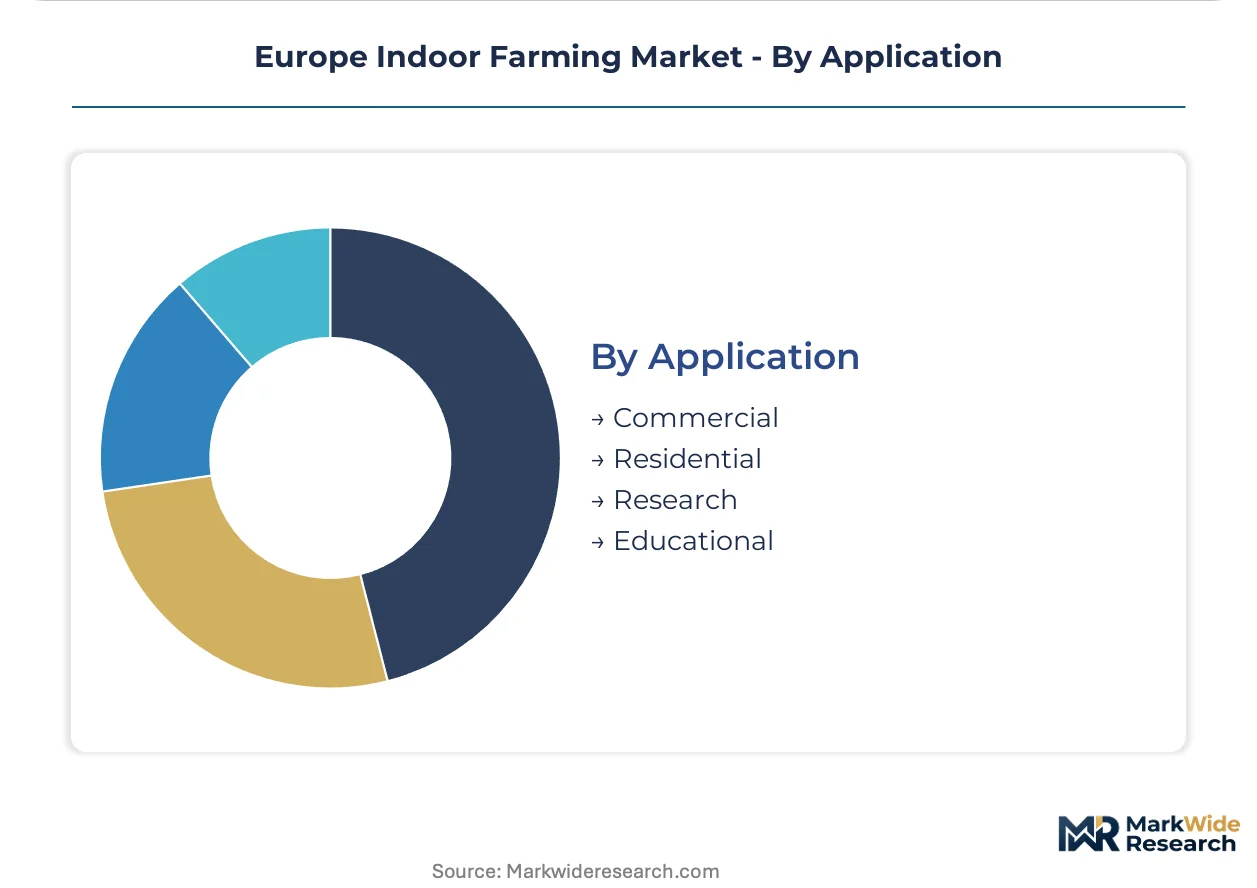
Application:
Facility purpose shapes regulatory exposure and certification requirements, with pharmaceutical and educational installations facing distinct compliance burdens from commercial food production.
- Commercial:Revenue-generating installations across the Netherlands, Germany, and France constitute the core market, with EFSA novel food guidelines and national organic standards determining market access.
- Research:Wageningen University and Danish agricultural stations drive cultivar development and photomorphogenesis studies, with public funding reducing commercial return requirements.
- Residential:Apartment-scale systems in dense urban cores serve supply-chain-conscious consumers, with aesthetic design and noise suppression as key purchase criteria.
- Educational:School and university installations in Scandinavia and the UK emphasize curriculum integration and sustainability demonstration over yield optimization.
By capital deployment, Commercial absorbs the majority. By funding growth, Research expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and national recovery funds are channeling capital into climate-controlled agriculture infrastructure across member states, with regulatory alignment on carbon accounting creating cross-border investment flows.
Netherlands
Wageningen University research partnerships drive cultivar innovation for Dutch greenhouse operators, while the F-Gas Regulation accelerates heat pump retrofits in Westland and Aalsmeer growing clusters. Eindhoven-based LED engineering firms supply spectral tuning systems to German and Belgian installations.
Germany
Berlin and Munich restaurant procurement teams specify zero-mile greens, pulling supply from city-adjacent vertical farms with just-in-time logistics. The national implementation of EU Scope 3 disclosure rules elevates soil-free cultivation in retailer carbon accounting. Bavarian engineering firms dominate precision HVAC system exports.
France
Paris foodservice operators contract hyperlocal basil and microgreens from Île-de-France vertical farms, with Carrefour and Auchan demanding multi-year volume commitments. ANSM guidelines on novel food safety determine market access for pharmaceutical-grade botanicals. Lyon agri-tech startups cluster around research institutions.
United Kingdom
London retail-integrated farm deployments collapse distribution layers for Marks & Spencer and Tesco produce categories. Defra organic certification ambiguity for soilless cultivation creates cross-border friction with EU markets. Bristol and Cambridge research stations drive aeroponic system development.
Poland
Lower land and labor costs attract Dutch agri-tech expertise for export-oriented strawberry and tomato production. EU cohesion fund grants support greenhouse modernization in Mazovia and Silesia. Warsaw logistics hubs serve German and Scandinavian retail channels.
Europe Indoor Farming Market Key Industry Players
Channel-controlling players compete with product-specialist players across equipment, software, and produce supply layers. The vendor base organizes around three archetypes: modular hardware suppliers, climate control software platforms, and vertically integrated produce operators. Consolidation pressure concentrates among LED fixture manufacturers and greenhouse engineering firms. Dominant competitive moves include strategic partnerships with retail grocery banners and technology licensing agreements for spectral tuning patents.
Within the modular vertical farm tier, Infarm Holding GmbH exemplifies retail channel integration, while Signify N.V. anchors the horticultural LED segment through spectral engineering capabilities. Priva occupies a position in climate control software, competing on integration depth with Dutch greenhouse automation systems. These three entities represent distinct strategic archetypes: produce-forward channel control, component technology leadership, and systems integration expertise.
| Leading Market Players |
|---|
| Infarm Holding GmbH |
| Signify N.V. |
| Priva |
| Jones Food Company Ltd. |
| LettUs Grow |
| Intelligent Growth Solutions |
| Bridge Greenhouses Ltd. |
| KUBO Group |
| GrowUp Farms Limited |
| Others |
Cost & Logistics Intelligence
Dutch greenhouse engineering firms concentrate precision HVAC and LED fixture manufacturing, anchoring margin capture downstream with German and French retail banners that demand energy-indexed multi-year contracts. This upstream clustering shapes how operators structure power purchase agreements and equipment financing to defend project returns.
Pricing Analysis
Certification grade creates the primary spread between commercial food-grade installations and pharmaceutical-grade botanical facilities. Three-tier pricing structure across premium GMP-compliant, standard EFSA-registered, and economy non-certified tiers dominates contract structures. Cost compression in standard-tier leafy greens intensifies because semiconductor LED cost declines outpace energy price hedging. Restaurant procurement teams exhibit highest price sensitivity due to thin foodservice margins, while pharmaceutical extractors accept premium pricing for documented climate compliance.
Supply Chain Analysis
Contract manufacturing for precision climate hardware concentrates with Dutch and Belgian engineering firms serving sealed growing environments. Component sourcing draws from German sensor manufacturers, Taiwanese semiconductor foundries, and Chinese LED chip fabricators. Single-geography dependency for HVAC systems creates vulnerability to F-Gas Regulation compliance timelines. Distribution runs through direct retail banner partnerships and specialized agri-tech distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon accounting mandates are disrupting traditional produce sourcing, positioning soil-free cultivation as a verifiable low-carbon alternative that commands procurement preference from Scope 3-disclosing retailers.
For Market Incumbents: Pre-empt margin erosion from LED commoditization by locking long-dated power purchase agreements before German and French retail banners harden energy-indexed contract terms. Consolidate around spectral tuning patent portfolios to defend against Asian semiconductor firms entering horticultural fixture markets. Deepen backward integration into climate control software layers to capture recurring service revenue from Dutch greenhouse automation retrofits. For New Entrants and Emerging Players: Build out Polish and Romanian greenfield installations to exploit land and labor cost arbitrage against Dutch and German operators. Pharmaceutical-grade botanicals in France offer the most penetrable premium segment given ANSM guideline clarity and EMA GMP certification pathways. Pursue farm-in-store modular deployments with Carrefour and Auchan to collapse distribution layers and capture full retail margin. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated produce operators with locked retail channel access rather than pure-play equipment manufacturers facing LED commoditization. Five-to-ten year viability hinges on securing multi-year offtake agreements before buyer consolidation completes. Monitor German and Italian electricity pricing volatility as the critical inflection signal for operating margin stress across climate-controlled facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Retrofit Deployment | F-Gas Regulation deadlines in the Netherlands force accelerated climate hardware replacement cycles. |
| Spectral Patent Licensing | Dutch LED engineering firms monetize photomorphogenesis expertise through technology transfer agreements. |
| Retail Banner Partnership | Edeka and Carrefour volume commitments provide revenue visibility for project finance structures. |
| Eastern European Expansion | Polish and Romanian sites capture Dutch agri-tech expertise at lower land and labor cost bases. |
| GMP Certification Pathway | EMA-compliant climate documentation opens pharmaceutical-grade botanical pricing tiers for French operators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vertical farm operations directors, greenhouse automation engineers, retail produce category buyers, and climate control software architects. Secondary validation drew from EU F-Gas Regulation implementation timelines, EFSA novel food safety guidelines, ECHA REACH substance authorization databases, and national organic certification standards. Bottom-up installation counts across Dutch, German, and French growing clusters were triangulated against top-down equipment shipment data from LED fixture and HVAC system manufacturers.
Calibration against historical capital deployment patterns and regulatory milestone effects anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include cultivation technology, crop category, end-user channel, and facility application type. CAGRs were derived from fitted growth curves incorporating semiconductor cost decline trajectories, energy price scenario bands, and retail procurement contract structuring trends. Industry-specific inputs encompassed Dutch greenhouse engineering capacity utilization and German Scope 3 disclosure implementation pace.
Stress conditions across electricity price volatility, F-Gas Regulation compliance cost shocks, and retail buyer consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about LED cost curves, regulatory enforcement timelines, and channel contracting evolution. Quarterly review of German and Italian power market indicators, ECHA substance authorization progress, and retail banner procurement RFP issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
Hydroponic Substrate Market