
 Global Indoor Farming Technology Market | 2026-2036
Global Indoor Farming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indoor Farming Technology Market Outlook
The EU F-Gas Regulation is decoupling refrigeration-dependent climate control from conventional HVAC economics in European indoor farming operations. Signify Holding leverages its Philips Horticulture LED portfolio to dominate photon efficacy benchmarks across vertical farm installations. NETAFIM anchors drip irrigation intelligence within automated nutrient delivery architectures, while AeroFarms specializes in aeroponic root-misting protocols that eliminate substrate costs entirely.
Indoor farming technology encompasses controlled-environment agricultural systems that deploy artificial lighting, hydroponic or aeroponic substrates, and sensor-networked climate management to cultivate crops without soil or open-field exposure. LED Grow Lights now constitute the dominant energy input category, with spectral tunability enabling cultivators to optimize photomorphogenic responses across lettuce, tomato, and basil crop cycles. Climate Control Systems and Smart Sensors represent the fastest-expanding technology pairing, as integrated IoT architectures reduce labor intensity while tightening yield variance bands for Commercial Growers and Vertical Farms.
The EPA regulates agricultural chemical runoff thresholds that soilless systems bypass, while the EU Green Deal's Farm to Fork Strategy tightens pesticide residue limits that indoor cultivation inherently satisfies. Japan's METI subsidizes plant factory capital expenditure through its Smart Agriculture program, directly lowering breakeven thresholds for domestic operators. Stakeholders must weigh regulatory arbitrage opportunities against energy price volatility when selecting facility locations and technology stacks.
Market Dynamics
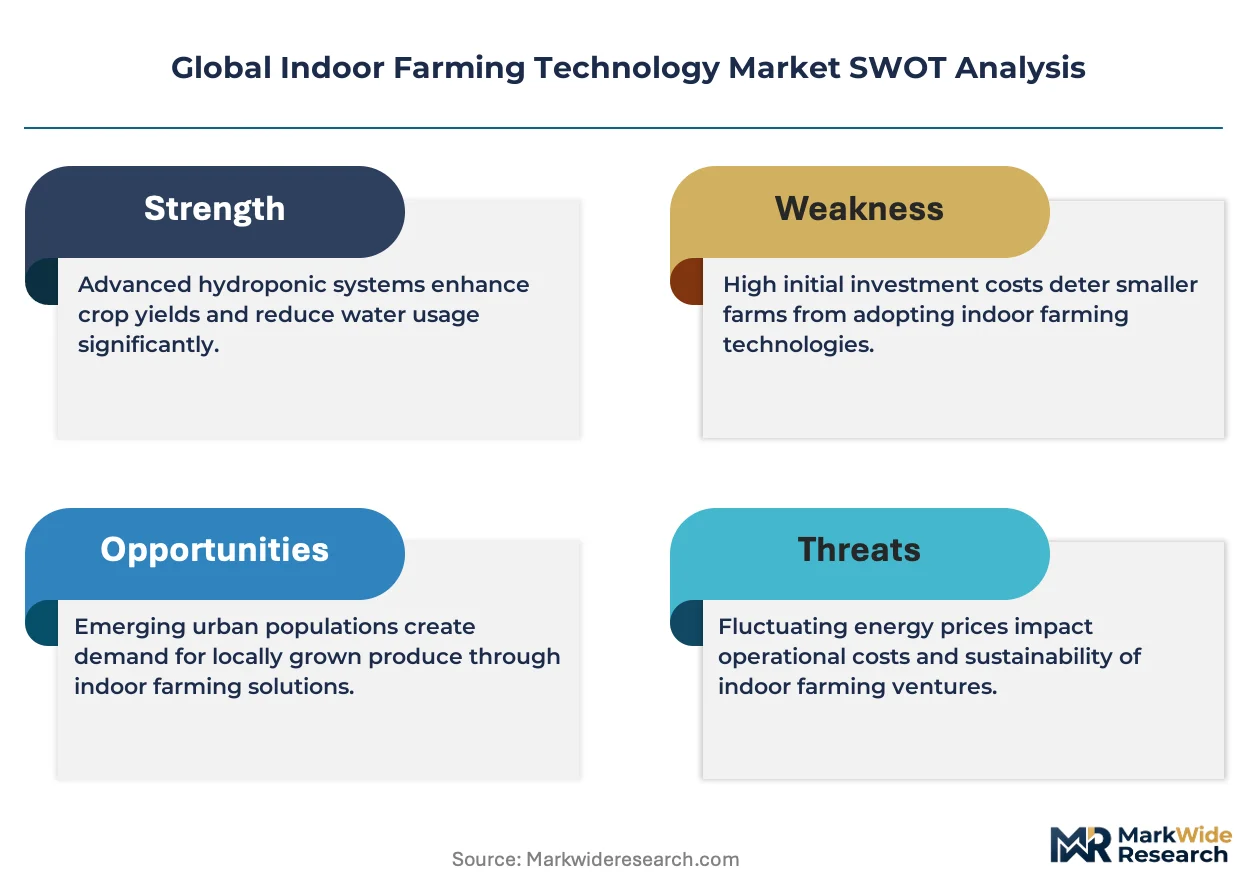
Energy input arbitrage is restructuring facility economics as LED photon efficacy gains compress operating expenditure per kilogram of produce, while grid price volatility forces operators toward on-site renewable generation and storage integration.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Pesticide residue limits are tightening across member states, creating regulatory pull toward soilless cultivation systems that bypass chemical runoff thresholds entirely.
- Japan METI Smart Agriculture subsidies:Capital expenditure support for plant factories is lowering breakeven thresholds for domestic vertical farm operators in Tokyo and Osaka metropolitan corridors.
- LED spectral tunability:Photon delivery systems now enable cultivators to optimize photomorphogenic responses across lettuce, tomato, and basil crop cycles, tightening yield variance bands.
Market Restraints
- Electricity price volatility:Grid-dependent climate control systems expose operators to input cost swings that erode margin predictability in deregulated European and North American markets.
- Refrigerant supply concentration:The EU F-Gas Regulation is decoupling HVAC economics from conventional cooling by restricting hydrofluorocarbon availability, compressing equipment procurement timelines.
- Technical talent scarcity:Integrated IoT architecture deployment requires cross-functional expertise spanning horticulture, electrical engineering, and data analytics that educational pipelines have not scaled.
Strategic Opportunities
- Saudi Arabia NEOM food security mandates:Desert-adjacent megaproject requirements for domestic produce supply are creating first-mover advantages for climate-controlled system integrators.
- Pharmaceutical-grade basil and camomile:Metabolite consistency requirements for nutraceutical extraction are opening premium contract cultivation slots previously served by field agriculture.
- Aeroponic root-misting convergence with AI vision:Elimination of substrate costs combined with real-time root health monitoring is expanding into high-value herb segments.
Industry Challenges
- Multi-system integration complexity:Synchronizing LED arrays, nutrient dosing, and climate control from disparate vendors requires custom middleware that extends commissioning timelines.
- Organic certification pathway ambiguity:Soilless cultivation eligibility for USDA Organic and EU Organic labels remains contested, forcing operators to pursue alternative premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indoor Farming Technology Market |
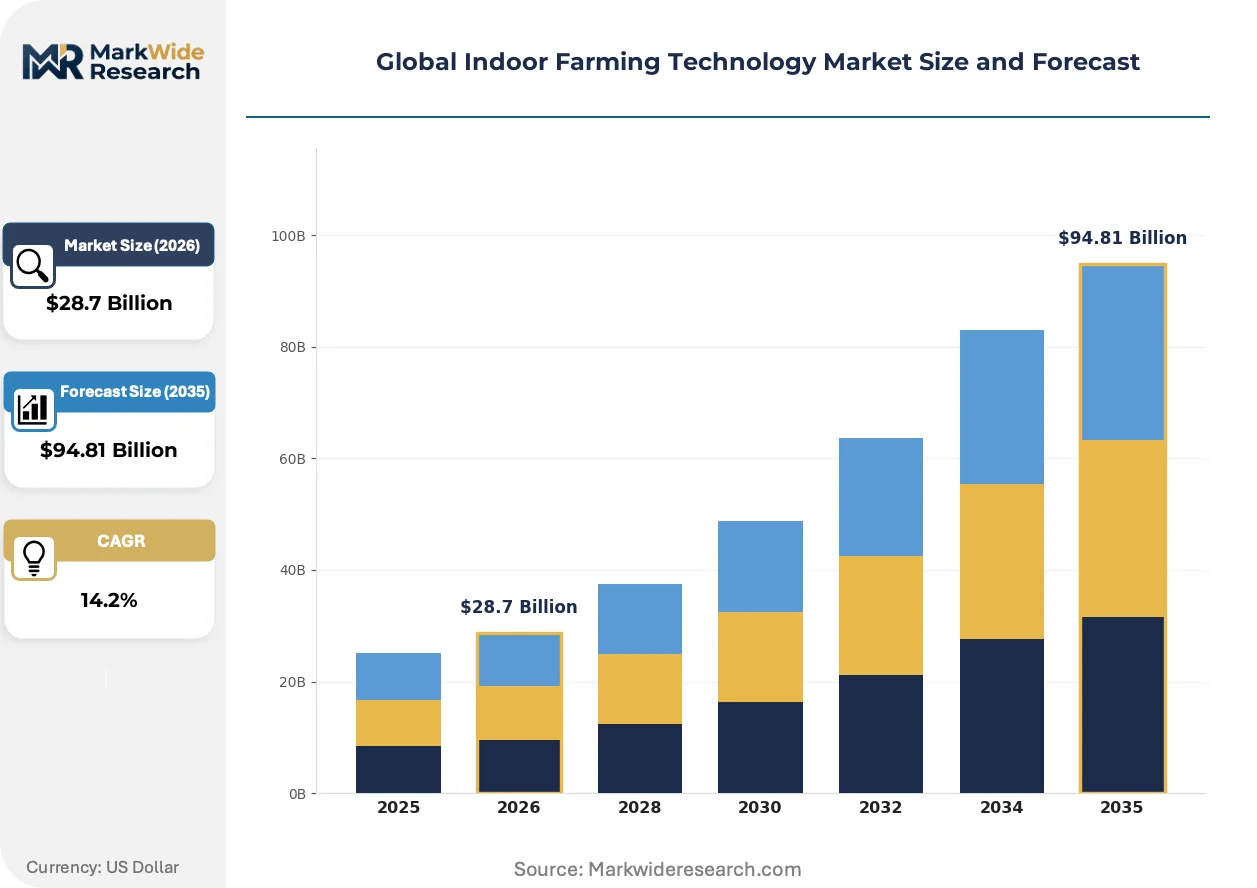
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponics, Aeroponics, Aquaponics, LED Grow Lights Technology: Climate Control Systems, Smart Sensors, Automated Nutrient Delivery, Grow Systems Application: Vegetables, Fruits, Herbs, Flowers End User: Commercial Growers, Research Institutions, Home Growers, Vertical Farms |
| Companies Covered | Signify Holding, NETAFIM, Scotts Company LLC, AeroFarms, Argus Control Systems, LumiGrow, Everlight Electronics, Richel Group, Gotham Greens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indoor Farming Technology Market Strategic Shifts
Automation architectures are compressing labor intensity while spectral science and substrate elimination are rewriting cost structures across controlled-environment agriculture.
Spectral-tunable LED arrays are expanding into pharmaceutical-grade crop production. Biopharmaceutical cultivators in Switzerland and Singapore are adopting narrow-band photon delivery to standardize metabolite profiles for active ingredient extraction. This precision is expanding into contract supply agreements that field agriculture cannot match.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerant availability for climate control equipment. European vertical farm operators are retrofitting facilities with CO2-based transcritical cooling or adsorption systems to maintain temperature setpoints. Dutch commercial installations are responding fastest, with equipment replacement cycles compressing from seven to four years.
Direct procurement from technology-integrated cultivators is displacing traditional produce wholesale channels. Restaurant groups and retail chains in Japan and the UAE are contracting dedicated grow capacity with harvest-to-door logistics. This disintermediation is most visible in Dubai, where hotel and catering procurement teams now specify cultivar genetics and harvest windows in supply agreements.
Global Indoor Farming Technology Market Segmentation
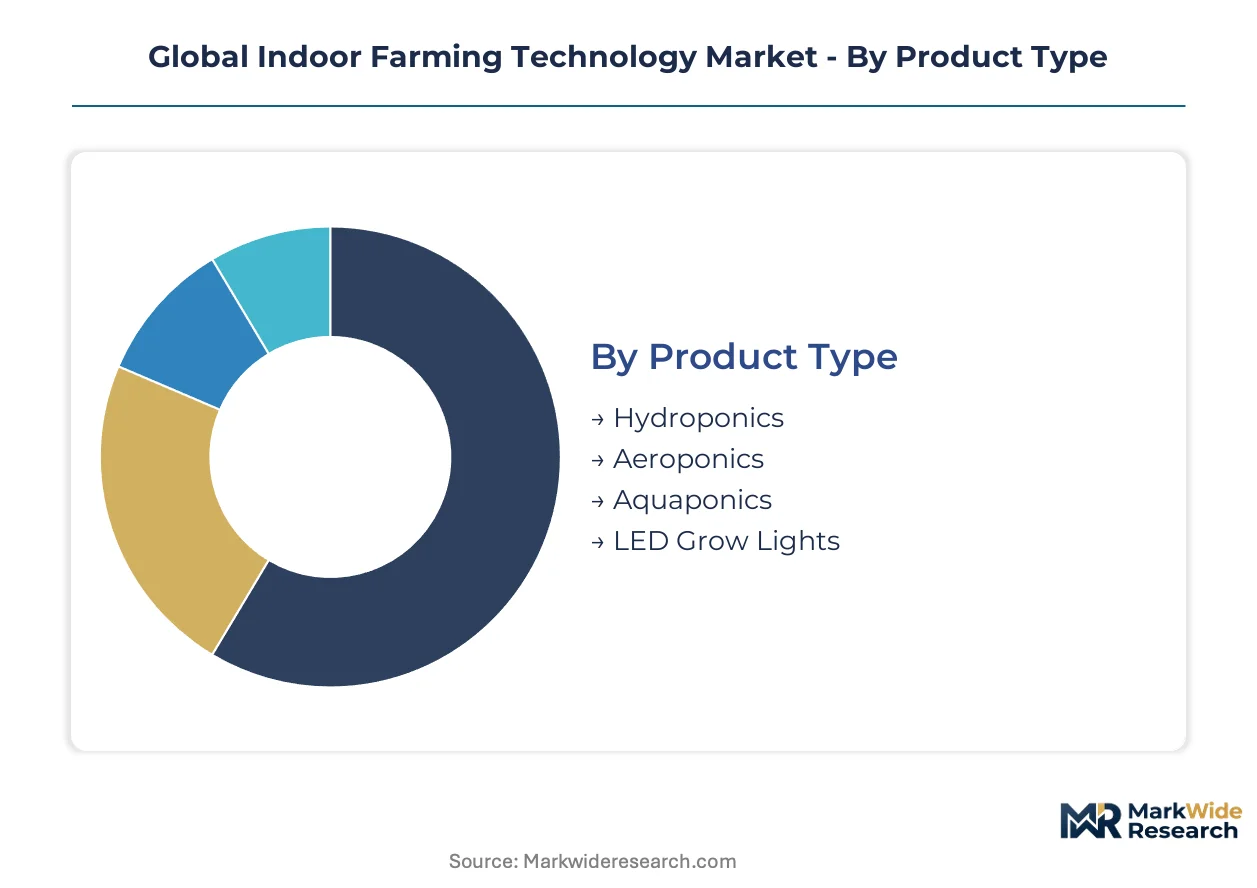
Technology deployment patterns in controlled-environment agriculture diverge sharply by facility scale and crop economics. Segment boundaries reflect capital intensity thresholds, regulatory compliance burdens, and the spectral precision required for pharmaceutical versus commodity produce.
Product Type:
Supply concentration clusters around substrate elimination technologies that compress operating expenditure per harvest cycle.
- Hydroponics:Nutrient film technique and deep water culture systems dominate commercial installations. Dutch greenhouse operators in Westland and Aalsmeer cluster demand here, driven by EU Green Deal water efficiency mandates that favor closed-loop irrigation over soil-based cultivation.
- LED Grow Lights:Spectral-tunable photon delivery systems now constitute the dominant energy input category. Japanese plant factories in Chiba and Kyoto prefectures concentrate procurement, with METI subsidies accelerating replacement of legacy high-pressure sodium installations.
- Aeroponics:Root-misting protocols eliminate substrate costs entirely through ultrasonic or pressure-compensated nozzle architectures.
- Aquaponics:Integrated fish-cultivation loops serve niche educational and research installations with limited commercial scaling.
Today's leader: LED Grow Lights. Tomorrow's challenger: Aeroponics.
Technology:
Cost tier stratification separates integrated platform vendors from point-solution specialists across climate management and sensing layers.
- Climate Control Systems:HVAC and dehumidification architectures with CO2 enrichment modules. UAE vertical farms in Dubai and Abu Dhabi concentrate demand, where desert heat loads force transcritical cooling retrofits ahead of EU F-Gas Regulation timelines.
- Smart Sensors:IoT-enabled pH, EC, and environmental parameter monitoring with edge-computing analytics. Singapore's SFA-licensed urban farms deploy these most densely, with government-backed Agri-Food Innovation Park mandating real-time yield traceability.
- Automated Nutrient Delivery:Dosing pumps and mixing stations with feedback-controlled recirculation.
- Grow Systems:Rack-based vertical farming infrastructure with modular tray configurations.
Climate Control Systems anchor current procurement budgets. Smart Sensors are climbing the fastest as labor substitution pressures intensify.
Application:
Margin structure varies dramatically between pharmaceutical-grade metabolite consistency requirements and commodity leafy green production.
- Vegetables:Lettuce, spinach, and brassica cultivation in controlled environments. US commercial growers in California's Salinas Valley and New York's Hudson Valley corridor drive volume, with EPA agricultural runoff thresholds pushing soilless adoption.
- Herbs:Basil, camomile, and mint for nutraceutical and culinary extraction. Swiss pharmaceutical cultivators near Basel concentrate premium contract demand, where metabolite standardization requirements exclude field agriculture.
- Fruits:Strawberry and tomato vine crops requiring extended photoperiod management.
- Flowers:Ornamental and breeding stock production with limited commercial scale.
Vegetables command installed base. Herbs offer the steepest expansion trajectory through pharmaceutical contract cultivation.
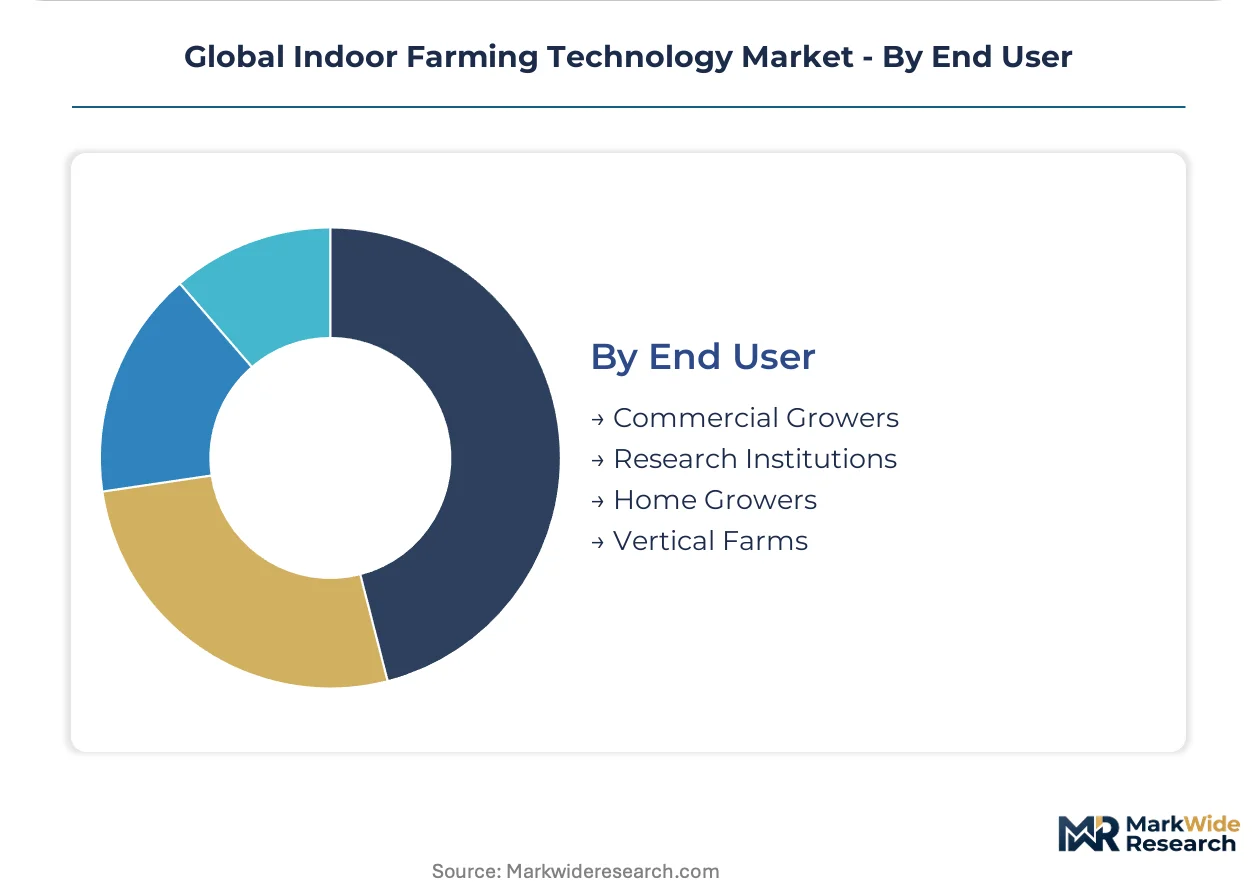
End User:
Customer type determines technology stack complexity, with facility scale dictating integration depth and automation levels.
- Vertical Farms:Purpose-built multi-story installations with fully integrated climate, lighting, and nutrient architectures. Japanese operators in Tokyo's Koto Ward and Osaka's Sakai City cluster here, leveraging METI capital expenditure support to achieve breakeven at metropolitan distribution proximity.
- Commercial Growers:Greenhouse and warehouse conversions with phased automation retrofits. Netherlands-based operations in Bleiswijk and Naaldwijk represent the densest concentration, responding to EU Farm to Fork Strategy pesticide residue limits.
- Research Institutions:University and government facility pilots with grant-funded equipment procurement.
- Home Growers:Small-scale cabinet and tent systems with limited technology integration.
Vertical Farms set technology roadmaps. Commercial Growers are gaining share fastest through retrofit automation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Horticultural engineering talent clusters in the Netherlands anchor European innovation pipelines, while Japanese precision manufacturing expertise drives Asian automation adoption. Israeli agritech specialists and UAE project developers round out the geography-specific workforce concentrations shaping deployment patterns.
Netherlands
Westland and Aalsmeer greenhouse corridors concentrate climate-control engineering expertise for commercial-scale installations. The EU Green Deal's Farm to Fork Strategy tightens pesticide residue limits that soilless systems bypass entirely. Bleiswijk-based operators are retrofitting legacy facilities with CO2-based transcritical cooling ahead of F-Gas Regulation phase-out schedules.
Japan
Tokyo's Koto Ward and Osaka's Sakai City metropolitan corridors concentrate plant factory deployment driven by extreme land scarcity. METI's Smart Agriculture program subsidizes capital expenditure for domestic vertical farm operators. Chiba and Kyoto prefectures are replacing legacy high-pressure sodium installations with spectral-tunable LED arrays at accelerated procurement cycles.
United States
California's Salinas Valley and New York's Hudson Valley corridor drive commercial grower volume for soilless vegetable production. EPA agricultural runoff thresholds push adoption away from open-field cultivation toward closed-loop hydroponic systems. Commercial operators in these clusters are integrating automated nutrient delivery with IoT sensor networks to tighten yield variance bands.
United Arab Emirates
Dubai and Abu Dhabi vertical farms concentrate demand for transcritical cooling systems under extreme desert heat loads. MOHAP food security mandates accelerate procurement timelines for climate-controlled domestic produce supply. Hotel and catering procurement teams in Dubai now specify cultivar genetics and harvest windows in direct supply agreements with technology-integrated cultivators.
Switzerland
Basel-region pharmaceutical cultivators concentrate premium contract demand for metabolite-consistent herbs. Swissmedic nutraceutical extraction standards exclude field agriculture from pharmaceutical-grade basil and camomile supply chains. Biopharmaceutical operators near Basel are adopting narrow-band photon delivery to standardize active ingredient profiles for contract manufacturing agreements.
Global Indoor Farming Technology Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the technology stack, creating a tiered market structure where scale advantages clash with agility premiums. The vendor landscape separates into three strategic archetypes: lighting-system conglomerates with horticulture divisions, irrigation-automation specialists with precision agriculture heritage, and aeroponic pure-plays with substrate-elimination IP. Dominant competitive moves include strategic partnerships between climate-control equipment vendors and LED manufacturers, plus geographic expansion into Gulf food-security megaprojects.
Among the lighting-system tier, Signify Holding anchors Dutch photon-efficacy benchmarks through its Philips Horticulture LED portfolio. NETAFIM exemplifies the irrigation-automation archetype with Israeli precision-dosing heritage. AeroFarms occupies a position within the aeroponic specialist tier, representing substrate-free cultivation protocols. These three entities collectively illustrate the geographic and technological diversification patterns visible across the competitive set.
| Leading Market Players |
|---|
| Signify Holding |
| NETAFIM |
| Scotts Company LLC |
| AeroFarms |
| Argus Control Systems |
| LumiGrow |
| Everlight Electronics |
| Richel Group |
| Gotham Greens |
| Others |
Value Chain & Pricing Dynamics
Captive LED chip fabrication in South Korea and Taiwan anchors photon efficacy leadership while compressing module procurement costs for Dutch and Japanese system integrators. This upstream control over spectral hardware translates directly into pricing power for climate-controlled grow system vendors serving EU Green Deal compliance mandates.
Pricing Analysis
Bundled full-system contracts dominate large-scale vertical farm procurement, while unbundled component sales persist among commercial greenhouse retrofits. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade spectral precision from commodity leafy green configurations. Cost compression in mid-tier LED arrays is intensifying because Chinese chip manufacturers are expanding 660nm red emitter capacity. Commercial growers in California's Salinas Valley exhibit highest price sensitivity due to thin agricultural margins, while Swiss pharmaceutical cultivators near Basel demonstrate lowest sensitivity given metabolite consistency requirements.
Supply Chain Analysis
Workforce availability constraints in Dutch horticultural engineering clusters and Japanese precision manufacturing corridors are extending equipment commissioning timelines for climate control system integrators. Component supply concentrates in China for aluminum substrate LED boards, Germany for CO2 transcritical cooling compressors, and Israel for precision nutrient dosing pumps. Raw material dependencies span gallium nitride wafers, rare-earth phosphors, and food-grade polymer tubing. Single-source vulnerability runs through Taiwanese 450nm blue emitter foundries. Distribution runs through direct OEM relationships with vertical farm developers rather than traditional agricultural equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Indoor Farming Technology Market functions as a regulatory compounder where EU F-Gas Regulation phase-out schedules and Japan METI subsidy windows create predictable demand stair-steps for climate control and LED replacement cycles.
For Market Incumbents: Hedge against refrigerant supply disruption by accelerating CO2 transcritical cooling partnerships with German compressor manufacturers ahead of EU F-Gas Regulation enforcement. Consolidate position in Japanese metropolitan corridors through METI-aligned financing structures that lower customer breakeven thresholds. Vertical integration into gallium nitride chip sourcing mitigates Taiwanese foundry concentration risk.
For New Entrants and Emerging Players: The EU Green Deal Farm to Fork Strategy in Netherlands and Germany opens a window for pesticide-free cultivation system vendors to capture commercial grower retrofit demand. White-space concentrates in pharmaceutical-grade herb contract cultivation serving Swissmedic-regulated nutraceutical extractors. Target UAE food security mandates through direct procurement relationships with Dubai hotel and catering operators specifying harvest-to-door logistics.
For Investors and Strategic Acquirers: Roll-up economics work for aeroponic pure-plays with substrate-elimination IP because customer acquisition costs fall dramatically once pharmaceutical contract cultivation credentials are established. Long-term viability centers on technology stacks demonstrating measurable metabolite consistency advantages over field agriculture. Signal to monitor: Swiss and Singapore biopharmaceutical cultivators expanding narrow-band photon delivery contracts beyond basil and camomile into higher-value active ingredient crops.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Cooling Retrofit | EU F-Gas Regulation compliance secures operational continuity for Dutch commercial installations. |
| Spectral-Tunable LED Platform Launch | Philips Horticulture LED benchmarks enable photomorphogenic optimization across lettuce and tomato cycles. |
| Pharmaceutical-Grade Contract Cultivation | Swissmedic standards exclude field agriculture from nutraceutical extraction supply chains near Basel. |
| Desert Heat Load System Integration | MOHAP food security mandates in Dubai accelerate climate-controlled domestic produce procurement timelines. |
| Aeroponic Root-Misting IP Acquisition | Substrate elimination protocols compress operating expenditure per harvest cycle for high-value herb segments. |
Study Parameters
Direct dialogue with vertical farm operations directors, greenhouse engineering consultants, LED procurement specialists, and pharmaceutical cultivation quality managers grounded qualitative findings in operational reality. Secondary validation drew from EU Green Deal implementation reports, METI Smart Agriculture subsidy disclosures, EPA agricultural runoff threshold documentation, and Swissmedic nutraceutical extraction standards. Bottom-up and top-down triangulation cross-checked facility-level capital expenditure patterns against national agricultural technology adoption forecasts.
Bottom-up modeling aggregated individual technology component demand across hydroponic, aeroponic, and aquaponic installations, while top-down analysis calibrated against national food security investment flows. Segmentation dimensions spanned substrate elimination technology, climate control integration depth, crop metabolite grade requirements, and facility scale tier. CAGRs derived from fitted adoption curves weighted by regulatory milestone timing and capital subsidy availability. Industry-specific inputs included LED photon efficacy improvement trajectories and transcritical cooling equipment replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy price volatility spikes or gallium nitride supply chain disruptions. Forecasts reflect documented assumptions regarding METI subsidy continuity and EU F-Gas Regulation enforcement pacing. Material deviation in Japanese land scarcity intensity or Swiss pharmaceutical contract cultivation expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Smart Indoor Gardening System Market