
 North America Indoor Farming Market | 2026-2036
North America Indoor Farming Market Size, Share, and Industry Trends Forecast 2026-2036
North America Indoor Farming Market Insights
Controlled-environment agriculture capacity across the United States and Canada is expanding as developers retrofit industrial warehouses and brownfield sites for vertical production. AeroFarms anchors its position through proprietary aeroponic stacking systems that maximize yield per square foot. Bowery Farming differentiates via fully integrated automation software that governs climate, irrigation, and spectral tuning. Plenty sustains competitive intensity through large-scale leafy green operations positioned near major metropolitan distribution nodes.
Indoor farming denotes the cultivation of crops within enclosed structures where artificial lighting, climate systems, and nutrient delivery replace dependence on ambient weather and soil conditions. LED arrays typically deliver photosynthetically active radiation at 400-700 nanometers while consuming substantially less energy than legacy high-pressure sodium fixtures, enabling year-round harvest cycles regardless of external seasonality. Hydroponics dominates installed production volume due to lower capital requirements and faster operational ramp, while aeroponics captures premium margin pools through superior water efficiency and accelerated growth rates. Automation technology is deepening its share of technology spending as labor costs climb and growers pursue batch-to-batch consistency.
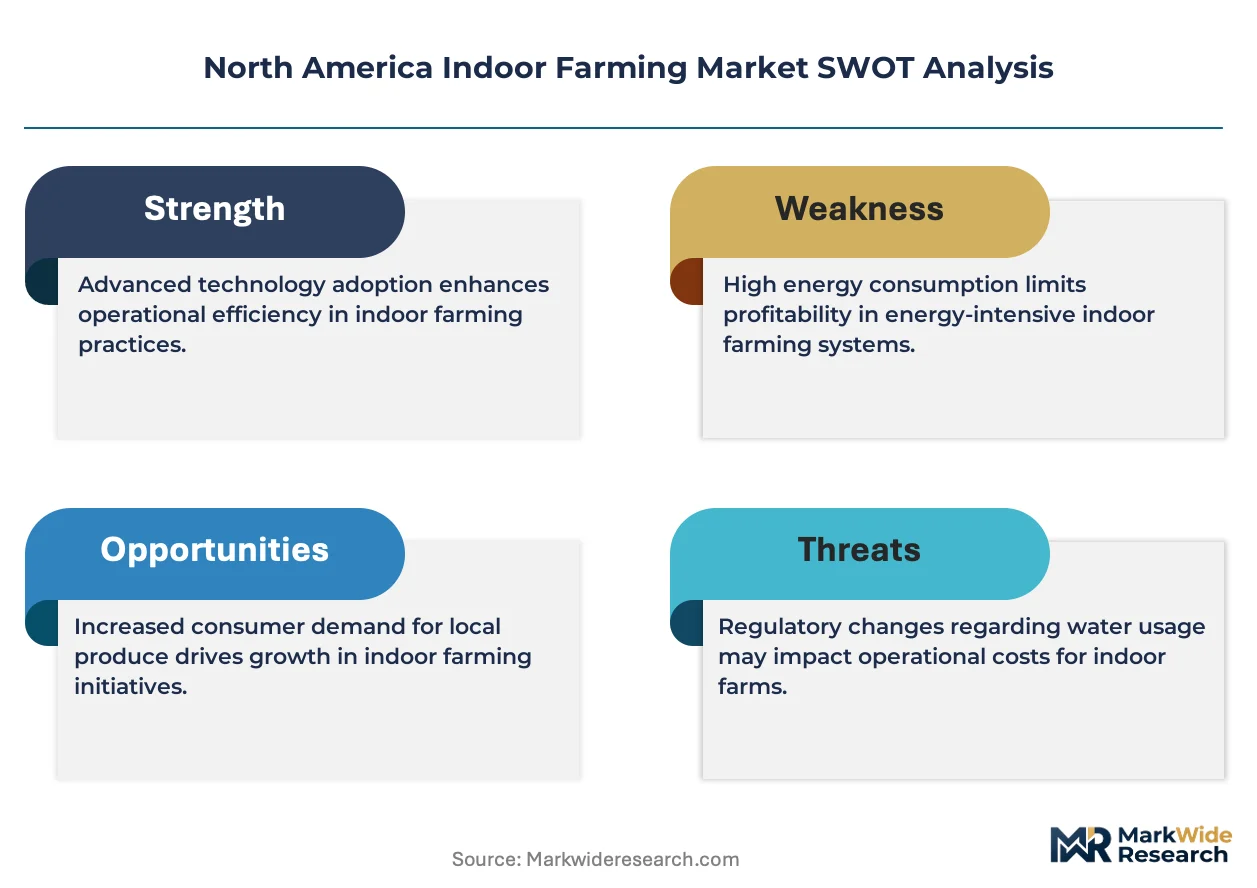
The EPA governs agricultural water discharge and pesticide application standards that directly shape nutrient solution management protocols in indoor facilities. FDA food safety modernization rules, alongside state-level cannabis and produce-specific frameworks in California and New York, create layered compliance obligations that favor operators with dedicated quality infrastructure. Stakeholders must weigh capital allocation between geographic expansion and technology stack upgrades as regulatory scrutiny intensifies and buyer specifications tighten.
Market Dynamics
Capital allocation in North American indoor farming is pivoting toward retrofitting existing industrial infrastructure rather than greenfield construction, as developers exploit brownfield tax incentives and proximity to urban distribution corridors.
Growth Catalysts
- USDA Organic Certification:Premium pricing tiers for certified produce are pulling institutional foodservice buyers toward verified indoor operations that can guarantee pesticide-free supply chains.
- LED Spectral Tuning:Advanced diode arrays delivering targeted photosynthetic wavelengths are compressing growth cycles and enabling cultivar-specific light recipes that field agriculture cannot replicate.
- California Water Stress:Persistent drought conditions in the Central Valley are accelerating migration of leafy green production into controlled environments where recirculating systems achieve 95% water efficiency.
Market Restraints
- Energy Cost Volatility:Electricity represents 25-30% of operating expenditure in vertical facilities, exposing margins to grid price spikes in Texas and Ontario deregulated markets.
- Input Concentration Risk:Specialized nutrient solution chemistry depends on concentrated phosphate and potassium suppliers concentrated in Saskatchewan and Florida mining corridors.
- Technical Yield Ceilings:Photosynthetic efficiency plateaus in stacked configurations limit the theoretical maximum biomass per cubic meter, constraining unit economics in high-rise developments.
Strategic Opportunities
- Great Lakes Urban Periphery:Detroit, Cleveland, and Milwaukee present underexploited warehouse conversion potential with direct rail access to Chicago and Toronto distribution nodes.
- Pharmaceutical-Grade Botanicals:Consistent cannabinoid and alkaloid profiles from controlled environments are attracting contract manufacturing interest from Health Canada-licensed processors.
- Inflation Reduction Act Credits:Clean energy production tax credits for on-site solar and geothermal installations are improving project IRRs for developers integrating renewable generation.
Industry Challenges
- Horticultural Engineering Talent Scarcity:The intersection of plant science, HVAC design, and automation programming lacks established training pipelines, forcing operators to poach from adjacent industries.
- FDA Food Safety Modernization Compliance:Preventive controls for human food rules impose documentation burdens and environmental monitoring protocols that legacy greenhouse operators struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Indoor Farming Market |
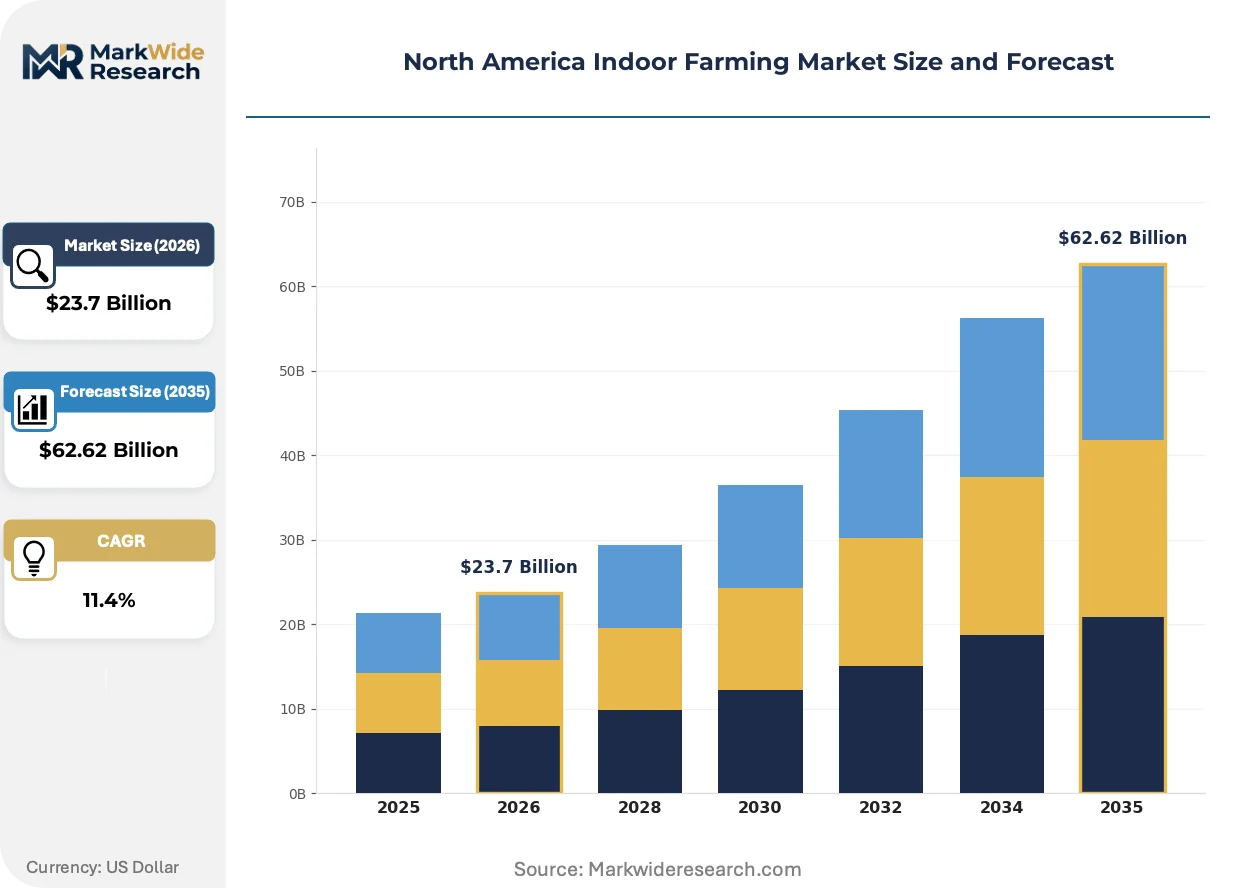
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponics, Aeroponics, Aquaponics, Soil-based Technology: LED Lighting, Climate Control, Sensors, Automation End User: Commercial Growers, Retail Outlets, Research Institutions, Home Users Application: Vegetables, Herbs, Fruits, Flowers |
| Companies Covered | AeroFarms, Bowery Farming, BrightFarms, Hydrofarm, Plenty, 80 Acres Farms, Freight Farms, Netafim, Green Sense Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Indoor Farming Market Trends and Innovations
Automation architectures are displacing labor-dependent cultivation workflows across North American facilities, compressing the gap between batch consistency targets and operational execution.
Spectral imaging systems paired with machine learning classifiers are rewriting quality assurance protocols in post-harvest operations. Large-format retailers including Kroger and Whole Foods Market are mandating computer-vision-verified defect detection for private-label produce contracts. This convergence is compressing rejection rates and enabling real-time harvest timing decisions that maximize shelf-life extension.
The EPA's evolving agricultural water discharge standards are tightening nutrient solution management requirements for facilities above threshold production volumes. Operators must now document zero-liquid-discharge compliance or secure municipal pretreatment agreements. California and New York state environmental agencies are enforcing these frameworks most aggressively, pushing mid-scale growers toward closed-loop irrigation retrofits.
Direct contracting between indoor operators and quick-service restaurant chains is displacing traditional produce distribution intermediaries. Chipotle and Sweetgreen are sourcing lettuce and herbs through multi-year offtake agreements with named cultivation facilities. This channel compression is most visible in the Northeast Corridor, where transportation cost advantages from Newark and Philadelphia metro facilities support daily just-in-time delivery schedules.
North America Indoor Farming Market Segmentation
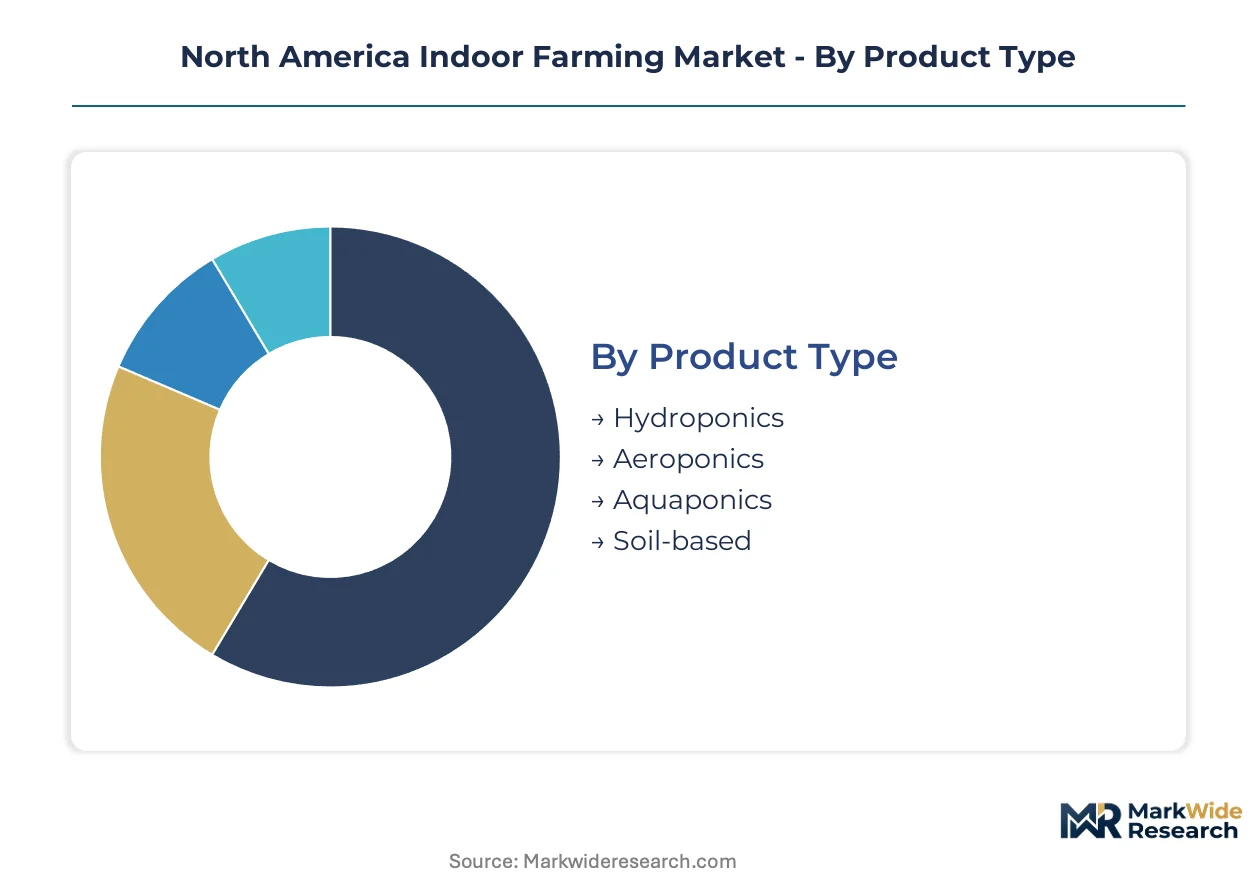
Technology choices in North American indoor farming lock in capital intensity and operating cost structures for decades. Segmentation reveals where volume production concentrates versus where premium margins accumulate.
Product Type:
Volume leadership sits with hydroponics, while aeroponics commands the steepest margin premiums.
- Hydroponics:Nutrient solution submerges plant roots in water-based media without soil, enabling faster crop cycles and simpler operational training. Commercial growers across California's Central Valley and the Great Lakes corridor favor this method for leafy green production at scale, driven by lower upfront capital requirements and established supply chains for equipment and consumables.
- Aeroponics:Mist-based nutrient delivery suspends roots in air, achieving superior water efficiency and accelerated biomass accumulation. Premium pricing from restaurant chains and institutional foodservice buyers pulls adoption near metropolitan distribution nodes, constrained by higher technical complexity and specialized maintenance demands.
- Aquaponics:Integrated fish cultivation generates organic nutrient inputs for plant growth, appealing to sustainability-certification-focused operators in the Northeast Corridor.
- Soil-based:Organic substrate cultivation meets USDA certification requirements for operations targeting premium retail channels in California and New York.
Today's leader: Hydroponics. Tomorrow's challenger: Aeroponics.
Technology:
Capital allocation tilts toward automation as labor costs climb, yet LED lighting absorbs the largest share of energy spending.
- LED Lighting:Spectrally tunable diode arrays deliver photosynthetically active radiation at 400-700 nanometers while consuming substantially less energy than legacy high-pressure sodium fixtures. California and Ontario facilities deploying advanced spectral recipes report compressed growth cycles for cultivar-specific production, though electricity remains 25-30% of operating expenditure.
- Automation:Robotics and integrated control systems govern climate, irrigation, and harvest timing with minimal human intervention. Large-format retailers mandating computer-vision-verified defect detection are pulling adoption across commercial operations, constrained by horticultural engineering talent scarcity at the intersection of plant science and software programming.
- Climate Control:HVAC and humidity management systems maintain optimal growing conditions regardless of external weather patterns.
- Sensors:IoT-enabled environmental monitoring enables real-time adjustments to nutrient delivery and atmospheric conditions.
Where capital concentrates: LED retrofits. Where margins expand: Automation integration.
End User:
Procurement concentration among commercial growers contrasts with fragmentation across home and research segments.
- Commercial Growers:Industrial-scale operators supply restaurant chains and retail distributors through multi-year offtake agreements. Chipotle and Sweetgreen direct contracting is displacing traditional produce distribution intermediaries, particularly in the Northeast Corridor where daily just-in-time delivery schedules leverage proximity advantages.
- Retail Outlets:Supermarket chains and specialty grocers operate captive cultivation facilities or source through named supplier relationships for private-label produce.
- Research Institutions:Universities and agricultural extension services deploy controlled environments for cultivar development and agronomic studies.
- Home Users:Consumer-grade systems target urban households seeking hyperlocal herb and vegetable production.
Volume anchors with commercial growers. Experimentation concentrates with research institutions.
Application:
Leafy vegetables generate baseline revenue while pharmaceutical-grade botanicals attract premium contract manufacturing interest.
- Vegetables:Lettuce, spinach, and brassica varieties dominate production volume due to short growth cycles and established buyer specifications. Persistent drought conditions in California's Central Valley are accelerating migration of field production into controlled environments where recirculating systems achieve 95% water efficiency.
- Herbs:Basil, cilantro, and specialty varieties command pricing premiums from restaurant chains seeking flavor consistency and extended shelf life. Daily just-in-time delivery schedules from Newark and Philadelphia metro facilities support freshness requirements.
- Fruits:Strawberry and tomato cultivation in controlled environments targets off-season premium pricing.
- Flowers:Ornamental and pharmaceutical-grade botanical production serves contract manufacturing interest from Health Canada-licensed processors.
Current revenue base: Vegetables. Steepest expansion trajectory: Herbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada pursues controlled-environment agriculture through federal grant programs and provincial energy incentives, while Mexico concentrates protected cultivation in high-altitude corridors serving North American export windows.
United States
California's Central Valley drought stress and Northeast Corridor restaurant chain procurement anchor domestic capacity expansion. The USDA administers organic certification requirements that shape pesticide-free production protocols. Newark and Philadelphia metro facilities execute daily just-in-time delivery schedules for Sweetgreen and Chipotle offtake agreements.
Canada
Health Canada-licensed cannabis processors generate contract manufacturing demand for pharmaceutical-grade botanical consistency. The federal government and Ontario province deploy clean energy production tax credits under the Inflation Reduction Act framework for on-site solar and geothermal installations. Toronto and Vancouver warehouse conversion projects exploit brownfield tax incentives and direct rail access to Chicago distribution nodes.
Mexico
High-altitude protected cultivation corridors in central Mexico target off-season premium pricing for strawberry and tomato exports to US markets. The national agricultural regulator enforces phytosanitary standards for cross-border produce shipments. Querétaro and Guanajuato states concentrate greenhouse infrastructure serving Texas and California distribution channels.
Great Lakes Urban Periphery
Detroit, Cleveland, and Milwaukee present underexploited warehouse conversion potential with direct rail access to Chicago and Toronto nodes. State-level water-use regulations in Michigan and Ohio tighten compliance thresholds for recirculating irrigation systems. Cleveland metropolitan facilities leverage proximity advantages for institutional foodservice procurement contracts.
North America Indoor Farming Market Competitive Landscape
United States producers anchor the technology-intensive tier; Canadian specialists hold positions in pharmaceutical-grade botanical segments. The vendor base organizes around three strategic archetypes: aeroponic stacking system developers, fully integrated automation software providers, and large-scale metropolitan-proximate operators. Competitive moves concentrate on brownfield warehouse retrofits and multi-year offtake agreement negotiations with restaurant chains.
Within the automation-integrated tier, Bowery Farming exemplifies control system consolidation, while Plenty occupies a position in large-scale leafy green production near distribution nodes. AeroFarms anchors the aeroponic specialization archetype. These three entities represent distinct capital allocation strategies between proprietary technology development and geographic expansion.
| Leading Market Players |
|---|
| AeroFarms |
| Bowery Farming |
| BrightFarms |
| Hydrofarm |
| Plenty |
| 80 Acres Farms |
| Freight Farms |
| Netafim |
| Green Sense Farms |
| Others |
Pricing and Supply Chain Analysis
USDA organic certification requirements gate both qualified supply and premium-tier pricing access for North American indoor farming operations, as restaurant chains and institutional foodservice buyers demand pesticide-free supply chains that only certified facilities can deliver. This regulatory filter concentrates pricing power among operators who have invested in quality infrastructure while squeezing uncertified competitors toward commodity tiers.
Pricing Analysis
Capacity additions in the Great Lakes urban periphery are reshaping price floors for leafy green commodities as Detroit and Cleveland warehouse conversions expand regional supply. Pricing stratifies across premium, standard, and economy tiers based on USDA organic certification status and proximity to metropolitan distribution nodes. Cost compression in the standard tier is intensifying because LED energy costs remain fixed at 25-30% of operating expenditure. Quick-service restaurant chains exhibit the least price sensitivity due to multi-year offtake agreements, while retail distributors face the most pressure from spot-market alternatives.
Supply Chain Analysis
Horticultural engineering talent scarcity in California and Ontario manufacturing corridors constrains equipment deployment timelines for automation-integrated facilities. Specialized nutrient solution chemistry draws from phosphate mining corridors in Saskatchewan and potassium suppliers concentrated in Florida. Single-source vulnerability runs through concentrated LED diode manufacturing in East Asian supply chains. Distribution runs through direct rail access to Chicago and Toronto nodes for Great Lakes facilities, with daily just-in-time delivery schedules displacing traditional produce distribution intermediaries in the Northeast Corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American indoor farming has entered a late-cycle quality phase where restaurant chain procurement specifications favor certified, traceable supply over volume scale. This demand shift toward premium specifications rewards operators with dedicated quality infrastructure and multi-year offtake relationships.
For Market Incumbents: Acquire brownfield warehouse assets in Detroit, Cleveland, and Milwaukee to secure proximity advantages before tax incentive windows narrow. Incumbent operators must also deepen backward integration into proprietary automation software stacks to defend against Bowery Farming's fully integrated control systems and the emerging entrant archetype of climate-tech venture-backed developers. Certification investment in USDA organic and state-level water-use compliance represents the priority lever for margin protection as regulatory scrutiny intensifies. For New Entrants and Emerging Players: Restaurant chain procurement managers represent the most accessible channel partner type for unproven operators seeking initial revenue traction. New entrants should target pharmaceutical-grade botanicals for Health Canada-licensed processors as the most penetrable application segment, where consistent cannabinoid profiles command premium contract manufacturing rates. A direct contracting go-to-market angle with quick-service chains in the Northeast Corridor bypasses entrenched distribution intermediaries and accelerates reference customer acquisition. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale aeroponic specialists because fragmented ownership across California's Central Valley and Great Lakes corridor prevents operational standardization at scale. Platform consolidation targeting facilities with existing USDA certification and municipal pretreatment agreements offers the clearest path to long-term viability across the five-to-ten year investment horizon. The signal to watch is Inflation Reduction Act credit utilization rates, as developers integrating on-site solar and geothermal installations demonstrate superior project IRRs that will attract follow-on capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Warehouse Acquisition | Detroit and Cleveland conversions exploit tax incentives and direct rail access to Chicago distribution nodes. |
| Proprietary Automation Development | Bowery Farming's integrated control systems demonstrate competitive moat through climate and irrigation governance. |
| USDA Organic Certification Investment | Certified facilities capture premium pricing tiers from Chipotle and Sweetgreen multi-year offtake agreements. |
| Direct Restaurant Chain Contracting | Channel compression displaces traditional produce intermediaries in Newark and Philadelphia metro facilities. |
| Renewable Generation Integration | On-site solar and geothermal installations improve project IRRs through Inflation Reduction Act production tax credits. |
Research Methodology
Direct dialogue with indoor farming facility operators, horticultural engineering consultants, restaurant chain procurement directors, LED equipment manufacturers, and regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EPA agricultural water discharge filings, FDA food safety modernization rule documentation, USDA organic certification databases, state-level environmental agency enforcement records, and brownfield tax incentive program disclosures. Bottom-up facility capacity estimates triangulated against top-down market size calculations to ensure convergence across independent analytical paths.
Bottom-up modeling tracked installed production volume by technology type and metropolitan distribution node, while top-down analysis assessed aggregate capital deployment patterns across the analysis window. Segmentation dimensions included cultivation method, automation integration level, end-user procurement channel, and crop application category. CAGRs were derived from fitted growth curves incorporating LED energy cost trajectories, regulatory compliance burden indices, and restaurant chain sourcing commitment velocities. Forecast inputs weighted California water stress severity and Inflation Reduction Act credit uptake rates as region-specific demand accelerants.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LED energy cost volatility, EPA nutrient discharge standard evolution, and quick-service restaurant chain bankruptcy cycles. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory enforcement intensity. Material deviation in drought persistence across California's Central Valley or wholesale electricity price spikes in Texas and Ontario deregulated markets warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Commercial Greenhouse Market