
 Hydroponic Substrate Market | 2026-2036
Hydroponic Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroponic Substrate Market Outlook
North American peat producers is repositioning supply chains toward coconut coir alternatives as sustainability pressures mount. ScottsMiracle-Gro leverages its retail distribution network to dominate home gardener channels. American Hydroponics anchors its position through specialized systems integration for commercial operations. Advanced Nutrients differentiates via nutrient-substrate bundling strategies that tighten grower loyalty.
Hydroponic substrate refers to the inert or semi-inert material that supports plant root systems in soilless cultivation, typically featuring porosity ratings between 70-95% and water-holding capacities calibrated to specific crop requirements. These materials provide physical anchorage, oxygen exchange, and moisture retention while enabling precise nutrient delivery in recirculating or drain-to-waste systems. Rockwool retains the largest installed base among commercial vegetable cultivation applications due to decades of proven performance in tomato and cucumber operations. Coconut coir captures the fastest expansion trajectory as growers seek renewable alternatives with comparable hydraulic properties to peat-based products. Mineral wool formulations maintain premium positioning in research institutions where protocol standardization and batch consistency justify elevated procurement budgets.
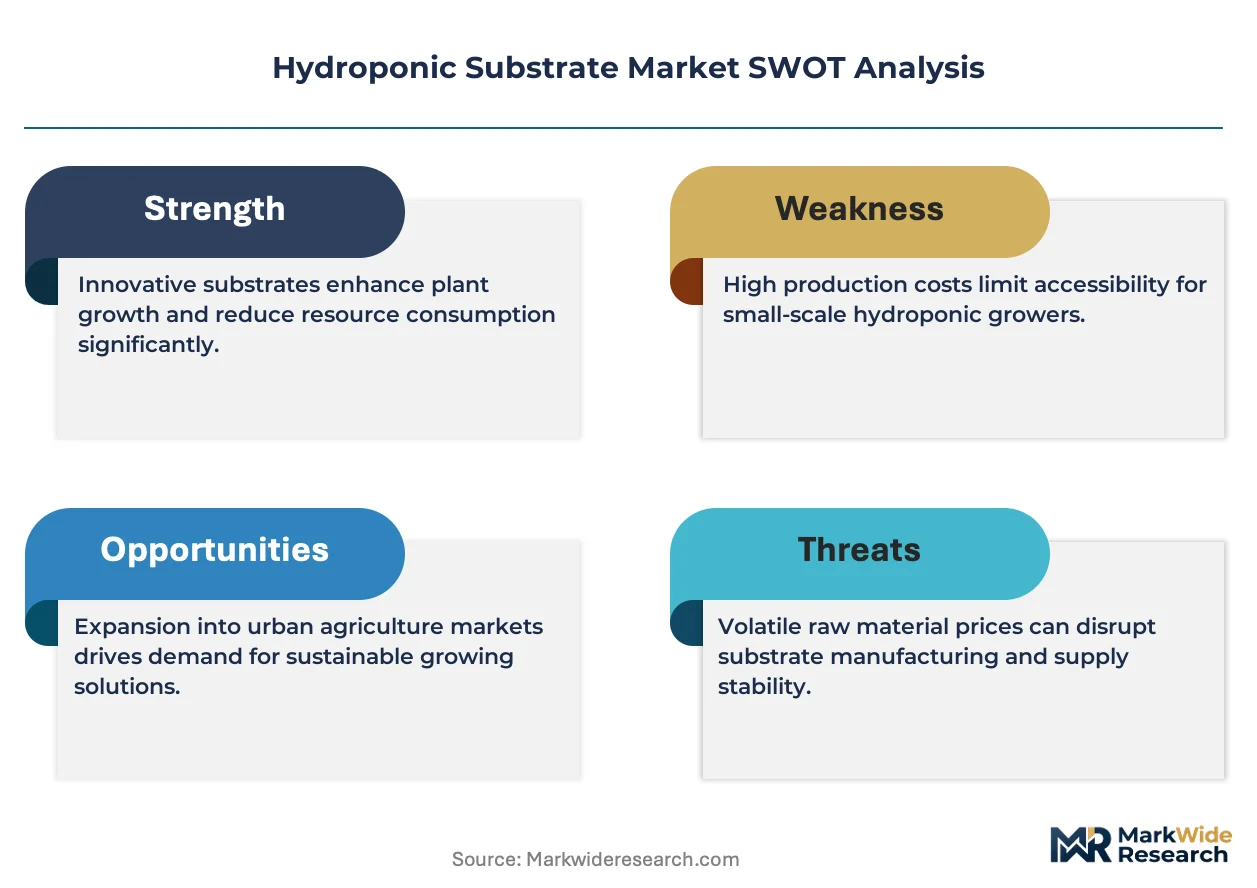
The EPA oversees water discharge compliance for large-scale hydroponic facilities under Clean Water Act provisions, while USDA organic certification standards determine substrate eligibility for certified crop production. State-level agricultural extension services in California and Florida issue supplemental guidelines on substrate sanitation protocols to mitigate pathogen transmission between growing cycles. Stakeholders must monitor evolving definitions of organic-compliant inputs and water recycling mandates as these frameworks increasingly determine market access and premium pricing eligibility.
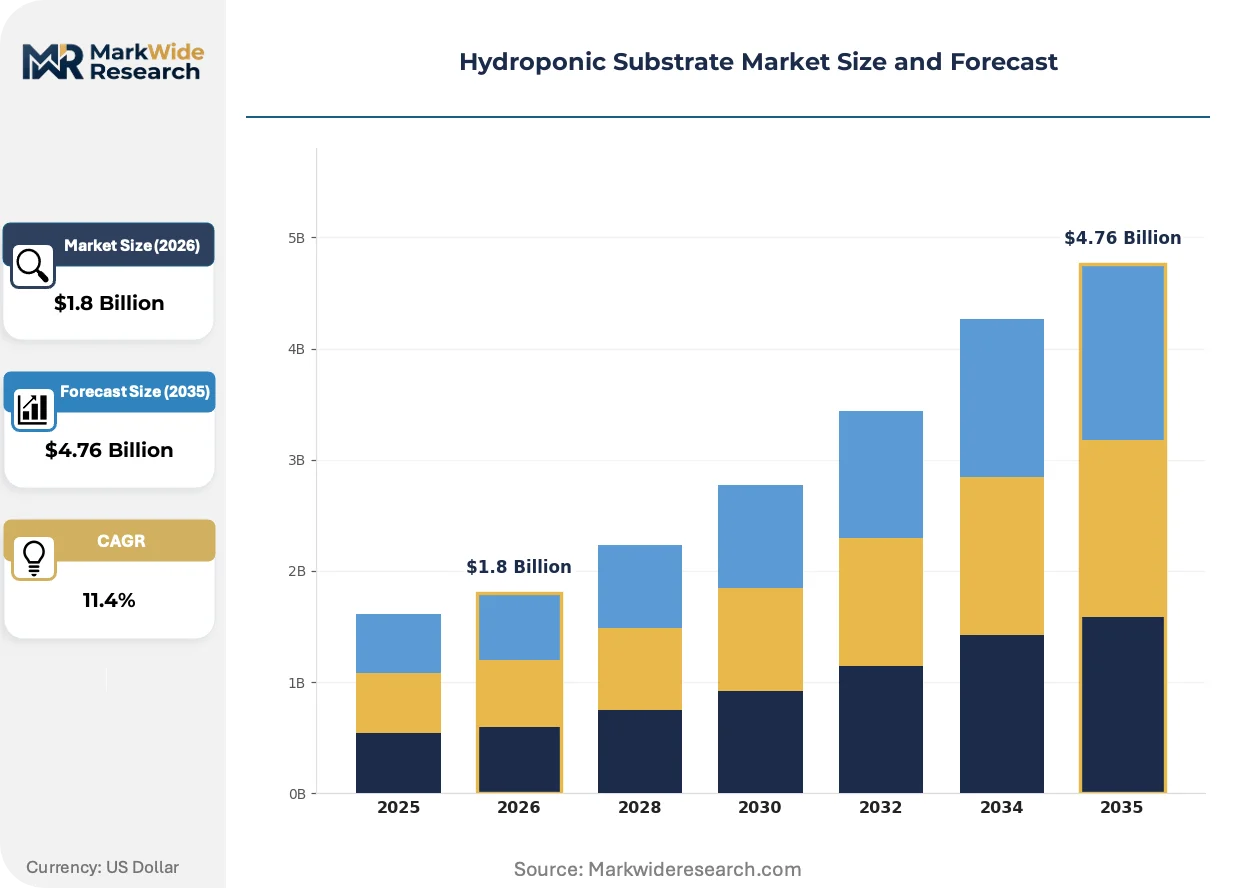
Market Dynamics
EU F-Gas Regulation mandates are compressing allowable synthetic inputs for soilless cultivation, forcing commercial greenhouse operators toward certified organic substrate alternatives with verified carbon footprints and renewable sourcing credentials.
Growth Catalysts
- Controlled-Environment Agriculture Expansion:Commercial greenhouse clusters in the Netherlands, Spain, and Canada are scaling tomato and cucumber production volumes, driving bulk substrate procurement contracts with multi-year supply agreements.
- EU Organic Certification Standards:Tightening eligibility criteria for soilless inputs under EU regulatory frameworks are redirecting grower procurement toward coconut coir and bio-based alternatives that satisfy premium crop labeling requirements.
- Water Recycling Mandates:Recirculating hydroponic systems in arid regions require substrates with calibrated drainage coefficients, creating specification demand for engineered mineral wool and precision-graded coir products.
Market Restraints
- Peat Supply Concentration:Baltic region extraction quotas and wetland preservation policies are constraining traditional peat availability, elevating input costs for manufacturers dependent on legacy formulations.
- Coconut Coir Logistics Friction:Sri Lankan and Indian subcontinent supply chains face container shipping volatility and quality inconsistency between fiber batches, complicating procurement planning for North American formulators.
- Rockwool Energy Intensity:Basalt melting processes carry elevated natural gas exposure, compressing margins when European energy benchmarks spike and limiting price competitiveness against lower-carbon alternatives.
Strategic Opportunities
- Australian CEA Clusters:Protected cropping expansion in New South Wales and Victoria offers first-mover positioning for substrate suppliers capable of meeting biosecurity import protocols and local organic certification requirements.
- Nutrient-Substrate Bundling:Integrated input packages combining calibrated growing media with crop-specific fertilizer regimes are tightening grower switching costs and capturing recurring revenue streams in commercial vegetable operations.
- Urban Vertical Farm Specifications:High-density indoor facilities in Singapore and the UAE require lightweight, stackable substrate formats with automated handling compatibility, opening premium pricing tiers for engineered foam and fiber composites.
Industry Challenges
- Substrate Sanitation Protocols:California and Florida agricultural extension services mandate pathogen elimination procedures between growing cycles, requiring capital investment in steam or chemical treatment infrastructure that smaller operators struggle to finance.
- Batch Consistency Certification:Research institutions and pharmaceutical-grade cultivators demand documented physical property uniformity across substrate lots, forcing manufacturers to implement quality control systems that extend lead times and inflate working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroponic Substrate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Coir, Rockwool, Perlite, Vermiculite Material: Natural Fiber, Mineral Wool, Foam, Clay Pellets End User: Commercial Growers, Greenhouses, Research Institutions, Home Gardeners Application: Vegetable Cultivation, Flower Production, Herbs Growth, Microgreens |
| Companies Covered | Emerald Harvest, American Hydroponics, ScottsMiracle-Gro, Gotham Greens, Nature’s Miracle, VitaLink, Hydrodynamics International, BrightFarms, Advanced Nutrients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroponic Substrate Market Strategic Shifts
Substrate engineering is pivoting from commodity bulk supply toward precision-formulated crop-specific solutions, with automation compatibility and carbon accounting emerging as decisive specification criteria in commercial procurement.
Containerized substrate production systems are modularizing regional supply chains by enabling localized fiber processing and blending operations near major greenhouse clusters. Dutch equipment manufacturers are deploying compact coir retting and compression units in Spain and Mexico, cutting ocean freight exposure and customs delay risk. This distributed manufacturing architecture is compressing the traditional Asia-Europe-North America supply triangle into hub-and-spoke regional networks with faster inventory turns.
EU F-Gas Regulation phase-down schedules are eliminating synthetic rooting media derived from fluorinated compounds, redirecting R&D investment toward bio-based binding agents and natural fiber composites. German and Dutch formulators are accelerating peat-free substrate development to preempt 2030 organic certification deadlines. Commercial tomato operations in Almeria and Westland are piloting certified alternatives to maintain premium retail channel access under tightening supermarket sustainability procurement rules.
Direct contracting between substrate manufacturers and large greenhouse cooperatives is displacing distributor-mediated procurement in high-volume vegetable production. Dutch grower associations in Westland and Aalsmeer are negotiating multi-year supply agreements with fixed-price escalators, transferring inventory risk upstream while securing specification continuity. This channel consolidation is most visible in the Benelux region, where three purchasing cooperatives now control the majority of rockwool and coir volume for protected cropping.
Hydroponic Substrate Market Segmentation
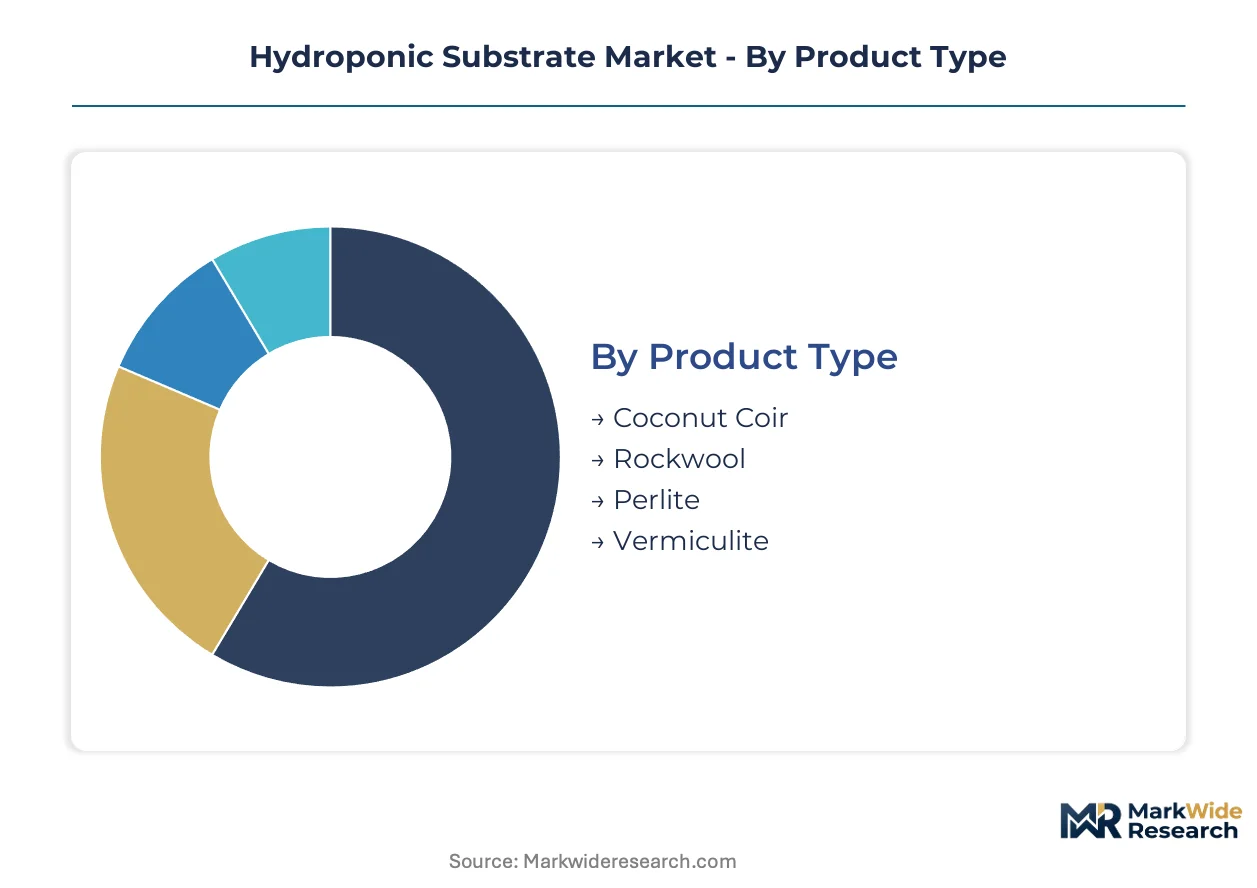
Substrate selection in hydroponic systems determines oxygen diffusion rates, water retention profiles, and nutrient buffering capacity. Procurement patterns diverge sharply between commodity bulk buyers and precision agriculture operators seeking batch-certified inputs. Specification requirements intensify as EU organic certification and water recycling mandates reshape allowable material categories.
Product Type:
Replacement cycles accelerate where sustainability pressures render legacy substrates non-compliant with tightening certification standards.
- Coconut Coir:Processed coconut husk fiber delivers 70-85% porosity with superior rewetting capacity compared to peat alternatives. Demand concentrates in Dutch and Spanish greenhouse clusters where EU organic certification requirements are displacing synthetic rooting media. Container shipping volatility from Sri Lankan processing centers creates procurement friction for North American formulators.
- Rockwool:Spun basalt mineral wool maintains the largest installed base in commercial tomato and cucumber operations due to decades of proven hydraulic performance. Almeria and Westland greenhouse cooperatives specify rockwool for its drainage coefficient consistency in recirculating systems. Natural gas exposure in melting processes compresses margins when European energy benchmarks spike.
- Perlite:Expanded volcanic glass provides lightweight aeration in propagation trays and seedling substrates. Florida and California vegetable nurseries specify coarse grades for drainage layers.
- Vermiculite:Hydrated laminar magnesium-aluminum-iron silicate delivers cation exchange capacity for nutrient retention. Research institutions favor fine grades for laboratory protocol standardization.
Volume placements concentrate in rockwool; the faster expansion belongs to coconut coir.
Material:
Cost tier differentiation separates premium-certified inputs from commodity bulk supply in procurement specifications.
- Natural Fiber:Coconut coir and jute composites command premium positioning where renewable sourcing credentials satisfy supermarket sustainability procurement rules. Dutch equipment manufacturers are deploying modular retting units in Mexico and Spain to regionalize supply chains.
- Mineral Wool:Basalt and slag wool formulations dominate research institution procurement where batch consistency documentation justifies elevated procurement budgets. German formulators are accelerating peat-free development to preempt organic certification deadlines.
- Foam:Phenolic and polyurethane foams serve high-density vertical farms in Singapore and the UAE requiring lightweight, stackable formats with automated handling compatibility.
- Clay Pellets:Expanded shale provides reusable drainage media in ebb-and-flow systems. Australian protected cropping expansion in New South Wales drives import demand for certified biosecurity-compliant shipments.
Natural fiber captures the steepest expansion trajectory; mineral wool retains the deepest revenue concentration.
End User:
Application maturity separates established commercial operations from emerging home gardener channels in specification complexity.
- Commercial Growers:Large-scale greenhouse cooperatives in the Netherlands negotiate multi-year supply agreements with fixed-price escalators, transferring inventory risk upstream. Direct contracting displaces distributor-mediated procurement in high-volume vegetable production.
- Greenhouses:Controlled-environment agriculture clusters across Canada and Australia require substrates with calibrated drainage coefficients for recirculating systems. California and Florida extension services mandate pathogen elimination protocols between growing cycles.
- Research Institutions:Pharmaceutical-grade cultivators and agricultural universities demand documented physical property uniformity across substrate lots. Quality control systems extend lead times and inflate working capital requirements for manufacturers.
- Home Gardeners:Retail distribution networks dominate this channel, with compressed substrate bricks and pre-blended grow bags capturing convenience premiums. Specification complexity remains minimal compared to commercial procurement.
Greenhouse placements dominate volume; research institutions command the highest per-unit pricing.
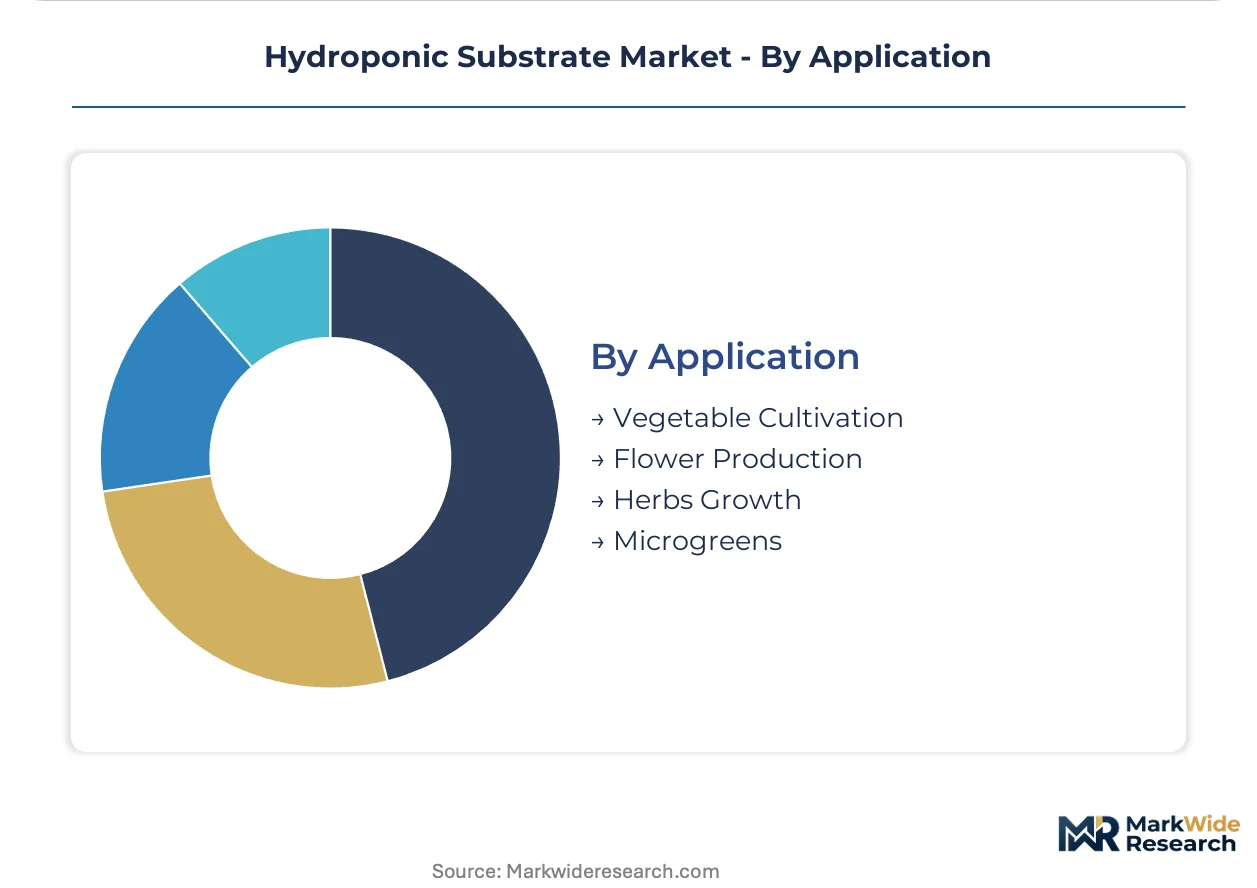
Application:
Customer type segmentation separates commodity vegetable production from premium flower and herb categories in margin structure.
- Vegetable Cultivation:Tomato and cucumber operations in Almeria and Westland anchor bulk substrate demand with standardized rockwool slab and coconut coir grow bag specifications. Supermarket sustainability procurement rules are redirecting volumes toward certified organic alternatives.
- Flower Production:Orchid and rose greenhouse operators in Aalsmeer specify precision-graded substrates with pH buffering capacity tailored to acid-loving species. Premium retail channel access depends on input traceability documentation.
- Herbs Growth:Basil and leafy green producers favor coconut coir for its rewetting properties in high-frequency irrigation regimes. Urban vertical farms in the UAE specify lightweight formats for stacked production towers.
- Microgreens:Rapid-turnover propagation requires thin substrate mats with fine fiber structure for root anchorage in 7-14 day harvest cycles. Research institutions pilot hemp and jute fiber alternatives to peat-based products.
Vegetable cultivation holds the largest volume footprint; microgreens demonstrate the most rapid specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sri Lankan coconut husk processing centers and Dutch basalt melting facilities anchor the hydroponic substrate supply geography, with demand clustering in greenhouse corridors across the Netherlands, Spain, Canada, and Australia.
Netherlands
Westland and Aalsmeer greenhouse cooperatives drive bulk procurement of rockwool slabs and coconut coir grow bags for tomato and cucumber operations. The EU F-Gas Regulation is compressing allowable synthetic inputs, redirecting volumes toward certified organic alternatives. Dutch equipment manufacturers are deploying modular coir retting units in regional hub-and-spoke networks.
Spain
Almeria's protected cropping expansion anchors Mediterranean demand for substrates with calibrated drainage coefficients in recirculating systems. National organic certification standards under EU frameworks are tightening eligibility criteria for soilless inputs. Commercial tomato operations are piloting peat-free alternatives to maintain premium retail channel access under supermarket sustainability procurement rules.
Canada
Controlled-environment agriculture clusters in Ontario and British Columbia are scaling vegetable production volumes, driving multi-year substrate supply agreements. Health Canada and PMRA oversight determines input eligibility for certified crop production. British Columbia's agricultural extension services issue supplemental guidelines on substrate sanitation protocols to mitigate pathogen transmission.
Australia
Protected cropping expansion in New South Wales and Victoria offers first-mover positioning for suppliers meeting biosecurity import protocols. The country's national agricultural regulator enforces strict quarantine requirements on coconut coir shipments from Sri Lankan processing centers. Sydney and Melbourne metro areas are emerging as high-density vertical farm specification demand centers.
United States
California and Florida extension services mandate pathogen elimination procedures between growing cycles, requiring capital investment in steam treatment infrastructure. The EPA oversees water discharge compliance for large-scale hydroponic facilities under Clean Water Act provisions. Central Valley greenhouse operators and Miami-Dade ornamental producers concentrate procurement demand for engineered mineral wool and precision-graded coir products.
Hydroponic Substrate Market Competitive Environment
Global majors compete with regional champions across substrate formulation and distribution reach, creating a tiered structure where scale-driven manufacturers face specialized systems integrators. Consolidation concentrates around multi-input bundling strategies and direct contracting with large greenhouse cooperatives. Three archetypes dominate: retail-channel mass marketers, commercial systems specialists, and nutrient-substrate bundlers. Competitive moves center on backward integration into fiber processing and geographic expansion through modular production units.
Among North American mass-market suppliers, ScottsMiracle-Gro occupies a position exemplifying retail distribution dominance, while American Hydroponics anchors the commercial systems integration tier. Advanced Nutrients represents the nutrient-substrate bundling archetype, tightening grower switching costs through integrated input packages.
| Leading Market Players |
|---|
| Emerald Harvest |
| American Hydroponics |
| ScottsMiracle-Gro |
| Gotham Greens |
| Nature's Miracle |
| VitaLink |
| Hydrodynamics International |
| BrightFarms |
| Advanced Nutrients |
| Others |
Value Chain & Pricing Dynamics
Dutch greenhouse cooperatives in Westland and Aalsmeer anchor procurement volume, concentrating buyer power and forcing contract-based long-term offtake agreements with fixed-price escalators that transfer inventory risk upstream to substrate manufacturers.
Pricing Analysis
Service-bundling separates certified organic substrate packages with technical support from unbundled commodity bulk supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EU organic compliance commanding substantial premiums. Price erosion runs through standard-grade rockwool as energy cost volatility compresses basalt melting margins. Home gardener retail channels exhibit highest price sensitivity, while research institutions demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Valencia, and Vancouver anchor hub-and-spoke networks that compress ocean freight exposure. Raw material sourcing draws from Sri Lankan coconut husk processing, German basalt mining, and Canadian peatlands. Container shipping volatility from South Asian fiber processors creates single-source vulnerability for North American formulators. Distribution runs through direct contracting with greenhouse cooperatives, displacing traditional distributor-mediated procurement in high-volume vegetable production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate manufacturers face a vertical-integration race as backward integration into fiber processing and captive coir retting operations emerge as decisive margin levers.
For Market Incumbents: Cement market position through multi-year supply agreements with fixed-price escalators that lock in Dutch and Spanish greenhouse cooperatives. Invest in modular coir retting units in Mexico and Spain to preempt logistics friction from Sri Lankan supply chains. Certification investment in EU organic compliance standards represents the critical defensive lever against peat-free substitution threats. For New Entrants and Emerging Players: The premium-economy price gap in Australian protected cropping offers white-space positioning for suppliers meeting biosecurity import protocols. Target New South Wales and Victoria greenhouse clusters with certified organic alternatives to rockwool. Direct contracting with grower associations bypasses entrenched distributor networks in this underdeveloped procurement landscape. For Investors and Strategic Acquirers: The window for entry favors regional coir processing specialists with captive fiber supply and modular production architecture. Long-term viability hinges on organic certification compliance and carbon accounting transparency. Watch EU F-Gas Regulation phase-down schedules as the inflection signal accelerating peat-free substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Processing | Captive coconut coir supply from Sri Lankan retting operations insulates against container shipping volatility. |
| Modular Regional Production Deployment | Compact coir compression units in Spain and Mexico compress lead times for Almeria greenhouse clusters. |
| Organic Certification Investment | EU F-Gas Regulation compliance unlocks premium retail channel access for Dutch tomato operations. |
| Nutrient-Substrate Bundling | Integrated input packages tighten grower switching costs in commercial vegetable production. |
| Direct Contracting with Grower Cooperatives | Multi-year supply agreements with Westland associations transfer inventory risk upstream. |
Study Parameters
Trade databases, EU regulatory filings, and agricultural extension service guidelines formed the secondary backbone, supplemented by primary interviews with greenhouse operations managers, substrate procurement leads at Dutch cooperatives, coconut coir processing technicians, and agricultural extension specialists. Bottom-up and top-down triangulation validated volume estimates across rockwool, coconut coir, and perlite product categories.
Bottom-up modeling anchored projections in greenhouse expansion pipelines and substrate replacement cycles, while top-down analysis cross-checked against controlled-environment agriculture investment flows. Segmentation dimensions included product type, material composition, end-user archetype, and application category. CAGRs derived from fitted growth curves reflecting regulatory phase-down schedules and organic certification adoption patterns.
Inputs from greenhouse cooperatives and fiber processors were available through the study window; gaps in real-time shipping cost data introduce uncertainty bands around procurement friction estimates. Forecasts reflect documented assumptions on energy price trajectories and regulatory enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
United States Plant Growth Chambers Market