
 Vertical Farming Market | 2026-2036
Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Farming Market Analysis
Fresh produce procurement by supermarket chains is shifting toward controlled-environment agriculture as retailers seek year-round supply consistency. AeroFarms leverages aeroponic technology leadership to anchor premium leafy green contracts with Northeast US grocers. Plenty Unlimited Inc. sustains its position through large-scale automated facilities in California. Freight Farms competes via modular container systems that occupy urban edge locations near demand clusters.
Vertical farming deploys stacked cultivation layers in climate-controlled indoor environments, typically utilizing hydroponic or aeroponic nutrient delivery systems with LED spectral tuning to optimize photosynthetic photon flux density between 200 and 400 µmol/m²/s for leafy biomass accumulation. The primary commercial purpose is to decouple fresh produce supply from seasonal variation, arable land constraints, and long-haul logistics. Hydroponics leads installed capacity due to lower technical complexity and established operator expertise, while aeroponics captures margin pools through water-use efficiency and accelerated crop cycles. LED lighting dominates technology expenditure as spectral programmability becomes the primary yield determinant, and climate control systems extend growing season economics into previously non-viable geographies.
The EPA regulates agricultural water discharge and pesticide applications that vertical farms bypass entirely, while the FDA's Food Safety Modernization Act imposes preventive controls that indoor operations satisfy through closed-loop environmental monitoring. OSHA standards for confined-space agriculture worker safety shape facility design requirements in US installations. Stakeholders must monitor how evolving produce safety certifications and municipal zoning for urban agriculture interact with capital deployment timelines.
Market Dynamics
LED spectral tuning and climate control automation are compressing crop cycle economics while the EU Green Deal's farm-to-fork targets restructure supermarket procurement toward controlled-environment agriculture.
Growth Catalysts
- EU Green Deal farm-to-fork targets:The regulation tightens conventional agriculture economics across member states, redirecting fresh produce procurement toward controlled-environment suppliers.
- Arid climate food security pressures:The United Arab Emirates accelerates indoor farming deployment as import dependence and water scarcity intensify sovereign supply concerns.
- Aeroponic water-use efficiency:This cultivation method captures margin pools through reduced resource consumption and accelerated biomass accumulation cycles.
Market Restraints
- LED lighting capital intensity:Spectral programmability hardware dominates facility technology expenditure, stretching payback periods for new entrants.
- Specialized agronomy talent scarcity:Confined-space agriculture requires cross-disciplinary expertise in controlled-environment systems, constraining operational scaling.
- Conventional field agriculture substitution:Open-field production maintains cost advantages for commodity crops, limiting vertical farming to premium perishables.
Strategic Opportunities
- Urban edge modular deployment:Container-based systems occupy proximate locations near demand clusters, compressing last-mile logistics costs.
- Supermarket chain direct contracting:Retailers seek year-round supply consistency, creating captive offtake arrangements with technology-differentiated operators.
- OSHA confined-space safety compliance:Evolving worker protection standards for indoor agriculture shape facility design specifications, favoring purpose-built automated installations.
Industry Challenges
- Photosynthetic photon flux density optimization:Precise LED calibration between 200 and 400 µmol/m²/s demands specialized photobiology expertise scarce in conventional horticulture.
- FDA Food Safety Modernization Act preventive controls:Closed-loop environmental monitoring systems must satisfy documentation burdens that extend commissioning timelines.
- Municipal zoning friction:Urban agriculture land-use classifications interact unpredictably with capital deployment schedules across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Farming Market |
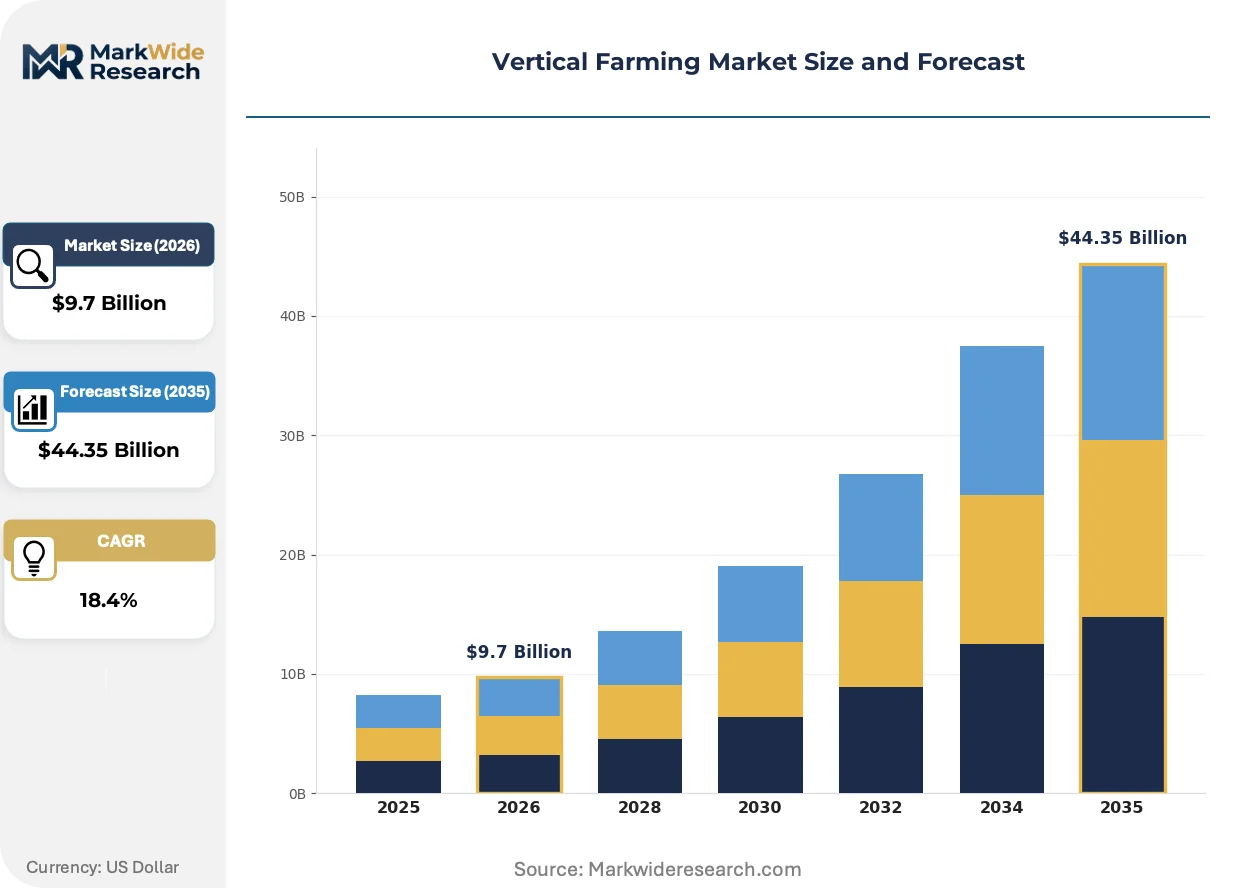
| Market Size in 2026 | $9.7 Billion |
| Market Size in 2035 | $44.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponics, Aeroponics, Aquaponics, Soil-based Technology: LED Lighting, Climate Control, Sensors, Automation End User: Restaurants, Retailers, Wholesalers, Households Application: Leafy Greens, Herbs, Berries, Microgreens |
| Companies Covered | AeroFarms, Plenty Unlimited Inc., Freight Farms, Bowery Farming, Signify Holding, BrightFarms, 80 Acres Farms, Eden Green Technology, Heliospectra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Farming Market Emerging Trajectories
Spectral programmability and automation architectures are compressing the technical barriers between pilot-scale facilities and commercial viability, while regulatory frameworks restructure competitive positioning around certification and traceability.
Container-based cultivation architecture is modularizing deployment patterns for vertical farming infrastructure. Urban grocers and institutional foodservice operators are adopting these systems to establish hyperlocal supply nodes. This modularity is compressing facility commissioning timelines from years to months while reducing geographic constraints on site selection.
The EU Green Deal's sustainability mandates are tightening disclosure requirements for agricultural supply chains. Retailers must document carbon intensity and water stewardship across procurement portfolios. Leafy green categories in Northern European markets face the steepest compliance burdens, accelerating buyer migration toward verifiable controlled-environment sources.
Direct contracting between supermarket chains and vertical farm operators is displacing traditional wholesale distribution channels. Retailers consolidate supplier relationships to secure volume commitments and traceability documentation. This consolidation is most visible in Northeast US metropolitan corridors where year-round supply consistency commands procurement priority.
Vertical Farming Market Segmentation
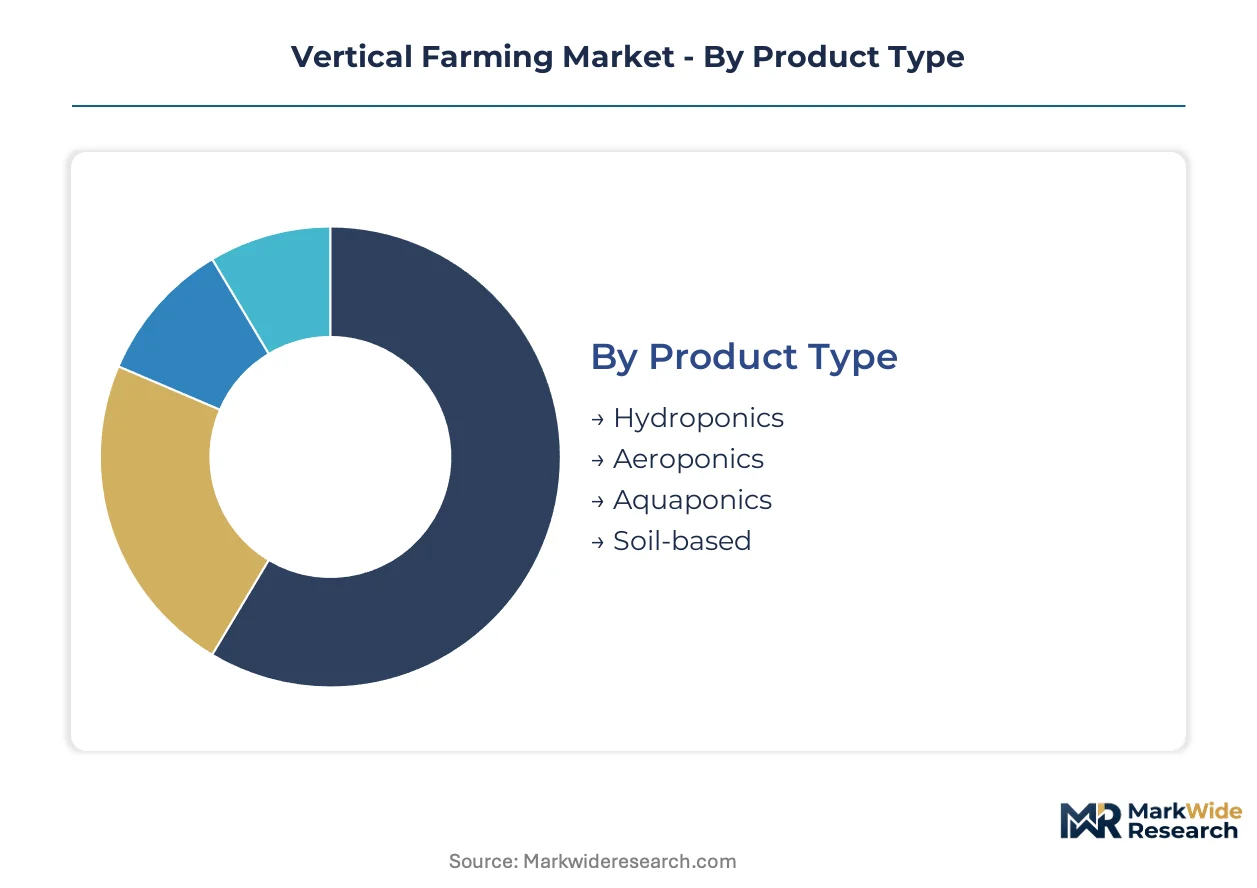
Vertical farming's commercial structure fragments across cultivation methods, technology stacks, buyer types, and crop categories. Each segmentation axis carries distinct margin profiles and capital intensity requirements that shape operator positioning.
Product Type:
Cost tier differentiation separates commodity operators from premium positioning in cultivation system selection.
- Hydroponics:Nutrient film technique and deep water culture systems dominate installed base through lower technical complexity and established agronomic protocols. Volume concentrates in North American and European greenhouse conversions where operator expertise transfers readily from conventional horticulture; water-use efficiency satisfies tightening discharge regulations without aeroponic infrastructure investment.
- Aeroponics:Mist-based root zone delivery achieves 95% water reduction versus field agriculture and compresses leafy green crop cycles by 30-40%. Demand clusters in the United Arab Emirates and Singapore where sovereign food security programs absorb capital intensity in exchange for import substitution; premium pricing captures margin pools unavailable to hydroponic competitors.
- Aquaponics:Integrated fish-produce systems occupy niche educational and research installations with limited commercial scaling.
- Soil-based:Organic certification pathway systems serve premium retail channels requiring substrate-based cultivation documentation.
Volume sits with Hydroponics; growth tilts toward Aeroponics.
Technology:
Application criticality determines technology expenditure sequencing in facility buildouts.
- LED Lighting:Spectral programmability between 200-400 µmol/m²/s photosynthetic photon flux density governs yield consistency and biomass accumulation rates. Demand concentrates in retrofit installations and new facilities across California, the Netherlands, and Japan where electricity costs justify premium diode efficiency; spectral tuning expertise constrains operator scaling.
- Climate Control:HVAC and dehumidification systems extend growing season economics into non-viable geographies. Procurement concentrates in Middle Eastern and Northern European deployments where external climate-hostility creates captive demand; integration with building automation systems compresses operational labor intensity.
- Sensors:Environmental monitoring arrays satisfy FDA Food Safety Modernization Act documentation burdens.
- Automation:Robotic transplanting and harvesting systems reduce confined-space agriculture labor exposure.
Capital deployment prioritizes LED Lighting; technology integration margins expand fastest in Climate Control.
End User:
Customer type dictates contract structure, volume commitment, and traceability documentation intensity.
- Retailers:Supermarket chains consolidate supplier relationships to secure year-round supply consistency and EU Green Deal-compliant carbon disclosure. Direct contracting concentrates in Northeast US metropolitan corridors and Northern European markets where procurement officers prioritize traceability documentation over spot-market pricing.
- Restaurants:Fine-dining and fast-casual chains adopt hyperlocal supply for menu differentiation and freshness signaling. Demand clusters in urban core locations where last-mile logistics compression justifies premium sourcing; contract volumes remain below retail scale but tolerate higher per-unit pricing.
- Wholesalers:Traditional distribution channels face displacement as retailer-direct contracting accelerates.
- Households:Consumer-scale systems occupy hobbyist and education segments with limited commercial relevance.
Contract value concentrates with Retailers; margin expansion tilts toward Restaurants.
Application:
Volume scale and harvest frequency separate commercially viable categories from pilot-scale experimentation.
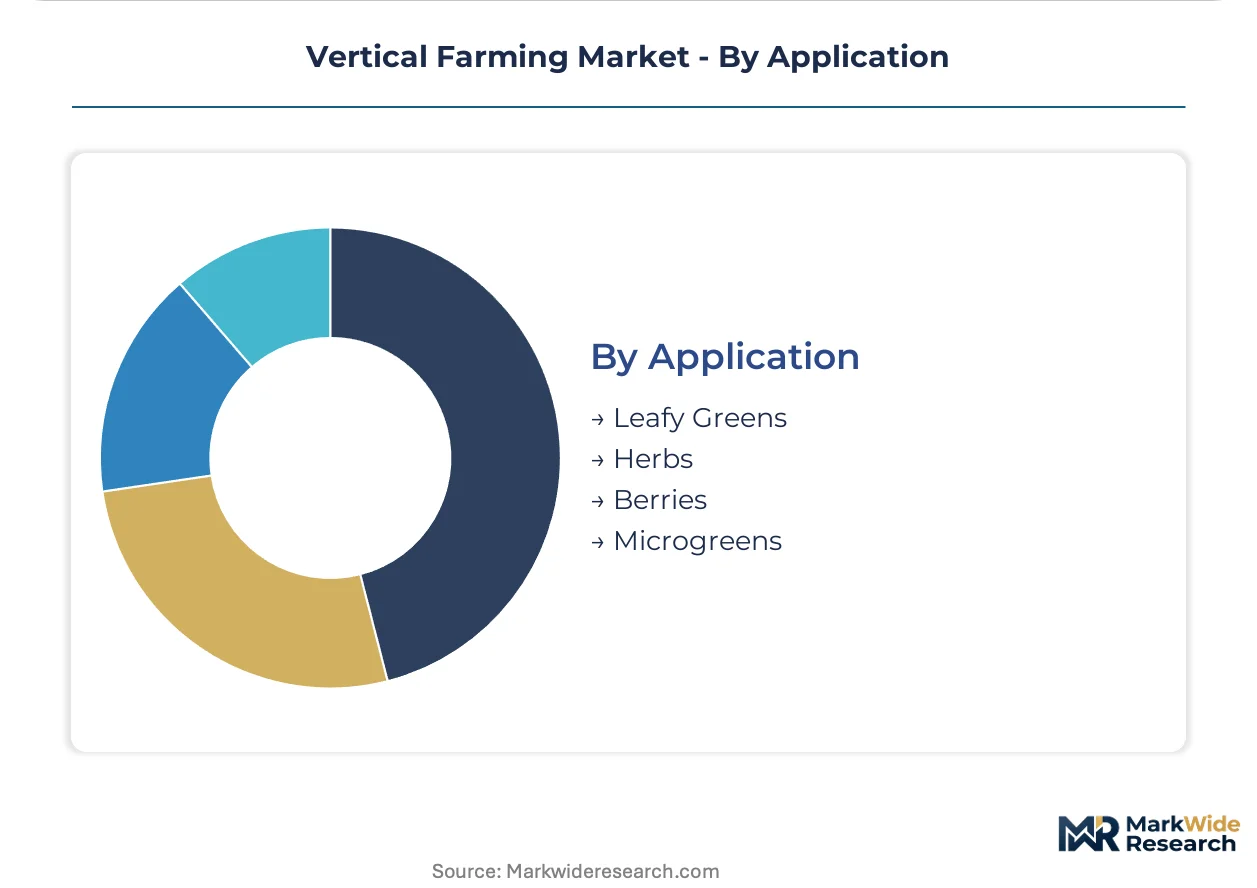
- Leafy Greens:Lettuce, spinach, and kale categories dominate revenue through rapid crop cycles, standardized harvesting protocols, and established consumer acceptance. Production concentrates in automated facilities serving Northeast US and Northern European retail chains where year-round availability commands procurement priority; unit economics support facility-level returns.
- Herbs:Basil, cilantro, and parsley command premium pricing in foodservice channels through flavor intensity advantages over field-grown alternatives. Demand clusters in urban restaurant supply networks where freshness differentiation supports 2-3x field pricing; smaller harvest volumes limit facility-scale deployment.
- Berries:Strawberry and raspberry cultivation remains technically challenging with extended crop cycles constraining capital turnover.
- Microgreens:High-value niche serves chef-direct and specialty retail with limited volume scaling.
Revenue concentration rests with Leafy Greens; pricing power expands fastest in Herbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in temperate zones with established horticulture infrastructure, while consumption demand clusters in water-stressed import-dependent markets where sovereign food security programs justify capital-intensive controlled-environment deployment.
United States
Northeast metropolitan corridors generate captive demand from supermarket chains seeking year-round leafy green supply consistency. The FDA's Food Safety Modernization Act imposes preventive controls that indoor operations satisfy through closed-loop environmental monitoring. Greater Boston and New York Metro anchor automated facility deployment serving retail direct-contracting procurement officers.
United Arab Emirates
Arid climate and food import dependence exceeding 85% accelerate sovereign investment in controlled-environment agriculture. MOHAP food safety standards align with international certification requirements for premium produce export positioning. Dubai and Abu Dhabi concentrate aeroponic facility construction targeting import substitution and re-export hub status.
Netherlands
Established greenhouse horticulture expertise transfers readily to vertical farming system integration and LED spectral tuning optimization. The EU Green Deal's farm-to-fork sustainability targets tighten conventional agriculture economics across member states. Westland municipality and Eindhoven Region host technology development clusters serving Northern European retail compliance migration.
Singapore
Land scarcity and 90% food import dependence drive sovereign funding for urban agriculture capacity expansion. The national food agency's licensing framework prioritizes traceability documentation and environmental monitoring system validation. Lim Chu Kang and Sengkang anchor vertical farm clusters supplying hyperlocal retail and foodservice networks.
Japan
Declining agricultural workforce and extreme weather vulnerability concentrate policy support for automated indoor cultivation. METI energy efficiency standards shape LED lighting procurement specifications for facility operators. Chubu region around Nagoya hosts plant factory clusters serving precision supply contracts with convenience retail chains.
Vertical Farming Market Vendor Landscape
Top-tier vendors anchor technology-differentiated premium contracting, while modular system specialists occupy urban edge deployment niches. The vendor base stratifies across integrated facility operators, equipment technology suppliers, and container-based system fabricators. Archetypes include aeroponic yield optimizers, hydroponic scale operators, and spectral hardware specialists. Competitive moves concentrate on direct retail contracting consolidation and automation architecture licensing.
Among integrated facility operators, AeroFarms and Plenty Unlimited Inc. exemplify technology-differentiated positioning through aeroponic cultivation systems and automated large-scale installations respectively. Freight Farms occupies the modular deployment archetype with container-based systems designed for urban edge siting. Signify Holding and Heliospectra represent the spectral technology supplier tier, occupying positions as LED hardware providers to facility operators across multiple geographies. 80 Acres Farms and Bowery Farming sit within the automated scale operator category, while BrightFarms and Eden Green Technology exemplify regional direct-contracting models with supermarket chain relationships.
| Leading Market Players |
|---|
| AeroFarms |
| Plenty Unlimited Inc. |
| Freight Farms |
| Bowery Farming |
| Signify Holding |
| BrightFarms |
| 80 Acres Farms |
| Eden Green Technology |
| Heliospectra |
| Others |
Supply Flow & Price Mechanics
LED diode price indices cascade through vertical farming facility economics, compressing margins for operators locked into legacy lighting procurement while aeroponic technology leaders capture premium pricing power through water-use efficiency differentiation.
Pricing Analysis
Cost-down pressure on hydroponic tier operators accelerates because supermarket chains consolidate supplier relationships around year-round supply guarantees. Contract-based long-term offtake dominates, with pricing stratifying across premium aeroponic, standard hydroponic, and economy greenhouse-conversion tiers. Certification level under EU Green Deal farm-to-fork disclosure requirements and volume scale drive price differentiation. Retail procurement officers show lowest price sensitivity; commodity spot buyers in wholesale channels face highest margin compression.
Supply Chain Analysis
Domestic-content mandates in UAE sovereign food security programs and Singapore's 30-by-30 initiative are reshaping sourcing toward local facility construction and regional equipment integration. Component manufacturing concentrates in the Netherlands, Japan, and the United States for LED spectral hardware and climate control systems. Raw material dependencies span semiconductor-grade silicon for diodes, aluminum extrusion for racking systems, and specialized nutrient formulations. Single-source vulnerability in diode chip fabrication creates supply chain risk. Distribution runs through direct retailer contracting and foodservice channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Food Safety Modernization Act's preventive controls documentation burden erects a compliance moat that technology-mature operators exploit against undercapitalized entrants lacking closed-loop monitoring infrastructure.
For Market Incumbents: To counter modular container system entrants compressing commissioning timelines, anchor supermarket direct-contracting relationships through multi-year supply guarantees and accelerate backward integration into LED spectral tuning hardware to capture technology expenditure margins. For New Entrants and Emerging Players: EU Green Deal farm-to-fork targets in Northern Europe open a window for controlled-environment suppliers with verifiable carbon disclosure documentation. Target UAE and Singapore sovereign procurement programs as most penetrable geographies; pursue foodservice channel partnerships as lower-competition entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated scale operators with existing retail chain relationships in Northeast US metropolitan corridors. Long-term viability hinges on technology differentiation sustainability; monitor LED efficiency improvement curves as inflection indicator for facility economics reset.| Strategic Initiative | Industry Significance |
|---|---|
| Aeroponic Technology Licensing | UAE sovereign programs absorb capital intensity for water-use efficiency advantages. |
| Direct Retailer Contracting Consolidation | Northeast US supermarket chains prioritize year-round supply consistency over spot pricing. |
| LED Spectral Hardware Integration | Facility operators capture technology expenditure margins through in-house diode programming. |
| Modular Container Deployment | Urban edge siting compresses last-mile logistics costs for foodservice channel penetration. |
| EU Green Deal Compliance Certification | Carbon disclosure documentation secures premium procurement positioning in Northern Europe. |
Methodological Framework
Trade publications, customs filings, and facility commissioning databases formed the secondary backbone, supplemented by primary interviews with controlled-environment agriculture facility operators, supermarket procurement officers, LED lighting system engineers, and agronomy talent specialists. Bottom-up capacity installations triangulated against top-down retail procurement volume estimates.
Historical trendline analysis of facility deployment rates and technology expenditure patterns anchored the projection framework. Segmentation dimensions span cultivation method, technology stack, end-user type, and crop category across the analysis window. CAGRs derived from fitted growth curves incorporating sovereign food security program funding trajectories and LED efficiency improvement assumptions.
The model assumes a particular technology adoption path; alternative pathways for aeroponic root-zone misting systems would alter the outlook. Forecasts reflect assumptions around electricity cost trajectories and municipal zoning permissiveness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Controlled Environment Agriculture Market