
 Commercial Vegetable Chopper Market | 2026-2036
Commercial Vegetable Chopper Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vegetable Chopper Market Outlook
Preventive maintenance subscriptions is rebalancing capital deployment for commercial vegetable choppers, converting upfront equipment purchases into recurring operational expenditures. KitchenAid leverages its service network density to anchor premium positions in North American commercial kitchens. Mueller Austria competes through specialized compact designs targeting independent restaurants with limited prep-line footprint. Breville extends its brand equity from consumer appliances into light-commercial segments through controlled distribution partnerships.
A commercial vegetable chopper is a motorized or hand-powered food preparation machine with blade assemblies typically operating at 1,500–3,500 RPM, designed to reduce whole vegetables into uniform cuts for high-volume foodservice and processing operations. Stainless steel blade housings and NSF-certified contact surfaces define industrial-grade units built for continuous daily operation in regulatory-inspected environments. Electric choppers dominate installed base across restaurant chains where throughput requirements exceed manual capacity, while industrial slicers command margin pools in food processing plants running multi-shift production. Semi-automatic technology occupies the fastest-expanding tier as mid-size catering services seek labor efficiency without full automation capital burden. Carbon steel segments retain niche demand among specialty processors prioritizing edge retention in high-abrasion root vegetable applications.
NSF International standards and FDA Food Code provisions govern material safety and cleanability requirements for commercial vegetable choppers sold into US foodservice channels, with third-party certification now a baseline market access condition. ECHA REACH restrictions on chromium migration from stainless steel alloys are tightening material sourcing specifications for European-bound equipment. Stakeholders must monitor evolving EFSA guidance on food contact material thresholds alongside state-level commercial kitchen energy efficiency mandates that increasingly capture small electric food preparation equipment within scope.
Market Dynamics
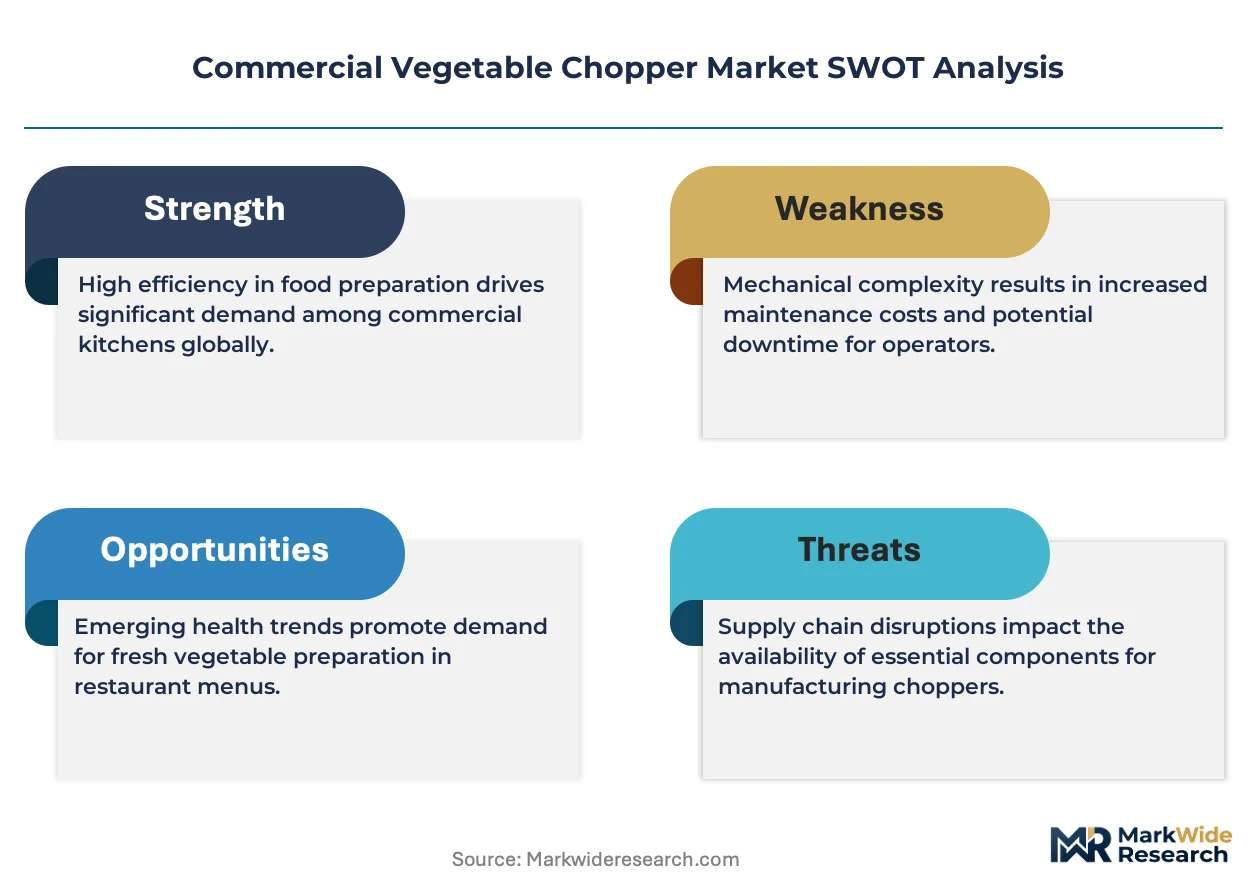
Cloud-connected maintenance subscriptions are rebalancing capital deployment for commercial vegetable choppers, converting upfront equipment purchases into recurring operational expenditures while altering how foodservice operators evaluate total cost of ownership across multi-year holding periods.
Growth Catalysts
- NSF Certification Mandates:FDA Food Code provisions governing material safety and cleanability requirements have elevated third-party certification to a baseline market access condition across US foodservice channels, forcing equipment upgrades.
- Semi-Automatic Technology Adoption:Mid-size catering services are driving demand for labor efficiency solutions that avoid full automation capital burdens, expanding the addressable market for intermediate equipment tiers.
- Germany's Precision Manufacturing Concentration:Mittelstand suppliers in Germany's manufacturing corridor anchor European supply chains for high-throughput dicing systems, creating regional production advantages.
Market Restraints
- Stainless Steel Alloy Cost Volatility:ECHA REACH restrictions on chromium migration from stainless steel alloys are tightening material sourcing specifications and compressing margin pools for European-bound equipment manufacturers.
- Carbon Steel Substitution Pressure:Specialty processors prioritizing edge retention in high-abrasion root vegetable applications retain demand for carbon steel segments, fragmenting material standardization.
- Continuous Operation Technical Limits:Electric choppers operating at 1,500–3,500 RPM face thermal management constraints that cap daily duty cycles in high-volume restaurant chain environments.
Strategic Opportunities
- Cloud-Connected Service Unbundling:Predictive maintenance platforms enabled by IoT sensor integration create recurring revenue streams independent of equipment sales, reshaping vendor-customer relationships.
- Energy Efficiency Mandate Expansion:State-level commercial kitchen energy efficiency regulations increasingly capture small electric food preparation equipment within scope, creating compliance-driven replacement cycles.
- Light-Commercial Segment Extension:Controlled distribution partnerships targeting independent restaurants with limited prep-line footprint open adjacent market space between consumer and industrial tiers.
Industry Challenges
- Multi-Standard Certification Complexity:Equipment manufacturers must navigate simultaneous NSF International standards, FDA Food Code provisions, and evolving EFSA guidance on food contact material thresholds, extending product launch timelines.
- Blade Assembly Technical Labor Scarcity:Precision grinding and balancing of 1,500–3,500 RPM blade assemblies requires specialized machinist skills that concentrate in aging workforce pools across traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vegetable Chopper Market |
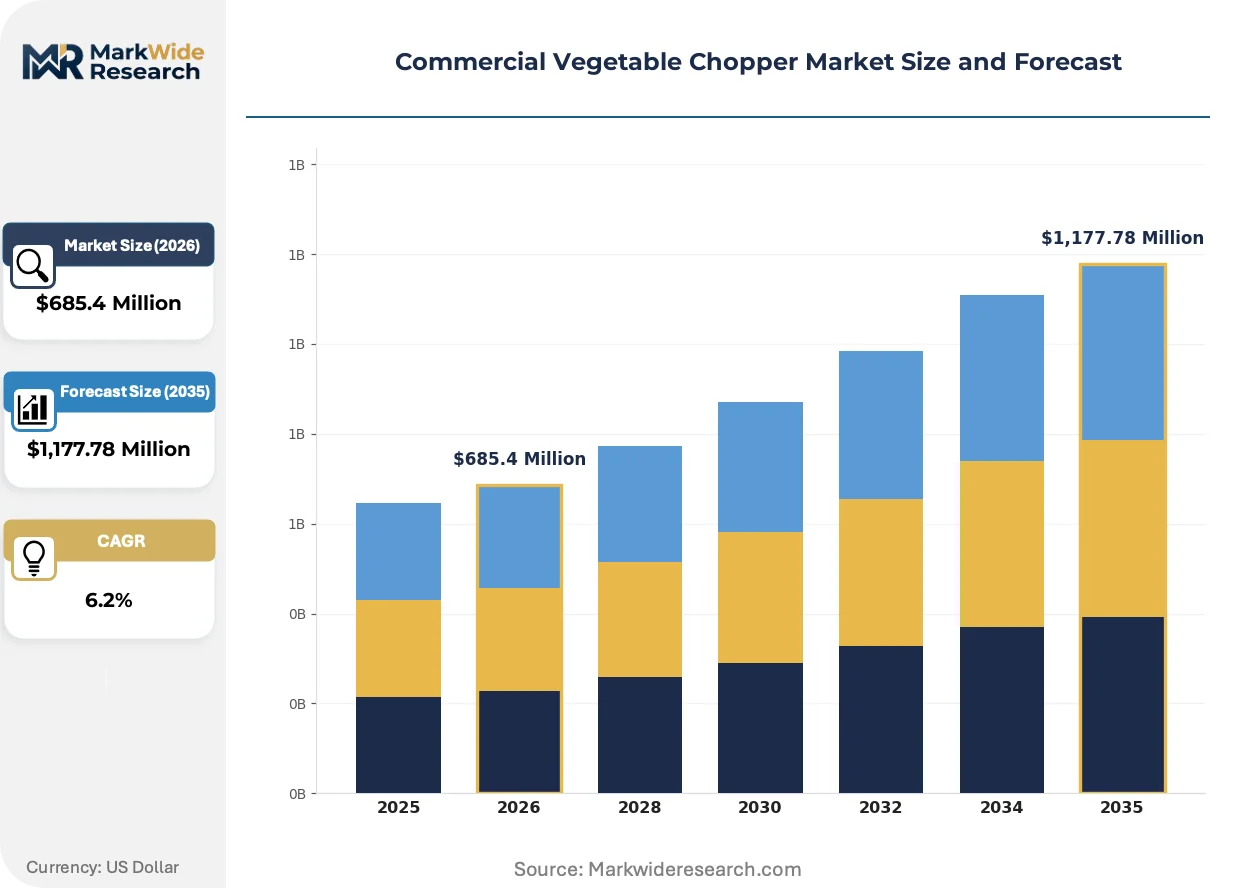
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Choppers, Electric Choppers, Industrial Slicers, Dicers Technology: Mechanical, Automatic, Semi-Automatic, Hydraulic End User: Restaurants, Catering Services, Food Processing Plants, Supermarkets Material: Stainless Steel, Plastic, Aluminum, Carbon Steel |
| Companies Covered | Braun, KitchenAid, Twothousand Machinery, Mueller Austria, Ninja, Newin, Breville, Fullstar, Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vegetable Chopper Market Strategic Shifts
Equipment architecture is fragmenting into service-enabled platforms rather than standalone capital assets, with blade systems, motor housings, and connectivity modules evolving on independent upgrade cycles that decouple hardware longevity from feature obsolescence.
Interchangeable blade cartridge systems with standardized mounting interfaces are modularizing how commercial kitchens configure prep-line equipment. Regional restaurant chains with seasonal menu rotations adopt cartridge subscriptions to swap dicing, slicing, and julienne configurations without dedicated machines. This architecture compresses capital requirements per cutting function while expanding aftermarket parts revenue for original equipment suppliers.
EFSA guidance evolution on food contact material thresholds is tightening cleanability documentation requirements for European-bound equipment. Manufacturers must now validate surface roughness measurements and crevice elimination protocols beyond baseline CE marking compliance. German food processing plants running multi-shift production face the steepest compliance recertification burdens as auditors apply emerging thresholds retroactively to installed equipment bases.
Subscription-based maintenance contracts are displacing traditional warranty-plus-breakdown service models in North American restaurant chains. Kitchen operators trade capital reserves for predictable monthly outlays covering blade sharpening, motor calibration, and regulatory documentation. This preference shift concentrates most visibly in urban food halls and ghost kitchen facilities where equipment utilization rates exceed 18 hours daily and downtime costs dwarf service contract premiums.
Commercial Vegetable Chopper Market Segmentation
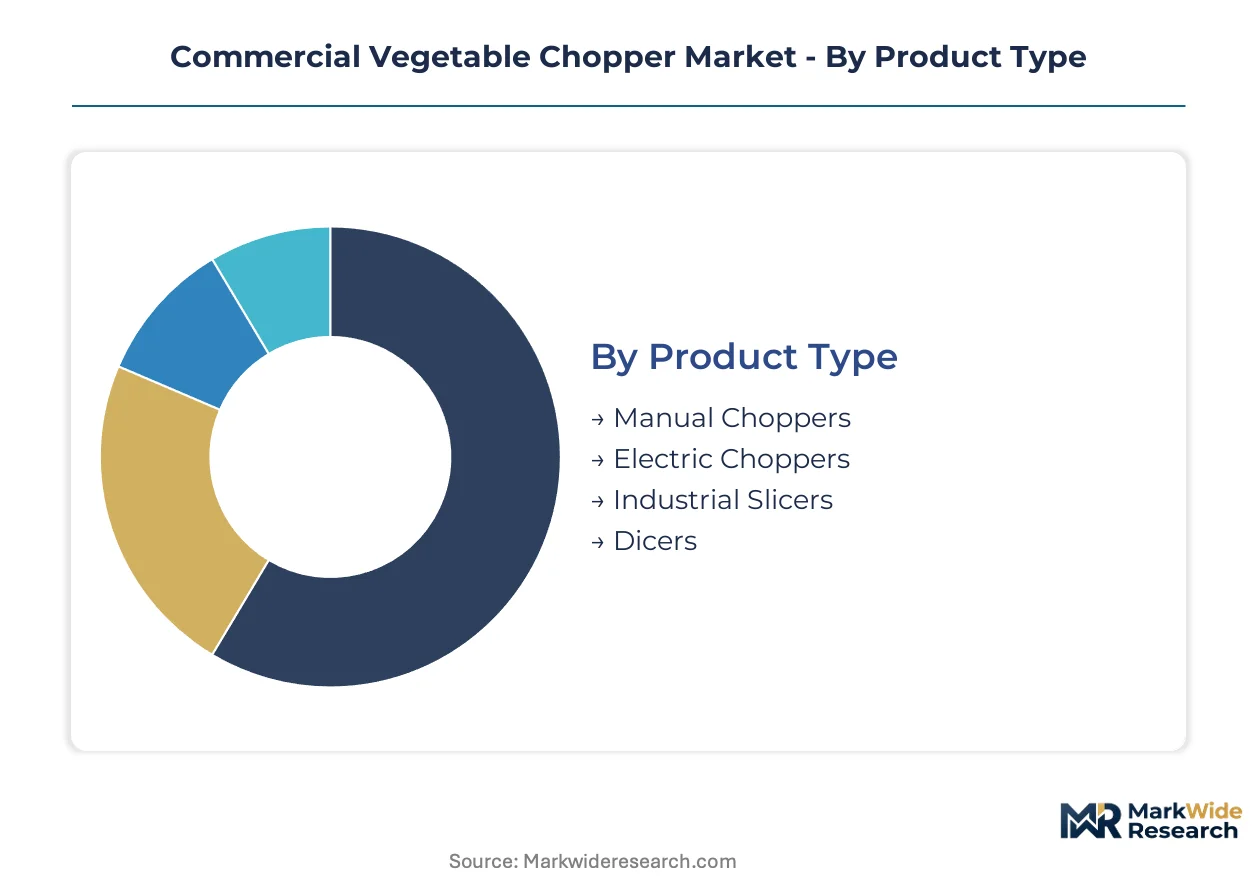
Segmentation in commercial vegetable choppers reveals divergent capital deployment patterns across foodservice tiers. Equipment specifications, automation levels, and material certifications fragment procurement criteria between high-volume processors and limited-footprint operators.
Product Type:
Capital intensity varies sharply across product categories, with full automation demanding the steepest upfront outlays while manual alternatives minimize entry barriers for emerging operators.
- Manual Choppers:Hand-powered units with rotating blade drums or lever-activated cutting grids require no electrical infrastructure. Independent restaurants in Germany's Mittelstand corridor favor these for prep-line flexibility where volume spikes remain unpredictable.
- Electric Choppers:Motorized blade assemblies operating at 1,500–3,500 RPM dominate installed base across US restaurant chains where throughput requirements exceed manual capacity. Thermal management constraints cap daily duty cycles in high-utilization ghost kitchen environments.
- Industrial Slicers:High-capacity belt-fed systems command premium margin pools in food processing plants running multi-shift production. NSF certification mandates drive replacement cycles as FDA Food Code provisions tighten.
- Dicers:Grid-based cutting mechanisms producing uniform cube outputs anchor European supply chains from German precision manufacturing clusters. ECHA REACH restrictions on chromium migration reshape material sourcing specifications.
Electric choppers absorb the bulk of installed capacity; dicers are expanding most quickly.
Technology:
Automation sophistication determines labor substitution economics, with intermediate tiers capturing mid-size operators seeking efficiency without full capital burden.
- Mechanical:Direct-drive or hand-cranked systems without electronic controls minimize maintenance complexity and spare parts dependency. Carbon steel blade variants retain niche demand among specialty root vegetable processors.
- Automatic:Sensor-activated feed systems with programmable cut specifications maximize throughput in food processing plants. Cloud-connected maintenance subscriptions convert these into recurring operational expenditure models.
- Semi-Automatic:Operator-assisted feed mechanisms with motorized cutting cycles occupy the fastest-expanding tier. Mid-size catering services across North American urban food halls adopt these for labor efficiency without full automation capital burden.
- Hydraulic:Pressure-driven cutting force for dense produce applications commands specialized deployment in industrial settings. High-pressure system maintenance requirements concentrate service relationships with original equipment suppliers.
Semi-automatic systems are climbing the fastest; automatic platforms retain the deepest revenue concentration.
End User:
Utilization intensity and regulatory exposure differentiate customer segments, with continuous-operation environments prioritizing uptime guarantees over acquisition cost.
- Restaurants:Full-service and quick-service chains with standardized prep requirements drive volume demand for electric chopper configurations. State-level energy efficiency mandates increasingly capture small electric food preparation equipment within compliance scope.
- Catering Services:Event-based operators with variable throughput needs favor modular equipment with rapid reconfiguration capabilities. Seasonal menu rotations accelerate adoption of interchangeable blade cartridge systems.
- Food Processing Plants:Multi-shift production facilities demand industrial slicers and dicers with continuous-duty motor ratings. EFSA guidance evolution on food contact material thresholds imposes recertification burdens on installed equipment bases.
- Supermarkets:In-store prep operations for ready-to-eat produce sections require compact footprint designs with visible sanitation features. Limited back-of-house space constraints favor vertical integration of multiple cutting functions.
Restaurants absorb the bulk of installed capacity; food processing plants are gaining share fastest.
Material:
Regulatory compliance and abrasion resistance trade off against cost and weight considerations, with certification requirements narrowing viable material choices in inspected environments.
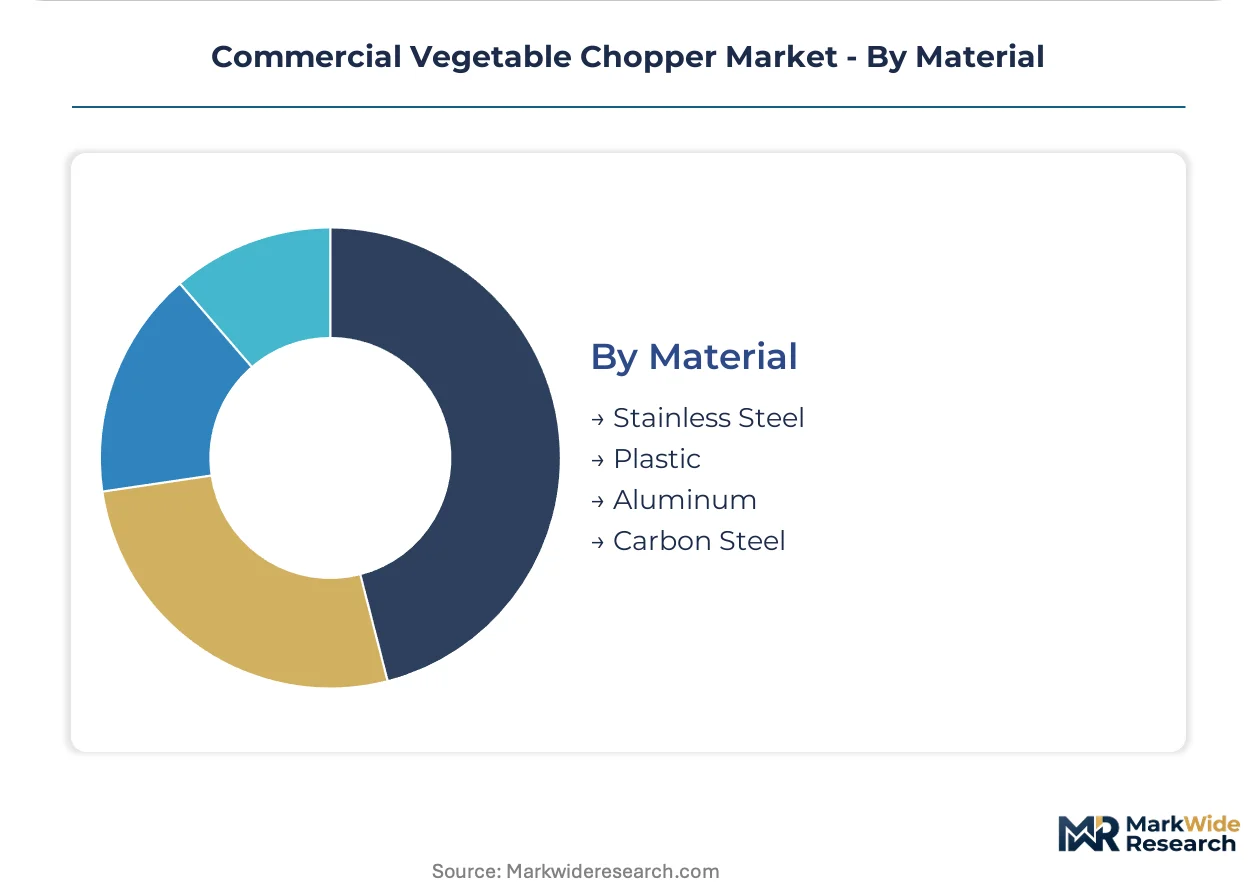
- Stainless Steel:NSF-certified 304 and 316 grade alloys with polished contact surfaces define industrial-grade units for regulatory-inspected environments. Full stainless steel construction meeting NSF standards is reshaping procurement criteria across North American foodservice operations.
- Plastic:Food-grade polymer housings and blade guards reduce weight and cost in light-commercial segments. BPA-free certification requirements and surface degradation under sanitizing chemicals limit operational lifespan.
- Aluminum:Anodized alloy components balance weight reduction with thermal conductivity for motor housing applications. ECHA REACH restrictions on metal migration tighten sourcing specifications for European-bound equipment.
- Carbon Steel:High-carbon blade alloys prioritize edge retention in high-abrasion root vegetable applications. Specialty processors in niche segments retain demand despite corrosion susceptibility requiring intensive maintenance protocols.
Stainless steel absorbs the bulk of installed capacity; aluminum is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity concentrates in Germany's precision manufacturing corridor while consumption spreads across dispersed foodservice markets. The United States absorbs the largest installed base of electric choppers. China's manufacturing scale and India's expanding restaurant sector reshape trade flows.
United States
Ghost kitchen proliferation and urban food hall expansion drive electric chopper demand for 18-hour daily utilization cycles. FDA Food Code provisions governing material safety and cleanability requirements force NSF-certified equipment upgrades across restaurant chains. California's energy efficiency mandates increasingly capture small electric food preparation equipment within compliance scope.
Germany
Mittelstand suppliers anchor European supply chains for high-throughput dicing systems serving food processing plants. ECHA REACH restrictions on chromium migration from stainless steel alloys tighten material sourcing specifications for domestic manufacturers. Baden-Württemberg's precision engineering clusters concentrate blade assembly grinding and balancing capabilities.
China
Domestic restaurant chain standardization and central kitchen buildouts expand demand for semi-automatic equipment tiers. SAMR food contact material standards and GB certification requirements shape equipment specifications for both domestic sale and export. Guangdong Province's metal fabrication centers supply motor housings and blade assemblies to regional equipment assemblers.
India
Quick-service restaurant expansion and cloud kitchen aggregation platforms drive capital deployment into compact footprint electric choppers. FSSAI food safety regulations and state-level commercial kitchen licensing requirements elevate certification expectations for imported equipment. Maharashtra's Mumbai-Pune corridor concentrates foodservice distributor networks serving western India.
United Kingdom
Catering services and contract food management operators seek modular equipment configurations for seasonal menu flexibility. CE marking requirements and evolving EFSA guidance on food contact material thresholds extend product launch timelines for continental suppliers. London's food hall and delivery-kitchen density concentrates demand for high-utilization equipment with uptime guarantees.
Commercial Vegetable Chopper Market Competitive Environment
Capital-heavy producers compete with asset-light designers for position across equipment tiers. The vendor base separates into integrated manufacturers controlling blade foundry and motor winding capabilities versus assemblers sourcing standardized subsystems. Three archetypes dominate: full-stack producers with captive component production, regional specialists serving single-country markets, and brand licensors outsourcing manufacturing entirely. Competitive moves concentrate on strategic partnerships for distribution reach and portfolio diversification into adjacent prep equipment categories.
Among appliance-brand licensors, KitchenAid leverages its service network density to anchor premium positions in North American commercial kitchens. Mueller Austria competes through specialized compact designs targeting independent restaurants with limited prep-line footprint. Breville extends its brand equity from consumer appliances into light-commercial segments through controlled distribution partnerships. These three exemplify how brand extension strategies reshape competitive positioning across the manual-to-electric product spectrum.
| Leading Market Players |
|---|
| Braun |
| KitchenAid |
| Twothousand Machinery |
| Mueller Austria |
| Ninja |
| Newin |
| Breville |
| Fullstar |
| Cuisinart |
| Others |
Value Chain & Pricing Dynamics
California's Title 24 energy efficiency mandates gate qualified supply for commercial vegetable choppers, restricting premium-tier pricing access to manufacturers with certified motor systems and documented thermal management protocols.
Pricing Analysis
Margin tightening in mid-tier electric choppers reflects ECHA REACH compliance costs for stainless steel alloys. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified units with cloud connectivity from basic electric models and manual alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Independent restaurants exhibit highest price sensitivity; ghost kitchen operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Specialized machinist skills for precision blade grinding concentrate in aging workforce pools across Baden-Württemberg and Guangdong Province manufacturing corridors. Component sourcing draws from German Mittelstand suppliers for dicing systems, Chinese metal fabrication centers for motor housings, and Indian distributor networks for aftermarket parts. Single-source vulnerability persists in high-carbon blade alloy supply. Distribution runs through regional foodservice equipment dealers and direct OEM relationships with chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where NSF certification creates a barrier-to-entry moat that rewards incumbent investment in third-party validation infrastructure.
For Market Incumbents: Anticipate margin compression from carbon steel substitution pressure by deepening captive blade foundry capabilities and securing multi-year stainless alloy contracts. Channel control through exclusive service network agreements defends position against emerging compact-design specialists targeting independent restaurants.
For New Entrants and Emerging Players: Capture the semi-automatic technology tier where mid-size catering services seek labor efficiency without full automation capital burden. India's quick-service restaurant expansion offers the most penetrable geography. A cloud-connected maintenance subscription model provides differentiation against established transactional vendors.
For Investors and Strategic Acquirers: EFSA guidance tightening on food contact material thresholds is the leading indicator that recertification service capabilities will command acquisition premiums. Five-to-ten year viability favors targets with integrated blade assembly grinding operations rather than pure brand licensors. Monitor state-level energy efficiency mandate expansion as the signal for compliance-driven replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Service Platform Launch | KitchenAid's dense North American service network enables predictive maintenance revenue independent of equipment sales. |
| Interchangeable Blade Cartridge System | Regional restaurant chains with seasonal menu rotations compress capital requirements per cutting function. |
| NSF Certification Pre-Investment | Early compliance with evolving FDA Food Code provisions secures baseline market access before enforcement waves. |
| German Mittelstand Supply Partnership | Baden-Württemberg precision engineering clusters anchor European supply chains for high-throughput dicing systems. |
| Light-Commercial Distribution Expansion | Controlled partnerships with independent restaurants open adjacent market space between consumer and industrial tiers. |
Study Parameters
Document review covered FDA Food Code provisions, ECHA REACH regulatory filings, and NSF certification databases, complemented by interviews with foodservice equipment procurement managers, commercial kitchen maintenance directors, OEM product development leads, and regional distributor account executives. Secondary validation drew from customs trade data, foodservice industry association reports, and SEC filings of publicly listed appliance manufacturers. Bottom-up equipment shipment analysis triangulated against top-down foodservice operator capital expenditure surveys.
Installed base and revenue outputs across the projection horizon reflect segmentation by product type, automation technology, end-user vertical, and material certification tier. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance-driven upgrade patterns. Industry-specific forecast inputs incorporated ghost kitchen utilization intensity metrics and state-level energy efficiency mandate adoption timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA food contact material threshold evolution and stainless steel alloy cost volatility. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foodservice labor cost trajectories. Material deviation in ECHA REACH restriction scope or FDA Food Code revision timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Automatic Composter Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Soil Mixer Market