
 Europe Grow Light Market | 2026-2036
Europe Grow Light Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Grow Light Market Intelligence
CE marking under the Ecodesign Directive is redrawing competitive boundaries for luminaire suppliers serving European horticulture. Signify Holding leverages its vertical integration into LED chip sourcing to sustain margin control across premium fixture lines. Gavita International B.V. anchors its position through deep specialization in high-pressure sodium replacements for greenhouse retrofits. Heliospectra AB differentiates via tunable-spectrum platforms that target research institutions requiring precise photomorphogenic control.
Europe grow lights are electrically powered luminaires engineered to emit photosynthetically active radiation in the 400–700 nanometer range, typically incorporating aluminum heat sinks and driver electronics rated for high-humidity environments to sustain crop development cycles in controlled agricultural settings. LED fixtures now dominate new installations given their compliance trajectory with EU Ecodesign tiered efficacy requirements, while HID technology retains residual share in legacy greenhouse infrastructure where capital replacement cycles lag. Smart technology integration represents the fastest-expanding segment as connected controls enable dynamic dimming aligned with utility demand-response programs, and commercial growers constitute the deepest margin pool due to their volume procurement scale and technical specification sophistication.
The EU Green Deal and F-Gas Regulation are accelerating phase-out timelines for mercury-containing HID lamps, while ECHA REACH compliance obligations constrain substrate and coating chemistries in fixture manufacturing. EMA and national agricultural regulators in member states are scrutinizing light-pollution externalities from large-scale vertical farm installations near urban boundaries. Stakeholders must monitor the interplay between tightening Ecodesign efficacy thresholds and the readiness of passive-cooling architectures to maintain lumen output without active thermal management.
Market Dynamics
The EU F-Gas Regulation's mercury lamp phase-out timeline is compressing replacement cycles across Dutch and German greenhouse infrastructure, forcing capital allocation toward LED retrofit architectures before 2027 enforcement windows.
Growth Catalysts
- EU Green Deal decarbonization mandates:National agricultural ministries in the Netherlands and Germany are channeling structural funds into vertical farm electrification, accelerating LED fixture procurement for controlled-environment agriculture.
- Tunable-spectrum photobiology:Research institutions across Scandinavia and the Benelux are deploying multi-channel LED arrays to isolate photomorphogenic responses in high-value crops, expanding addressable fixture specifications.
- Spain and Italy:Mediterranean protected-cropping regions are retrofitting legacy high-pressure sodium infrastructure with EU-funded efficiency grants, opening volume deployment corridors for compliant luminaire suppliers.
Market Restraints
- Aluminum heat sink input volatility:Primary aluminum price swings from Nordic smelters transmit directly to fixture bill-of-materials, compressing margin visibility for passive-cooling LED architectures.
- Driver electronics supply concentration:German and Austrian power electronics specialists control high-humidity-rated driver supply, creating single-source vulnerability for fixture assemblers without captive semiconductor capability.
- Mercury-containing lamp legacy lock-in:Eastern European greenhouse operators face extended replacement cycles due to capital constraints, delaying LED transition timelines beyond regulatory phase-out dates.
Strategic Opportunities
- Polish and Romanian vertical farm greenfield development:These member states offer underpenetrated deployment terrain where EU cohesion funds support first-mover LED infrastructure without legacy retrofit friction.
- CSRD-aligned carbon accounting integration:Large horticultural groups in France and Germany now require fixture-level energy telemetry for Scope 2 reporting, creating premium attach-rate potential for connected control systems.
- Photobiology-as-a-service convergence:Research consortia are bundling tunable-spectrum hardware with spectral recipe subscriptions, shifting revenue from capital equipment to recurring service arrangements.
Industry Challenges
- REACH-compliant substrate chemistry reformulation:Fixture manufacturers must requalify heat sink coatings and PCB laminates under evolving ECHA substance restrictions, extending new product introduction timelines.
- Passive-cooling thermal management at high lumen density:Maintaining output without active ventilation requires advanced aluminum extrusion geometries that strain existing European metalworking capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Grow Light Market |
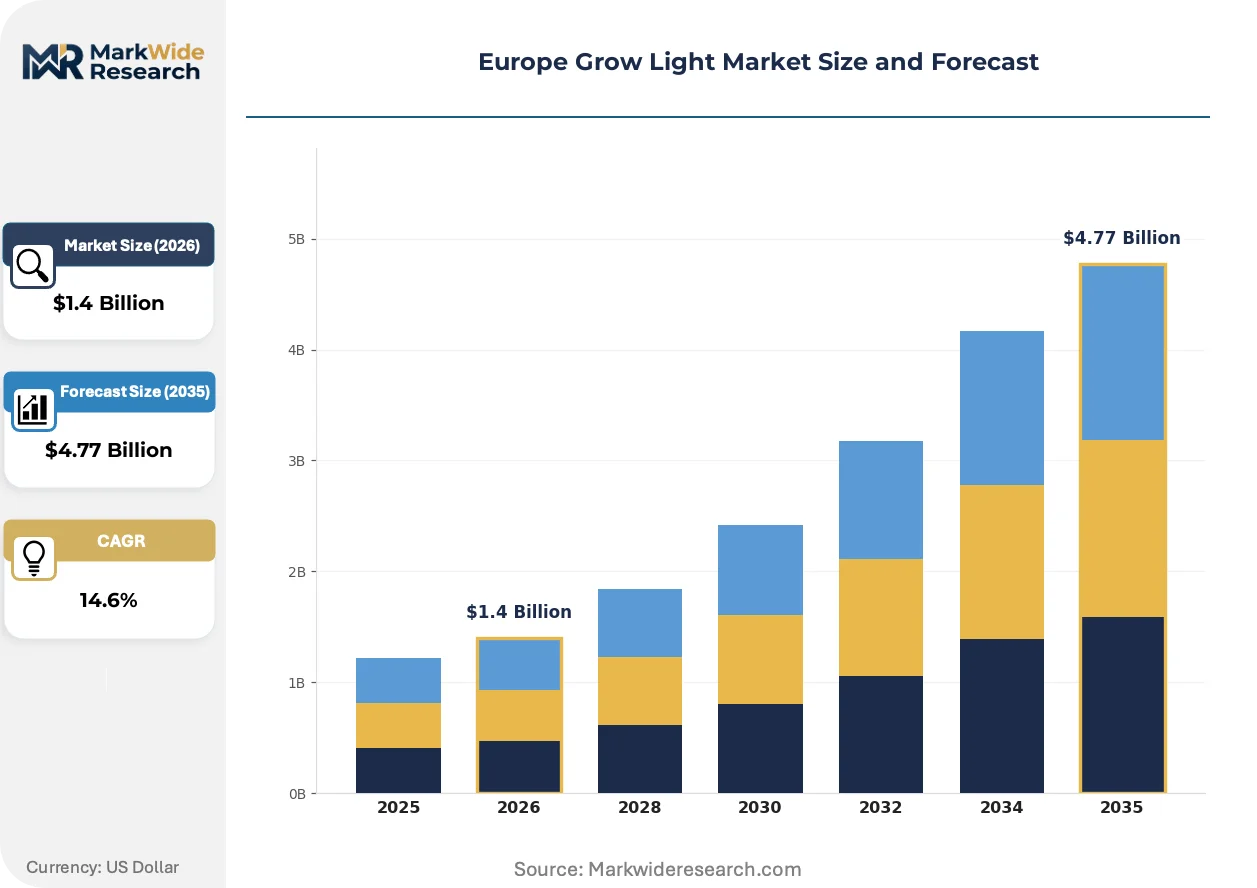
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HID, Fluorescent, Incandescent Technology: Active, Passive, Hybrid, Smart End User: Commercial Growers, Home Gardeners, Research Institutions, Vertical Farms Application: Vegetable Production, Flower Cultivation, Seed Germination, Bonsai Growing |
| Companies Covered | Signify Holding, Gavita International B.V., Heliospectra AB, ams-OSRAM AG, Hortilux Schréder, Valoya, Lemnis Oreon B.V., Agrolux B.V., PAR Source Lighting Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Grow Light Market Strategic Shifts & Innovations
Spectral programmability and connected control architectures are redefining competitive differentiation in European horticultural lighting, shifting value capture from hardware specification toward data-enabled growing protocols.
Multi-channel LED engines with independent dimming control is fragmenting the fixture market into crop-specific configurations. Tomato and lettuce growers in the Netherlands are adopting distinct spectral recipes at accelerating refresh rates. This technology is fragmenting supplier portfolios into narrow horticultural specializations rather than general-purpose greenhouse luminaires.
CE marking under tiered Ecodesign Directive efficacy thresholds is compressing market access for non-compliant imports. The 2027 tightening of minimum lumens-per-watt requirements will disqualify basic LED retrofits from distribution channels. German agricultural cooperatives are pre-qualifying fixtures against forthcoming thresholds to avoid stranded asset risk.
Research institutions are consolidating procurement around long-term spectral service contracts rather than capital purchases. Universities in Sweden and Denmark now contract for guaranteed photon delivery per growth cycle, transferring performance risk to hardware suppliers. This model is most visible in Nordic countries where public procurement rules favor operational expenditure structures over capital budgets.
Europe Grow Light Market Segmentation
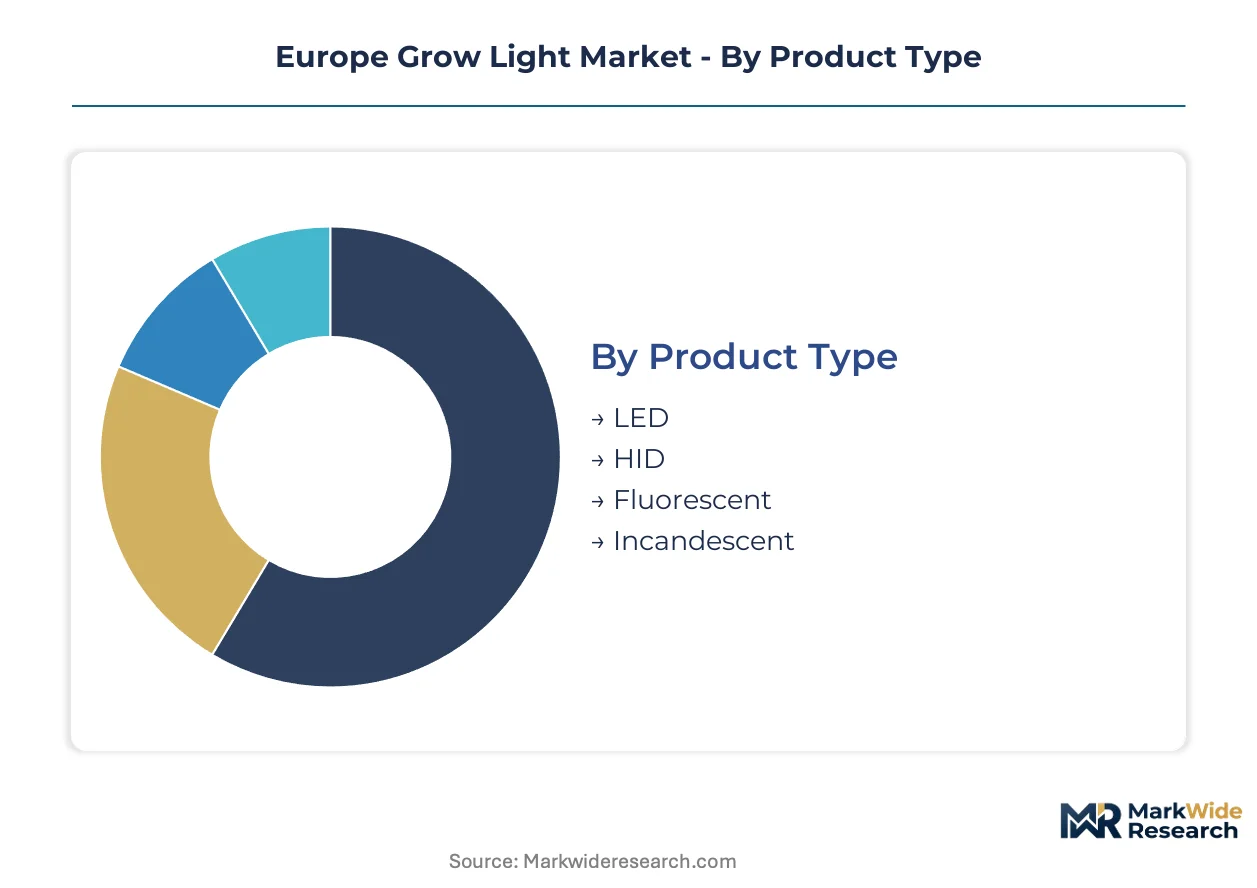
Segmentation in the Europe Grow Light Market exposes how margin pools concentrate around technology sophistication and customer procurement scale. Fixture specifications diverge sharply between legacy greenhouse retrofits and greenfield vertical farm installations.
Product Type:
LED fixtures capture the deepest margin pools through premium efficacy tiers and connected control attach-rates, while HID technology retains residual value in capital-constrained replacement cycles.
- LED:Solid-state luminaires with aluminum heat sinks and multi-channel spectral engines deliver 400–700 nanometer output with programmable dimming. Dutch commercial vertical farms are scaling LED installations ahead of F-Gas Regulation enforcement windows, compressing payback periods through EU Green Deal efficiency grants.
- HID:High-intensity discharge lamps including high-pressure sodium and metal halide technologies dominate legacy greenhouse infrastructure. Eastern European operators face extended replacement cycles due to capital constraints, delaying transition timelines beyond regulatory phase-out dates.
- Fluorescent:Linear and compact fluorescent systems serve low-intensity propagation benches and home gardener segments with limited spectral tunability.
- Incandescent:Thermal-radiation sources with poor photosynthetic efficiency retain niche presence in hobbyist applications and supplemental heating contexts.
HID holds installed capacity across Mediterranean protected-cropping regions. LED is rotating up the share rankings through Ecodesign Directive compliance mandates.
Technology:
Procurement patterns bifurcate between passive-cooling architectures favored by cost-sensitive commercial growers and smart systems demanded by research institutions requiring spectral programmability.
- Smart:Connected control platforms with IoT-enabled dimming, environmental sensor integration, and utility demand-response compatibility. German agricultural cooperatives are pre-qualifying smart fixtures against forthcoming Ecodesign thresholds to avoid stranded asset risk.
- Passive:Heat sink-dependent thermal management without active ventilation, relying on aluminum extrusion geometry for lumen maintenance. Nordic smelter aluminum price volatility transmits directly to fixture bill-of-materials, compressing margin visibility for European assemblers.
- Active:Forced-air or liquid cooling systems enabling higher lumen density in compact form factors, deployed in high-bay vertical farm configurations.
- Hybrid:Combined passive-active thermal architectures balancing reliability and output density for mid-scale commercial operations.
Passive systems anchor volume shipments. Smart technology is climbing the fastest through CSRD-aligned carbon accounting requirements.
End User:
Customer type determines specification complexity and contract structure, with research institutions driving tunable-spectrum innovation and commercial growers demanding scale economics.
- Commercial Growers:Large-scale greenhouse and vertical farm operators with volume procurement leverage and technical sophistication. Tomato and lettuce producers in the Netherlands are adopting distinct spectral recipes, fragmenting supplier portfolios into narrow horticultural specializations.
- Research Institutions:Universities and agricultural research centers requiring precise photomorphogenic control and multi-channel spectral programmability. Swedish and Danish universities now contract for guaranteed photon delivery per growth cycle, transferring performance risk to hardware suppliers.
- Vertical Farms:Controlled-environment agriculture facilities with stacked production architecture and high fixture density per square meter.
- Home Gardeners:Consumer segment with price-sensitive procurement and limited technical specification requirements.
Commercial growers command procurement scale. Research institutions are rotating up the share rankings through photobiology-as-a-service convergence.
Application:
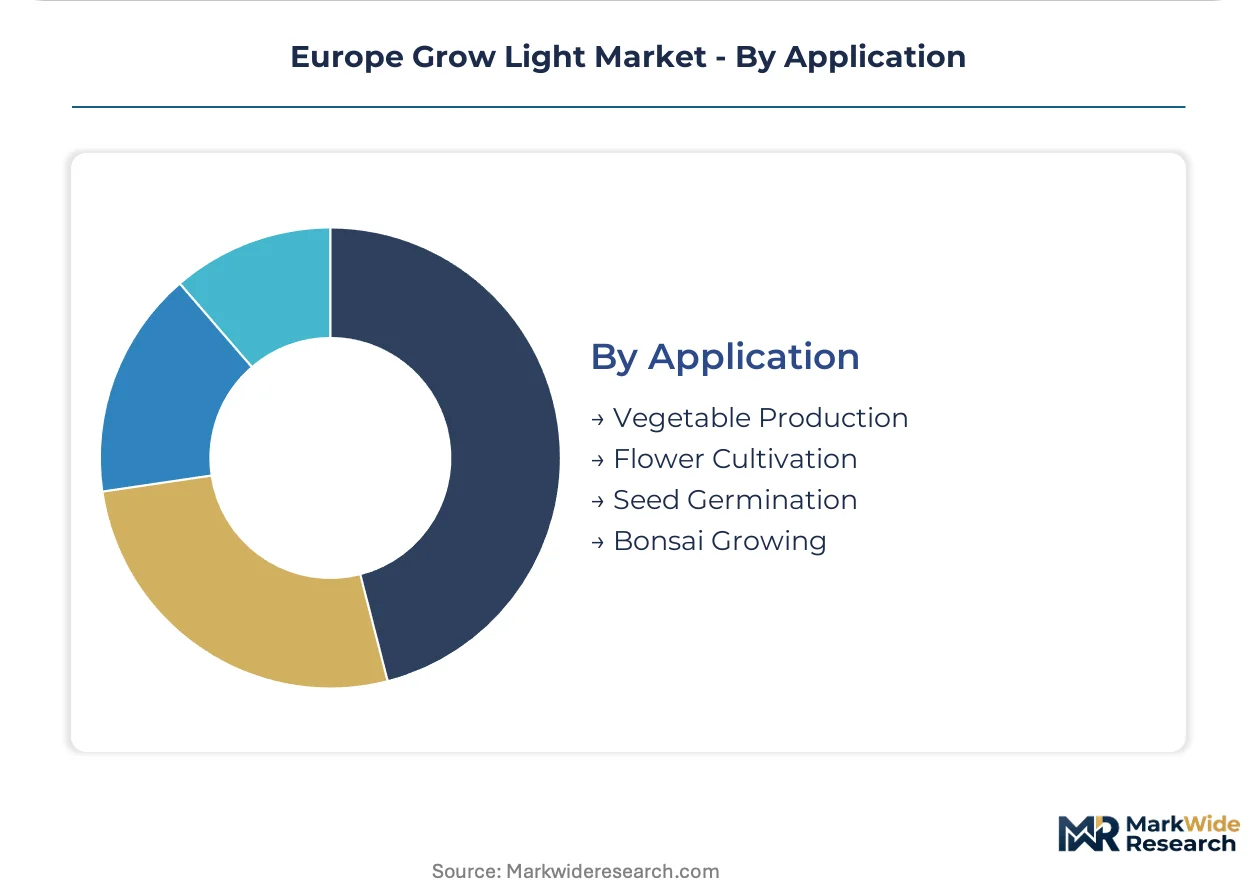
Crop-specific photon requirements fragment fixture specifications, with vegetable production driving standardization and flower cultivation demanding spectral customization.
- Vegetable Production:Leafy greens and fruiting crops with high photosynthetic photon flux density requirements and predictable growth cycles. Lettuce growers in Benelux regions are deploying standardized LED recipes at accelerating refresh rates.
- Flower Cultivation:Ornamental and medicinal crops requiring precise photoperiod manipulation and spectrum-tuned morphogenic control. Research consortia are bundling tunable-spectrum hardware with spectral recipe subscriptions for high-value flower species.
- Seed Germination:Low-intensity propagation phases with uniform light distribution requirements and minimal heat loading.
- Bonsai Growing:Specialty horticulture with compact fixture form factors and extended photoperiod precision for dwarf species maintenance.
Vegetable production holds installed capacity. Flower cultivation is expanding most quickly through premium crop value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal structural funds and F-Gas Regulation phase-out timelines are redistributing grow light demand across member states, with Dutch and German operators accelerating LED procurement ahead of enforcement windows.
Netherlands
Commercial vertical farms in Westland and Aalsmeer are scaling LED installations to replace mercury-containing HID lamps before F-Gas restrictions bite. The Dutch national agricultural ministry channels EU cohesion funds into controlled-environment agriculture electrification. Eindhoven-based horticultural clusters drive specification sophistication through proximity to Philips-originated lighting expertise.
Germany
Research institutions across Bavaria and North Rhine-Westphalia are deploying tunable-spectrum systems for photomorphogenic studies. Ecodesign Directive tiered efficacy thresholds are compressing market access for non-compliant imports. Munich and Stuttgart agricultural cooperatives pre-qualify fixtures against forthcoming 2027 requirements to avoid stranded asset exposure.
Spain
Mediterranean protected-cropping regions in Almería and Murcia are retrofitting legacy high-pressure sodium infrastructure with EU-funded efficiency grants. The Spanish agricultural ministry aligns national subsidy programs with EU Green Deal decarbonization mandates. Andalusian greenhouse clusters represent volume deployment corridors for compliant luminaire suppliers.
Poland
Vertical farm greenfield development in Warsaw and Łódź metropolitan areas offers underpenetrated terrain without legacy retrofit friction. EU cohesion funds support first-mover LED infrastructure in member states with lower agricultural automation baselines. Polish horticultural operators leverage structural fund access to leapfrog directly to smart-connected fixture architectures.
Sweden
Universities in Lund and Uppsala are consolidating procurement around long-term spectral service contracts rather than capital purchases. Swedish public procurement rules favor operational expenditure structures over capital budgets for research infrastructure. Nordic research consortia bundle tunable-spectrum hardware with guaranteed photon delivery subscriptions per growth cycle.
Europe Grow Light Market Key Industry Players
Player mix skews toward specialized horticultural lighting firms with deep greenhouse sector relationships. Market structure exhibits moderate consolidation around Dutch and German-origin suppliers with established CE marking pathways. Three archetypes dominate: LED chip-integrated multinationals, HID replacement specialists, and tunable-spectrum research-platform vendors. Competitive dynamics center on Ecodesign pre-certification racing and spectral recipe IP accumulation.
Within the research-platform tier, Heliospectra AB exemplifies the photobiology-as-a-service convergence through its Swedish base and public procurement positioning. Among Dutch-origin specialists, Gavita International B.V. and Agrolux B.V. occupy positions anchored in greenhouse retrofit relationships and high-pressure sodium replacement expertise. Signify Holding represents the chip-integrated multinational archetype through its Eindhoven-originated vertical integration into LED sourcing and premium fixture line control.
| Leading Market Players |
|---|
| Signify Holding |
| Gavita International B.V. |
| Heliospectra AB |
| ams-OSRAM AG |
| Hortilux Schréder |
| Valoya |
| Lemnis Oreon B.V. |
| Agrolux B.V. |
| PAR Source Lighting Solutions |
| Others |
Cost & Logistics Intelligence
Aluminum heat sink fabrication scale in Nordic smelter networks concentrates cost leverage among Dutch and German fixture assemblers, compressing margin floors for smaller European players while elevating procurement power for volume buyers negotiating long-term offtake agreements under EU Green Deal efficiency grant programs.
Pricing Analysis
CE certification tier creates the primary spread between premium tunable-spectrum fixtures and basic retrofit LED modules, with Ecodesign Directive pre-qualification commanding material premiums from German agricultural cooperatives. Project-based contracting dominates commercial grower procurement, while research institutions in Sweden and Denmark favor operational expenditure structures with guaranteed photon delivery subscriptions. Cost compression in passive-cooling architectures is intensifying because Nordic aluminum price volatility transmits directly to bill-of-materials, forcing margin tightening across mid-tier European assemblers. Home gardeners exhibit highest price sensitivity, while commercial vertical farms in the Netherlands demonstrate lowest sensitivity given EU structural fund coverage and scale procurement leverage.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes strain inbound logistics for driver electronics and LED chip substrates, extending lead time uncertainty for fixture assemblers without captive semiconductor capability. Manufacturing concentration centers on China for LED chip fabrication, Germany and Austria for humidity-rated driver electronics, and Nordic countries for primary aluminum extrusion feedstock. Fixture production draws from aluminum heat sinks, multi-channel LED engines, and power electronics as critical inputs. Single-source vulnerability in German and Austrian driver supply creates structural risk for European assemblers lacking backward integration. Distribution runs through horticultural equipment distributors and direct OEM relationships with large greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Dutch and German commercial grower cooperatives, compressing supplier margins and elevating specification requirements that favor incumbents with established Ecodesign pre-certification pathways.
For Market Incumbents: Consolidate backward integration into LED chip sourcing to sustain margin control against emerging Asian component suppliers, while accelerating Ecodesign Directive pre-qualification racing to lock out non-compliant imports before 2027 efficacy threshold tightening. Deepen spectral recipe IP accumulation through research institution partnerships in Scandinavia and the Benelux to defend against photobiology-as-a-service entrants. For New Entrants and Emerging Players: Anchor in Polish and Romanian vertical farm greenfield development where EU cohesion funds support first-mover LED infrastructure without legacy retrofit friction, targeting commercial growers with smart-connected fixture architectures that leapfrog passive-cooling incumbent offerings. Pursue research institution procurement through operational expenditure contract structures aligned with Nordic public procurement rules favoring service over capital expenditure. For Investors and Strategic Acquirers: Tunable-spectrum research-platform vendors with established photobiology-as-a-service revenue streams and Swedish public procurement positioning represent the most defensible acquisition archetype over the long-term viability window. Monitor Ecodesign Directive enforcement windows as inflection indicators for stranded asset risk among HID replacement specialists lacking LED transition pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Ecodesign Pre-Certification Racing | CE marking ahead of 2027 efficacy thresholds locks distribution channel access against non-compliant imports. |
| Backward Integration into LED Sourcing | Captive chip supply insulates margin control from Asian component price volatility and allocation constraints. |
| Photobiology-as-a-Service Convergence | Recurring revenue contracts with Swedish and Danish universities transfer performance risk from buyer to supplier. |
| EU Cohesion Fund Alignment | Polish and Romanian structural fund access enables greenfield vertical farm deployment without legacy friction. |
| Spectral Recipe IP Accumulation | Proprietary light protocols for tomato and lettuce cultivars fragment supplier portfolios into narrow specializations. |
Research Approach
Operator-level perspectives from greenhouse operations managers, vertical farm technical directors, agricultural cooperative procurement leads, and university research facility managers anchored the qualitative base, cross-referenced with secondary validation from EU Ecodesign Directive filings, ECHA REACH substance restriction updates, F-Gas Regulation implementation guidance, and national agricultural ministry structural fund disclosures. Bottom-up fixture shipment analysis and top-down market sizing triangulated volume estimates across the projection horizon.
Sensitivity analysis around aluminum price volatility, driver electronics allocation constraints, and EU Green Deal grant disbursement timing informed scenario boundaries. Segmentation dimensions modeled include fixture technology tier, thermal management architecture, end-user procurement scale, crop application specificity, and regional regulatory cluster. CAGRs derived from installed base rotation rates and replacement cycle compression under F-Gas Regulation phase-out timelines, incorporating spectral programmability adoption curves and connected control attach-rate trajectories.
Material uncertainties — Nordic smelter capacity utilization shifts, Ecodesign Directive efficacy threshold revisions, and ECHA substance restriction scope expansions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and structural fund continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market