
 Square Silos Market | 2026-2036
Square Silos Market Size, Share, and Industry Trends Forecast 2026-2036
Square Silos Market Insights
Commercial grain elevators and agricultural cooperatives are bifurcating from smaller on-farm buyers as the dominant procurement archetype in square silo investment. Sukup Manufacturing Co. leverages its Iowa-based manufacturing footprint to dominate North American distribution for steel square silos in the 1000-2000 ton capacity class. AGI competes through vertical integration into handling equipment and aeration systems that lock in silo specifications. Symaga anchors southern European demand with galvanized steel designs engineered for Mediterranean humidity conditions.
Square silos are rigid, flat-walled storage structures fabricated from corrugated or smooth steel panels, reinforced concrete, or aluminum alloys, engineered for vertical bulk material containment with capacities ranging from below 500 tons to above 2000 tons. Their geometric profile maximizes floor-space efficiency in constrained industrial sites and enables modular expansion through side-by-side configuration. Steel construction leads material segmentation due to structural strength, seismic resilience, and weldable modification options for aeration and temperature monitoring. The above 2000 tons storage capacity segment sustains premium margin pools tied to integrated conveying and automated discharge systems. Chemical storage applications in the application dimension are accelerating fastest as hazardous material containment rules tighten across manufacturing jurisdictions.
FDA food safety guidelines, OSHA grain handling standards, and EPA stormwater runoff regulations collectively shape square silo design specifications, installation protocols, and site permitting timelines in the United States. REACH compliance and CE marking requirements in Europe restrict polymer and coating chemistries while mandating structural load certifications for commercial installations. Stakeholders must monitor evolving carbon-border adjustment mechanisms and domestic content incentives that will reconfigure supplier qualification criteria and total cost of ownership calculations for new storage infrastructure.
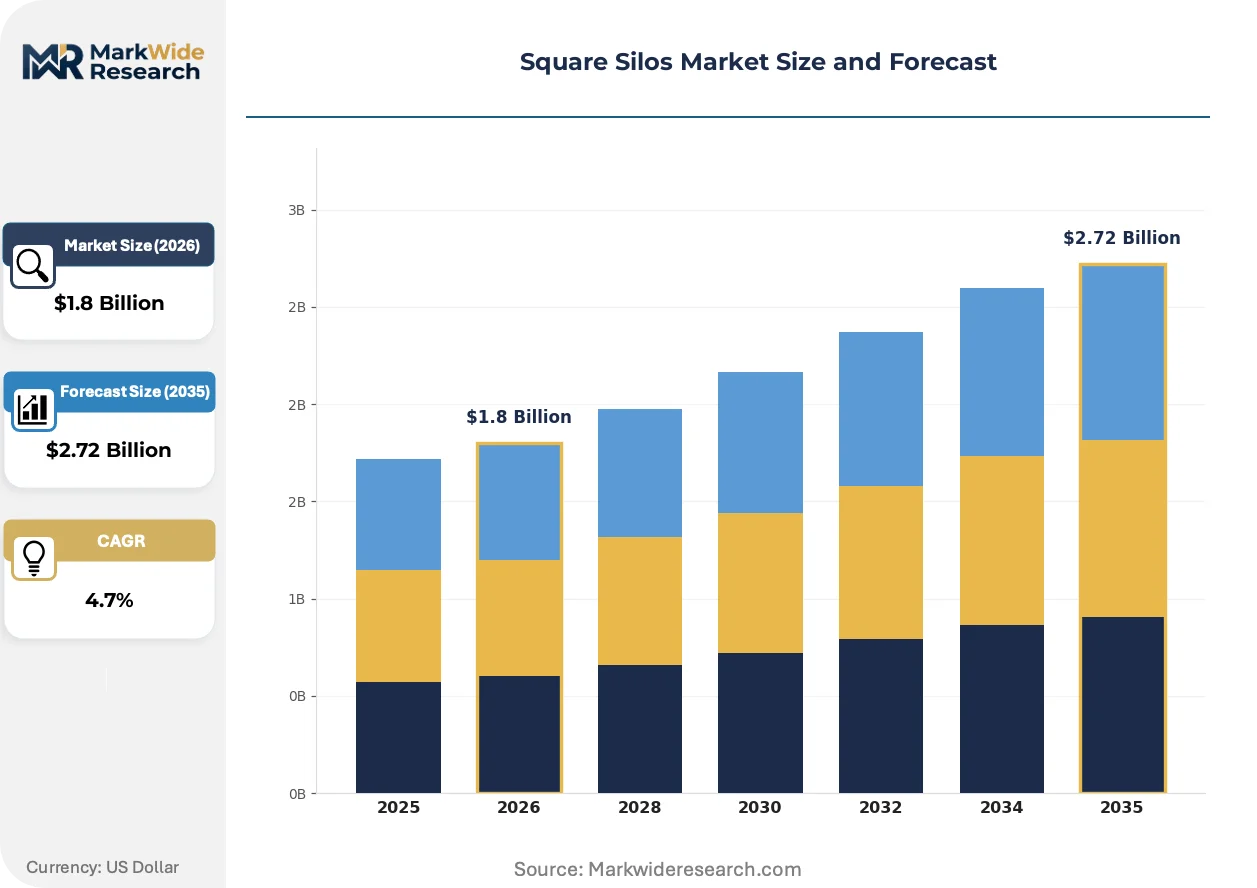
Market Dynamics
Agricultural cooperatives in the United States Corn Belt are systematically replacing legacy grain handling infrastructure with modular square silo systems, compressing procurement cycles and reshaping supplier qualification criteria toward integrated aeration and discharge capabilities.
Growth Catalysts
- EU F-Gas Regulation:Steel material certification requirements under REACH and F-Gas rules are redirecting procurement toward European manufacturers with verified coating chemistries and structural load documentation.
- Above 2000 ton capacity:Commercial grain elevators are consolidating storage into fewer, larger installations with automated conveying systems that lock in premium specifications and multi-year service contracts.
- Chemical storage applications:Hazardous material containment mandates across manufacturing jurisdictions are accelerating demand for sealed, corrosion-resistant square silo designs with integrated monitoring.
Market Restraints
- Galvanized steel input costs:Zinc price volatility and European energy premiums are compressing margins for manufacturers dependent on hot-dip galvanizing processes.
- Seismic certification requirements:Japan's METI structural standards and California building codes are extending engineering timelines and limiting supplier pools for high-capacity installations.
- Round silo substitution:Welded steel round silos retain cost advantages in unconstrained rural sites where floor-space efficiency carries no premium.
Strategic Opportunities
- India agricultural modernization:FSSAI grain storage standards and state-level cooperative consolidation are creating first-mover openings for corrosion-resistant designs in humid subtropical conditions.
- Carbon-border adjustment mechanisms:EU CBAM phase-in is incentivizing regional steel sourcing and domestic manufacturing investments that shorten supply chains for European buyers.
- IoT-enabled predictive maintenance:Convergence of wireless temperature monitoring with automated aeration controls is enabling subscription-based service models that extend customer lifetime value.
Industry Challenges
- Welding certification scarcity:Qualified pressure vessel welders for sealed chemical storage applications command premium wages and extended recruitment timelines across North American fabrication facilities.
- Legacy aeration retrofit complexity:Integrating modern monitoring systems into existing flat-bottom silo foundations requires structural reinforcement that disrupts active storage operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Square Silos Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Concrete, Aluminum, Fiberglass, Polymer Storage Capacity: Below 500 Tons, 500-1000 Tons, 1000-2000 Tons, Above 2000 Tons Application: Grain Storage, Feed Storage, Chemical Storage, Bulk Material Handling, Seed Preservation End User: Agricultural Cooperatives, Food Processors, Chemical Manufacturers, Feed Mills |
| Companies Covered | Sukup Manufacturing Co., AGI, Symaga, Prado Silos, Mysilo, Silos Córdoba, Brock Grain Systems, Sioux Steel Company, Cimbria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Square Silos Market Trends and Innovations
Smart monitoring systems and modular fabrication methods are compressing installation timelines while regulatory pressure on material traceability is reconfiguring supplier relationships across the value chain.
Corrugated galvanized steel panels with factory-applied polymer coatings are displacing bare metal designs in coastal and high-humidity installations. Agricultural cooperatives in Spain and southern Italy are specifying these configurations for Mediterranean conditions. The shift is compressing maintenance cycles and extending asset depreciation schedules for buyers prioritizing total cost of ownership over first-cost minimization.
REACH compliance documentation and CE marking requirements are mandating batch-level steel traceability and coating chemistry disclosure for commercial installations across European Union member states. Manufacturers without in-house metallurgical testing capabilities are facing extended third-party certification timelines. The above 2000 ton capacity segment is absorbing the highest compliance burden as structural load certifications require finite element analysis submissions.
Outcome-based service contracts bundling aeration monitoring with predictive maintenance are displacing traditional equipment-only sales in North American grain elevator procurement. AGI and Sukup Manufacturing are restructuring field service organizations to capture recurring revenue streams. The United States Corn Belt exhibits the fastest adoption velocity as cooperative buyers consolidate vendor relationships and demand uptime guarantees.
Square Silos Market Segmentation
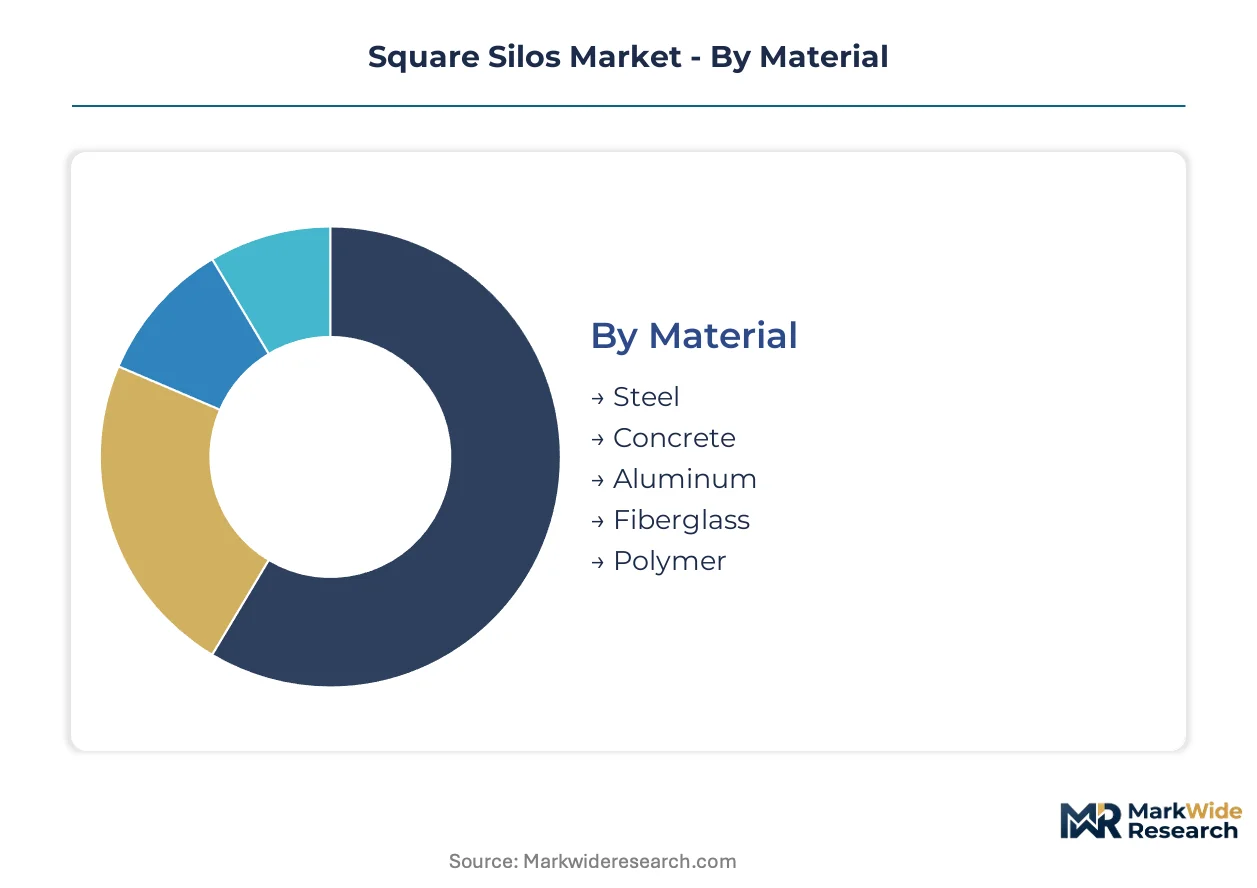
Segmentation in square silos reveals how material selection and capacity specifications diverge between agricultural bulk handlers and chemical containment operators. Procurement patterns split sharply across end-use verticals, with regulatory compliance requirements dictating supplier qualification criteria and design engineering priorities.
Material:
Round silo substitution pressure concentrates most intensely on aluminum and polymer segments, where cost-per-ton differentials against welded steel cylinders erode specification wins in unconstrained rural sites.
- Steel:Corrugated or smooth panels fabricated from galvanized carbon steel deliver structural strength and seismic resilience for high-capacity installations. Agricultural cooperatives across the United States Corn Belt specify steel construction for modular expansion capability and weldable modification options for aeration integration.
- Concrete:Cast-in-place or precast reinforced designs anchor permanent bulk material facilities requiring fire resistance and thermal mass. Chemical manufacturers in jurisdictions with EPA stormwater and hazardous material rules specify concrete for secondary containment integration and spill barrier compatibility.
- Aluminum:Lightweight alloy panels suit coastal installations where corrosion resistance outweighs first-cost considerations. Mediterranean agricultural operations specify aluminum for humidity tolerance in grain preservation applications.
- Fiberglass:Composite construction delivers chemical inertness for aggressive substance storage. Specialty chemical handlers specify fiberglass where steel corrosion rates accelerate maintenance cycles beyond asset depreciation schedules.
- Polymer:Rotomolded or extruded plastic designs serve small-scale feed storage and seed preservation. On-farm buyers in developing agricultural markets specify polymer for mobility and foundation simplicity.
Steel retains volume leadership across commercial installations; chemical storage applications hold the steepest expansion curve as containment mandates tighten.
Storage Capacity:
Cost tier stratification separates premium-engineered large installations from standardized mid-capacity units, with automation integration driving margin capture at the upper bound.
- Below 500 Tons:Compact designs serve on-farm grain storage and specialty seed preservation with minimal foundation requirements. Small agricultural operations in India specify these units for FSSAI-compliant decentralized storage under state cooperative consolidation programs.
- 500-1000 Tons:Mid-range configurations balance modular scalability with aeration system compatibility. Regional grain elevators in Spain and Italy specify this tier for Mediterranean humidity management with factory-applied polymer coatings.
- 1000-2000 Tons:Commercial-grade installations dominate North American Corn Belt replacement cycles with integrated conveying and temperature monitoring. Sukup Manufacturing anchors this segment through Iowa-based fabrication and distribution density.
- Above 2000 Tons:Large-scale systems command premium specifications with automated discharge and predictive maintenance subscriptions. Commercial grain elevators consolidate procurement into fewer installations, locking in multi-year service contracts and finite element analysis documentation for structural load certification.
1000-2000 tons commands the largest procurement volume; above 2000 tons gains share fastest through cooperative consolidation and automation bundling.
Application:
Customer type concentration varies sharply by application, with chemical containment requiring sealed designs and agricultural storage prioritizing aeration throughput.
- Grain Storage:Primary application for square silo geometry maximizing floor-space efficiency in constrained elevator sites. United States agricultural cooperatives drive systematic replacement of legacy infrastructure with modular steel configurations.
- Feed Storage:Intermediate capacity requirements with moisture control specifications for nutritional preservation. Feed mills specify integrated aeration to prevent mycotoxin accumulation under FDA food safety guidelines.
- Chemical Storage:Sealed, corrosion-resistant designs with integrated monitoring systems for hazardous material containment. Manufacturing jurisdictions accelerating REACH-style rules propel specification growth for pressure-vessel-certified fabrication.
- Bulk Material Handling:Mineral, cement, and aggregate containment requiring abrasion-resistant panel configurations. Industrial sites specify reinforced discharge systems for continuous-flow operations.
- Seed Preservation:Climate-controlled environments with humidity management for germination integrity. Specialized agricultural operations specify polymer or aluminum construction for thermal stability.
Grain storage anchors installed base volume; chemical storage climbs the fastest as hazardous material rules expand across manufacturing jurisdictions.
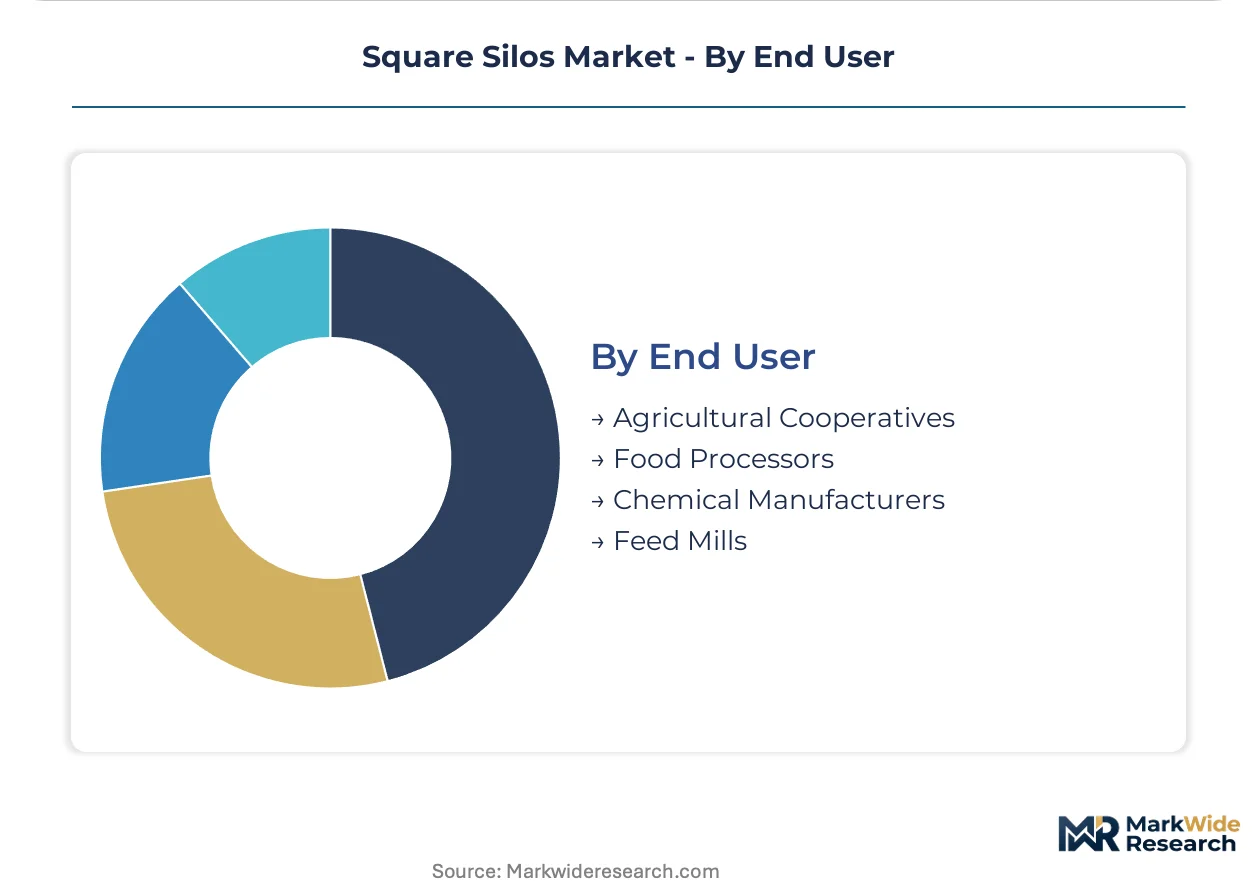
End User:
Supply concentration patterns diverge between consolidated cooperative buyers and fragmented on-farm purchasers, reshaping distribution channel economics.
- Agricultural Cooperatives:Consolidated procurement power driving specification standardization and vendor reduction. Corn Belt cooperatives compress procurement cycles toward integrated aeration and discharge capabilities.
- Food Processors:FDA compliance requirements dictating material traceability and sanitary design specifications. Large-scale handlers specify steel construction with batch-level documentation for supply chain verification.
- Chemical Manufacturers:Hazardous material containment mandates requiring sealed designs and pressure vessel certifications. European buyers under F-Gas Regulation redirect procurement toward REACH-compliant manufacturers with verified coating chemistries.
- Feed Mills:Nutritional quality preservation driving aeration system integration and moisture monitoring. Mid-capacity steel configurations dominate this segment for cost-performance balance.
Agricultural cooperatives retain procurement volume leadership; chemical manufacturers hold the steepest expansion trajectory as containment regulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel fabricators export modular square silo systems to agricultural cooperatives across the United States Corn Belt, establishing a transatlantic trade corridor anchored by REACH-compliant certification documentation.
United States
Agricultural cooperatives in Iowa and Illinois are replacing legacy round silo infrastructure with steel square configurations. OSHA grain handling standards mandate integrated aeration monitoring for installations above 1000 tons capacity. The Des Moines manufacturing cluster hosts Sukup Manufacturing Co., which anchors North American distribution through captive fabrication and dense service networks.
Germany
Steel mills in the Ruhr region supply galvanized panel stock to domestic silo fabricators serving chemical storage applications. ECHA REACH compliance requirements restrict coating chemistries and mandate batch-level material traceability. The North Rhine-Westphalia industrial corridor concentrates pressure-vessel-certified welding capacity for sealed hazardous material containment designs.
Spain
Andalusian olive oil cooperatives and Murcian grain handlers specify aluminum and polymer-coated steel configurations for Mediterranean humidity tolerance. F-Gas Regulation compliance redirects public procurement toward domestic manufacturers with verified structural load documentation. The Seville-Valencia axis hosts Symaga and Silos Córdoba, anchoring southern European demand for corrosion-resistant flat-walled storage.
India
State-level agricultural cooperative consolidation in Maharashtra and Gujarat is creating first-mover demand for FSSAI-compliant decentralized grain storage. BIS structural standards and DGFT import tariffs are incentivizing domestic fabrication investments. The Pune industrial cluster is emerging as a hub for mid-capacity steel square silo assembly serving humid subtropical conditions.
Brazil
Soybean export handlers in Mato Grosso and Paraná are specifying above-2000-ton steel configurations with automated discharge systems. ANVISA food safety guidelines and state environmental licensing are extending engineering timelines for large-scale installations. The Campinas-Sorocaba corridor concentrates feed mill demand for intermediate-capacity aerated storage designs.
Square Silos Market Competitive Landscape
Listed leaders compete with private specialists across material certification and regional distribution density. The vendor base organizes into three tiers: integrated handling equipment conglomerates, regional steel fabricators with captive galvanizing, and specialty chemical containment constructors. Strategic moves concentrate on backward integration into coating chemistry control and geographic expansion through distributor acquisition.
Within the North American premium-fabrication tier, Sukup Manufacturing Co. and AGI exemplify divergent positioning archetypes. Sukup anchors its position through Iowa-based manufacturing density and Corn Belt cooperative relationships. AGI occupies a position emphasizing upstream control over aeration and conveying equipment that locks in silo specifications. Among European corrosion-resistant specialists, Symaga represents the Mediterranean humidity-engineering archetype, while Prado Silos and Mysilo exemplify Iberian and Turkish regional fabrication scale respectively. Brock Grain Systems and Sioux Steel Company sit within the mid-capacity standardized-product tier competing on first-cost minimization for on-farm buyers.
| Leading Market Players |
|---|
| Sukup Manufacturing Co. |
| AGI |
| Symaga |
| Prado Silos |
| Mysilo |
| Silos Córdoba |
| Brock Grain Systems |
| Sioux Steel Company |
| Cimbria |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at galvanized steel mills in Germany and the United States establishes price floors for square silo panels, compressing margin buffers for fabricators serving agricultural cooperatives while rewarding REACH-compliant European manufacturers with procurement preference under EU F-Gas Regulation certification requirements.
Pricing Analysis
Next-generation IoT-enabled silo systems with integrated aeration monitoring command 40-60% price premiums over legacy uninstrumented designs, while bare-metal configurations face accelerating cost compression from polymer-coated alternatives. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance subscriptions from equipment-only sales and basic galvanized panel supply. Price differentiation rests on CE marking documentation and finite element analysis certification for above-2000-ton installations. Zinc price volatility and European energy premiums are intensifying margin pressure in hot-dip galvanizing tiers. On-farm buyers in developing agricultural markets exhibit highest price sensitivity, while commercial grain elevators prioritize total cost of ownership over first-cost minimization.
Supply Chain Analysis
Inventory cycles for corrosion-resistant steel panels extend 8-14 weeks at German and Spanish fabricators, constraining rapid-response procurement for Corn Belt cooperative replacement programs. Supply concentrates in Germany, the United States, and Spain, with Ruhr-region steel mills feeding galvanized stock to domestic silo manufacturers. Raw material dependencies center on zinc ingot supply from Nyrstar's European smelters, polymer coating chemistries subject to REACH disclosure, and pressure-vessel-certified welding consumables. Single-source vulnerability in qualified welder pools for sealed chemical storage applications threatens delivery timelines. Distribution runs through captive fabrication networks in Iowa and North Rhine-Westphalia, with aftermarket service density determining competitive positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service contracts bundling aeration monitoring with predictive maintenance are expanding faster than hardware-only sales, converting capital expenditure relationships into recurring revenue streams that extend customer lifetime value across the United States Corn Belt.
For Market Incumbents: Compound defensive positioning by deepening backward integration into coating chemistry control and acquiring regional distributors to lock in channel density against emerging corrosion-resistant specialists. Round silo substitution pressure in unconstrained rural sites threatens specification wins in aluminum and polymer segments; counter through captive galvanizing investments and REACH-compliant certification documentation that redirects European procurement. For New Entrants and Emerging Players: Predictive maintenance service gaps in legacy flat-bottom silo infrastructure present white-space openings for retrofit specialists with wireless temperature monitoring capabilities. Target India's Maharashtra and Gujarat state cooperative consolidation programs for FSSAI-compliant decentralized storage demand. Enter through partnership with domestic Pune-cluster fabricators to navigate BIS structural standards and DGFT import tariffs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among above-2000-ton capacity specialists with multi-year service contracts and finite element analysis documentation capabilities. Long-term viability favors manufacturers with in-house metallurgical testing and pressure-vessel welding certification. Watch EU carbon-border adjustment mechanism phase-in as inflection indicator for regional steel sourcing preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | REACH-compliant manufacturers capture procurement preference under EU F-Gas Regulation certification requirements. |
| IoT-Enabled Predictive Maintenance Launch | Subscription service models displace equipment-only sales in North American grain elevator procurement cycles. |
| Geographic Expansion through Distributor Acquisition | Corn Belt cooperative consolidation rewards dense service networks with uptime guarantee contracts. |
| Pressure-Vessel Welding Certification Investment | Sealed chemical storage demand accelerates under hazardous material containment mandates across manufacturing jurisdictions. |
| Regional Manufacturing Footprint Establishment | EU CBAM phase-in incentivizes domestic fabrication investments that shorten supply chains for European buyers. |
Research Methodology
Operator-level perspectives from agricultural cooperative procurement directors, grain elevator maintenance managers, steel fabrication plant engineers, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC 10-K filings from listed handling equipment manufacturers, and ECHA REACH compliance documentation. Bottom-up capacity and shipment estimates triangulated against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested forecast robustness against zinc price volatility scenarios, EU CBAM implementation timelines, and cooperative consolidation acceleration in target geographies. The analytical framework modeled material type, storage capacity tier, application vertical, and end-user concentration dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance cost trajectories, with grain storage volume trends and chemical containment mandate expansion serving as primary demand inputs.
Forecasts assume regulatory continuity in EU REACH and F-Gas regimes, United States OSHA grain handling standards, and India FSSAI storage requirements; material policy shifts would require re-modeling of supplier qualification timelines and procurement preference structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Commercial Grain Mill Market