
 Agricultural Mapping Services Market | 2026-2036
Agricultural Mapping Services Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Mapping Services Market Analysis
Brazil is reconfiguring agricultural mapping capacity through expanded drone service networks and localized data processing centers. Trimble Inc. leverages its GNSS correction infrastructure to dominate high-accuracy field boundary mapping across South American grain corridors. John Deere anchors its competitive position through backward integration into display hardware and cloud-based agronomy platforms. Hexagon AB competes via specialized geospatial software suites that extend into soil variability analytics and prescription mapping tools.
Agricultural mapping services encompass the acquisition, processing, and visualization of geospatial data to characterize field conditions, crop health, and terrain features, typically employing sub-meter GPS accuracy and multispectral spectral indices such as NDVI. These services enable variable-rate application of seeds, fertilizers, and crop protection products based on spatially explicit productivity zones. Remote Sensing Tools and UAV Technology segments are capturing margin pools as fleet operators shift from hardware sales toward recurring data subscription models. Precision Agriculture applications lead adoption volumes while Soil Analysis represents the fastest-growing service line as carbon credit verification protocols intensify sampling density requirements. Farmers and Agricultural Consultants as end-user categories diverge sharply in willingness-to-pay, with consultant-led bundled services commanding premium pricing over direct farmer subscriptions.
The FAA governs commercial drone operations including beyond-visual-line-of-sight agricultural surveys through Part 107 waivers and evolving type certification pathways. The EU Green Deal and F-Gas Regulation indirectly shape demand by restricting traditional soil assessment methods and promoting non-invasive remote sensing alternatives. ISO standards for geographic information quality assurance create baseline interoperability requirements that filter market access for smaller service providers. Stakeholders must monitor evolving national drone airspace classifications and carbon MRV protocol specifications to anticipate which data products will carry regulatory premium value.
Market Dynamics
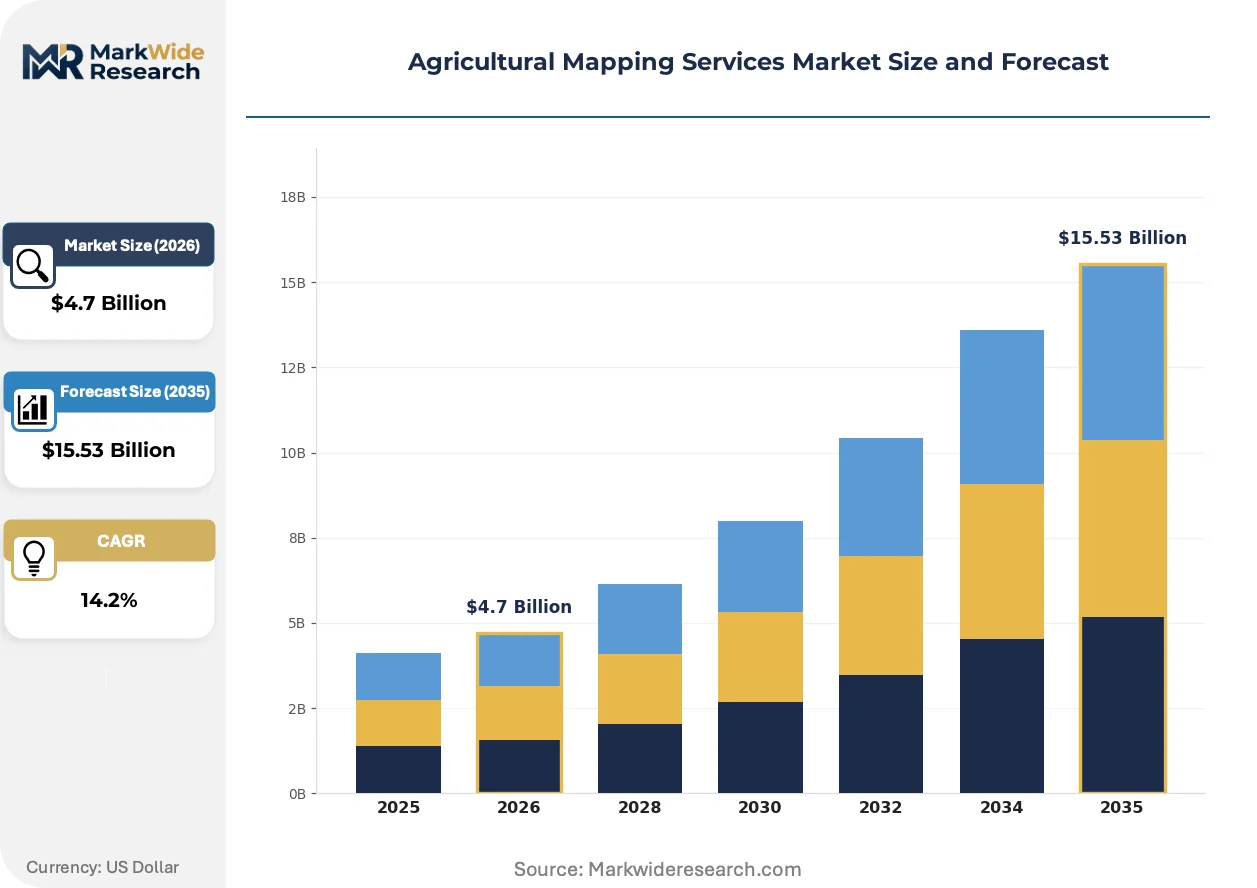
The agricultural mapping services sector is reconfiguring around regulatory-mandated geospatial compliance, with subsidy eligibility in major grain-producing jurisdictions now contingent on satellite-verified field boundary documentation and carbon inventory protocols.
Growth Catalysts
- EU Green Deal satellite monitoring mandates:The European Union's Common Agricultural Policy now requires geospatial compliance for direct payment eligibility, forcing adoption of precision agriculture platforms across member state farming operations.
- Carbon credit verification protocols:Soil sampling density requirements for MRV (Measurement, Reporting, Verification) frameworks are intensifying demand for high-resolution terrain characterization and prescription mapping tools.
- Brazil's Mato Grosso digitization wave:Agribusinesses across the soybean belt are deploying drone service networks and localized data processing centers to optimize input costs at field-level granularity.
Market Restraints
- GNSS correction infrastructure concentration:High-accuracy field boundary mapping depends on sparse ground-based reference station networks, creating supply bottlenecks in remote agricultural corridors.
- FAA Part 107 waiver complexity:Beyond-visual-line-of-sight agricultural surveys face prolonged certification timelines, restricting fleet scalability for commercial drone operators.
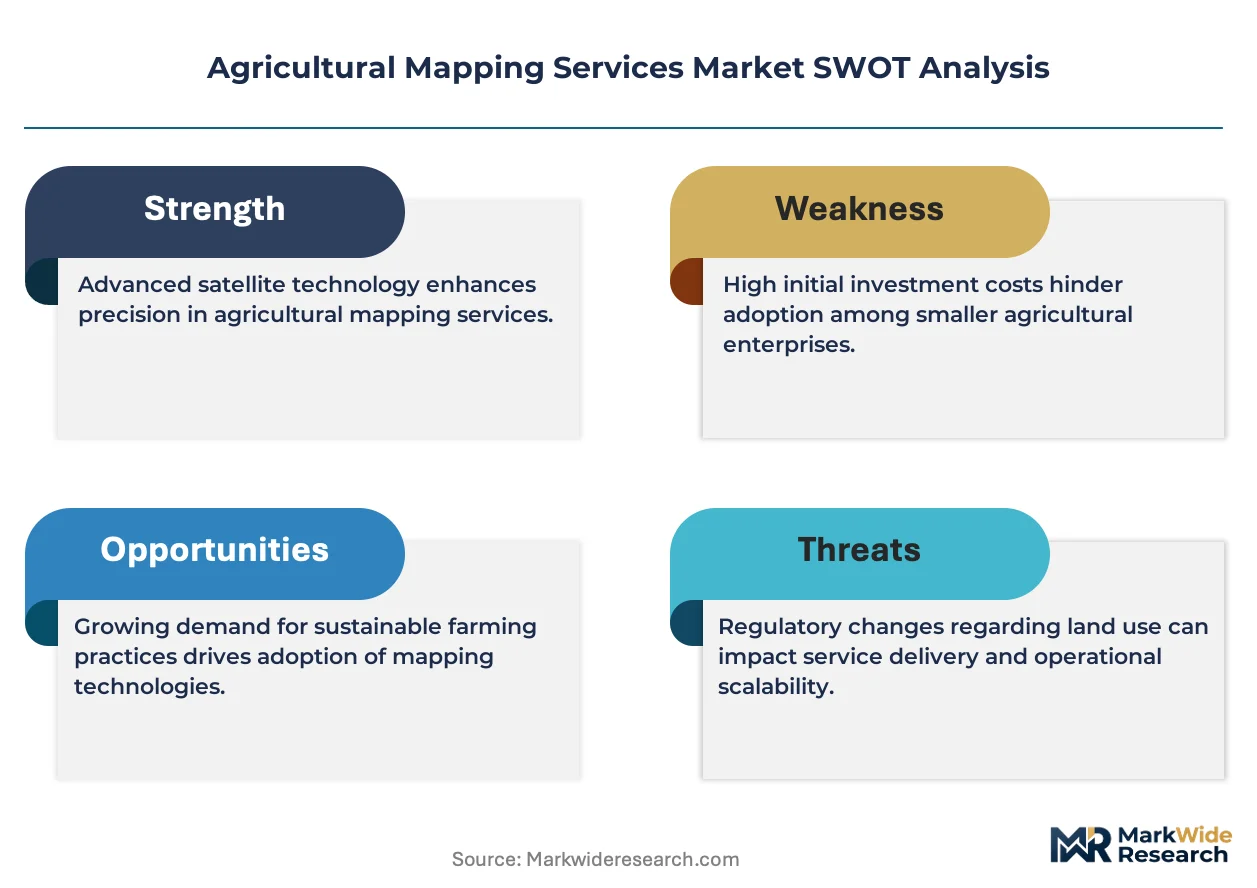
- Multispectral sensor cost volatility:Precision agriculture hardware remains capital-intensive for smaller farming operations, limiting addressable market penetration outside large-scale commercial holdings.
Strategic Opportunities
- Soil Analysis service line expansion:Carbon credit verification is driving fastest-growing demand for spatially explicit productivity zone characterization and variable-rate input application.
- Recurring data subscription models:Fleet operators are capturing margin pools by shifting from hardware sales toward agronomy-as-a-service platforms with annual recurring revenue structures.
- Consultant-led bundled services:Agricultural consultants command premium pricing over direct farmer subscriptions by integrating mapping outputs with agronomic advisory and input procurement.
Industry Challenges
- ISO geographic information quality assurance gaps:Interoperability standards create baseline compliance barriers that filter market access for smaller service providers lacking certification infrastructure.
- Legacy display hardware integration friction:Cloud-based agronomy platforms face technical complexity when interfacing with installed bases of proprietary terminal equipment in older machinery fleets.
- Drone airspace classification fragmentation:Evolving national regulatory frameworks for commercial UAV operations create compliance uncertainty for cross-border service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Mapping Services Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GIS Software, Remote Sensing Tools, Drones, Data Analytics End User: Farmers, Agricultural Consultants, Government Agencies, Research Institutions Technology: Satellite Imagery, LiDAR, UAV Technology, IoT Sensors Application: Crop Monitoring, Soil Analysis, Land Use Planning, Precision Agriculture |
| Companies Covered | Trimble Inc., John Deere, Hexagon AB, Topcon Corporation, AG Leader Technology, SoilOptix, TARANIS, The Sanborn Map Company, Airbus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Mapping Services Market Emerging Trajectories
Service delivery models across agricultural mapping are pivoting from transactional hardware sales toward embedded software subscriptions, while regulatory pressure on carbon accountability reshapes data product specifications.
Hyperspectral imaging systems are extending spectral resolution beyond traditional NDVI indices to detect early-stage crop stress and nutrient deficiency signatures. Large grain trading houses and crop insurance underwriters are adopting these platforms at accelerated procurement cycles. The technology is rendering obsolete single-band vegetation indices that fail to discriminate between biotic and abiotic stress factors.
The EU F-Gas Regulation restricts traditional soil assessment methods involving invasive sampling and chemical analysis, promoting non-invasive remote sensing alternatives for carbon inventory verification. This industrial consequence accelerates deployment of electromagnetic induction and gamma radiometrics for soil property inference. Soil Analysis service providers across Germany and France are restructuring field protocols to eliminate F-Gas-dependent equipment from certification workflows.
After-sales service unbundling is separating hardware maintenance from data analytics subscriptions, allowing farmers to decouple equipment ownership from agronomic intelligence access. Dealer networks and independent agronomy consultancies are capturing displaced margin pools previously retained by integrated OEM platforms. This pattern is most visible in Australia's wheat belt and the US Corn Belt, where farmer cooperatives negotiate direct SaaS contracts bypassing machinery dealerships.
Agricultural Mapping Services Market Segmentation
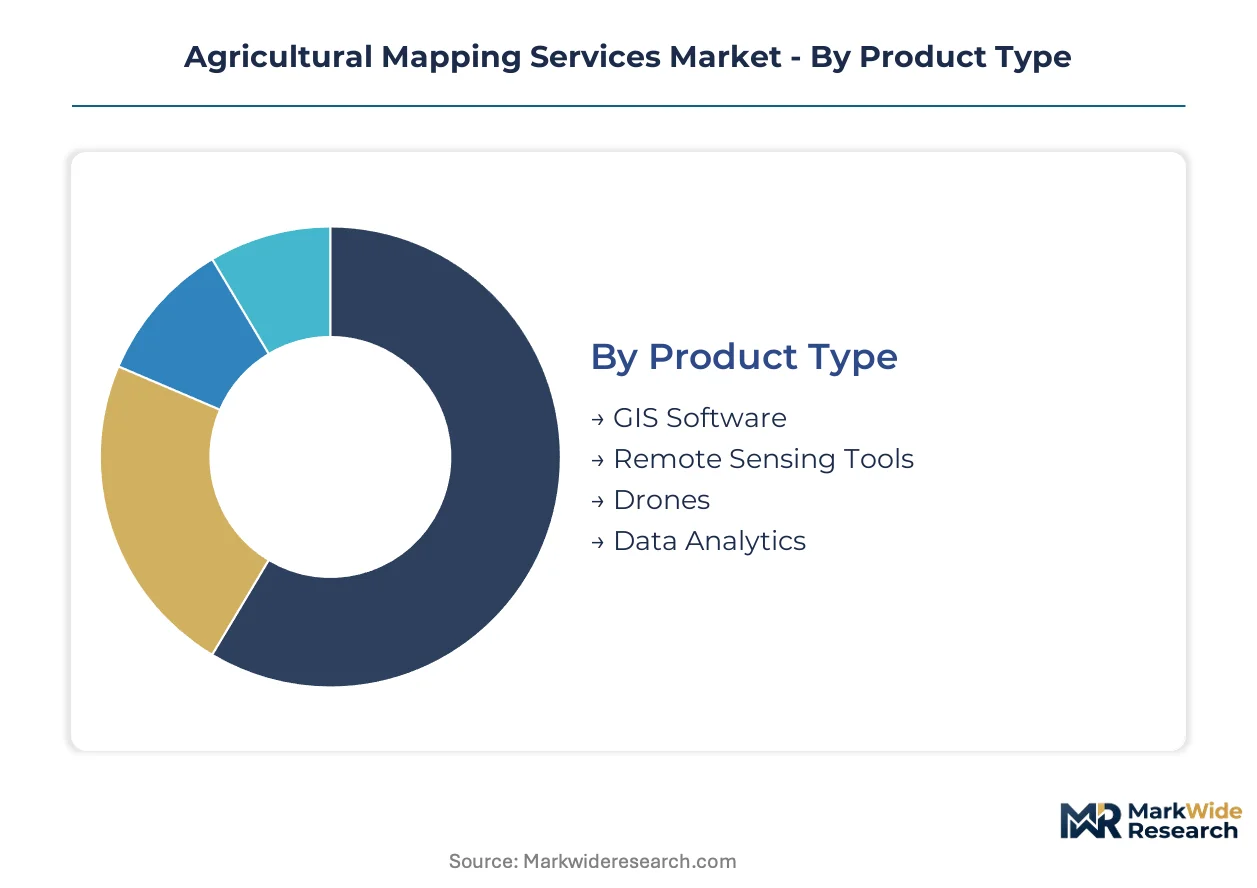
Segmentation in agricultural mapping services reveals divergent margin structures across product delivery modes and customer willingness-to-pay. Service providers calibrate pricing and support intensity based on whether the end-user operates as a direct farmer subscriber or a consultant-led bundled service.
Product Type:
After-sales service intensity varies sharply across product categories, with hardware-dependent segments requiring field maintenance networks while software platforms shift toward remote support models.
- GIS Software:Geospatial information systems provide the foundational layer for field boundary delineation, prescription map generation, and multi-year yield database management. Demand concentrates among agricultural consultants in Brazil's Mato Grosso soybean belt who require sub-meter accuracy for variable-rate input application. These users command premium pricing through bundled advisory services that integrate mapping outputs with procurement recommendations.
- Remote Sensing Tools:Multispectral and hyperspectral imaging platforms capture vegetation indices including NDVI for crop health assessment across large acreages. Carbon credit verification protocols in the European Union are intensifying sampling density requirements, driving fastest-growing adoption among soil analysis service providers restructuring field protocols to eliminate F-Gas-dependent equipment.
- Drones:UAV hardware enables sub-hourly revisit times for targeted field zones with centimeter-scale resolution. FAA Part 107 waiver complexity restricts fleet scalability for commercial operators seeking beyond-visual-line-of-sight coverage.
- Data Analytics:Cloud-based agronomy platforms transform raw sensor feeds into actionable prescription maps and yield forecasts. Recurring subscription models are displacing perpetual licenses as fleet operators capture margin pools through annual recurring revenue structures.
Remote Sensing Tools holds the largest share; momentum sits with Data Analytics.
End User:
Customer type determines pricing architecture, with direct farmer subscriptions competing against consultant-mediated bundled offerings that capture premium positioning through integrated advisory.
- Farmers:Direct subscribers typically operate large-scale commercial holdings with capital budgets for precision agriculture hardware. Procurement concentrates in Australia's wheat belt and the US Corn Belt where farmer cooperatives negotiate direct SaaS contracts bypassing machinery dealerships.
- Agricultural Consultants:Independent agronomy practices and dealer networks integrate mapping outputs with input procurement and field advisory. Carbon credit verification mandates across Germany and France are expanding consultant-led service penetration as farmers outsource compliance documentation.
- Government Agencies:Public sector procurement supports subsidy administration, land registry maintenance, and environmental monitoring programs. EU Common Agricultural Policy satellite monitoring requirements now mandate geospatial compliance for direct payment eligibility.
- Research Institutions:Academic and extension service users demand open data formats and interoperability with legacy analytical pipelines. ISO geographic information quality assurance standards create baseline compliance barriers for smaller service providers lacking certification infrastructure.
Farmers hold the largest share; momentum sits with Agricultural Consultants.
Technology:
Technology selection reflects trade-offs between spatial resolution, temporal frequency, and capital intensity, with platform choice constraining downstream service margin potential.
- Satellite Imagery:Constellation-based platforms provide daily revisit capability at 10-30 meter native resolution, suitable for regional crop condition monitoring. EU Green Deal mandates are accelerating procurement cycles among grain trading houses requiring supply chain visibility.
- LiDAR:Laser ranging systems generate high-density elevation models for drainage planning and erosion control. Terrain characterization demand is climbing fastest for carbon inventory verification requiring precise volumetric soil carbon estimates.
- UAV Technology:Drone-mounted sensors deliver sub-decimeter resolution with on-demand scheduling flexibility. Evolving national airspace classifications create compliance uncertainty for cross-border service providers.
- IoT Sensors:Ground-based networks provide continuous soil moisture and microclimate monitoring at fixed locations. Integration friction with cloud-based agronomy platforms limits deployment in older machinery fleets with proprietary terminal equipment.
Satellite Imagery holds the largest share; momentum sits with UAV Technology.
Application:
Application focus determines data product specifications, with regulatory pressure on carbon accountability reshaping soil analysis service lines toward verification-grade sampling protocols.
- Crop Monitoring:Vegetation index time series enable early detection of biotic stress, nutrient deficiency, and irrigation anomalies. Large grain trading houses are adopting hyperspectral platforms at accelerated procurement cycles to discriminate between stress factors invisible to traditional NDVI.
- Soil Analysis:Spatially explicit productivity zone characterization supports variable-rate lime, fertilizer, and seed application. EU F-Gas Regulation restrictions on invasive sampling methods are promoting non-invasive electromagnetic induction and gamma radiometrics alternatives.
- Land Use Planning:Cadastral mapping and field boundary documentation support subsidy eligibility and property transaction due diligence. GNSS correction infrastructure concentration creates supply bottlenecks in remote agricultural corridors lacking ground-based reference stations.
- Precision Agriculture:Integrated platforms combine multiple data streams for automated variable-rate application control. After-sales service unbundling is separating hardware maintenance from agronomic intelligence access across dealer networks.
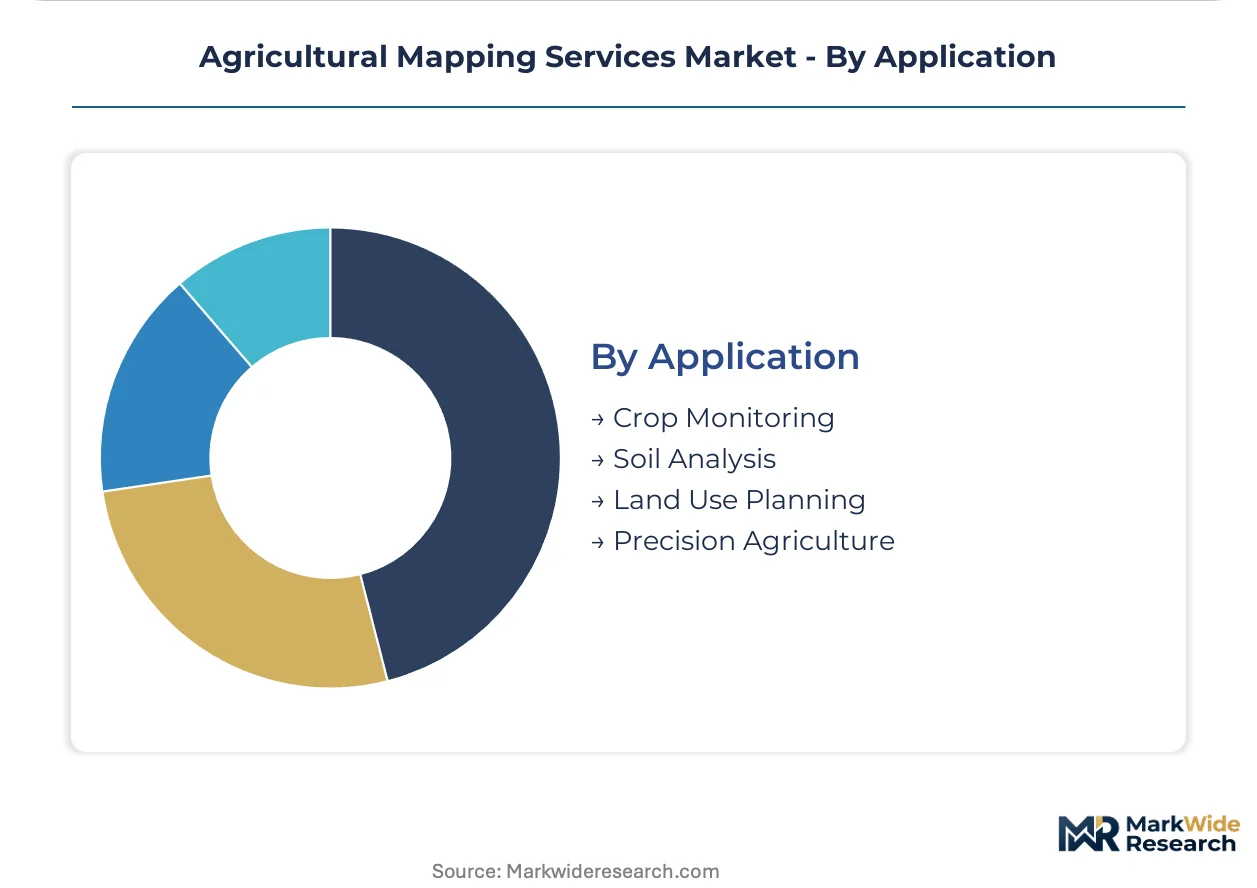
Precision Agriculture holds the largest share; momentum sits with Soil Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-accuracy field boundary mapping concentrates where ground-based GNSS correction infrastructure overlays major grain corridors. Service providers cluster around subsidy administration hubs and carbon credit verification zones where regulatory compliance mandates geospatial documentation.
United States
Large-scale commercial farming operations in the Corn Belt drive precision agriculture platform procurement. FAA Part 107 waivers govern beyond-visual-line-of-sight drone surveys, creating certification bottlenecks for fleet operators. Farmer cooperatives across Iowa and Illinois negotiate direct SaaS contracts that bypass traditional machinery dealerships.
Brazil
Agribusinesses across the Mato Grosso soybean belt deploy drone service networks and localized data processing centers. ANVISA and national aviation regulators classify commercial UAV airspace, shaping compliance requirements for cross-border service providers. Field-level digitization concentrates in the Cerrado frontier where input cost optimization commands premium pricing.
Germany
Soil Analysis service providers restructure field protocols to eliminate F-Gas-dependent equipment from carbon inventory workflows. The EU Green Deal and Common Agricultural Policy satellite monitoring mandates force geospatial compliance for direct payment eligibility. Bavarian and Lower Saxony farming operations outsource compliance documentation to consultant-led bundled services.
Australia
Wheat belt farmer cooperatives drive after-sales service unbundling, separating hardware maintenance from agronomic intelligence access. The country's national aviation regulator governs commercial drone operations across vast pastoral holdings. Regional grain trading houses in Western Australia adopt hyperspectral platforms for supply chain visibility.
France
Carbon credit verification protocols intensify demand for electromagnetic induction and gamma radiometrics soil property inference. EU F-Gas Regulation restrictions on invasive sampling methods promote non-invasive remote sensing alternatives. Agricultural consultants across the Île-de-France and Auvergne-Rhône-Alpes regions capture premium pricing through integrated advisory and input procurement.
Agricultural Mapping Services Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor hardware and correction services. The vendor base stratifies across three tiers: diversified agriculture technology conglomerates with captive distribution, independent geospatial software houses, and fleet-based drone service operators. Two strategic archetypes dominate: backward-integrated machinery OEMs bundling display hardware with cloud subscriptions, and specialized data analytics providers selling agronomy-as-a-service. Competitive moves concentrate on M&A for GNSS infrastructure assets and partnerships bridging legacy terminal equipment with cloud-native platforms.
Among diversified technology conglomerates, Trimble Inc. and John Deere exemplify contrasting integration strategies. Trimble anchors high-accuracy field boundary mapping through its GNSS correction infrastructure across South American grain corridors. John Deere occupies a position defined by backward integration into display hardware and cloud-based agronomy platforms. Hexagon AB represents the specialized geospatial software archetype, extending into soil variability analytics and prescription mapping tools without captive machinery distribution.
| Leading Market Players |
|---|
| Trimble Inc. |
| John Deere |
| Hexagon AB |
| Topcon Corporation |
| AG Leader Technology |
| SoilOptix |
| TARANIS |
| The Sanborn Map Company |
| Airbus |
| Others |
Supply Flow & Price Mechanics
Mato Grosso's drone service network expansion concentrates high-accuracy mapping capacity in Brazil's soybean belt, translating upstream hardware density into downstream pricing leverage for field-level data subscriptions. The EU Green Deal's satellite monitoring mandates and Brazil's ANVISA airspace classifications collectively reshape procurement economics across both regulatory jurisdictions.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for agricultural mapping services across European member states. Three-tier pricing structure across premium, standard, and economy levels separates consultant-led bundled advisory from direct farmer SaaS subscriptions and basic hardware-only procurement. Cost compression in economy tiers is intensifying because multispectral sensor cost volatility limits addressable market penetration outside large-scale commercial holdings. Direct farmer subscribers in Australia's wheat belt exhibit highest price sensitivity, while agricultural consultants capturing carbon credit verification mandates command premium positioning.
Supply Chain Analysis
Multispectral and hyperspectral sensor manufacturing draws from Taiwan, South Korea, and USA fabrication capacity. GNSS correction infrastructure components and electromagnetic induction equipment for soil analysis rest on specialized semiconductor and precision optics feedstocks. Single-source vulnerability concentrates in ground-based reference station networks for high-accuracy field boundary mapping. Distribution runs through dealer networks and independent agronomy consultancies unbundling after-sales service from hardware maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified GNSS correction infrastructure and FAA Part 107 waiver processing capacity constrains service expansion velocity. Firms controlling these bottleneck assets capture disproportionate margin pools.
For Market Incumbents: Insulate high-accuracy field boundary mapping dominance through captive GNSS correction infrastructure expansion across South American grain corridors. Invest in ISO geographic information quality assurance certification to filter smaller competitors from subsidy-eligible procurement channels. Defensive consolidation of drone service networks in Brazil's Cerrado frontier counters emerging fleet operators. For New Entrants and Emerging Players: Pursue soil analysis service line penetration where carbon credit verification protocols intensify sampling density requirements fastest. Target consultant-led bundled services in Germany and France where EU F-Gas Regulation restrictions eliminate traditional competitors. Lead with electromagnetic induction and gamma radiometrics non-invasive alternatives to bypass F-Gas-dependent equipment barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among data analytics providers shifting from hardware sales toward agronomy-as-a-service platforms. Long-term viability centers on annual recurring revenue structures displacing perpetual licenses across the projection horizon. Acquisition focus: specialized geospatial software houses with soil variability analytics capability. Signal to watch: FAA Part 107 waiver approval velocity as fleet scalability inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| GNSS Infrastructure Acquisition | Captures bottleneck assets for high-accuracy field boundary mapping across Brazilian grain corridors. |
| Carbon MRV Protocol Certification | Unlocks premium pricing for soil analysis services under EU Green Deal verification mandates. |
| SaaS Platform Migration | Transforms transactional hardware revenue into annual recurring data subscription models. |
| Consultant Network Partnership | Accesses bundled service premium pricing through agricultural advisory integration. |
| Non-Invasive Sensor Deployment | Eliminates F-Gas-dependent equipment from field protocols ahead of regulatory restrictions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA regulatory filings, EU Common Agricultural Policy documentation, and ANVISA airspace classifications. Interviews with precision agriculture platform executives, agricultural consultant practice leads, drone fleet operators, and carbon credit verification specialists anchor demand-side intelligence. Customs data on multispectral sensor imports, SEC 10-K filings from diversified agriculture technology conglomerates, and ISO certification registries provide supply-side validation. Bottom-up service provider capacity estimates triangulate against top-down subsidy administration budget allocations.
Forecast inputs include technology adoption curves across satellite imagery, UAV, and IoT sensor platforms, regulatory compliance deadline schedules, and carbon credit pricing trajectories. Segmentation dimensions span product type, end user archetype, technology platform, and application focus across the analysis window. CAGRs derive from installed base growth rates and annual recurring revenue conversion patterns. Industry-specific inputs incorporate FAA Part 107 waiver approval timelines and EU F-Gas Regulation implementation phases.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, carbon credit market liquidity, or grain export demand would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology cost reduction curves. Cross-checking against national aviation regulator waiver statistics and EU subsidy disbursement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Digital Farming Technology Market