
 Europe Vertical Farming Market | 2026-2036
Europe Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vertical Farming Market Intelligence
The unbundling of produce sales from farm operation services is decoupling crop price volatility from long-term contracts for European buyers. Infarm specializes in this model, deploying its modular units directly within grocery stores and restaurants across Germany and France. Jones Food Company, in contrast, leverages its large-scale plant factories in the UK to supply retailers with high-volume, private-label leafy greens.
Vertical farming is a method of controlled-environment agriculture where crops are cultivated in vertically stacked layers. These systems utilize soilless cultivation techniques and artificial lighting, often LED, to control all environmental variables and optimize plant growth year-round. Hydroponics remains the dominant production system due to its maturity and scalability, while aeroponics shows significant growth potential because of its water efficiency. Leafy greens and herbs constitute the largest crop type categories, driven by their short growth cycles and high demand from retailers.
The European Food Safety Authority (EFSA) sets standards for food safety and novel foods, which directly impacts the marketability of vertically farmed produce. Initiatives under the EU Green Deal, particularly the Farm to Fork strategy, provide a supportive policy framework by promoting sustainable and local food production. The primary decision for operators now revolves around balancing high-capital, centralized plant factories against decentralized, in-store farming models to serve different European markets.
Market Dynamics
The central tension in the European market is the strategic choice between large, centralized plant factories and decentralized, in-store farming units. This decision is influenced by the EU's Farm to Fork strategy, which prioritizes local and sustainable food production.
Growth Catalysts
- EU Policy Support:The Farm to Fork strategy incentivizes short supply chains and reduced pesticide use, directly benefiting vertical farming's business model.
- Food Service Demand:European food service providers require a consistent, year-round supply of fresh produce that is independent of seasonality.
- LED Technology:Advances in LED lighting efficiency are lowering key operational costs while improving crop yields and quality for growers.
Market Restraints
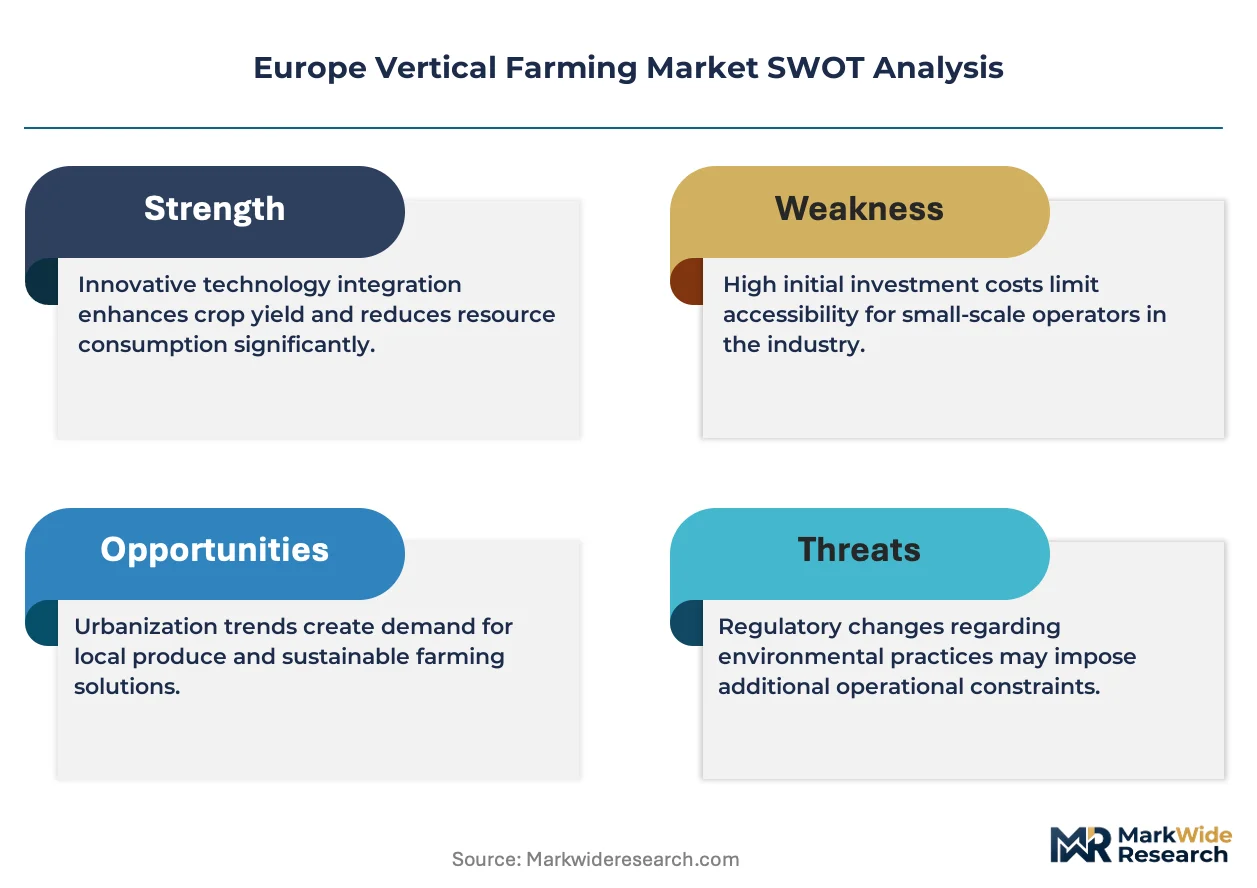
- High Capital Intensity:The substantial upfront investment required for automated climate control, lighting, and racking systems presents a significant barrier to entry for new operators in the European market.
- Energy Price Vulnerability:Heavy reliance on electricity for lighting and HVAC exposes farms to volatile energy markets, a critical operational risk, especially in regions with high power costs.
- Limited Crop Portfolio:Economic viability is currently concentrated in high-margin leafy greens and herbs, with staple crops remaining largely unfeasible due to technical and cost constraints.
Strategic Opportunities
- Crop Diversification:There is significant potential in cultivating high-value niche products like strawberries, saffron, or pharmaceutical-grade botanicals to command premium prices and enter new markets.
- Eastern Europe Expansion:Underpenetrated markets in Eastern Europe present an opportunity for growth, addressing urban demand for fresh produce where traditional agricultural supply chains may be weaker.
- AI-Driven Optimization:Integrating artificial intelligence to dynamically manage lighting, nutrient, and climate recipes can maximize yield and resource efficiency, creating a competitive advantage for operators.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel with combined expertise in plant science, data analytics, and engineering hinders operational efficiency and innovation across European facilities.
- Regulatory Fragmentation:Navigating the varied food safety and organic certification standards across different EU member states complicates market access and adds administrative overhead for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vertical Farming Market |
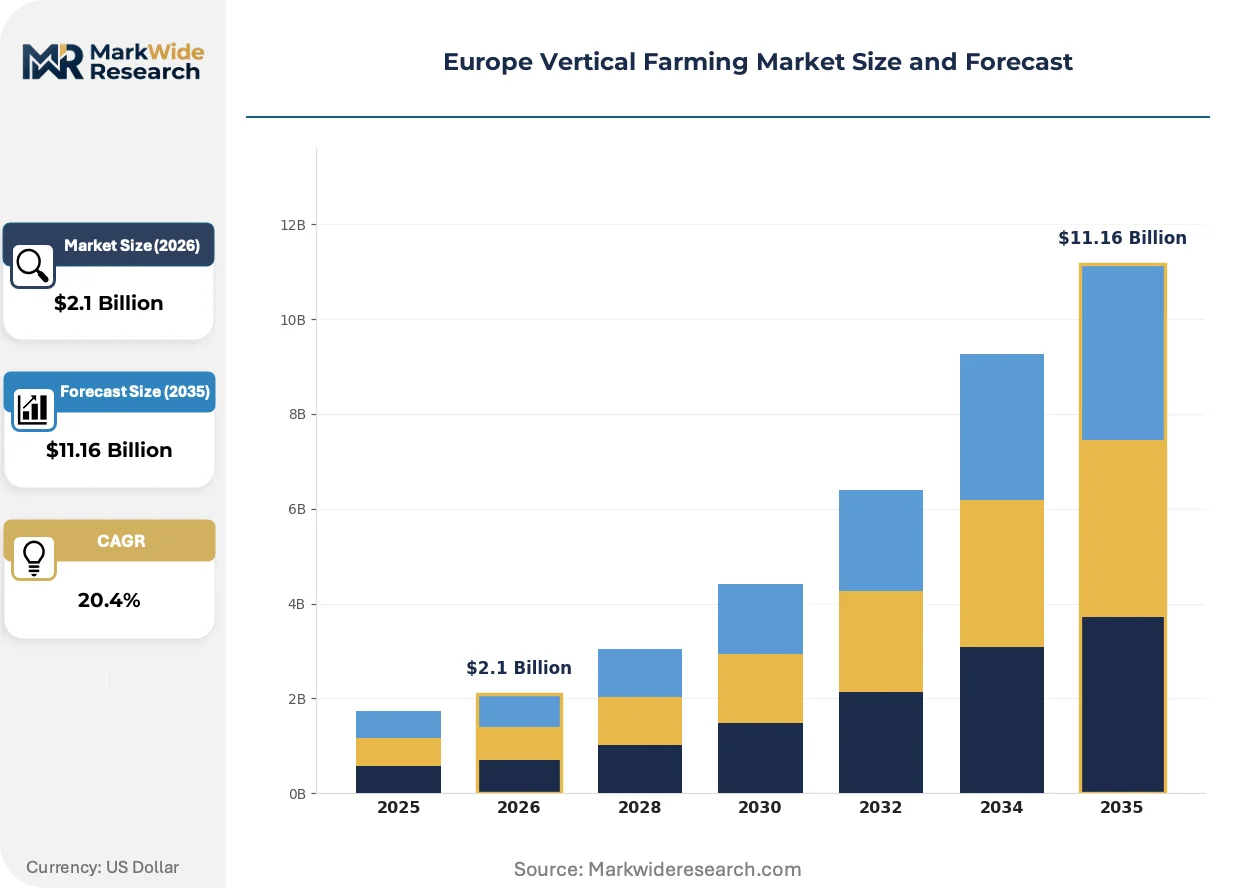
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $11.16 Billion |
| CAGR (2026 – 2036) | 20.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Farms, Greenhouses, Plant Factories, Shipping Container Farms, Aquaponics Systems Crop Type: Leafy Greens, Herbs, Microgreens, Fruiting Vegetables, Edible Flowers Production System: Hydroponics, Aeroponics, Aquaponics, Soil-Based Cultivation, Fogponics End User: Retailers, Food Service Providers, Wholesalers, Specialty Growers, Exporters |
| Companies Covered | Urban Crop Solutions, GrowGroup IFS, Infarm, Valoya, Planet Farms, Jones Food Company, Nordic Harvest, iFarm, AeroFarms, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vertical Farming Market Strategic Shifts & Innovations
Technological advancement is enabling new business models that unbundle farm operations from crop marketing, allowing for more specialized and risk-mitigated contracts. This separation is redefining the relationship between growers, retailers, and food service providers in Europe.
Aeroponics, a cultivation method misting roots with nutrient-rich vapor, offers superior water efficiency over hydroponics. Specialized growers of high-value botanicals adopt it for precise nutrient control. This technology is expanding into the cultivation of common leafy greens, challenging the dominance of hydroponic systems in large-scale European facilities.
The EU's Farm to Fork strategy, a pillar of the European Green Deal, sets targets for sustainable food production. This policy creates a favorable market for vertical farms, which avoid pesticides and use less water. Producers of leafy greens in Germany and the Netherlands leverage these credentials to gain preferential access to retail channels.
A significant behavioral shift involves unbundling farm operation services from the direct sale of produce. This model displaces the traditional grower-seller approach by allowing long-term service contracts independent of crop price volatility. The trend is most prominent in German and French retail, where grocers seek supply stability and predictable operational costs.
Europe Vertical Farming Market Segmentation
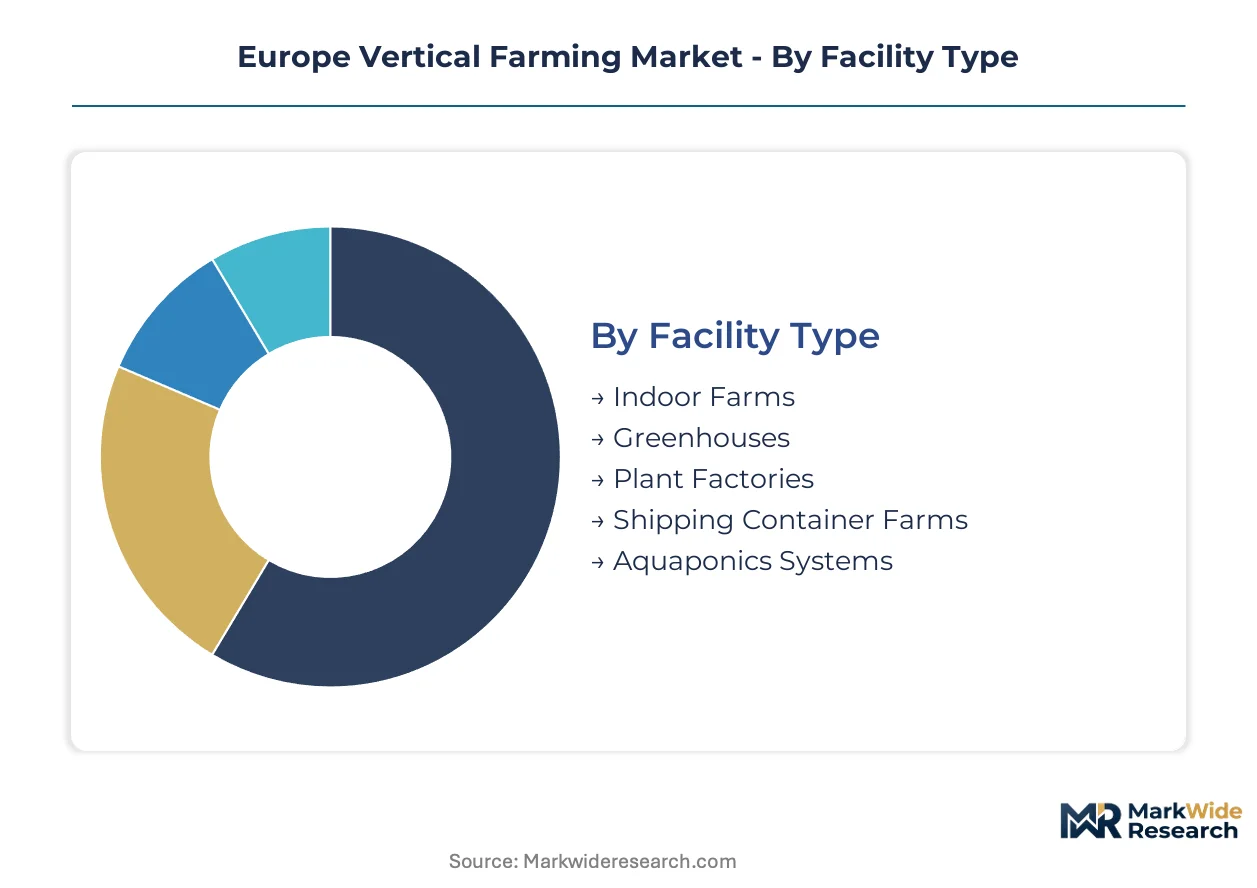
The European vertical farming market exhibits diverse operational models and strategic priorities, necessitating a granular segmentation to understand its complex dynamics. Analyzing these segments provides clarity on where investment flows, which technologies gain traction, and how different end-user needs shape production.
Facility Type:
Regulatory burdens and certification requirements significantly influence the operational models across various facility types in European vertical farming.
- Plant Factories:These are large-scale, highly automated, climate-controlled facilities optimizing crop growth through advanced environmental management systems. They supply high-volume private-label leafy greens to European retailers, driven by consistent quality needs and year-round availability.
- Indoor Farms:These controlled-environment agriculture setups operate within existing buildings or dedicated structures, often featuring modular and scalable designs. They serve localized demand from food service providers and specialty retailers across Germany and France, valuing fresh, local produce.
- Greenhouses:These facilities integrate vertical layers into traditional greenhouse structures, enhancing land use efficiency and leveraging natural light while maintaining environmental control in the Netherlands.
- Shipping Container Farms:Modular, portable units repurposed from shipping containers, providing hyperlocal production capabilities for urban centers and remote areas in the UK.
- Aquaponics Systems:Combine aquaculture (raising aquatic animals) with hydroponics, creating a symbiotic environment for sustainable, integrated food production in Scandinavia.
Plant Factories sit at the top of the volume ranking, with Shipping Container Farms climbing the fastest.
Crop Type:
The economic viability of vertical farming operations in Europe often hinges on the crop's margin profile and cultivation cycle.
- Leafy Greens:This category includes varieties like lettuce, spinach, and kale, characterized by short growth cycles, high yield density, and consistent consumer demand. They constitute the largest crop category for European retailers, driven by year-round consumer preference and ease of cultivation.
- Herbs:These are aromatic plants such as basil, mint, and cilantro, grown for culinary and sometimes medicinal purposes, commanding premium prices. They are highly sought after by European food service providers for consistent quality and availability, reducing supply chain variability.
- Microgreens:Young vegetable greens harvested shortly after cotyledon leaves have developed, valued for their intense flavor, nutritional density, and aesthetic appeal in European fine dining.
- Fruiting Vegetables:Crops like strawberries and cherry tomatoes, requiring more energy and longer growth cycles, represent a high-value niche in Scandinavian vertical farms.
- Edible Flowers:Specialty produce used for garnishing and culinary aesthetics, finding demand in premium European restaurants and catering services.
Demand for leafy greens and herbs heavily influences the current production capacity across European vertical farms.
Production System:
Technology maturity and resource efficiency define the adoption patterns of various production systems within the European market.
- Hydroponics:This soilless cultivation method involves growing plants in nutrient-rich water solutions, often recirculated to conserve resources. It remains the dominant system in large-scale European vertical farms due to its proven scalability and established operational protocols.
- Aeroponics:This method grows plants in an air or mist environment without soil, using nutrient-rich vapor sprayed directly onto the roots. It shows significant growth potential in specialized European facilities, offering superior water efficiency and precise nutrient control for high-value botanicals.
- Aquaponics:Integrates aquaculture (raising fish or other aquatic animals) with hydroponics, creating a symbiotic environment where fish waste fertilizes plants in Germany.
- Soil-Based Cultivation:Utilizes traditional soil mediums in vertically stacked layers, often for niche or experimental crops in smaller European setups that prioritize organic certification.
- Fogponics:A variant of aeroponics using ultrasonic transducers to create a fine mist for nutrient delivery, enhancing root oxygenation in advanced Dutch systems.
Resource efficiency remains a primary driver for the evolution of production systems, with aeroponics gaining traction for its water-saving attributes.
End User:
Procurement patterns and demand for consistent, fresh produce differentiate the requirements of various end-user segments across Europe.
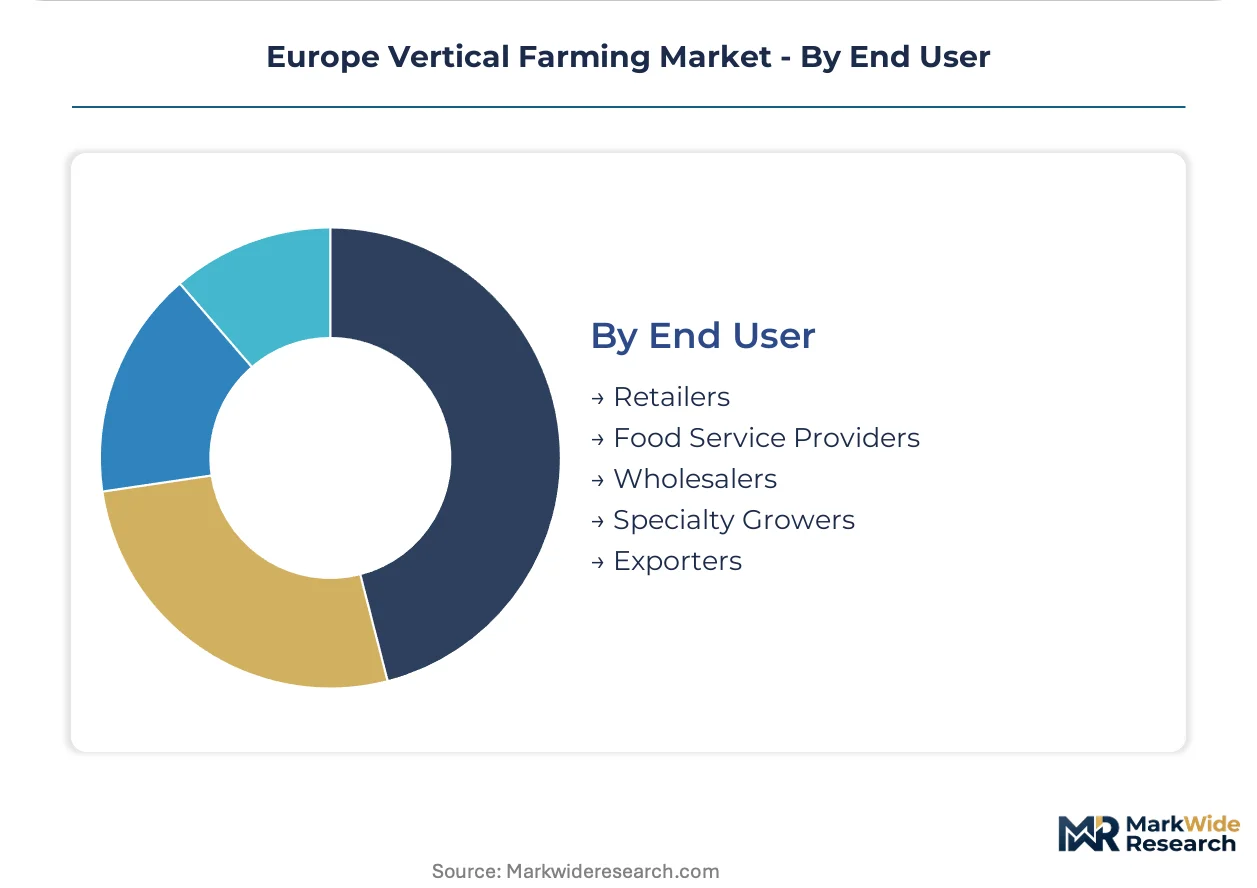
- Retailers:This segment includes large supermarket chains and grocery stores requiring high volumes of consistent, often private-label, produce. They drive demand for large-scale vertical farms in the UK and Germany, seeking stable supply chains and reduced price volatility.
- Food Service Providers:Comprising restaurants, hotels, and catering companies, this segment prioritizes freshness, local sourcing, and consistent quality for their culinary operations. They fuel the growth of decentralized and in-store vertical farming models across France and Italy, ensuring year-round availability of fresh ingredients.
- Wholesalers:These entities act as intermediaries distributing vertically farmed produce to smaller retailers, independent grocers, and institutions across diverse European markets.
- Specialty Growers:Focus on cultivating niche, high-value crops for specific markets or direct-to-consumer sales, often through farmers' markets or online platforms in Scandinavian countries.
- Exporters:Companies that grow and ship vertically farmed produce across national borders within the EU, leveraging logistical hubs in the Netherlands for efficient distribution.
Strategic focus for vertical farm operators often balances high-volume supply to retailers with the bespoke demands of food service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European vertical farming market's foundational growth began in the Netherlands, leveraging its advanced horticultural technology and logistics infrastructure. This initial scaling created a blueprint for controlled-environment agriculture across the continent. The EU's Farm to Fork strategy further amplifies this regional development, encouraging local, sustainable food production systems.
Netherlands
The Netherlands, with its advanced horticultural technology, drives significant demand for export-oriented high-value produce. The EU Green Deal initiatives and national policies strongly support resource-efficient cultivation techniques. The Westland region remains a global hub for horticultural innovation, concentrating research and development activities.
Germany
German retailers and food service providers require consistent, locally-sourced fresh produce, driving market expansion. EFSA standards for food safety directly influence marketability and consumer trust in new agricultural methods. Berlin is emerging as a critical center for vertical farming startups, concentrating investment in urban agricultural projects.
United Kingdom
Consumer demand for private-label leafy greens fuels large-scale plant factory operations across the United Kingdom. The UK's environmental policies encourage sustainable food production and reduced food miles for urban populations. London and its surrounding areas show a concentration of large-scale facilities supplying major supermarket chains.
France
French food service providers and specialty retailers prioritize fresh, local produce year-round, boosting decentralized models. The EU's Farm to Fork strategy incentivizes short supply chains and reduced pesticide use in agriculture. Paris and its adjacent agricultural regions are seeing increased adoption of in-store farming models for direct consumer access.
Scandinavia
Niche market demand for high-value fruiting vegetables and specialty botanicals drives innovation across Scandinavia. National food safety agencies uphold stringent quality controls for novel food products entering consumer markets. Urban centers like Copenhagen and Stockholm are developing aquaponics systems for sustainable protein and produce integration.
Europe Vertical Farming Market Key Industry Players
Premium-margin players sit above commodity-margin players across the European vertical farming value chain, differentiating through technology and crop specialization. The market exhibits a tiered structure, with large-scale plant factories competing with decentralized, in-store models. Strategic archetypes include high-volume producers, niche crop specialists, and technology solution providers. Companies primarily engage in capacity expansion and strategic partnerships to secure market share.
Within the high-volume production archetype, Jones Food Company exemplifies large-scale operations focused on supplying retailers with consistent leafy greens across the UK. Infarm, in contrast, anchors the decentralized, in-store farming model, deploying modular units directly within grocery stores and restaurants across Germany and France. Urban Crop Solutions represents a technology-driven approach, providing comprehensive solutions for controlled-environment agriculture facilities, often serving as a key enabler for other growers in the European market.
| Leading Market Players |
|---|
| Urban Crop Solutions |
| GrowGroup IFS |
| Infarm |
| Valoya |
| Planet Farms |
| Jones Food Company |
| Nordic Harvest |
| iFarm |
| AeroFarms |
| Others |
Cost & Logistics Intelligence
Aeroponics, a cultivation method offering superior water efficiency, simultaneously reshapes cost economics for specialized growers and influences supply concentration towards high-value botanicals. This transition impacts resource allocation and market positioning across Europe.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing in the European vertical farming market. Price differentiation stems from consistent quality grades and the volume scale required by large retailers. Pricing pressure intensifies due to energy price vulnerability, especially for large-scale plant factories. Retailers exhibit high price sensitivity, seeking stable supply chains, while food service providers prioritize consistent quality and local sourcing over absolute lowest price.
Supply Chain Analysis
Regional distribution centers support high-volume supply to retailers, while localized hubs serve decentralized models. Supply concentrates in the Netherlands, leveraging its advanced horticultural technology and logistics infrastructure, alongside large-scale plant factories in the UK and Germany. The supply chain relies heavily on specialized LED lighting and nutrient solutions as key inputs. Regulatory fragmentation across diverse EU member states presents a structural risk for market access, impacting direct-to-retailer and direct-to-food-service distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European vertical farming market presents a late-cycle quality story, as demand shifts towards premium specifications for high-value botanicals and specialty produce. This trend emphasizes consistent quality and precise cultivation methods.
For Market Incumbents:Acquire AI optimization platforms to enhance resource efficiency and reduce operational costs across existing facilities. Consolidate smaller indoor farms to gain economies of scale against energy price vulnerability. Invest in R&D for crop diversification, moving beyond leafy greens to high-value botanicals, mitigating market saturation risks. Strengthen supply chain partnerships with European retailers to secure long-term off-take agreements.
For New Entrants and Emerging Players:Launch via direct-to-consumer models in underserved urban centers, particularly in Eastern Europe, addressing demand for fresh produce. Target high-value niche products like saffron or pharmaceutical botanicals, which command premium prices and offer higher margins. Eastern European urban centers represent the most penetrable geography due to weaker traditional agricultural supply chains. Focus on a local sourcing go-to-market angle for food service providers, emphasizing freshness and sustainability credentials.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized technology solution providers offering AI-driven optimization and advanced aeroponics systems. The long-term viability of this market hinges on continued progress towards sustainable food systems over a five-to-ten year window. Target acquisition archetypes include firms with strong intellectual property in controlled-environment agriculture or established decentralized in-store models. Watch for significant advances in energy storage solutions as a key inflection indicator for operational cost reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Eastern Europe | Addresses urban demand in Eastern Europe where traditional agricultural supply chains are weaker. |
| Crop Diversification into Botanicals | Unlocks premium pricing for high-value niche products like pharmaceutical-grade botanicals. |
| AI Integration for Environmental Control | Maximizes yield and resource efficiency by dynamically managing lighting and nutrient recipes. |
| Aeroponics System Adoption | Offers superior water efficiency and precise nutrient control for specialized European facilities. |
| Strategic Partnerships with Retailers | Secures long-term contracts and stable supply chains for large-scale plant factories in the UK. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative data — were reconciled to construct a comprehensive market view. Primary engagement included plant scientists, data analytics specialists, engineering leads, and food service procurement managers across Europe. Secondary validation leveraged EFSA reports, EU Green Deal policy documents, national horticultural statistics, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Historical data was cross-referenced against expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation by facility type, crop type, production system, end user, and regional market. Compound annual growth rates were derived through a regression analysis of identified market drivers. Key industry-specific forecast inputs included LED lighting efficiency advancements and European energy price volatility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or rapid technological breakthroughs. Forecasts reflect a documented set of assumptions regarding market dynamics and policy environments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
North America Indoor Farming Market