
 Vertical Farming Lighting Market | 2026-2036
Vertical Farming Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Farming Lighting Market Analytics
Modular rack-mounted lighting arrays is shifting buyer preference away from fixed-installation systems toward reconfigurable LED bars that operators can reposition across crop cycles. Signify leverages its Philips Horticulture LED platform to dominate European retrofit projects, while ams OSRAM anchors the premium full-spectrum segment through chip-level spectral engineering. Heliospectra AB differentiates with biologically tuned light recipes that target specific phenotypic responses in controlled environments.
Vertical farming lighting encompasses engineered photon-delivery systems that convert electrical energy into photosynthetically active radiation, typically operating within 400–700 nanometer wavelengths at photosynthetic photon flux densities exceeding 200 micromoles per square meter per second to accelerate crop turnover in soilless cultivation environments. LED product types now command the dominant margin pool as thermal efficiency and spectral programmability displace legacy high-pressure sodium installations across indoor facilities. Smart lighting technology represents the fastest-expanding segment, where integrated control systems enable real-time dimming responses to ambient conditions and crop-stage requirements, while hybrid installation configurations bridge greenhouse conversions toward fully enclosed vertical architectures.
The EU Green Deal and REACH frameworks enforce energy-efficiency benchmarks and substance restrictions on horticultural electronics sold within member states, compelling manufacturers to redesign driver circuits and thermal management systems for compliance. The US Department of Agriculture and FDA jointly oversee food-safety protocols in vertically farmed produce, indirectly shaping lighting specifications through sanitation-access requirements in growing environments. Stakeholders must monitor evolving spectral efficacy standards and carbon-border adjustment mechanisms that will determine which lighting suppliers retain access to premium regulated markets.
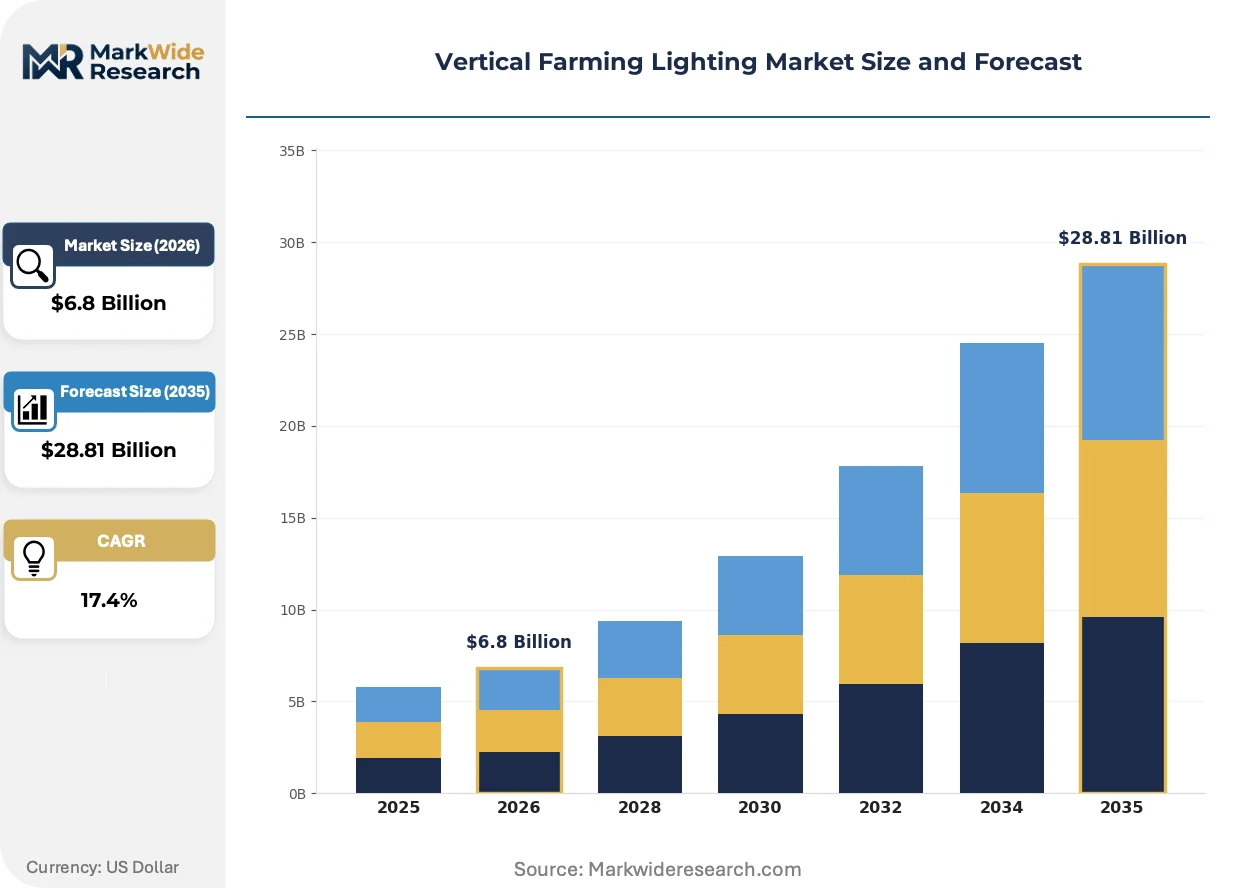
Market Dynamics
Spectral-tunable LED architectures are compressing crop-cycle economics for controlled-environment agriculture operators, forcing incumbent lighting suppliers to reengineer thermal management systems and driver electronics around EU Green Deal efficiency mandates.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Tightening horticultural energy benchmarks in member states accelerate LED retrofits across Dutch greenhouse-to-vertical-farm conversions.
- Leafy greens segment expansion:Controlled-environment operators in the Netherlands deploy reconfigurable rack-mounted arrays to maximize photon delivery per square meter.
- Spectral programmability:Chip-level engineering enables real-time wavelength tuning that matches photosynthetic photon flux density to crop-stage requirements.
Market Restraints
- Driver electronics cost volatility:Semiconductor supply concentration in East Asian foundries creates input price instability for power-conversion components.
- Thermal management complexity:High-density LED arrays require precision heat-sinking that exceeds legacy HVAC capacity in retrofitted facilities.
- REACH substance restrictions:ECHA limitations on certain thermal interface materials complicate European product certification timelines.
Strategic Opportunities
- Hybrid greenhouse conversion architectures:Bridge installations combining natural light supplementation with full-spectrum LED arrays capture transitional operators.
- Smart lighting integration:Convergence of IoT sensors and automated dimming protocols creates premium service attach rates for control-system vendors.
- Carbon-border adjustment mechanisms:Emerging EU import tariffs on carbon-intensive horticultural equipment favor low-carbon LED suppliers in regulated markets.
Industry Challenges
- Spectral engineering talent scarcity:Shortage of photobiologists capable of translating phenotypic targets into tunable light recipes delays product development cycles.
- Legacy HPS infrastructure incompatibility:Retrofit projects face electrical and structural reconfiguration costs when integrating LED arrays into existing racking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Farming Lighting Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HPS, Fluorescent, Induction Technology: Full Spectrum, Smart Lighting, Control Systems, Dimming Installation: Indoor, Greenhouses, Hybrid Systems, Container Farms End User: Agriculture, Retail, Research, Restaurants |
| Companies Covered | Signify, ams OSRAM, Heliospectra AB, Valoya, Everlight Electronics, Illumitex, Gavita International, OSRAM, Iwasaki Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Farming Lighting Market Evolving Landscape
Photon-delivery engineering is converging with digital control architectures, compressing the gap between spectral research and commercial deployment while reshaping how operators procure and reconfigure cultivation infrastructure.
Dynamic LED bar systems with magnetic mounting interfaces and standardized electrical connectors is modularizing vertical farm architecture. Dutch operators retrofitting clustered greenhouse facilities adopt these reconfigurable arrays to reposition lighting across lettuce, herb, and microgreen crop cycles without structural modification. The technology is modularizing capital deployment models, enabling phased capacity expansion and reducing stranded asset risk for multi-crop facilities.
REACH substance restrictions and EU Green Deal carbon-intensity benchmarks are tightening compliance requirements for horticultural electronics sold within member states. Manufacturers redesign thermal interface materials and driver circuit boards to eliminate restricted substances while maintaining efficacy ratings. European retrofit projects face extended certification timelines as suppliers validate redesigned components against evolving ECHA substance databases.
Buyer preference is consolidating around integrated lighting-control packages rather than component procurement. Dutch vertical farm operators now specify bundled spectral-tuning software, sensor networks, and maintenance protocols in single-vendor agreements. This bundling pattern concentrates procurement authority with facility engineering teams and compresses vendor qualification cycles for full-system suppliers.
Vertical Farming Lighting Market Segmentation
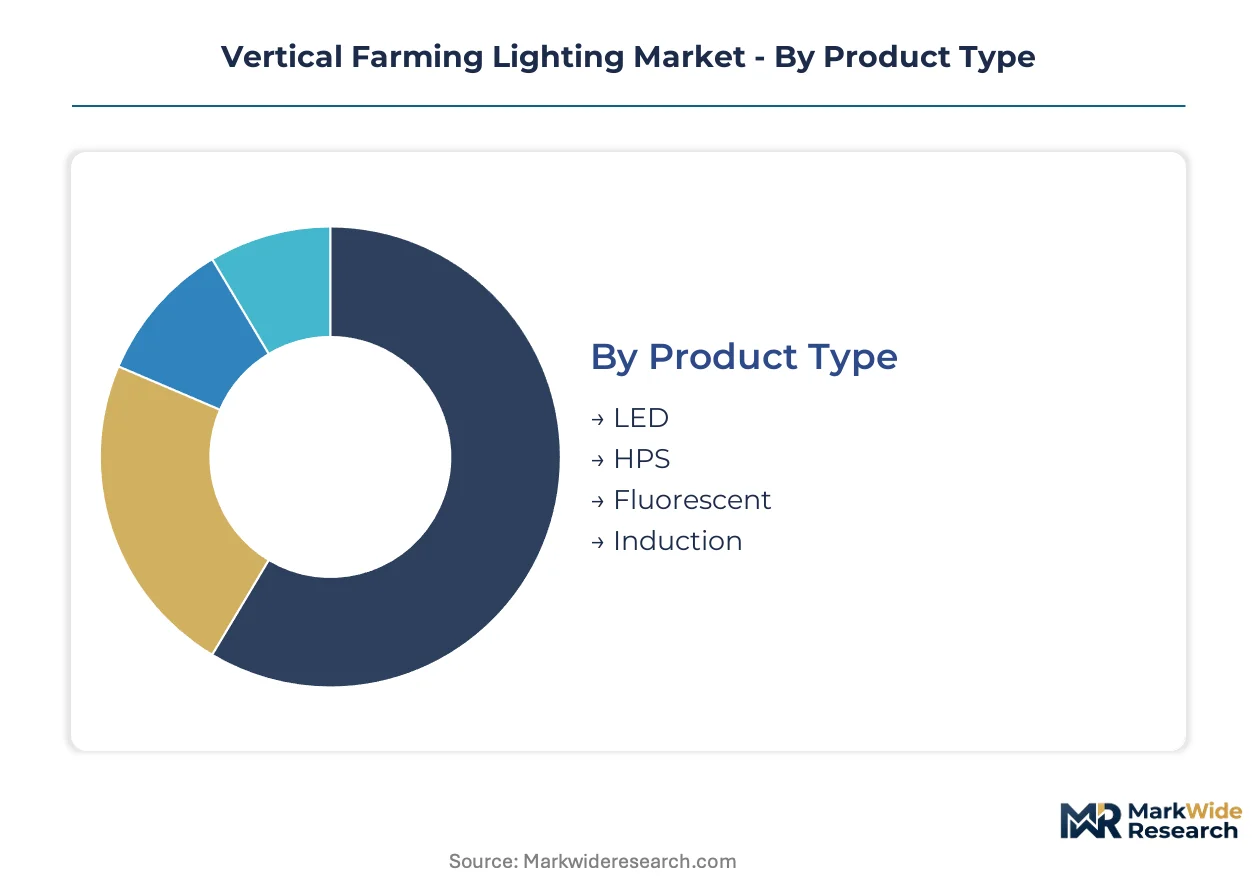
Segmentation in vertical farming lighting reveals how photon-delivery economics fragment across technology generations, installation architectures, and buyer sophistication. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor prioritization.
Product Type:
LED dominates volume deployment while legacy technologies retain niche premium positions in transitional installations.
- LED:Solid-state semiconductor arrays operating at 400–700 nanometer wavelengths with thermal efficiencies exceeding legacy alternatives. Dutch greenhouse-to-vertical-farm conversions deploy these for EU Green Deal compliance, though driver electronics cost volatility from East Asian foundry concentration squeezes margin stability.
- HPS:High-pressure sodium vapor lamps delivering broad-spectrum output with established horticultural efficacy benchmarks. Retrofit demand persists in North American facilities where electrical infrastructure amortization delays full LED replacement cycles.
- Fluorescent:Linear tube configurations offering lower capital entry points for research-scale installations and microgreen operations.
- Induction:Electrodeless discharge systems with extended operational lifespans, deployed primarily in pharmaceutical-grade cultivation requiring spectral consistency.
Mature deployment sits with HPS in legacy greenhouse infrastructure. Newer deployment is concentrated in LED arrays for Dutch and German vertical farm conversions.
Technology:
Smart capabilities command pricing premiums while basic spectral output commoditizes across supplier bases.
- Full Spectrum:Engineered wavelength combinations spanning photosynthetic and photomorphogenic activation bands. German research facilities and Dutch commercial operators prioritize these systems for phenotypic precision in leafy greens cultivation.
- Smart Lighting:IoT-integrated architectures enabling real-time dimming responses to ambient conditions and crop-stage requirements. These systems are expanding most quickly as Dutch operators bundle sensor networks with maintenance protocols in single-vendor procurement.
- Control Systems:Software platforms governing spectral scheduling and photoperiod management across multi-zone facilities.
- Dimming:Variable-output driver electronics allowing incremental photon flux adjustments without hardware reconfiguration.
Control system deployment concentrates in multi-crop commercial facilities. Dimming adoption is accelerating in research environments requiring protocol flexibility.
Installation:
Facility architecture determines thermal management requirements and natural light integration depth.
- Indoor:Fully enclosed vertical architectures with zero daylight penetration, requiring complete artificial photon coverage. These installations maximize rack density in Dutch urban facilities where land constraints drive cubic-meter productivity metrics.
- Greenhouses:Transparent envelope structures combining solar gain with supplemental LED arrays. Spanish and Italian operators favor these for energy cost mitigation under EU carbon-border adjustment exposure.
- Hybrid Systems:Bridge configurations enabling phased conversion from greenhouse to fully enclosed operation. Dutch clustered facilities deploy these to stranded asset risk across crop cycle transitions.
- Container Farms:Standardized shipping-container enclosures with integrated climate and lighting control. These units concentrate in Middle Eastern markets where arid conditions eliminate greenhouse viability.
Greenhouse installation retains the largest installed base. Container farm deployment is scaling fastest in water-scarce geographies lacking agricultural land.
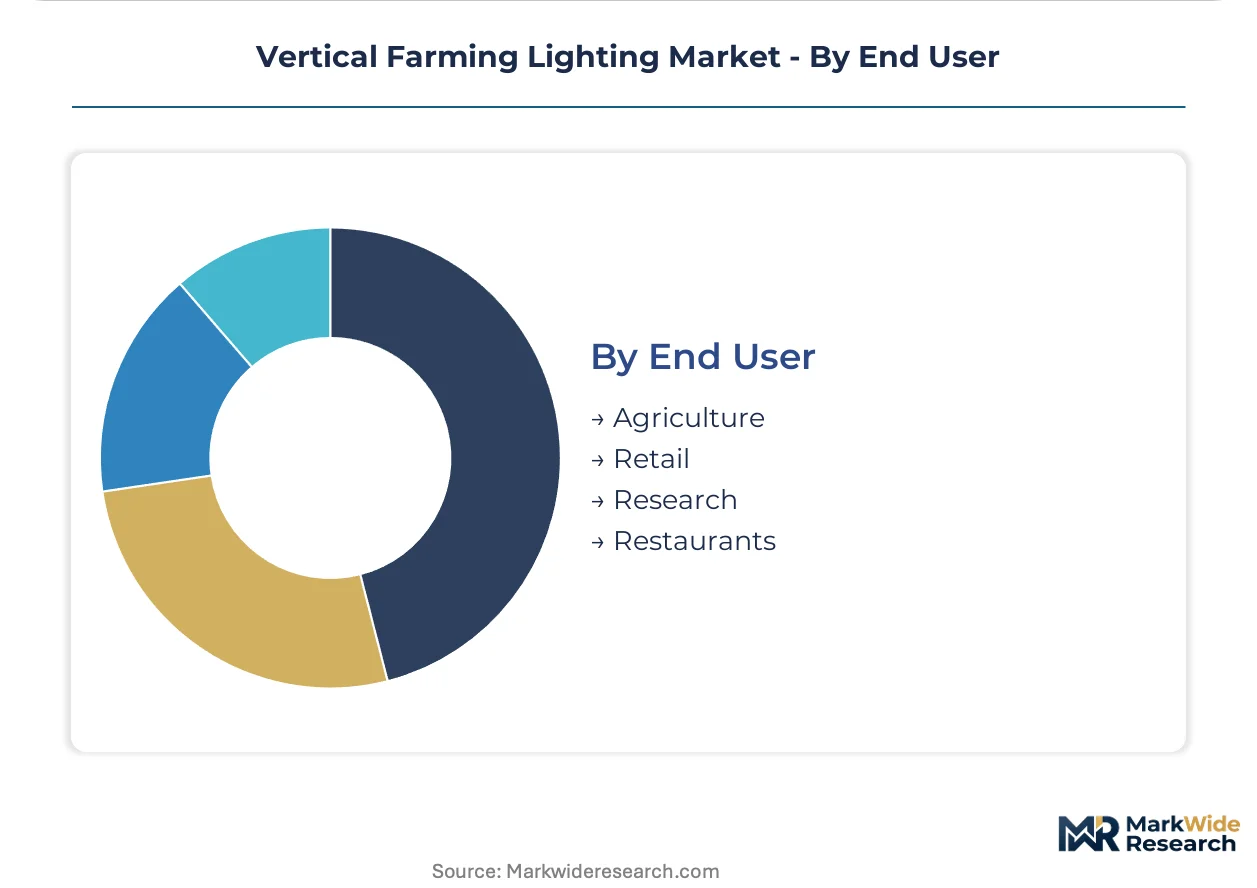
End User:
Buyer sophistication spans from production-scale agriculture to experience-driven food service.
- Agriculture:Commercial-scale controlled-environment operators optimizing yield-per-square-meter economics. Dutch leafy greens producers represent the core revenue concentration for spectral-tunable system vendors.
- Retail:Grocery chains and food retailers deploying in-store cultivation for supply chain compression and freshness marketing. These buyers prioritize standardized low-maintenance systems over configurable spectral platforms.
- Research:Academic and corporate R&D facilities investigating photobiological responses and cultivar optimization.
- Restaurants:Chef-driven establishments using visible cultivation for menu differentiation and ingredient provenance narrative.
Agricultural end users drive volume procurement and vendor qualification cycles. Restaurant adoption remains experimental with limited repeat purchase velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Dutch and German engineering clusters while consumption spreads across European retrofit sites and Middle Eastern container deployments. The Netherlands exports spectral-tunable systems to conversion projects in Belgium and Germany. UAE and Saudi operators import turnkey lighting packages for desert-adapted vertical farms.
Netherlands
Clustered greenhouse-to-vertical-farm conversions in Westland and Aalsmeer drive demand for reconfigurable LED arrays. EU Green Deal energy-efficiency mandates accelerate LED retrofits ahead of enforcement deadlines. Wageningen University partnerships with commercial operators test spectral recipes for lettuce and herb cultivars in controlled environments.
Germany
Research facilities in Bavaria and Baden-Württemberg procure full-spectrum systems for phenotypic precision studies. REACH substance restrictions force manufacturers to redesign thermal interface materials for ECHA compliance. Berlin-Brandenburg vertical farm startups source spectral-tunable arrays from domestic engineering suppliers.
United States
Retrofit demand persists in legacy greenhouse operations where electrical infrastructure amortization delays full LED replacement. USDA and FDA joint food-safety protocols shape lighting specifications through sanitation-access requirements. California and New York metro vertical farms deploy smart lighting with IoT-integrated control systems.
United Arab Emirates
Arid conditions eliminate greenhouse viability, concentrating container farm deployments with integrated climate and lighting control. NEOM Northwest development plans include large-scale vertical cultivation facilities. Dubai-based agritech ventures import standardized LED packages from European engineering suppliers.
China
Domestic LED chip manufacturing capacity supports cost-competitive module production for regional export. MIIT industrial policy encourages horticultural lighting R&D through targeted funding programs. Yangtze River Delta electronics clusters assemble driver electronics for supply to Southeast Asian vertical farm projects.
Vertical Farming Lighting Market Competitive Landscape
The competitive structure tilts toward technology-integrated specialists rather than component commodity suppliers. Two to three strategic archetypes dominate: full-system providers bundling hardware with spectral software, chip-level engineering houses controlling wavelength precision, and retrofit-focused integrators serving greenhouse conversion demand. M&A activity concentrates on sensor-network acquisitions and driver electronics vertical integration. Geographic expansion into Middle Eastern container farm markets represents the second dominant competitive move.
Among European lighting engineering specialists, Signify, ams OSRAM, and Heliospectra AB exemplify divergent positioning strategies. Signify occupies a position as a full-system provider leveraging established horticulture platforms. ams OSRAM represents the chip-level precision tier with spectral engineering capabilities. Heliospectra AB sits within the biologically-tuned specialization segment targeting phenotypic response optimization. These three anchors demonstrate how vendor qualification cycles in Dutch and German markets favor bundled procurement over component sourcing.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| Heliospectra AB |
| Valoya |
| Everlight Electronics |
| Illumitex |
| Gavita International |
| OSRAM |
| Iwasaki Electric |
| Others |
Value Network & Pricing Analysis
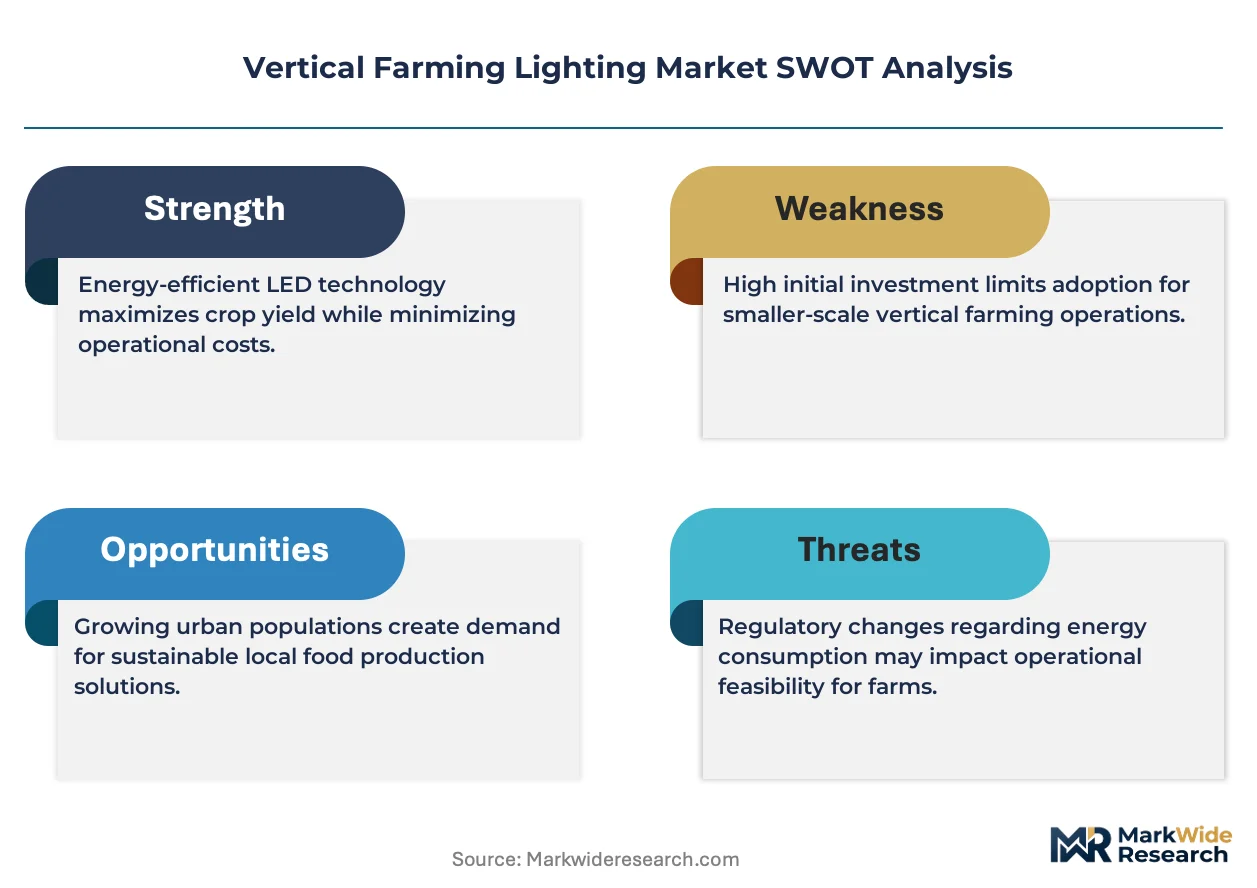
Certification-grade divergence between full-spectrum smart systems and basic LED arrays manifests in both procurement premiums and supply chain qualification depth, with EU Green Deal compliance tiers filtering vendor pools and compressing margin structures for non-compliant component suppliers.
Pricing Analysis
Margin tightening in basic LED modules reflects semiconductor foundry concentration in East Asian supply zones and REACH-driven thermal material redesign costs. Three-tier pricing structure across premium spectral-tunable, standard full-spectrum, and economy fixed-wavelength levels separates buyers by crop complexity and facility scale. Cost-down pressure on driver electronics accelerates because Dutch greenhouse operators now bundle lighting with sensor networks in single-vendor agreements. Research facilities show least price sensitivity, prioritizing phenotypic precision over capital efficiency.
Supply Chain Analysis
Dual-sourcing requirements for LED chips and driver electronics now dominate procurement protocols as buyers mitigate single-foundry exposure. Manufacturing gravity centers on China for chip fabrication, Taiwan for precision driver components, and the Netherlands for spectral engineering integration. Raw material dependencies span gallium nitride substrates, aluminum heat sinks, and copper winding stock. Tariff exposure on Chinese semiconductor imports creates structural vulnerability for cost-optimized suppliers. Distribution runs through Dutch engineering integrators serving clustered Westland conversions and direct OEM relationships with German research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU Green Deal energy-efficiency mandates and REACH substance restrictions erect technical barriers that favor incumbents with certified thermal management and validated spectral platforms.
For Market Incumbents: Cement platform dominance by acquiring sensor-network specialists to deepen IoT integration attach rates. Defend against modular LED bar entrants by locking multi-year maintenance protocols with Dutch greenhouse conversion clusters. Prioritize backward integration into driver electronics to buffer East Asian foundry volatility.
For New Entrants and Emerging Players: Begin with container farm deployments in Middle Eastern water-scarce markets where European incumbents lack established service infrastructure. Target UAE and Saudi agritech ventures seeking turnkey spectral packages. Pursue co-development partnerships with Yangtze River Delta electronics assemblers to access cost-competitive chip sourcing.
For Investors and Strategic Acquirers: Re-rating potential sits with biologically-tuned spectral specialists given phenotypic precision premiumization in leafy greens cultivation. Five-to-ten-year viability hinges on carbon-border adjustment mechanism positioning in EU markets. Monitor ECHA substance database updates as inflection signals for compliance-cost escalations that reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectral Software Platform Integration | Bundles sensor networks with maintenance protocols, concentrating procurement authority with Dutch facility engineering teams. |
| Driver Electronics Backward Integration | Captures margin pool and insulates against Taiwan foundry concentration risks in power-conversion components. |
| Hybrid Greenhouse Conversion Architecture | Bridges natural light supplementation with full-spectrum arrays, capturing transitional Dutch operators reducing stranded asset exposure. |
| Carbon-Border Adjustment Positioning | Aligns low-carbon LED certification with emerging EU import tariffs on carbon-intensive horticultural equipment. |
| Photobiology Talent Acquisition | Addresses spectral engineering scarcity by recruiting Wageningen-trained researchers capable of translating phenotypic targets into tunable recipes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with vertical farm operations directors, greenhouse conversion engineers, spectral platform product managers, and ECHA compliance officers at horticultural electronics manufacturers. Primary fieldwork combined with EU Green Deal implementation documents, ECHA substance restriction databases, and Dutch greenhouse energy-audit records enabled bottom-up facility deployment estimates triangulated against top-down LED import value flows.
Granularity-level modeling distinguished installation architecture, technology generation, and end-user sophistication across the projection horizon. Segment-specific CAGRs derived from facility conversion velocity in Dutch Westland and Aalsmeer clusters, spectral-tunable adoption curves in German research facilities, and container farm deployment scaling in UAE desert agriculture zones. Photon-efficacy improvement trajectories and driver electronics cost curves informed technology substitution assumptions.
Underlying measurement precision varies by segment; smart lighting and full-spectrum categories carry tighter precision than legacy HPS retrofit estimates due to bundled procurement opacity. Forecasts reflect documented assumptions on EU enforcement timelines and REACH substance restriction expansion. Deviation in ECHA thermal interface material rulings or carbon-border adjustment implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
GCC Grow Light Market