
 Global Infrared Heater for Agriculture Market | 2026-2036
Global Infrared Heater for Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infrared Heater for Agriculture Market Outlook
Aftermarket service revenue for greenhouse climate systems is reconfiguring how vendors capture lifetime value from infrared heater deployments. Gasolec leverages its European distribution network to sustain recurring calibration and replacement part contracts. Choretime anchors its competitive stance through deep specialization in poultry house infrared solutions across North American installations.
An infrared heater for agriculture converts electrical energy or combustion fuel into radiant heat through ceramic plates, quartz tubes, or metal sheathed elements operating at surface temperatures between 300°C and 900°C, directing infrared radiation toward plants or livestock without heating intervening air. The device serves to maintain thermal uniformity in controlled environments while reducing ventilation losses and fuel consumption relative to convection-based systems. Electric infrared heaters currently occupy the premium tier of product segmentation where precision control justifies higher capital outlay, while gas infrared heaters dominate volume sales in large-scale livestock facilities where operational cost minimization outweighs upfront investment. Application segmentation reveals greenhouse heating as the most mature demand pool, with crop protection applications representing the fastest structural expansion as frost mitigation protocols intensify across temperate fruit-growing zones.
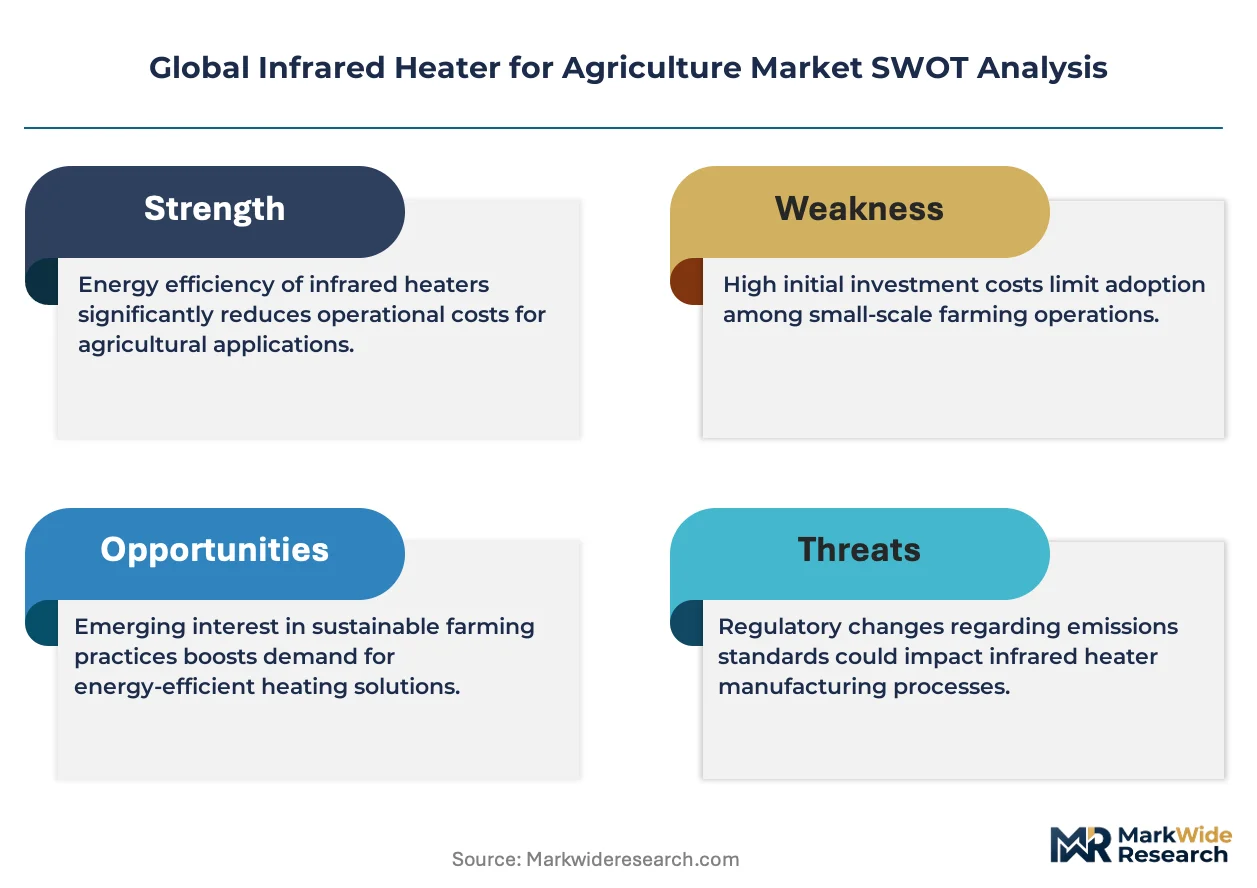
The EU Green Deal and F-Gas Regulation shape product development trajectories by restricting high-global-warming-potential refrigerants and mandating energy performance disclosures for agricultural equipment sold within member states. EPA agricultural burning standards in the United States and China's GB standards for agricultural machinery safety create divergent compliance pathways that fragment certification requirements across export markets. Stakeholders must monitor evolving carbon border adjustment mechanisms and national renewable heat incentive programs to align product portfolios with shifting subsidy eligibility criteria.
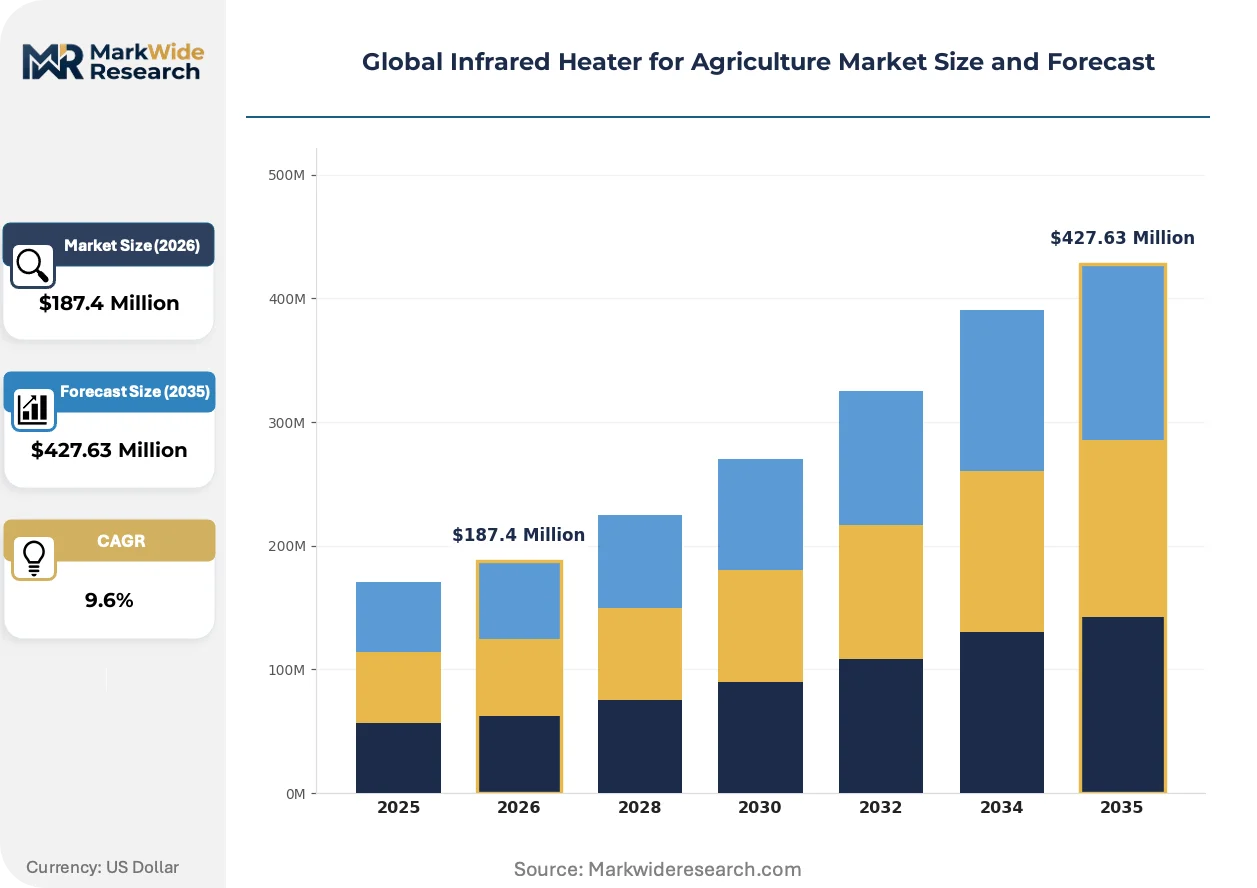
Market Dynamics
The EU Green Deal's emission reduction mandates are forcing greenhouse operators across Northern Europe to retire fuel-burning convection systems in favor of radiant heat architectures, compressing replacement cycles and rewiring vendor-customer relationships toward long-term service contracts.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-global-warming-potential refrigerants accelerate infrared heater deployment in Dutch and Spanish greenhouse clusters as operators seek heating alternatives that bypass compliance penalties.
- Controlled-environment agriculture:Vertical farming installations in Germany and Italy specify electric infrared panels for zone-level thermal control, driving specification pull-through from crop science consultants.
- Ceramic emitter plates:Advances in alumina-silicate substrate durability extend operational lifespan in poultry house environments, reducing lifecycle cost justification thresholds for livestock producers.
Market Restraints
- Copper and nickel alloy input volatility:Metal sheathed element production faces raw material price swings that compress fabrication margins and destabilize quoted project pricing.
- Quartz tube supply concentration:High-purity fused silica sourcing clusters in limited geographic corridors, exposing heater assemblers to single-source disruption risk.
- Biomass boiler substitution:Agricultural waste combustion systems compete for capital allocation in livestock facilities with access to on-farm feedstock.
Strategic Opportunities
- India's agricultural mechanization push:Cold chain infrastructure expansion in Maharashtra and Karnataka creates frost protection demand for orchard infrared installations.
- China's dual carbon goals:Provincial renewable heat incentive programs in Shandong and Hebei provinces subsidize electric infrared retrofits in intensive vegetable production zones.
- IoT-enabled predictive maintenance:Sensor-embedded ceramic emitters converging with cloud analytics platforms enable subscription-based thermal monitoring services.
Industry Challenges
- Thermodynamic modeling expertise:System integrators face scarcity of engineers capable of calculating radiant asymmetry and mean radiant temperature for complex greenhouse geometries.
- CE-MDR dual certification timelines:Agricultural machinery safety standards and medical device adjacent requirements create parallel approval pathways that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infrared Heater for Agriculture Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Infrared Heaters, Gas Infrared Heaters, Radiant Infrared Heaters, Portable Infrared Heaters Application: Plant Growth, Crop Protection, Greenhouse Heating, Livestock Heating End User: Farmers, Greenhouse Operators, Agricultural Cooperatives, Research Institutions Installation: Temporary Installation, Permanent Installation, Indoor Installation, Outdoor Installation |
| Companies Covered | Choretime, Cumberland, Eurogan, Gasolec, Horizont Group, Met Mann, Rexlan Europe, Sodalec Distribution, Mial F.Lli Massini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infrared Heater for Agriculture Market Strategic Shifts
Radiant heating architectures are virtualizing control interfaces and fragmenting procurement authority, with three convergent developments compressing traditional equipment sales into integrated climate-as-a-service offerings.
Carbon-fiber composite emitter substrates are virtualizing the thermal mass trade-off in high-frequency cycling applications. Greenhouse operators in the Netherlands deploy these elements for rapid dawn-response frost protection, eliminating the thermal lag inherent in ceramic and metal alternatives. The technology is virtualizing capital equipment decisions into operational expenditure frameworks where heating capacity rents by the growing season.
The EPA's agricultural burning standards tighten particulate emission thresholds for combustion-based heating in confined livestock housing. Producers across Iowa and North Carolina face retrofit deadlines that disqualify conventional gas-fired unit heaters from new barn construction permits. Electric infrared and catalytic gas systems capture specification share as compliance-ready alternatives that satisfy regional air quality management district requirements.
Aftermarket service unbundling separates hardware procurement from calibration and replacement part contracts. Dutch greenhouse cooperatives now tender climate system maintenance independently of initial equipment purchase, fragmenting vendor relationships and compressing margins on heater sales while expanding recurring revenue pools. This pattern replicates across German horticultural clusters where energy service companies assume operational responsibility for thermal infrastructure.
Global Infrared Heater for Agriculture Market Segmentation
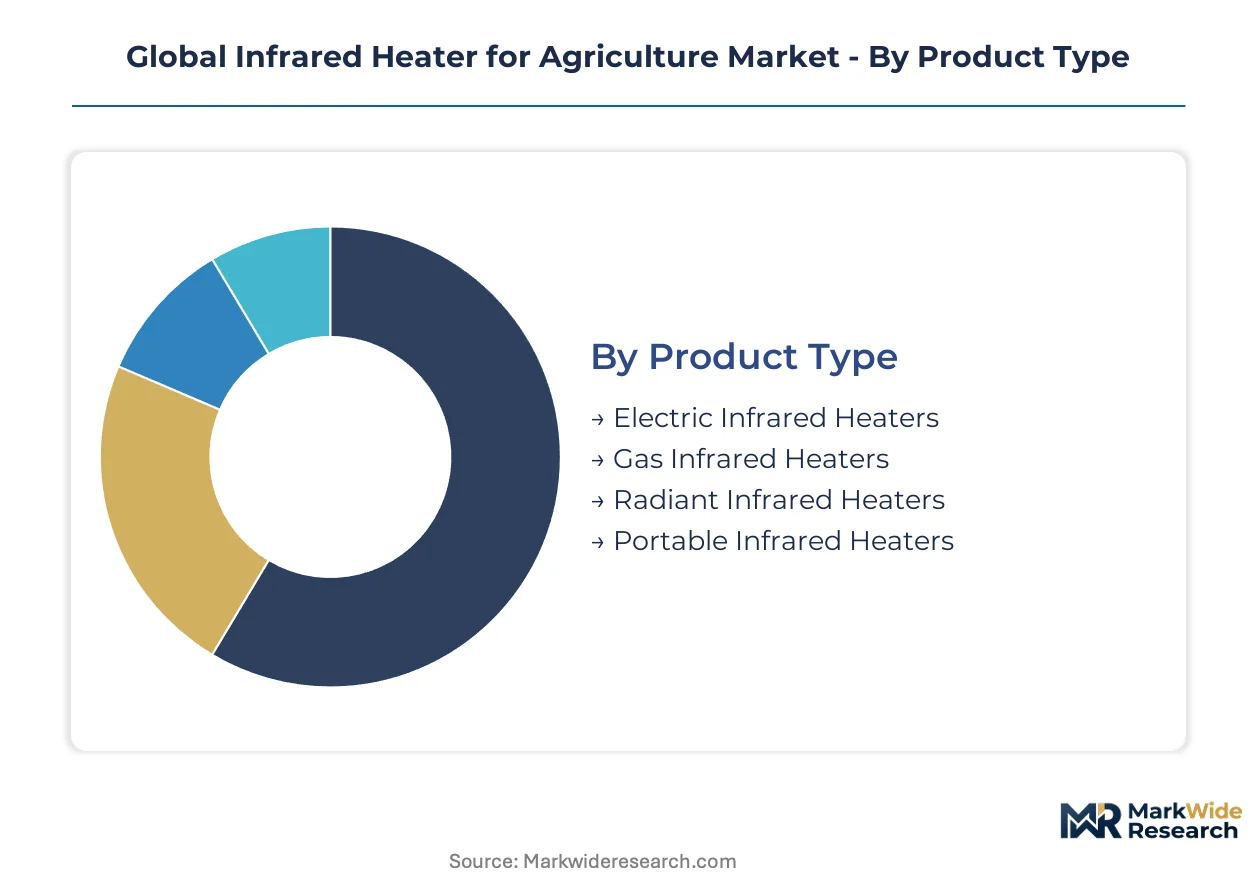
Infrared heater procurement in agriculture fragments across four structural dimensions that determine specification authority and vendor access points. Product type governs capital intensity and operating cost trade-offs. Application context dictates thermal uniformity requirements and regulatory exposure.
Product Type:
Mature combustion-based systems anchor volume sales while electric alternatives accelerate specification in precision-controlled environments.
- Electric Infrared Heaters:Ceramic plate and quartz tube configurations deliver surface temperatures between 300°C and 900°C with zone-level modularity. Dutch vertical farming installations in Westland specify these systems for dawn-response frost protocols where thermal lag elimination justifies premium capital outlay.
- Gas Infrared Heaters:Catalytic and direct-fired combustion architectures dominate North American poultry house deployments across Iowa and North Carolina. EPA agricultural burning standards tighten particulate thresholds that disqualify conventional unit heaters, redirecting permitting approval toward compliant radiant systems.
- Radiant Infrared Heaters:Metal-sheathed element designs serve permanent greenhouse infrastructure where mean radiant temperature uniformity governs crop yield consistency.
- Portable Infrared Heaters:Mobile cart-mounted units address seasonal frost protection in Italian orchard zones and Indian grape cultivation clusters.
Gas infrared heaters retain volume leadership across livestock facilities; electric infrared heaters hold the steepest expansion curve in controlled-environment agriculture.
Application:
Cost tier stratification separates capital-intensive permanent infrastructure from seasonal protection equipment with shorter depreciation schedules.
- Plant Growth:Supplemental photosynthetic photon flux management through thermal uniformity control accelerates germination velocity in German tomato propagation facilities. Zone-level infrared panel arrays replace convection systems that disrupt humidity gradients.
- Crop Protection:Frost mitigation protocols in Spanish citrus groves and French vineyard corridors drive portable radiant deployment during critical bud-break windows. Climate volatility intensifies insurance-driven investment in protective thermal infrastructure.
- Greenhouse Heating:Permanent ceramic emitter installations serve Dutch glasshouse clusters where EU Green Deal emission mandates compress replacement cycles for fuel-burning convection systems.
- Livestock Heating:Brooding zone infrared brooders dominate poultry house specification in the United States, with catalytic gas systems capturing share under tightening air quality management district requirements.
Greenhouse heating commands the largest installed base; crop protection applications are climbing the fastest as frost event frequency rises across temperate cultivation zones.
End User:
Customer type determines procurement centralization and service contract bundling patterns across the value chain.
- Farmers:Individual owner-operators in India's Maharashtra orchard belt prioritize portable electric units with minimal installation overhead for seasonal frost response.
- Greenhouse Operators:Dutch cooperative purchasing consortia unbundle equipment procurement from climate system maintenance, fragmenting vendor relationships toward energy service company intermediation.
- Agricultural Cooperatives:German horticultural clusters aggregate specification authority through shared technical departments that standardize on alumina-silicate ceramic emitter platforms.
- Research Institutions:Wageningen University and Chinese Academy of Agricultural Sciences facilities drive specification pull-through for experimental zone-level thermal control in crop science trials.
Greenhouse operators concentrate procurement volume through cooperative structures; research institutions are gaining specification influence fastest as crop science consultants shape commercial grower decisions.
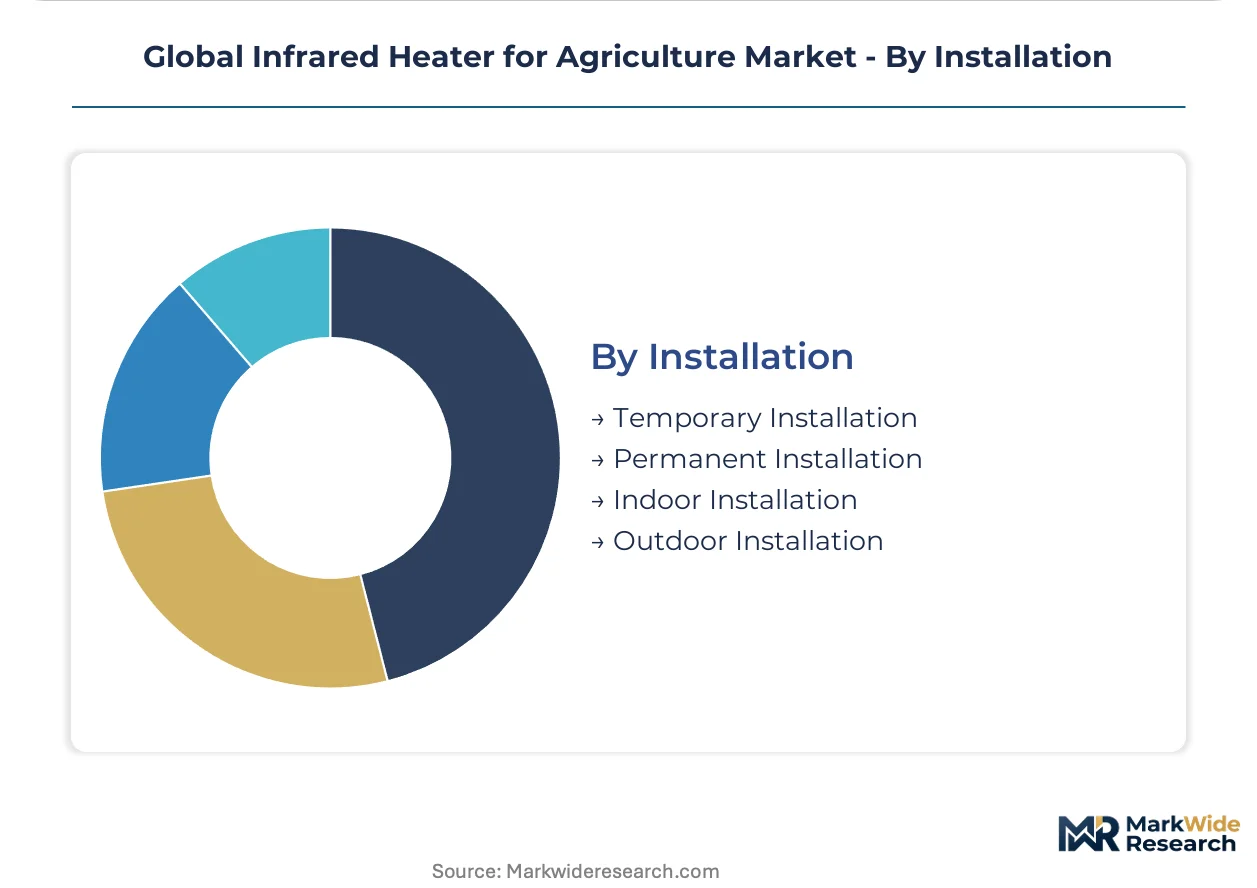
Installation:
Duration and location parameters govern equipment durability specifications and regulatory compliance pathways.
- Temporary Installation:Seasonal orchard protection in Spain's Valencia citrus zone and India's Karnataka coffee belt deploys mobile radiant equipment during discrete frost risk windows.
- Permanent Installation:Fixed ceiling-mounted emitter arrays dominate Dutch greenhouse infrastructure where EU F-Gas Regulation compliance mandates long-horizon thermal system planning.
- Indoor Installation:Confined livestock housing in the United States faces EPA agricultural burning standards that restrict combustion-based heating alternatives.
- Outdoor Installation:Vineyard corridor frost fans with integrated infrared supplementation operate across French Champagne and Italian Piedmont zones.
Permanent installations anchor replacement cycle revenue; temporary installations are expanding most quickly as climate volatility drives insurance-backed seasonal protection equipment acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across agricultural heating markets. Dutch greenhouse operators absorb premium electric infrared systems for EU compliance, while Indian orchard farmers demand low-capital portable units for seasonal frost protection.
Netherlands
Westland greenhouse cooperatives drive specification for ceramic emitter arrays that satisfy EU Green Deal emission mandates. The national environmental agency enforces strict carbon reporting for agricultural energy use. Rotterdam-port logistics clusters facilitate rapid equipment import for replacement cycle compression.
United States
Iowa and North Carolina poultry houses redirect capital toward catalytic gas infrared systems under tightening EPA agricultural burning standards. The EPA particulate thresholds disqualify conventional unit heaters from new barn permits. Midwest integrators consolidate procurement through multi-site service contracts with climate system vendors.
Germany
Baden-Württemberg tomato propagation facilities specify zone-level electric panels for thermal uniformity without humidity disruption. The national implementation of EU F-Gas Regulation accelerates retirement of refrigerant-dependent heating alternatives. Stuttgart-region crop science consultants pull through specification from research institutions to commercial growers.
China
Shandong and Hebei intensive vegetable zones subsidize electric infrared retrofits through provincial renewable heat incentive programs. The Ministry of Ecology and Environment dual carbon goals mandate agricultural energy intensity reductions. Yangtze River Delta greenhouse clusters trial carbon-fiber composite emitters for rapid dawn-response protocols.
India
Maharashtra and Karnataka orchard belts prioritize mobile radiant equipment for discrete frost risk windows. The Bureau of Indian Standards agricultural machinery safety framework governs equipment import certification. Cold chain infrastructure expansion in Nashik grape cultivation clusters creates specification pull-through for frost protection installations.
Global Infrared Heater for Agriculture Market Competitive Environment
Specialized heating fabricators and diversified agricultural equipment conglomerates split the market into distinct capability tiers. The vendor base concentrates around regional service networks rather than manufacturing scale advantages. Two archetypes dominate: European climate-system integrators with deep greenhouse expertise, and North American livestock-focused specialists with dense distribution in poultry belts. Competitive moves center on unbundling hardware sales from recurring service contracts, plus backward integration into emitter substrate production to secure supply continuity.
Within the European integrator tier, Gasolec B.V. and Eurogan S.A. exemplify service-contract anchoring strategies that capture lifetime value through calibration and replacement part revenue. Choretime anchors the North American specialist archetype with dense coverage of Midwest and Southeast poultry house retrofit cycles. Cumberland occupies a position bridging both geographies through multi-species livestock climate system portfolios. These three represent divergent responses to the same structural pressure: compressing equipment margins while expanding recurring revenue pools through operational responsibility transfers.
| Leading Market Players |
|---|
| Choretime |
| Cumberland |
| Eurogan |
| Gasolec |
| Horizont Group |
| Met Mann |
| Rexlan Europe |
| Sodalec Distribution |
| Mial F.Lli Massini |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese quartz tube fabrication is compressing emitter substrate pricing while forcing European ceramic plate manufacturers toward premium positioning through service bundling. Dutch greenhouse cooperatives exploit this divergence by unbundling hardware procurement from long-term calibration contracts, shifting supplier power toward aftermarket revenue capture.
Pricing Analysis
Aftermarket service revenue tiers drive lifetime value concentration across vendor portfolios. Three-tier pricing structure across premium, standard, and economy levels separates electric infrared panels with IoT-enabled predictive maintenance from basic gas-fired units and seasonal portable equipment. Price differentiation hinges on certification grade—CE-MDR dual-certified systems command substantial premiums—and geographic delivery cost differentials between Rotterdam-port imports and regional fabrication. Pricing pressure stems from biomass boiler substitution in livestock facilities with on-farm feedstock access. Indian orchard farmers exhibit highest price sensitivity, prioritizing low-capital portable units, while Dutch greenhouse operators absorb premium electric systems for EU Green Deal compliance.
Supply Chain Analysis
Upstream feedstock concentration in high-purity fused silica draws from Chinese, German, and Japanese specialty glass corridors. Raw material dependencies center on alumina-silicate ceramic substrates, copper-nickel alloy sheathing, and carbon-fiber composite precursors. Supply chain risk manifests in single-source vulnerability for quartz tube sourcing, where geographic clustering exposes assemblers to disruption. Distribution runs through European climate-system integrators with dense greenhouse service networks and North American poultry-belt specialists with multi-site maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story where EU F-Gas Regulation compliance deadlines are accelerating replacement cycles faster than historical equipment lifecycles would predict.
For Market Incumbents: Entrench through backward integration into emitter substrate production to secure supply continuity against quartz tube sourcing concentration. Deepen service contract anchoring by assuming operational responsibility for thermal infrastructure in Dutch and German greenhouse clusters, capturing recurring calibration revenue that offsets hardware margin compression from unbundled procurement patterns.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka orchard belts offer the most penetrable geographic underpenetration, where cold chain infrastructure expansion creates frost protection demand without incumbent service network saturation. Target portable electric infrared units for seasonal deployment through agricultural equipment distributors with existing farmer relationships, bypassing the capital-intensive permanent installation segment dominated by European integrators.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European climate-system integrators with deep greenhouse expertise and established calibration contract portfolios. Long-term viability favors acquisition targets with captive emitter substrate supply or proprietary IoT-enabled thermal monitoring platforms. The signal to watch is provincial renewable heat incentive program expansions in China's Shandong and Hebei provinces, which would accelerate electric infrared retrofit adoption and validate premium technology positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emitter Substrates | Captive supply of alumina-silicate ceramic plates insulates Gasolec and Eurogan from quartz tube sourcing volatility. |
| IoT-Enabled Predictive Maintenance Launch | Sensor-embedded ceramic emitters from Choretime enable subscription-based thermal monitoring across Iowa poultry houses. |
| CE-MDR Dual Certification Investment | Parallel approval pathways for agricultural machinery and medical-adjacent standards accelerate Dutch vertical farming specification. |
| Provincial Incentive Program Alignment | Product portfolio calibration to China's dual carbon goals unlocks subsidized electric retrofit demand in Hebei vegetable zones. |
| Aftermarket Service Unbundling | Independent tendering of climate system maintenance fragments vendor relationships toward energy service company intermediation. |
Study Parameters
Cross-validation between primary interviews with greenhouse operators, poultry house integrators, ceramic emitter fabricators, and agricultural equipment distributors anchors the qualitative findings against secondary validation from EU F-Gas Regulation filings, EPA agricultural burning standard enforcement records, Chinese provincial renewable heat incentive program disclosures, and customs trade data for infrared heater imports. Bottom-up equipment shipment tracking and top-down energy consumption modeling triangulate market sizing across the analysis window.
Calibration against historical replacement cycle data and regulatory compliance deadline schedules informs the projection framework across product type, application context, installation duration, and end-user procurement centralization dimensions. CAGRs derive from segment-level penetration rate trajectories and technology substitution elasticity estimates, with carbon-fiber composite emitter adoption curves and IoT-enabled service contract attachment rates as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese quartz tube manufacturers or accelerated EU carbon border adjustment implementation would shift outcomes. Cross-checking against agricultural energy intensity benchmarks from the IEA and national greenhouse gas inventory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Flexible Silos Market