
 Hoisin Sauce Market | 2026-2036
Hoisin Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Hoisin Sauce Market Insights
Restaurant chains and institutional food service buyers is collapsing into household consumers as the fastest-expanding buyer archetype for hoisin sauce. Lee Kum Kee leverages its heritage formulation expertise to sustain premium positioning across Asian and Western retail channels. Foshan Haitian Flavouring & Food Co. anchors domestic supply through massive fermentation capacity in Guangdong Province. Kikkoman Corporation competes by extending its soy sauce distribution infrastructure into complementary Asian condiment shelves.
Hoisin sauce is a thick, dark fermented condiment produced from soybeans, sugar, vinegar, garlic, and select spices, achieving its characteristic glossy viscosity through prolonged caramelization and starch gelatinization during cooking. The product functions primarily as a glazing agent for roasted meats, a dipping base for dim sum, and a savory-sweet binder in stir-fry applications. Traditional and organic product types dominate current volume, while vegan formulations capture the fastest structural expansion as plant-based dietary frameworks reshape ingredient sourcing requirements. Glass jar packaging sustains margin pools in premium retail, whereas bulk formats serve cost-sensitive food service procurement with minimal unit economics.
China's SAMR enforces GB standards for fermented condiment production, while the FDA oversees allergen disclosure and acidified food safety for imports entering the United States. REACH compliance in Europe restricts certain preservative additives, compelling reformulation for export-oriented manufacturers. Stakeholders must monitor evolving clean-label thresholds and certification requirements that determine market access across divergent regulatory regimes.
Market Dynamics
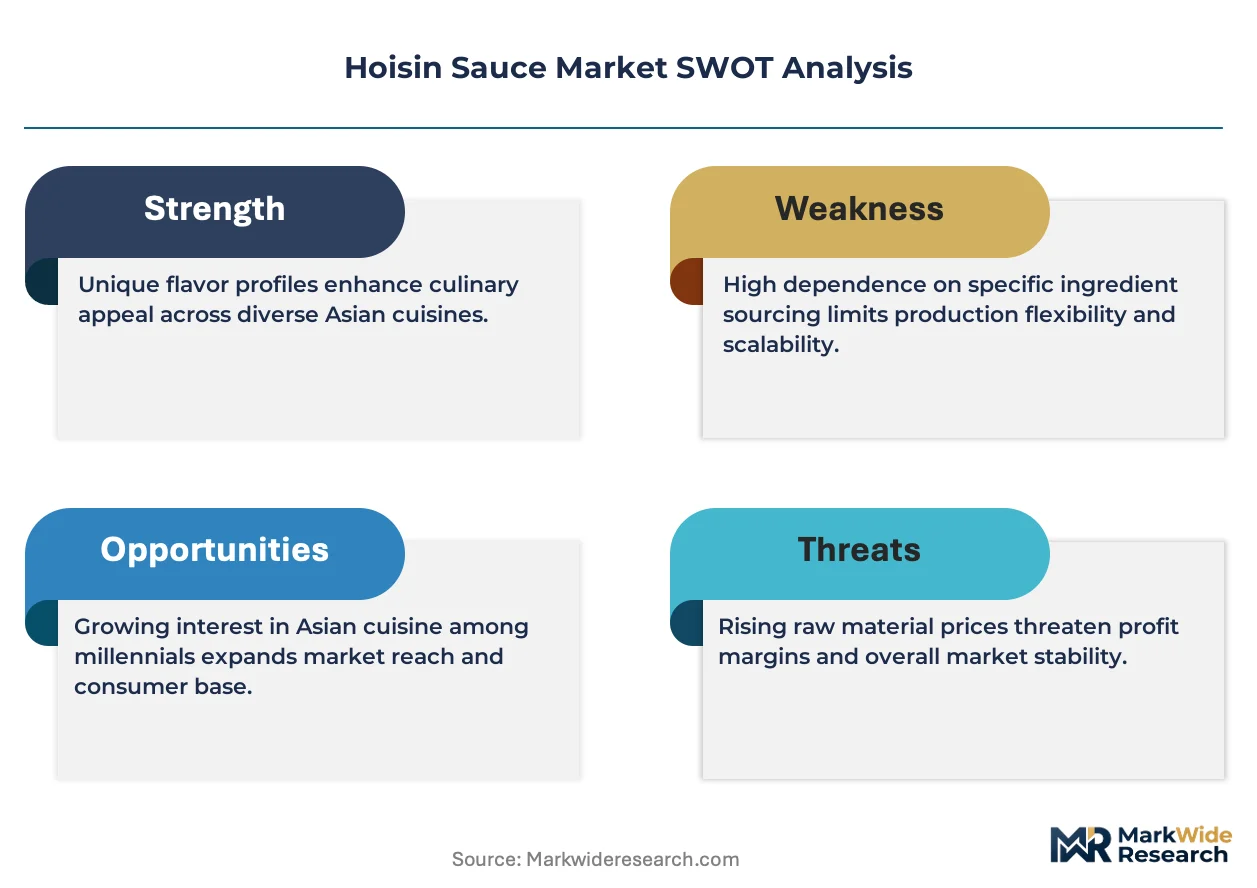
Plant-based dietary frameworks are restructuring hoisin sauce formulation requirements, forcing manufacturers to eliminate animal-derived ingredients from heritage recipes while preserving umami depth through microbial fermentation advances.
Growth Catalysts
- Urban household penetration:Coastal Chinese cities sustain heritage brand loyalty through multi-generational consumption habits, creating stable baseline demand for premium fermented condiments.
- Clean-label regulatory thresholds:REACH compliance in Europe is accelerating preservative-free reformulation investments among export-oriented Guangdong producers.
- Cross-cuisine menu integration:North American restaurant chains are embedding hoisin-based glazes into barbecue and fusion applications beyond traditional Chinese cooking.
Market Restraints
- Soybean input volatility:Fermentation feedstock costs fluctuate with Brazilian and Argentinian harvest cycles, compressing margins for mid-tier manufacturers.
- Supply concentration in Guangdong:Heritage production clusters around Foshan and Pearl River Delta create geographic vulnerability to climate disruptions and logistics bottlenecks.
- Fermentation cycle rigidity:Traditional six-month aging protocols limit rapid volume scaling during demand spikes.
Strategic Opportunities
- Southeast Asian underpenetration:Vietnam and Thailand present white-space expansion potential where local sweet-savory condiments dominate but premium positioning remains open.
- Retail channel innovation:Direct-to-subscription models for artisanal small-batch hoisin are capturing urban millennial households seeking traceable sourcing.
- Dual carbon alignment:China's MEE emissions targets are incentivizing solar-powered fermentation facilities that qualify for green export certification premiums.
Industry Challenges
- Master brewer talent scarcity:Traditional fermentation expertise concentrates among aging practitioners in Guangdong, with limited formal training pipelines.
- Allergen labeling complexity:SAMR's expanded disclosure mandates for fermented soy products require supply chain documentation upgrades that strain smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoisin Sauce Market |
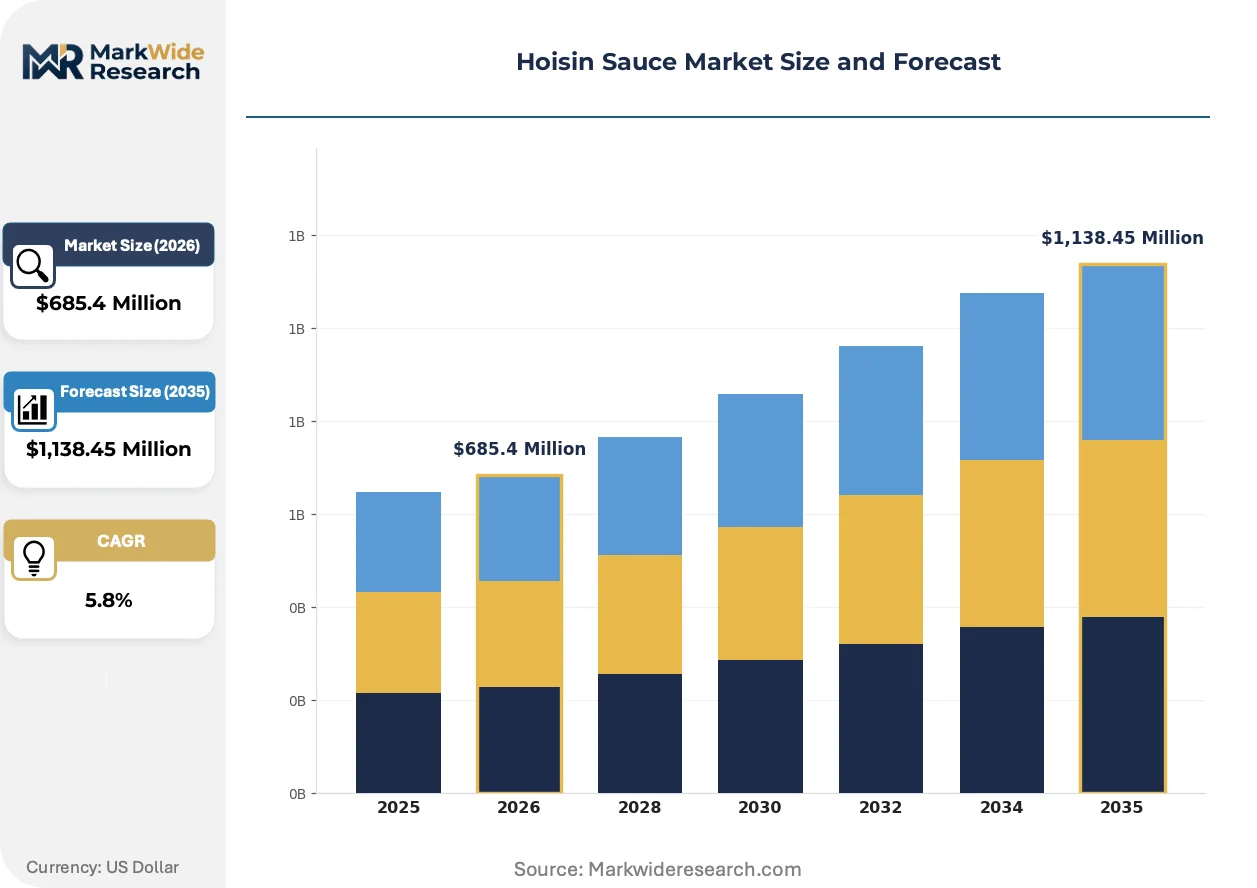
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Vegan, Traditional, Premium End User: Restaurants, Households, Food Service, Catering Packaging Type: Glass Jar, Plastic Bottle, Sachet, Bulk Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Ka-me, Laoganma Special Flavour Foodstuffs Company, Lee Kum Kee, Kikkoman Corporation, Hormel Foods LLC, HADAY, San-J, Foshan Haitian Flavouring & Food Co., Ltd., Koon Chun Sauce Factory Hong Kong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoisin Sauce Market Trends and Innovations
Biotechnology and precision fermentation are rewriting ingredient sourcing protocols for traditional condiments, while regulatory divergence between major import markets fragments formulation strategies.
Precision fermentation-derived amino acid complexes are displacing conventional soybean hydrolysates in premium hoisin formulations. Specialty food manufacturers in California and Netherlands pilot facilities have adopted these microbial proteins to bypass agricultural commodity cycles. The technology is displacing century-old reliance on whole-bean fermentation for umami extraction, compressing production timelines from months to weeks.
SAMR's GB standards for allergen disclosure in fermented condiments are forcing label redesigns across export portfolios. The regulation mandates explicit wheat and soybean tracing that conflicts with heritage recipes using blended grain mashes. European and North American import batches now require parallel documentation streams, with larger manufacturers absorbing compliance costs that marginalize artisanal competitors.
Restaurant procurement consolidation is compressing supplier rosters as institutional buyers demand volume-flexible contracts with clean-label guarantees. National food service distributors in the United States are replacing fragmented regional sauce importers with direct manufacturer relationships. This pattern concentrates most visibly in California and Texas metropolitan corridors where Asian-fusion chain expansion outpaces independent restaurant growth.
Hoisin Sauce Market Segmentation
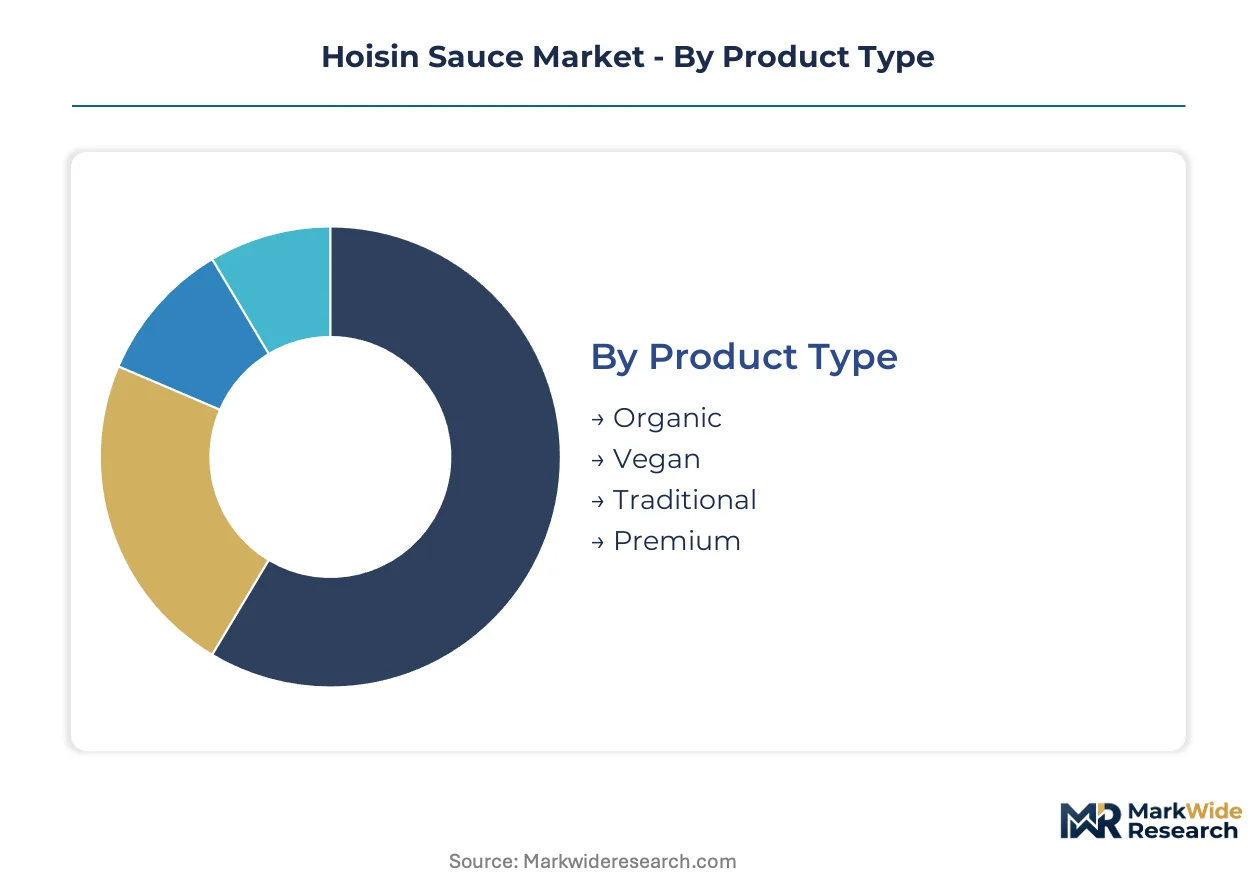
Segmentation in the hoisin sauce market reveals how fermentation heritage, packaging economics, and channel access create divergent margin pools. Each dimension carries distinct substitution pressures from adjacent condiment categories and alternative umami sources.
Product Type:
Substitution pressure from plant-based alternatives and clean-label expectations reshapes formulation priorities across heritage and modern production methods.
- Traditional:Fermented soybean bases with six-month aging protocols deliver the characteristic glossy viscosity and depth that anchors Cantonese cooking. Demand concentrates in Guangdong Province heritage markets where multi-generational households maintain brewing loyalty despite longer production cycles.
- Vegan:Elimination of animal-derived ingredients through microbial fermentation advances preserves umami intensity while meeting plant-based dietary frameworks. North American urban retail channels show the steepest uptake as millennial consumers cross-shop against tamari and coconut aminos.
- Organic:Certified ingredient sourcing with restricted pesticide residues commands premium shelf positioning in European and coastal US markets.
- Premium:Small-batch production with traceable provenance targets direct-to-consumer subscription models and specialty retail.
Traditional retains volume leadership; Vegan holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement from household premiumization, with food service intermediaries capturing margin through volume aggregation.
- Restaurants:Cross-cuisine menu integration in North American barbecue and fusion concepts drives hoisin-based glaze adoption beyond Chinese cooking. California and Texas metropolitan corridors show concentrated chain expansion outpacing independent operator growth.
- Households:Urban coastal China sustains heritage brand loyalty through multi-generational consumption habits, creating stable baseline demand for glass-jar premium formats.
- Food Service:National distributors consolidate supplier rosters, demanding volume-flexible contracts with clean-label guarantees that strain smaller Guangdong producers.
- Catering:Bulk procurement with minimal unit economics prioritizes cost-sensitive formats over fermentation quality signaling.
Restaurants dominate absolute volume; Households are climbing the fastest as retail channel innovation accelerates.
Packaging Type:
Supply concentration in Guangdong glassworks and Pearl River Delta logistics infrastructure shapes format availability and working capital requirements.
- Glass Jar:Premium retail margin pools depend on heritage aesthetics and shelf stability, with Foshan manufacturers maintaining dedicated furnace capacity for condiment viscosity requirements.
- Bulk:Food service and industrial procurement minimize per-unit costs through stainless steel totes and drum formats that bypass retail packaging overhead entirely.
- Plastic Bottle:Lightweight export logistics reduce freight costs for Southeast Asian shipping routes.
- Sachet:Single-serve hospitality and airline catering applications prioritize portion control over brand visibility.
Glass Jar sustains margin leadership; Bulk formats capture the greatest volume throughput.
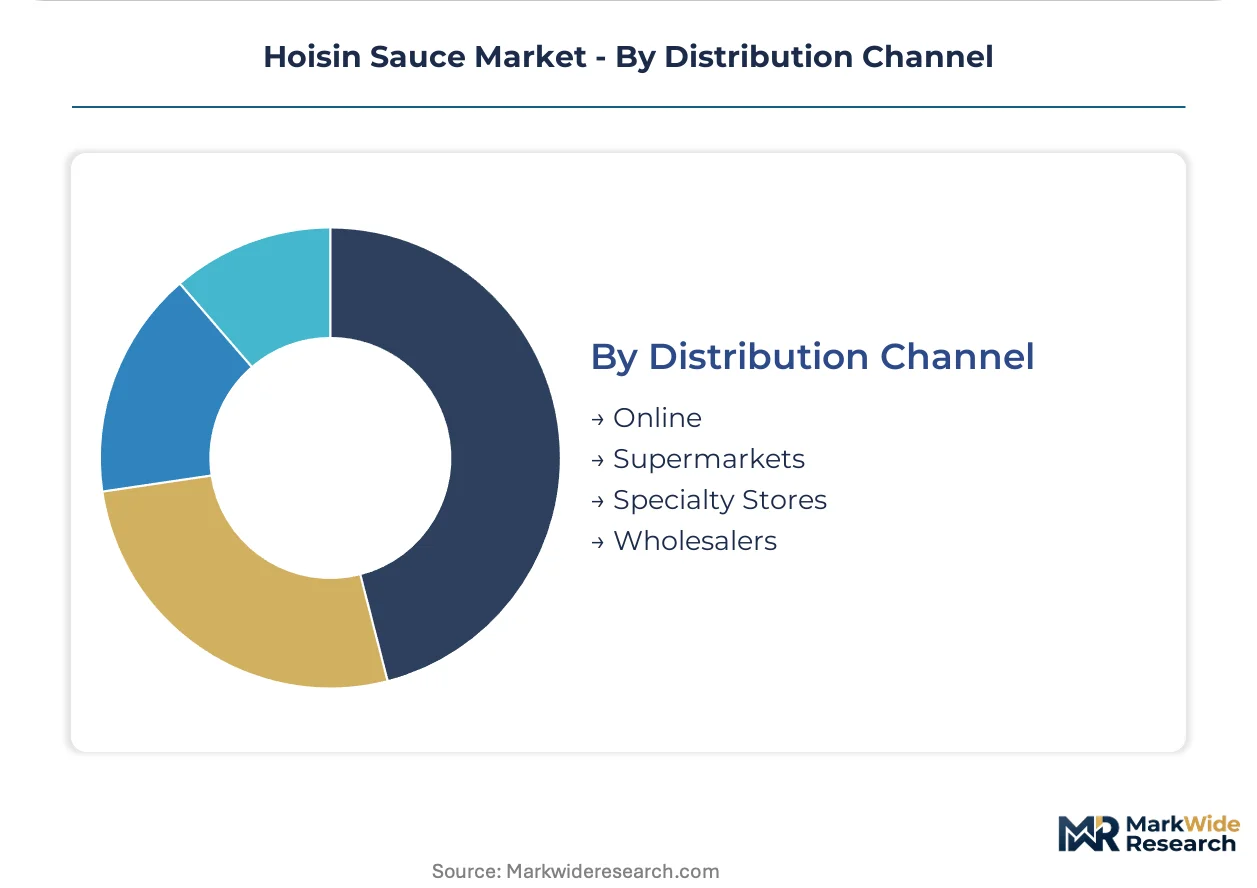
Distribution Channel:
Geographic reach and certification documentation requirements fragment channel strategies between domestic heritage markets and export-oriented compliance regimes.
- Supermarkets:Mainstream retail placement in China and North America depends on SAMR and FDA allergen labeling compliance that strains smaller producers' documentation capacity.
- Online:Direct-to-subscription models for artisanal small-batch hoisin capture urban millennial households seeking traceable sourcing and fermentation transparency.
- Specialty Stores:Asian grocery chains and gourmet retailers in Netherlands and California pilot facilities prioritize precision fermentation-derived premium positioning.
- Wholesalers:Institutional procurement consolidation compresses supplier rosters as national food service distributors replace fragmented regional importers.
Supermarkets anchor current volume; Online channels are gaining share fastest through subscription retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Restaurant chains and institutional food service buyers concentrate in coastal metropolitan corridors, while household consumers drive expansion through direct-to-subscription retail channels. Heritage fermentation clusters in Guangdong Province anchor supply-side capacity. Export-oriented manufacturers navigate divergent allergen disclosure mandates across import markets.
China
Urban coastal households in Guangdong and Shanghai sustain multi-generational consumption of heritage fermented condiments. SAMR enforces GB standards requiring explicit wheat and soybean tracing that conflicts with traditional blended grain mashes. Foshan manufacturers maintain dedicated glass furnace capacity for condiment viscosity requirements.
United States
North American restaurant chains embed hoisin-based glazes into barbecue and fusion applications beyond traditional Chinese cooking. FDA allergen disclosure and acidified food safety protocols govern import compliance. California and Texas metropolitan corridors show concentrated chain expansion outpacing independent operator growth.
Japan
Premium retail channels in Tokyo and Osaka demonstrate uptake of precision fermentation-derived amino acid complexes. METI oversees food additive standards that influence reformulation decisions for export-oriented producers. Kikkoman Corporation extends soy sauce distribution infrastructure into complementary Asian condiment shelves.
Netherlands
Specialty retailers and pilot facilities in Amsterdam and Rotterdam prioritize precision fermentation-derived premium positioning. REACH compliance restricts certain preservative additives, compelling reformulation for export-oriented manufacturers. Dutch distribution hubs serve as consolidation points for European clean-label condiment procurement.
Vietnam
Urban millennial households in Ho Chi Minh City and Hanoi present white-space expansion potential where local sweet-savory condiments dominate. The country's national food safety regulator enforces emerging standards for fermented sauce imports. Plastic bottle formats reduce freight costs for Southeast Asian shipping routes serving this underpenetrated market.
Hoisin Sauce Market Competitive Landscape
Player mix skews toward heritage fermentation specialists with multi-decade brand equity in Cantonese cooking traditions. Market structure exhibits moderate consolidation around Guangdong-based producers with captive aging capacity. Two strategic archetypes dominate: vertically integrated heritage brands controlling fermentation infrastructure, and diversified Asian condiment portfolios leveraging existing distribution. Competitive moves center on clean-label reformulation investments and direct-to-retail channel expansion bypassing traditional import intermediaries.
Within the heritage specialist tier, Lee Kum Kee and Foshan Haitian Flavouring & Food Co., Ltd. exemplify contrasting scale positions—Lee Kum Kee sustaining premium positioning across Asian and Western retail channels through formulation expertise, while Foshan Haitian anchors domestic supply through massive fermentation capacity. Kikkoman Corporation occupies a position as the diversified archetype, extending soy sauce distribution infrastructure into complementary Asian condiment shelves. These three represent the competitive spectrum from single-category heritage depth to cross-portfolio leverage.
| Leading Market Players |
|---|
| Ka-me |
| Laoganma Special Flavour Foodstuffs Company |
| Lee Kum Kee |
| Kikkoman Corporation |
| Hormel Foods LLC |
| HADAY |
| San-J |
| Foshan Haitian Flavouring & Food Co., Ltd. |
| Koon Chun Sauce Factory Hong Kong |
| Others |
Pricing and Supply Chain Analysis
SAMR's GB allergen disclosure standards for fermented condiments simultaneously gate supply qualification for export manufacturers and enforce price differentiation between compliant and non-compliant production tiers. Buyers in North American and European markets now demand parallel documentation streams that smaller Guangdong producers cannot absorb, compressing their margin pools while heritage brands capture certification premiums.
Pricing Analysis
Cost-plus contracts with Brazilian soybean indexation anchor pricing for mid-tier manufacturers serving institutional food service buyers. Three-tier pricing structure across premium glass-jar retail, standard plastic bottle export, and economy bulk formats reflects fermentation quality grade and REACH compliance certification. Pricing pressure stems from soybean input volatility tied to South American harvest cycles, with food service distributors exhibiting highest price sensitivity and direct-to-consumer subscription households showing lowest elasticity.
Supply Chain Analysis
Pearl River Delta logistics infrastructure and Foshan glassworks capacity constitute a chokepoint for premium condiment packaging availability. Supply concentrates in Guangdong Province, China, with secondary fermentation clusters in Hong Kong and Taiwan feeding specialty export channels. Raw material dependencies include Brazilian and Argentinian soybeans, Guangdong-grown wheat for grain mashes, and specific spice cultivars from Sichuan and Yunnan provinces. Single-source vulnerability runs through aging facility concentration in Foshan, where six-month fermentation protocols limit rapid volume scaling. Distribution runs through national food service distributors consolidating formerly fragmented regional import networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as national food service distributors replace fragmented regional sauce importers, compressing supplier rosters and demanding volume-flexible contracts with clean-label guarantees.
For Market Incumbents: Fortify fermentation infrastructure control by securing captive aging capacity in Guangdong and investing in precision fermentation R&D to bypass agricultural commodity cycles. Lee Kum Kee and Foshan Haitian must defend against microbial protein substitutes by emphasizing heritage formulation depth and multi-generational brand equity in Cantonese cooking traditions. For New Entrants and Emerging Players: Lead with direct-to-subscription models targeting urban millennial households in Vietnam and Thailand where local sweet-savory condiments dominate but premium positioning remains open. White-space expansion should prioritize plastic bottle formats for Southeast Asian shipping routes and precision fermentation-derived amino acid complexes for Netherlands specialty retail channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation pilot facilities as biotechnology rewrites ingredient sourcing protocols. Long-term viability favors acquisition targets with dual heritage brand equity and clean-label certification infrastructure spanning SAMR, FDA, and REACH compliance regimes. The signal to watch is solar-powered fermentation facility deployment qualifying for China's MEE green export certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein facilities in California and Netherlands compress production timelines from months to weeks. |
| Clean-Label Reformulation Investment | REACH-compliant preservative-free recipes open European market access for Guangdong exporters. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass consolidated food service distributor networks capturing urban millennial households. |
| Solar-Powered Fermentation Facilities | China's MEE emissions targets incentivize green export certification premiums for qualifying producers. |
| Southeast Asian Distribution Partnership | Plastic bottle logistics reduce freight costs for Vietnam and Thailand white-space penetration. |
Research Methodology
Desk research of customs trade records, SAMR regulatory filings, and fermented condiment industry association reports preceded structured interviews with Guangdong fermentation facility managers, North American food service procurement directors, European specialty retail buyers, and precision fermentation technology specialists. Primary fieldwork validated secondary data on aging protocol durations, soybean input cost structures, and cross-cuisine menu integration patterns. Bottom-up volume estimates from manufacturer capacity disclosures triangulated against top-down demand projections from retail channel audits.
Variance decomposition across product type, end user, packaging format, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate modeling incorporated fermentation cycle rigidity constraints, regulatory compliance cost absorption curves, and channel shift velocities toward direct-to-subscription retail. Industry-specific inputs included master brewer talent availability indices and solar-powered facility deployment rates qualifying for green certification premiums.
Forecasts assume regulatory continuity in SAMR GB standards, FDA allergen disclosure protocols, and REACH additive restrictions; material policy shifts would require re-modeling supply qualification thresholds and export market access assumptions. Practitioners should keep alternative scenarios live as biotechnology substitution rates and Southeast Asian import standard evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Dips and Spreads Market