
 Freeze Dried Melt Market | 2026-2036
Freeze Dried Melt Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Melt Market Insights
Capital-intensity divergence between large integrated processors and specialized regional operators is rotating competitive advantage toward in-house lyophilization infrastructure. Döhler Group leverages its European manufacturing footprint to supply multinational food and pharma clients with consistent batch-scale capacity. Van Drunen Farms anchors North American supply through backward integration into raw fruit and vegetable sourcing. Mercer Foods competes on custom formulation services for private-label nutritional brands.
Freeze dried melts are thermally processed materials rendered shelf-stable through sublimation-driven moisture removal, typically achieving residual water content below 3% to preserve bioactive integrity in pharmaceutical and food matrices. Vacuum freeze drying dominates installed capacity due to proven scalability for vaccine preservation and enzyme stabilization, though microwave-assisted freeze drying is gaining traction for accelerated cycle times in probiotic applications. Food ingredients and nutraceuticals represent mature volume pools with compressed margins, while biotechnology applications command premium positioning through stringent endotoxin and sterility specifications.
FDA cGMP guidelines for lyophilized parenterals, EMA Annex 1 revisions on sterile manufacturing, and ISO 13485 quality management standards collectively shape capital deployment and facility validation requirements across production networks. Regulatory alignment between these frameworks increasingly determines market access for contract manufacturers serving dual jurisdiction clients. Stakeholders must monitor harmonization gaps between FDA process analytical technology expectations and EMA real-time release testing protocols to avoid redundant qualification burdens.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating lyophilization capacity around FDA process analytical technology mandates, forcing mid-tier operators to choose between capital-intensive facility upgrades and exit from biologics stabilization services.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:European contract manufacturers are retrofitting isolator-based freeze drying lines to meet 2023 contamination control requirements, pulling demand for validated equipment packages.
- Enzyme stabilization protocols:Industrial biotechnology firms are embedding freeze dried melts into cold-chain-free diagnostic kits, expanding addressable use cases beyond traditional parenterals.
- United States nutraceutical clustering:Utah and North Carolina ingredient hubs are scaling dedicated lyophilization suites for probiotic and botanical extracts, creating regional supply anchors.
Market Restraints
- Energy cost volatility:Vacuum freeze drying cycles consume 1.5-2.5 kWh per kilogram of water removed; European electricity price spikes have compressed operating margins at toll manufacturing facilities.
- Single-source WFI dependency:Water-for-injection supply concentration in select United States municipal districts creates geographic vulnerability for sterile melt production.
- Spray drying substitution:Nutraceutical powder applications are migrating to lower-capex spray drying where bioactive heat tolerance permits, capping lyophilization volume in commodity segments.
Strategic Opportunities
- India CDMO expansion:CDSCO's streamlined approval pathways for lyophilized biologics are attracting multinational sponsors to Hyderabad and Bangalore manufacturing corridors.
- Microwave-assisted cycle convergence:Hybrid microwave-vacuum systems are reducing probiotic processing times by 40%, opening shelf-stable live culture applications previously uneconomical.
- Direct-to-clinic distribution:Specialty pharmacy networks are contracting for patient-specific freeze dried melt unit doses, bypassing traditional wholesale channels.
Industry Challenges
- Lyophilization scientist scarcity:Formulation and cycle development expertise resides with aging specialists; university programs lack dedicated freeze drying curricula.
- IQ/OQ/PQ timeline compression:FDA process validation expectations for commercial scale-up now demand 12-18 month qualification windows, delaying revenue recognition.
- Legacy SCADA integration:Paper-based batch records at established facilities face retrofit costs for real-time release testing compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Melt Market |
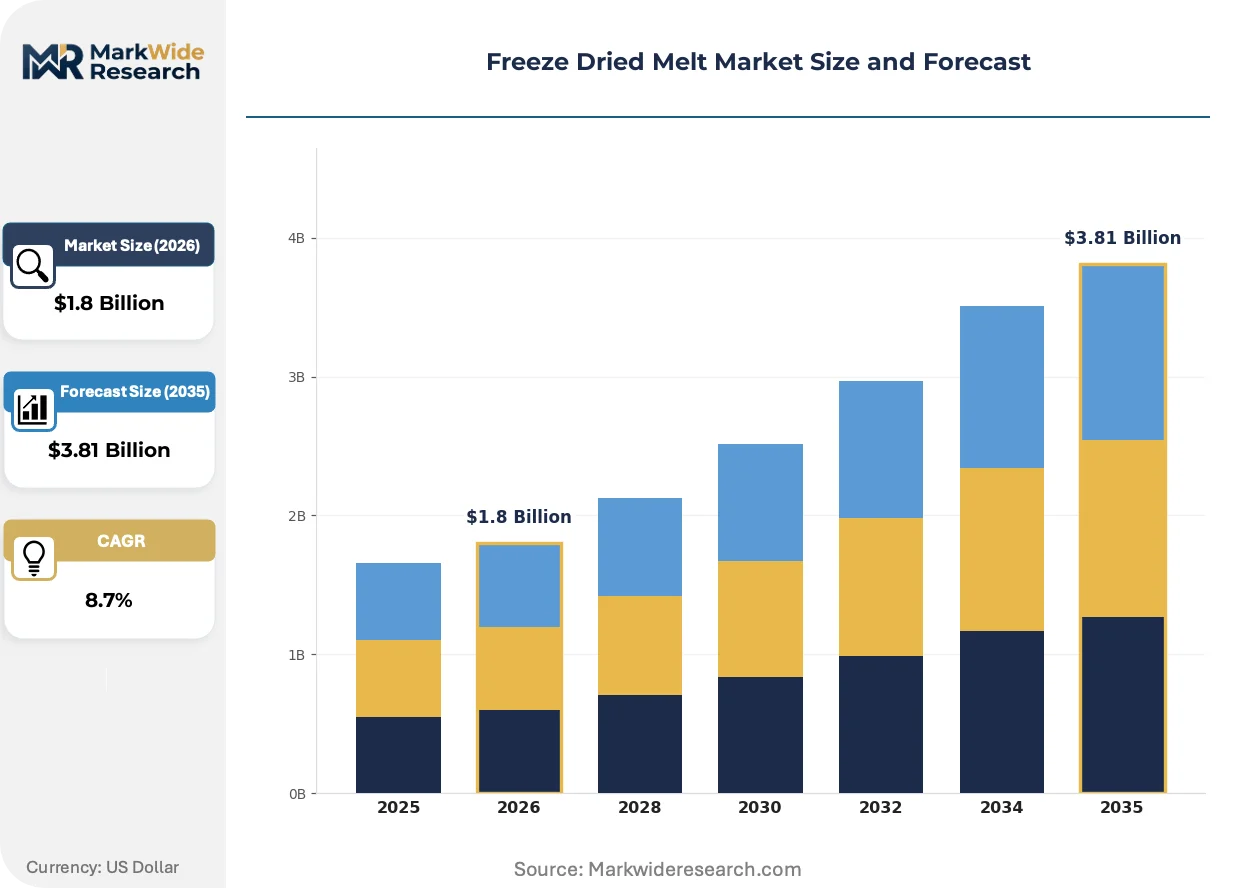
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biotechnology, Nutraceuticals, Food Ingredients, Chemical Reagents, Cosmetics Technology: Vacuum Freeze Drying, Spray Freeze Drying, Microwave-Assisted Freeze Drying, Ultraviolet Freeze Drying, Infrared Freeze Drying Application: Vaccine Preservation, Enzyme Stabilization, Probiotic Storage, Food Preservation, Flavor Enhancement, Cosmetic Formulation End User: Contract Manufacturing, Research Laboratories, Nutritional Supplement Manufacturers, Personal Care Producers, Specialty Chemical Firms |
| Companies Covered | Döhler Group, Van Drunen Farms, Mercer Foods, Thrive Freeze Dry, European Freeze Dry, SouthAM Freeze Dry, Freeze-Dry Foods, Chaucer Foods, Asahi Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Melt Market Trends and Innovations
Continuous manufacturing architectures are penetrating lyophilization workflows, challenging batch-based facility designs that have dominated pharmaceutical production for four decades.
Microwave-assisted freeze drying is displacing conventional vacuum shelf systems in high-throughput probiotic applications. North American nutraceutical contract manufacturers are piloting hybrid units for Lactobacillus and Bifidobacterium strains. The technology is displacing multi-day cycle times with sub-24 hour processing, compressing working capital requirements and enabling just-in-time production models previously infeasible for live cultures.
FDA process analytical technology guidance for lyophilized parenterals is tightening real-time moisture monitoring requirements. Manufacturers must deploy tunable diode laser absorption spectroscopy or equivalent in-line sensors to demonstrate batch uniformity. United States-based sterile injectables specialists are absorbing six-figure capital costs per production line to avoid regulatory rejection of traditional Karl Fischer endpoint testing.
Specialty pharmacy buyers are consolidating procurement around qualified CDMOs with dual FDA-EMA inspection histories. Large hospital systems are de-listing regional toll manufacturers lacking recent regulatory exposure. Germany and Switzerland anchor this concentration, where Basel-area and Munich corridor facilities capture preferred vendor status through accumulated inspection currency.
Freeze Dried Melt Market Segmentation
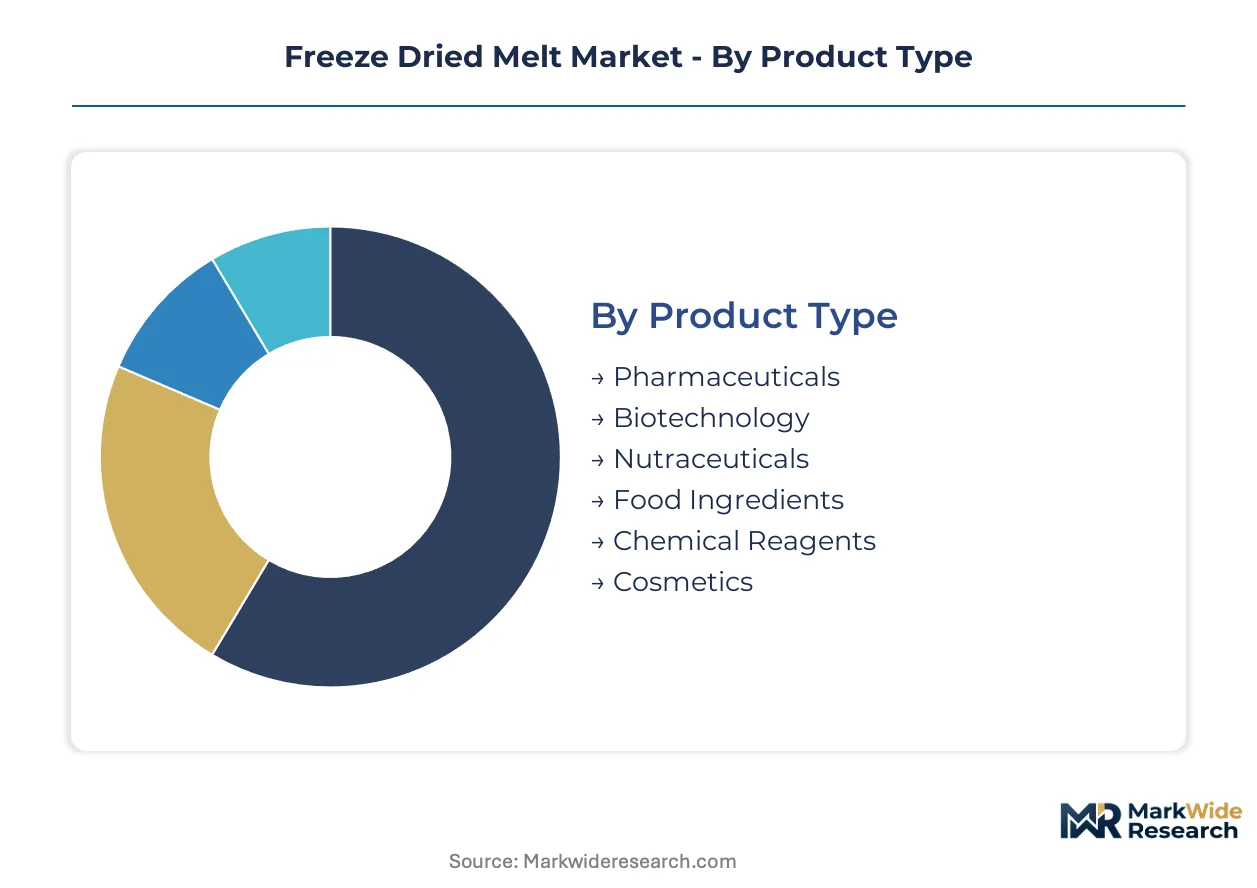
Freeze dried melt segmentation reveals divergent margin structures across therapeutic versus commodity applications. Technology choices determine capital intensity and cycle economics, while end-user concentration shapes contract terms and qualification burdens.
Product Type:
Substitution pressure from spray drying alternatives weighs most heavily on food-grade segments, forcing lyophilization suppliers to defend positioning through bioactive preservation claims.
- Pharmaceuticals:Parenteral formulations and biologic stabilizations demand residual moisture below 3% and endotoxin compliance. United States sterile injectables specialists anchor demand as FDA process analytical technology mandates tighten real-time release protocols.
- Biotechnology:Enzyme and diagnostic reagent applications embed freeze dried melts into cold-chain-free distribution models. Industrial biotechnology firms in Germany and Switzerland are expanding diagnostic kit volumes, pulling high-purity melt demand.
- Nutraceuticals:Probiotic and botanical extract applications face margin compression from spray drying substitution where heat tolerance permits.
- Food Ingredients:Fruit and vegetable matrices compete directly with air-dried and spray-dried alternatives on cost per kilogram.
- Chemical Reagents:Laboratory-grade stability requirements sustain niche positioning against conventional desiccation methods.
- Cosmetics:Active ingredient preservation in skincare formulations commands modest premiums over conventional emulsion systems.
Food Ingredients anchors the volume base while Biotechnology gains share at the steepest rate.
Technology:
Cost tier stratification separates proven vacuum infrastructure from emerging microwave and infrared alternatives competing on cycle economics.
- Vacuum Freeze Drying:Shelf-based sublimation systems dominate installed pharmaceutical capacity with proven scalability for vaccine preservation. FDA-validated equipment packages from German and Swiss suppliers anchor contract manufacturer procurement.
- Microwave-Assisted Freeze Drying:Hybrid systems reduce probiotic processing cycles by 40%, enabling just-in-time live culture production. North American nutraceutical contract manufacturers are piloting units for Lactobacillus and Bifidobacterium strains.
- Spray Freeze Drying:Atomization-based approaches serve high-throughput powder applications with intermediate capital requirements.
- Ultraviolet Freeze Drying:Niche surface sterilization integration addresses select cosmetic and reagent applications.
- Infrared Freeze Drying:Emerging radiant heating approaches compete for botanical extract applications requiring gentler thermal profiles.
Vacuum Freeze Drying commands the installed base while Microwave-Assisted Freeze Drying climbs the fastest as cycle time compression justifies capital replacement.
Application:
Application maturity curves separate established parenteral preservation from emerging probiotic and cosmetic use cases at varying commercialization stages.
- Vaccine Preservation:Lyophilized measles, yellow fever, and Ebola vaccines constitute non-substitutable demand with WHO prequalification requirements. United States and European fill-finish facilities maintain dedicated capacity for pandemic preparedness stockpiles.
- Enzyme Stabilization:Diagnostic kit manufacturers embed freeze dried melts for room-temperature distribution of PCR and immunoassay reagents. Cold-chain-free deployment models expand addressable markets in tropical climates.
- Probiotic Storage:Live culture shelf stability demands precise moisture control, with microwave-assisted cycles opening previously uneconomical applications.
- Food Preservation:Ready-to-eat meal components and instant coffee matrices represent mature volume with compressed differentiation.
- Flavor Enhancement:Encapsulated volatile compound preservation serves premium culinary applications with limited scale.
- Cosmetic Formulation:Active peptide and vitamin stabilization in luxury skincare commands development-stage volumes.
Food Preservation carries the volume foundation while Probiotic Storage expands most quickly as microwave cycle economics unlock live culture applications.
End User:
Customer type concentration determines qualification burden intensity, with contract manufacturers facing dual FDA-EMA inspection requirements that exclude smaller regional operators.
- Contract Manufacturing:CDMOs consolidate procurement around facilities with accumulated inspection currency from both FDA and EMA. Basel-area and Munich corridor specialists capture preferred vendor status from large pharmaceutical sponsors.
- Research Laboratories:Academic and government facilities drive small-batch demand for reagent-grade melts with flexible specification tolerances.
- Nutritional Supplement Manufacturers:Utah and North Carolina ingredient hubs scale dedicated lyophilization suites for private-label botanical and probiotic formulations.
- Personal Care Producers:Cosmetic formulators source through toll manufacturers with ISO 22716 cosmetic GMP compliance.
- Specialty Chemical Firms:Industrial enzyme and catalyst producers maintain captive lyophilization for process-critical intermediates.
Contract Manufacturing dominates value capture while Nutritional Supplement Manufacturers show the steepest volume trajectory as regional clustering accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in freeze dried melts tilts toward German and Swiss sterile manufacturing corridors, while United States toll processors absorb margin compression from energy cost spikes and WFI supply bottlenecks. This asymmetry reflects divergent regulatory inspection currency and infrastructure vintage across Atlantic production networks.
United States
Specialty chemical firms in Utah and North Carolina are scaling dedicated lyophilization suites for temperature-sensitive botanicals and probiotics. FDA process analytical technology mandates for real-time moisture monitoring are forcing six-figure capital upgrades per production line. The Wasatch Front corridor anchors nutraceutical clustering with backward integration into raw ingredient sourcing.
Germany
Basel-area and Munich corridor facilities capture preferred vendor status from multinational pharmaceutical sponsors through accumulated FDA-EMA dual inspection histories. EMA Annex 1 sterile manufacturing revisions are driving isolator-based freeze drying line retrofits. Bavarian contract manufacturers supply validated equipment packages across European biologics stabilization networks.
Switzerland
Swissmedic's alignment with FDA process validation protocols positions domestic CDMOs for specialty pharmacy procurement consolidation. Industrial biotechnology firms in the Basel region embed freeze dried melts into diagnostic kit manufacturing for tropical climate distribution. The country's precision engineering base supplies tunable diode laser absorption spectroscopy systems for in-line moisture monitoring.
India
CDSCO streamlined approval pathways for lyophilized biologics are attracting multinational sponsors to Hyderabad and Bangalore manufacturing corridors. Indian contract manufacturers compete on accelerated IQ/OQ/PQ timelines compared to legacy European facilities. The Genome Valley-Telangana cluster anchors biologics CDMO expansion with government-backed infrastructure incentives.
Japan
PMDA's convergence with FDA process analytical technology expectations enables domestic freeze drying specialists to serve dual-jurisdiction clients without redundant qualification. METI funding for continuous manufacturing architectures is penetrating lyophilization workflows at established pharmaceutical producers. The Kanto region maintains dedicated capacity for pandemic preparedness vaccine stockpiles under WHO prequalification requirements.
Freeze Dried Melt Market Competitive Landscape
Concentration sits with large integrated processors and specialized regional operators possessing in-house lyophilization infrastructure. The vendor base stratifies across three tiers: multinational ingredient suppliers with European manufacturing footprints, North American toll processors with backward integration into raw sourcing, and Asian contract manufacturers competing on regulatory acceleration. Dominant competitive moves include capacity expansion around FDA-EMA dual inspection capabilities and technology licensing for microwave-assisted cycle convergence.
Among European-based multinational suppliers, Döhler Group occupies a position exemplifying batch-scale consistency for food and pharma clients. Van Drunen Farms anchors North American supply archetypes through its integration into raw fruit and vegetable sourcing. Mercer Foods sits within the custom formulation tier, representing private-label nutritional brand servicing. These three entities collectively illustrate the geographic and capability segmentation shaping procurement consolidation patterns.
| Leading Market Players |
|---|
| Döhler Group |
| Van Drunen Farms |
| Mercer Foods |
| Thrive Freeze Dry |
| European Freeze Dry |
| SouthAM Freeze Dry |
| Freeze-Dry Foods |
| Chaucer Foods |
| Asahi Group Holdings |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month IQ/OQ/PQ qualification timelines concentrate pricing power with CDMOs holding accumulated FDA-EMA dual inspection currency, while mid-tier toll processors absorb margin compression from extended working capital cycles. This lead-time asymmetry rewards facilities in the Basel-Munich corridor with configured-to-order premiums while penalizing regional operators lacking regulatory entrenchment.
Pricing Analysis
The customization-premium spread separates configured-to-order biologic stabilization services from standard nutraceutical melts by 40-60% at the contract manufacturing tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-EMA dual-inspected facilities commanding top-tier positioning against single-jurisdiction competitors. Pricing pressure stems from spray drying substitution in botanical extract applications where heat tolerance permits, compressing lyophilization margins in commodity segments. Nutraceutical powder buyers exhibit highest price sensitivity, while sterile injectables specialists prioritize supply assurance over unit cost.
Supply Chain Analysis
Just-in-time production models for live probiotic cultures clash with strategic stockpile preferences for pandemic preparedness vaccine melts, bifurcating inventory strategy across therapeutic categories. Supply concentrates in Germany, Switzerland, and the United States for validated pharmaceutical-grade equipment and sterile fill-finish capacity, while India and China anchor expansion corridors for cost-sensitive nutraceutical volumes. Raw material dependencies center on water-for-injection supply from concentrated United States municipal districts, pharmaceutical-grade excipients from European chemical suppliers, and precision-engineered vacuum chamber components from Swiss-German manufacturing bases. Single-source WFI vulnerability creates geographic chokepoint exposure. Distribution runs through specialty pharmacy networks consolidating procurement around qualified CDMOs, bypassing traditional wholesale channels for patient-specific unit doses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock pharmaceutical sponsors into established CDMO relationships through accumulated inspection currency and validated cycle protocols.
For Market Incumbents: Shield accumulated FDA-EMA dual inspection histories through isolator-based line retrofits that exceed EMA Annex 1 contamination control requirements, raising qualification barriers for mid-tier competitors. Deepen backward integration into raw botanical sourcing in the Wasatch Front corridor to defend margin position against spray drying substitution in nutraceutical segments. Microwave-assisted cycle expertise represents the priority capability anchor for probiotic live culture applications. For New Entrants and Emerging Players: Lead with regulatory acceleration services targeting CDSCO streamlined approval pathways in the Hyderabad-Bangalore corridor, where IQ/OQ/PQ timeline compression attracts multinational sponsors frustrated by European facility backlogs. Diagnostic kit enzyme stabilization offers the most penetrable white-space target, embedding freeze dried melts into cold-chain-free distribution models for tropical climate deployment. Direct-to-clinic specialty pharmacy contracting provides the clearest go-to-market angle bypassing consolidated wholesale procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food-ingredient conglomerates with underutilized lyophilization assets lacking pharmaceutical-grade certification investment. Long-term viability over the next decade hinges on continuous manufacturing architecture adoption and real-time release testing compliance. The signal to watch is FDA process analytical technology enforcement intensity against Karl Fischer endpoint testing, which would accelerate capital replacement cycles and concentrate procurement among sensor-equipped facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Line Retrofit | EMA Annex 1 compliance upgrades capture preferred vendor status from European biologics sponsors. |
| Microwave-Assisted Cycle Adoption | Hybrid vacuum-microwave systems reduce probiotic processing times by 40% at North American nutraceutical CDMOs. |
| Dual FDA-EMA Inspection Accumulation | Basel-area and Munich corridor facilities leverage inspection currency for specialty pharmacy procurement consolidation. |
| Backward Integration into Raw Sourcing | Utah and North Carolina ingredient hubs secure supply assurance for temperature-sensitive botanical extracts. |
| Real-Time Moisture Monitoring Deployment | Tunable diode laser absorption spectroscopy installations satisfy FDA process analytical technology mandates for commercial scale-up. |
Research Methodology
A standing panel of lyophilization scientists, pharmaceutical contract manufacturing executives, regulatory affairs specialists, and specialty pharmacy procurement directors provided ongoing calibration against operational realities. Primary interviews with CDMO operations heads and FDA compliance officers combined with secondary validation from FDA guidance documents, EMA Annex 1 revision drafts, ISO 13485 certification databases, and CDSCO approval pathway records. Bottom-up facility capacity assessments triangulated against top-down pharmaceutical sponsor procurement surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, technology platform, application maturity, and end-user concentration dimensions. CAGRs derived from facility expansion announcements, equipment procurement pipelines, and sponsor pipeline disclosures for lyophilized biologics. Industry-specific forecast inputs incorporated CDSCO regulatory acceleration timelines and EMA Annex 1 retrofit spending patterns.
Forecasts assume regulatory continuity in FDA cGMP, EMA Annex 1, and CDSCO biologics approval regimes; material policy shifts would require re-modeling of qualification timeline assumptions and capital deployment patterns. Energy cost volatility in European electricity markets and WFI supply concentration risks represent specific revision triggers. Revision becomes warranted when spray drying substitution rates in nutraceutical applications cross thresholds that materially compress lyophilization volume forecasts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market