
 Celery Seed Extract Powder Market | 2026-2036
Celery Seed Extract Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Celery Seed Extract Powder Market Insights
India is rewriting supply dynamics for botanical extracts as domestic cultivation of Apium graveolens scales and extraction capacity expands in Gujarat and Uttar Pradesh. Sabinsa Corporation leverages its phytochemical R&D infrastructure to sustain leadership in standardized extract production. NOW Foods anchors North American distribution through vertically controlled supplement retail channels. Nature's Way Products, LLC differentiates via certified organic sourcing protocols that command premium positioning in health food stores.
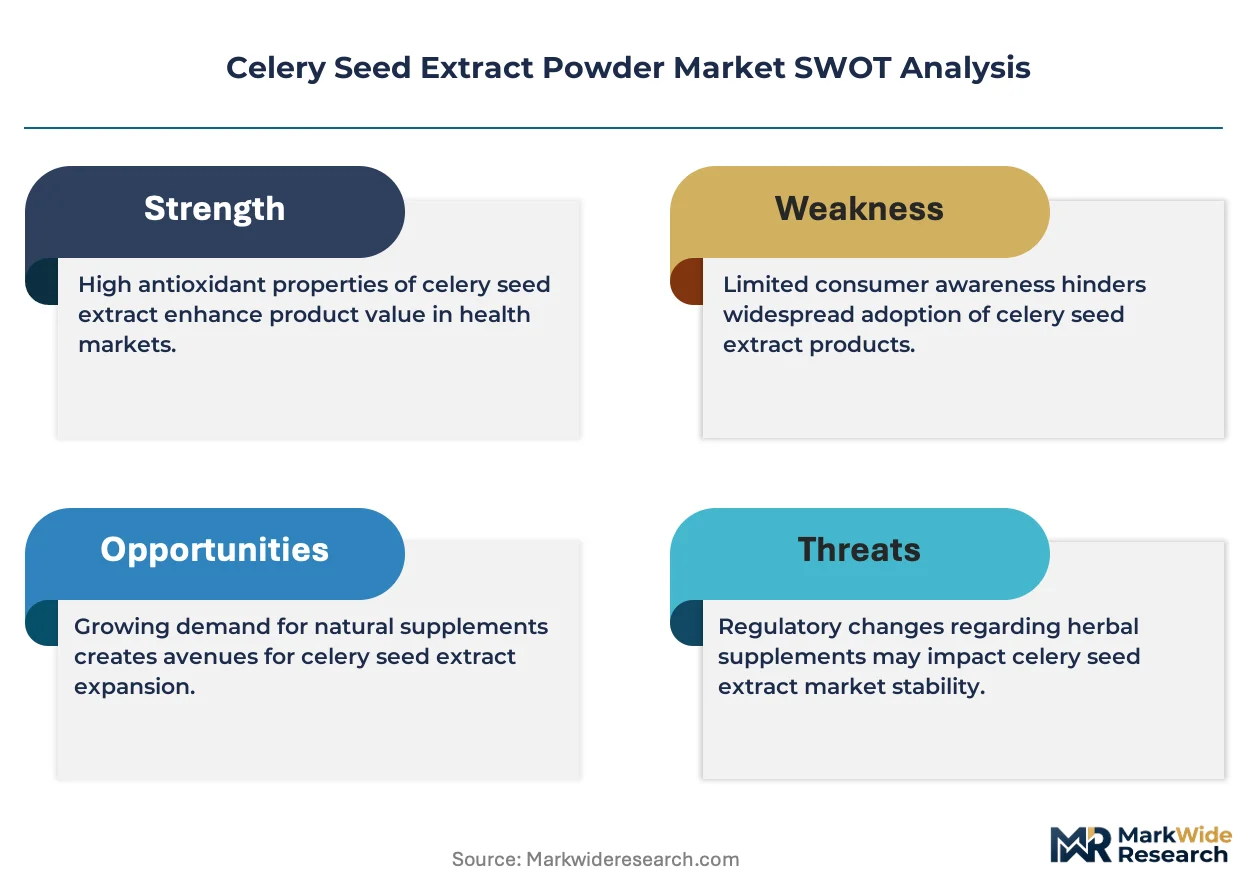
Celery seed extract powder comprises dried, milled seeds of Apium graveolens standardized for phthalide content, typically 3-n-butylphthalide and sedanenolide, via supercritical CO2 or ethanol extraction. The material functions primarily as a functional ingredient in dietary supplements targeting blood pressure management and inflammatory response modulation. Organic product type commands the highest margin pool as certification barriers limit supplier entry, while conventional grade dominates volume throughput. Nutraceuticals end user represents the fastest-expanding demand channel as clinical validation of celery seed bioactives accumulates. Dietary supplements application leads absolute consumption, though natural preservatives application is gaining traction in clean-label food manufacturing.
FDA dietary supplement cGMP enforcement and USDA National Organic Program certification shape product quality thresholds and market access conditions for celery seed extract suppliers. EFSA Novel Food assessments and EU REACH compliance for botanical extract imports create additional regulatory filtration that favors established exporters with documented safety dossiers. Stakeholders must monitor evolving pharmacovigilance requirements for botanical ingredients as regulatory agencies intensify post-market surveillance of supplement-adverse event reporting.
Market Dynamics
Supercritical CO2 extraction technology is compressing production timelines for celery seed extract while EFSA Novel Food assessments filter supplier entry, creating a bifurcation between rapid-scaling technical operators and legacy ethanol-dependent processors.
Growth Catalysts
- Cardiovascular supplement demand:Nutraceutical manufacturers are expanding procurement of celery seed extract for blood pressure management formulations as clinical validation of 3-n-butylphthalide bioactivity accumulates in peer-reviewed literature.
- EU Novel Food Regulation:Standardized safety dossiers under EFSA assessments are accelerating retail channel access for compliant suppliers across German and French health food networks.
- India cultivation expansion:Domestic Apium graveolens farming in Gujarat and Uttar Pradesh is reducing raw material lead times for extraction facilities serving European and North American buyers.
Market Restraints
- Organic certification scarcity:USDA National Organic Program and EU organic certification barriers limit supplier entry into premium-grade segments, concentrating margin capture among established certifiers.
- Phthalide standardization inconsistency:Variable 3-n-butylphthalide and sedanenolide content across batches creates formulation challenges for dietary supplement manufacturers requiring precise dosing.
- Seed supply volatility:Climate sensitivity of Apium graveolens cultivation in temperate zones generates input cost fluctuations that compress extractor margins during poor harvest cycles.
Strategic Opportunities
- Natural preservatives pivot:Clean-label food manufacturers are piloting celery seed extract as an antimicrobial alternative to synthetic preservatives in refrigerated prepared foods.
- Pharmacovigilance data services:Post-market surveillance requirements under FDA dietary supplement cGMP enforcement create advisory revenue streams for extractors with documented adverse event databases.
- Supercritical CO2 retrofit:Ethanol-dependent processors in India and Eastern Europe can capture premium pricing by upgrading extraction infrastructure to meet residual solvent limits in German pharmaceutical-grade contracts.
Industry Challenges
- Analytical chemist scarcity:Phthalide quantification via HPLC-MS requires specialized expertise that extraction facilities in emerging supply regions struggle to recruit and retain.
- Dual certification timelines:Simultaneous pursuit of USDA organic and EU Novel Food approvals extends product launch cycles by 18-24 months, tying up working capital.
- Legacy ERP integration:Batch traceability requirements for FDA cGMP compliance force mid-scale extractors to replace paper-based inventory systems with validated electronic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celery Seed Extract Powder Market |
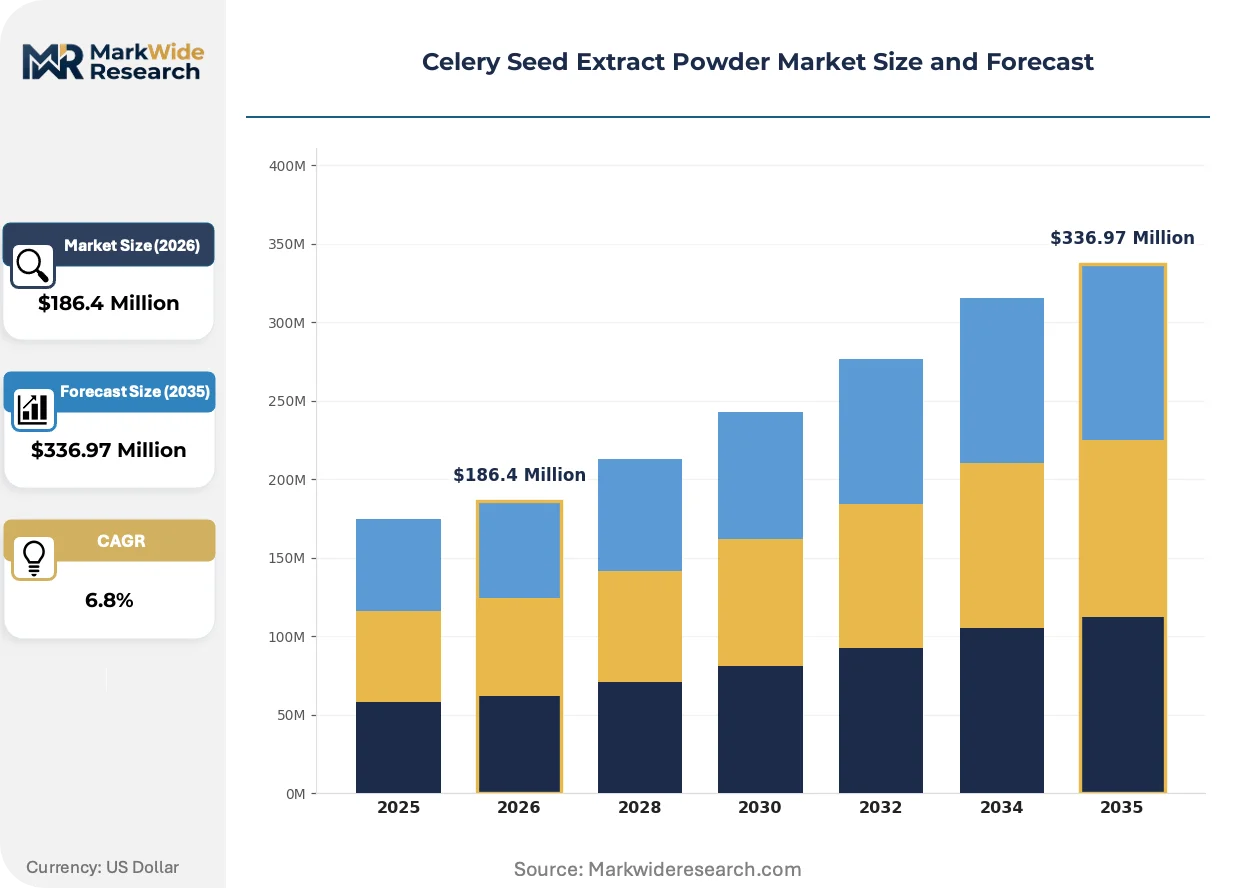
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $336.97 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Standardized, Powdered End User: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics Distribution Channel: Online, Retail, Direct Sales, Distributors Application: Dietary Supplements, Herbal Remedies, Flavor Enhancers, Natural Preservatives |
| Companies Covered | Herbalife Nutrition Ltd., Nature's Way Products, LLC, Swanson Health Products, NOW Foods, Starwest Botanicals, Inc., Organic India Pvt. Ltd., Mountain Rose Herbs, BulkSupplements.com, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celery Seed Extract Powder Market Trends and Innovations
Extraction technology convergence with digital quality assurance systems is compressing the gap between raw seed processing and finished supplement formulation, eliminating intermediate specification negotiation friction.
Supercritical CO2 extraction with inline near-infrared spectroscopy monitoring is replacing offline HPLC batch testing for real-time phthalide standardization. Dietary supplement contract manufacturers in the United States are adopting this configuration to reduce release testing from days to hours. The technology is rendering obsolete the traditional model of third-party laboratory certification before shipment.
EFSA Novel Food assessments are tightening botanical extract import documentation requirements for EU market access. Non-compliant shipments face detention at Rotterdam and Hamburg ports, forcing exporters to pre-submission dossier investment. Organic-certified celery seed extract encounters fewer assessment delays due to existing safety data pools.
Direct-procurement relationships between nutraceutical brands and extraction facilities are displacing ingredient distributor intermediaries. Large supplement retailers in the United States now contract directly with Gujarat-based processors for volume commitments. This channel compression is most visible in private-label cardiovascular formulations where price transparency pressures distributor margins.
Celery Seed Extract Powder Market Segmentation
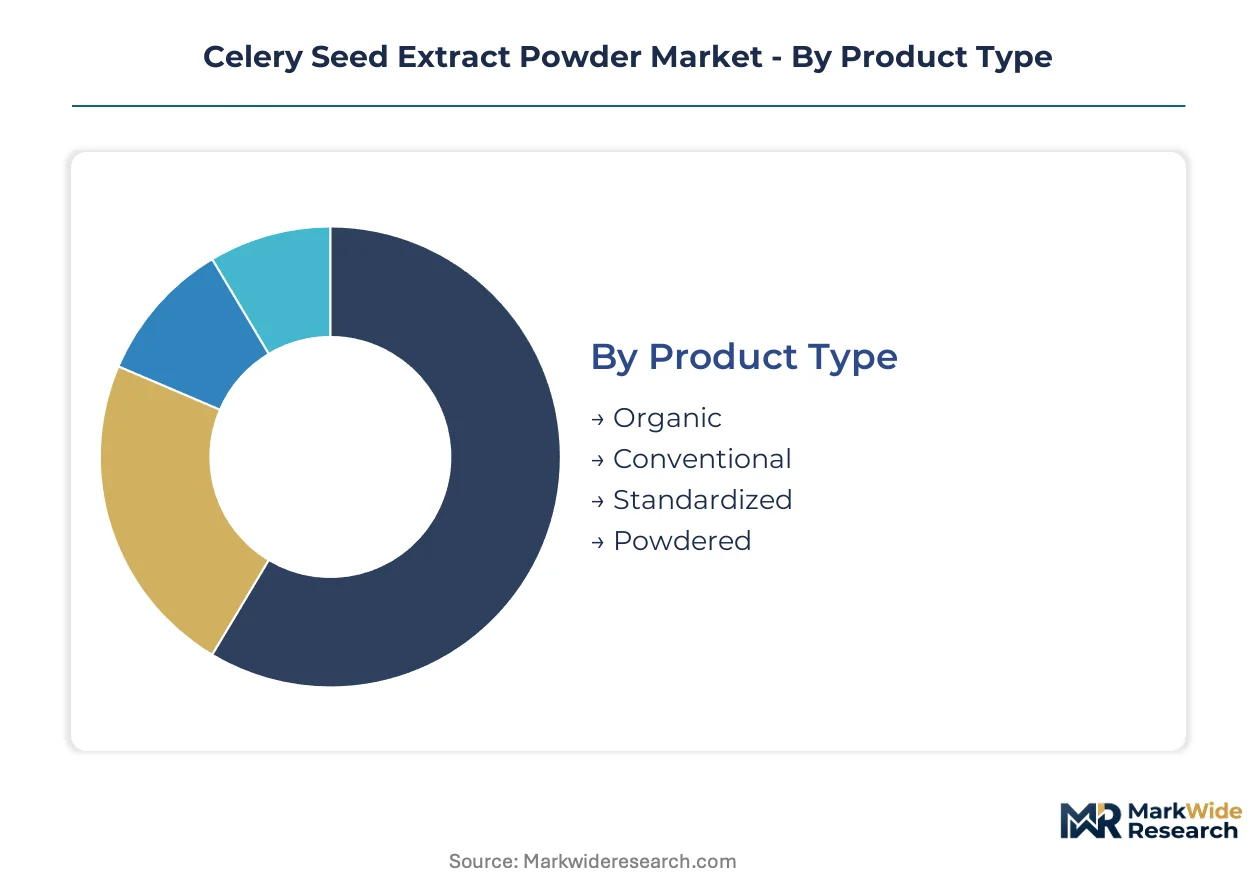
Celery seed extract powder segmentation reveals distinct margin and velocity profiles across certification grades, end-use channels, and extraction specifications. Procurement cycles vary dramatically between bulk pharmaceutical contracts and spot-market nutraceutical purchases.
Product Type:
Inventory turns compress fastest for conventional grades stocked by high-volume distributors, while organic certification extends procurement timelines through multi-stage audit requirements.
- Organic:USDA National Organic Program and EU organic certification restricts supplier entry, creating 18-24 month qualification cycles for new entrants. Premium positioning in German health food networks and North American natural products retail commands margin pools unavailable to conventional grades. Climate sensitivity of certified Apium graveolens cultivation in Gujarat and Uttar Pradesh generates supply volatility that strategic buyers hedge through multi-year contracts.
- Conventional:Unrestricted cultivation and streamlined extraction protocols enable rapid scaling for volume contracts. NOW Foods and comparable North American retailers source conventional grades for price-sensitive private-label cardiovascular formulations where phthalide standardization meets minimum thresholds rather than premium specifications.
- Standardized:Guaranteed 3-n-butylphthalide and sedanenolide content via HPLC-MS verification supports precise dosing in pharmaceutical-grade applications. Sabinsa Corporation maintains leadership through documented batch consistency that satisfies FDA cGMP enforcement requirements.
- Powdered:Milled seed material without phthalide concentration guarantees serves flavor and topical applications where bioactive standardization is unnecessary. Shorter production cycles support spot-market responsiveness for cosmetics manufacturers.
Conventional grade anchors the volume base while organic certification gains share at the steepest rate.
End User:
Contract structures diverge sharply between long-term pharmaceutical supply agreements and volatile spot purchasing from emerging cosmetics formulators.
- Nutraceuticals:Clinical validation of celery seed bioactives for blood pressure management drives formulation expansion by dietary supplement manufacturers. Direct procurement relationships between US retailers and Gujarat extraction facilities are displacing distributor intermediaries in this channel.
- Pharmaceuticals:EFSA Novel Food dossier requirements and FDA cGMP compliance create multi-year supplier qualification cycles. Documented adverse event databases and pharmacovigilance infrastructure separate qualified from speculative suppliers.
- Food & Beverage:Clean-label antimicrobial applications in refrigerated prepared foods represent emerging demand as synthetic preservative replacement accelerates. Pilot programs with US contract food manufacturers test shelf-life performance.
- Cosmetics:Anti-inflammatory positioning in topical formulations generates smaller volume demand with higher formulation flexibility requirements. Shorter product development cycles favor powdered grades over standardized extracts.
Nutraceuticals anchors the volume base while food and beverage applications expand most quickly.
Distribution Channel:
Channel economics fragment between high-touch direct sales requiring technical specification negotiation and self-service digital procurement.
- Direct Sales:Technical consultation on phthalide standardization and extraction method selection supports pharmaceutical and large nutraceutical contracts. Relationship duration averages 3-5 years with annual volume commitments.
- Distributors:Inventory aggregation and credit terms serve mid-scale supplement manufacturers lacking procurement infrastructure. Margin compression from direct-procurement trends threatens traditional distributor economics.
- Online:Digital platforms enable rapid price discovery for standardized grades with established specifications. Smaller cosmetics formulators and research institutions source pilot quantities through this channel.
- Retail:Branded finished products through health food stores and natural products chains represent downstream rather than ingredient-level distribution. Nature's Way Products leverages certified organic positioning in this channel.
Direct sales anchors the volume base while online channels climb the fastest.
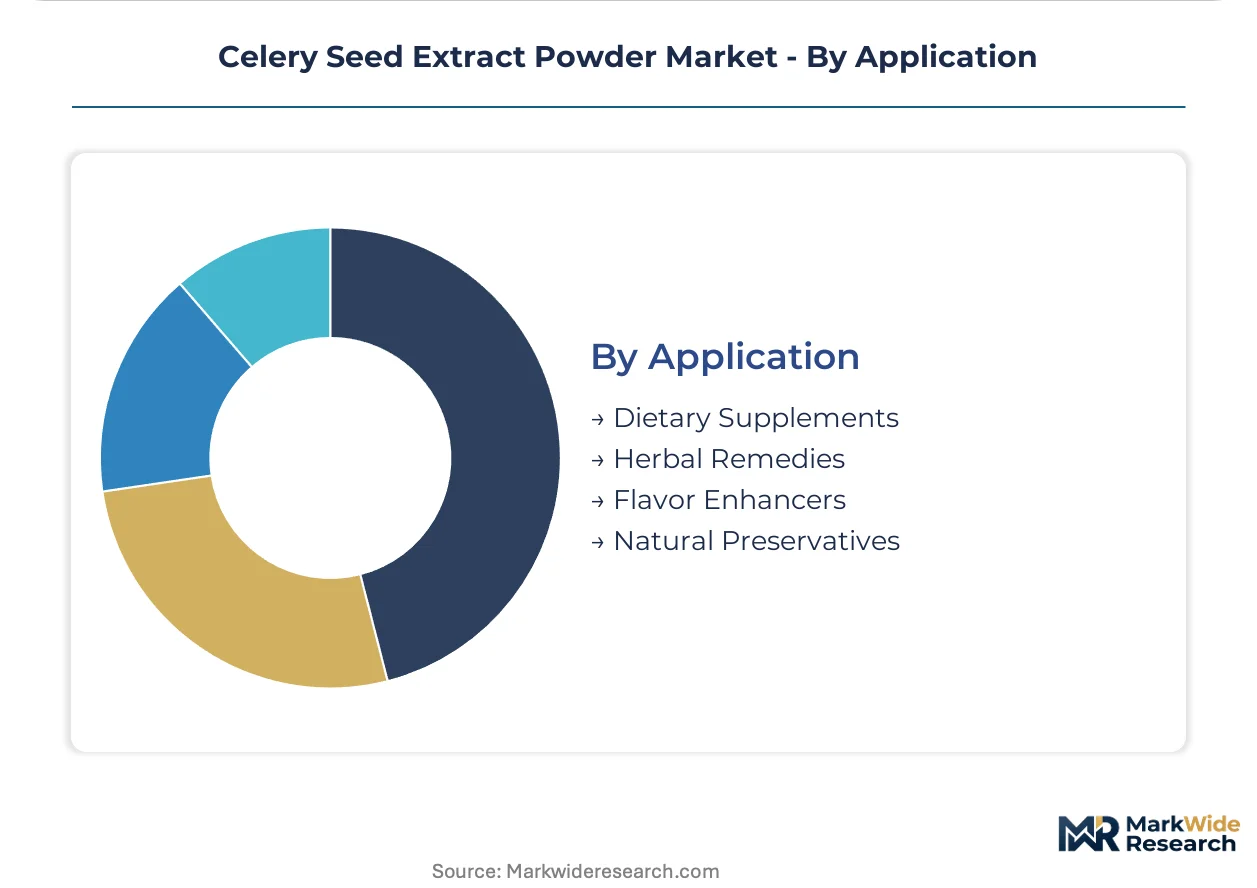
Application:
Formulation complexity ranges from single-ingredient capsules to multi-component food preservation systems with synergistic antimicrobial requirements.
- Dietary Supplements:Capsule and tablet formulations targeting cardiovascular health represent mature demand with established specification norms. Supercritical CO2 extraction with inline NIR monitoring reduces release testing timelines from days to hours for contract manufacturers.
- Natural Preservatives:Celery seed extract antimicrobial activity against Listeria and Salmonella in clean-label meat and dairy applications drives pilot manufacturing. German refrigerated prepared food manufacturers evaluate performance against synthetic alternatives.
- Herbal Remedies:Traditional medicine positioning in Ayurvedic and TCM formulations supports whole-seed and crude extract demand outside standardized phthalide specifications.
- Flavor Enhancers:Characteristic phthalide aroma profiles in savory food applications leverage powdered grades without bioactive standardization requirements.
Dietary supplements anchors the volume base while natural preservatives demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apium graveolens cultivation clusters in temperate zones with expanding extraction capacity in South Asia reshaping raw material flows. FDA cGMP enforcement in North America and EFSA Novel Food assessments in Europe filter supplier access, while Indian processing infrastructure captures contract manufacturing from Western nutraceutical brands.
United States
Dietary supplement contract manufacturers in New Jersey and California drive demand for standardized phthalide extracts. FDA dietary supplement cGMP enforcement intensifies batch documentation requirements, disqualifying smaller importers. Direct procurement relationships between retailers and Gujarat extraction facilities now bypass traditional distributor networks.
Germany
Health food retail chains in Hamburg and Munich prioritize EU organic-certified celery seed extract for cardiovascular formulations. EFSA Novel Food assessments detain non-compliant shipments at Rotterdam and Hamburg ports, favoring suppliers with pre-submitted safety dossiers. Supercritical CO2 extraction capacity concentrates in Baden-Württemberg pharmaceutical corridors.
India
Domestic Apium graveolens farming scales in Gujarat and Uttar Pradesh, reducing lead times for European and North American buyers. FSSAI food safety regulations align with export certification requirements for botanical extracts. Sabinsa Corporation leverages its phytochemical R&D infrastructure in Karnataka to sustain standardized extract production leadership.
Canada
Health Canada Natural Health Product regulations require site licensing for celery seed extract importers, extending supplier qualification timelines. Natural health product manufacturers in Ontario and British Columbia source organic grades for premium positioning in domestic retail. Vancouver-based distributors aggregate spot purchases from emerging cosmetics formulators.
Netherlands
Rotterdam port customs enforce EFSA Novel Food documentation for botanical extract imports, creating entry barriers for undocumented suppliers. Dutch ingredient traders in the Randstad region consolidate inventory for redistribution to German and French health food networks. Organic-certified extracts encounter fewer assessment delays due to existing safety data pools.
Celery Seed Extract Powder Market Competitive Landscape
Vertically integrated extractors and specialized botanical suppliers split the market between premium standardized grades and volume conventional offerings. Tiered supplier qualification emerges as FDA cGMP compliance and organic certification separate qualified from speculative participants. Two dominant competitive moves define positioning: supercritical CO2 extraction infrastructure upgrades in India, and direct-procurement relationship formation between Western retailers and South Asian processors.
Among North American nutraceutical retailers, NOW Foods and Nature's Way Products occupy positions at opposite ends of the certification spectrum. NOW Foods anchors volume throughput through conventional-grade private-label formulations, while Nature's Way Products exemplifies premium-tier positioning via certified organic sourcing protocols. Sabinsa Corporation represents the specialized extractor archetype, leveraging documented batch consistency and phytochemical R&D infrastructure to serve pharmaceutical-grade contracts requiring precise phthalide standardization.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nature's Way Products, LLC |
| Swanson Health Products |
| NOW Foods |
| Starwest Botanicals, Inc. |
| Organic India Pvt. Ltd. |
| Mountain Rose Herbs |
| BulkSupplements.com |
| Sabinsa Corporation |
| Others |
Pricing and Supply Chain Analysis
Seed supply volatility from climate-sensitive Apium graveolens cultivation in temperate zones compresses extractor margins during poor harvest cycles while simultaneously widening spreads between conventional and organic certification tiers. This input cost instability forces buyers into multi-year contracts that lock in premium pricing for certified grades while spot markets absorb residual volatility.
Pricing Analysis
FDA dietary supplement cGMP enforcement dictates the pricing tier structure by imposing compliance costs that filter speculative suppliers from qualified incumbents. Three-tier pricing separates organic-certified extracts from standardized pharmaceutical grades from conventional bulk powder. Price differentiation rests on certification depth and extraction method sophistication, with supercritical CO2-derived material commanding substantial premiums over ethanol-processed alternatives. Cost compression in conventional grades is intensifying because Indian cultivation expansion has shortened raw material lead times for volume buyers. Nutraceutical contract manufacturers exhibit highest price sensitivity, while pharmaceutical formulators prioritize batch consistency over unit economics.
Supply Chain Analysis
Extended payment terms from North American nutraceutical retailers now reach 90-120 days, forcing Gujarat and Uttar Pradesh extraction facilities to rely on supply-chain finance facilities or distributor intermediaries for working capital. Geographic supply concentrates in India, the United States, and Germany, with domestic Apium graveolens farming in Gujarat reducing European buyer lead times. Raw material dependencies encompass certified seed stock, supercritical CO2 equipment, and HPLC-MS analytical capacity. Single-source vulnerability runs through specialized phthalide quantification chemists that emerging facilities struggle to recruit. Distribution runs through direct procurement relationships that displace traditional ingredient distributors in high-volume cardiovascular formulation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of analytical chemists capable of HPLC-MS phthalide quantification creates a persistent capability gap that shapes competitive outcomes across extraction tiers and certification grades.
For Market Incumbents: Build pharmacovigilance data moats by documenting adverse event databases that satisfy FDA cGMP enforcement requirements and accelerate EFSA Novel Food assessments. Expand supercritical CO2 capacity in Karnataka or Gujarat to capture pharmaceutical-grade contracts with residual solvent specifications. Defend against direct-procurement disruption by offering integrated formulation services that embed technical consultation into supply agreements. For New Entrants and Emerging Players: Mid-scale cosmetics formulators in North America represent the most penetrable entry point, as this segment tolerates powdered grades without phthalide standardization and operates on shorter qualification cycles. Food and beverage natural preservatives applications in German refrigerated prepared foods offer second-mover advantages as pilot programs test shelf-life performance. Go-to-market execution should leverage digital procurement platforms for rapid price discovery and pilot-quantity responsiveness. For Investors and Strategic Acquirers: South Asian extraction facilities with dual USDA organic and EU Novel Food approvals command scarcity premiums as qualification timelines extend product launch cycles. Long-term viability hinges on backward integration into certified seed cultivation that insulates margin structures from climate-driven input volatility. Monitor EFSA detention rates at Rotterdam and Hamburg ports as inflection indicators for documentation-compliant supplier differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Infrastructure Upgrade | Captures pharmaceutical-grade contracts with German buyers requiring residual solvent compliance. |
| Dual Certification Pursuit | USDA organic plus EU Novel Food approval extends addressable market into premium health food retail. |
| Direct Procurement Relationship Formation | Bypasses distributor intermediaries in North American private-label cardiovascular formulations. |
| Pharmacovigilance Database Investment | Satisfies FDA cGMP enforcement and creates advisory revenue from post-market surveillance services. |
| Certified Seed Cultivation Integration | Backward integration into Gujarat organic farming reduces climate-driven supply volatility exposure. |
Research Methodology
Cross-validation between extraction facility production records and North American nutraceutical procurement databases anchors the qualitative findings on supply chain restructuring. Primary interviews with phytochemical R&D directors, dietary supplement contract manufacturing executives, EU regulatory affairs consultants, and Indian cultivation cooperatives combined with secondary validation from FSSAI export filings, EFSA Novel Food assessment registers, FDA cGMP inspection observations, and customs trade data. Bottom-up volume modeling from individual extraction facility capacities and top-down demand estimation from end-use consumption patterns were reconciled through iterative triangulation.
Calibration against historical price realization data for organic versus conventional grades informed the projection framework across the analysis window. Segmentation dimensions modeled encompass certification grade, extraction method, end-use channel, and phthalide standardization level. CAGRs were derived from slope analysis of segment-specific demand trajectories, with celery seed bioactive clinical validation timelines and clean-label food manufacturing adoption curves serving as industry-specific forecast inputs.
Practitioners should monitor EFSA Novel Food assessment backlogs, FDA cGMP enforcement intensity, and Apium graveolens harvest yield reports for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Saffron Market