
 Ketchup Concentrates Market | 2026-2036
Ketchup Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Ketchup Concentrates Market Foresight
Food service operators are redrawing procurement patterns for ketchup concentrates, shifting from finished goods toward bulk concentrate bases that lower per-unit costs and storage footprints. The Kraft Heinz Company leverages its captive tomato processing infrastructure across California and the Midwest to sustain cost advantages in industrial-grade supply. Conagra Brands anchors its position through long-term co-manufacturing contracts with major quick-service chains. Kagome Co., Ltd. differentiates via Japanese cultivar expertise and specialized umami-forward concentrate profiles.
Ketchup concentrates are highly viscous tomato-based preparations, typically manufactured through evaporation, pasteurization, and controlled reduction to achieve soluble solids concentrations between 28 and 36 degrees Brix, serving as standardized inputs for sauce reconstitution, filling lines, and institutional batch preparation. The conventional product type dominates current volume owing to its cost structure and compatibility with legacy processing equipment, while organic concentrates command disproportionate margin pools as certified supply chains tighten. Within end use, food service absorbs the largest share of concentrate volume, though industrial applications for ready-meal and sauce manufacturers represent the fastest-expanding demand channel.
The FDA governs acidified food regulations and nutritional labeling standards that dictate concentrate formulation thresholds, while USDA organic certification requirements constrain ingredient sourcing and processing methods for premium-tier products. State-level sodium reduction mandates in California and New York are accelerating reformulation investments across reduced sodium product lines. Stakeholders must monitor how evolving clean-label standards and concentrate-to-finished-goods yield ratios reshape procurement economics and capital allocation across processing assets.
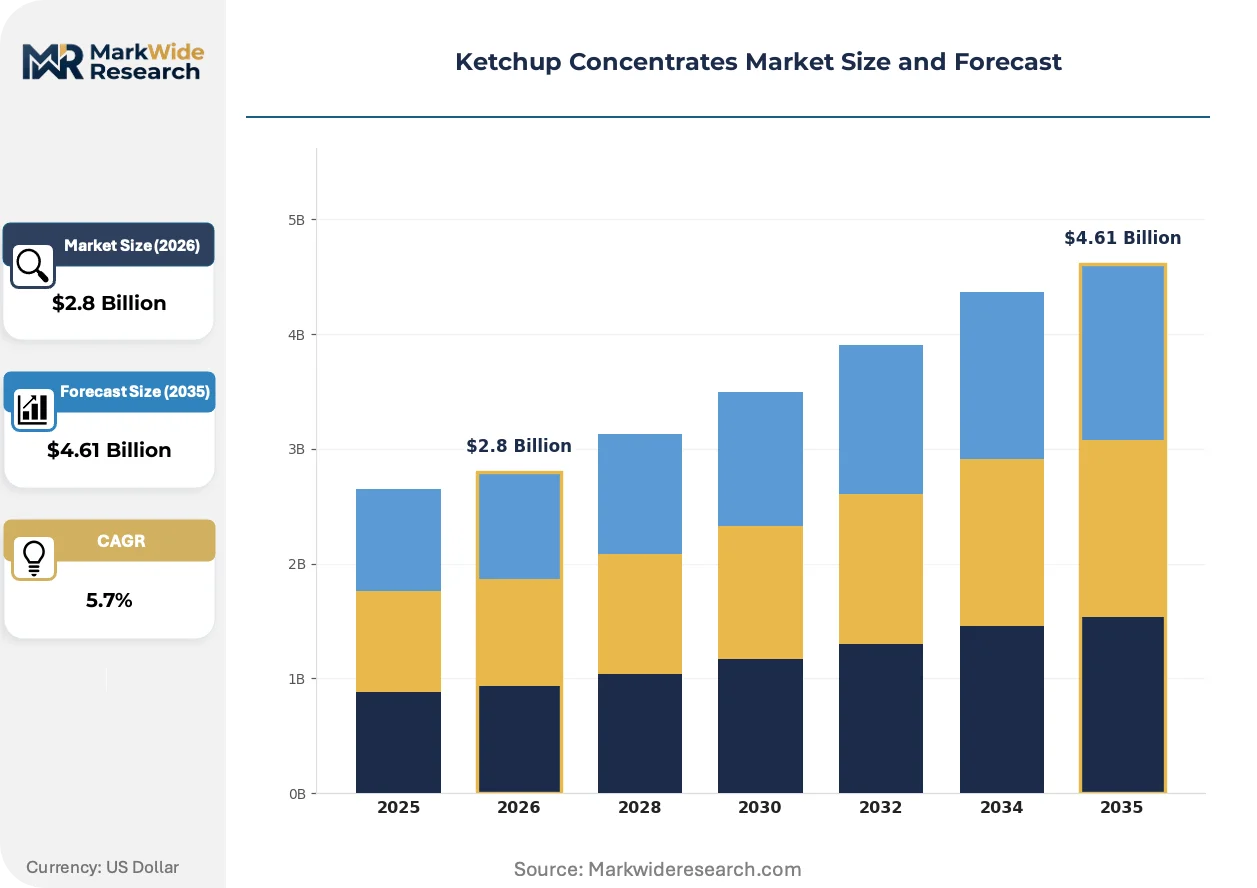
Market Dynamics
Food service operators are compressing their kitchen footprints and standardizing sauce preparation, creating pull for high-Brix concentrate bases that reconstitute at ratios of 1:3 to 1:5 versus finished ketchup. This operational efficiency mandate is restructuring procurement volumes toward industrial-grade supply contracts.
Growth Catalysts
- California sodium reduction mandates:State-level labeling requirements are forcing reformulation investments that expand the addressable market for reduced-sodium concentrate variants.
- Quick-service restaurant batch automation:Chains deploying centralized sauce kitchens require standardized concentrate inputs with consistent viscosity and acid profiles.
- Evaporative concentration technology:Falling-film and mechanical vapor recompression systems are lowering energy costs per Brix point in tomato processing.
Market Restraints
- California drought exposure:Tomato processing concentrates in the Central Valley, where water scarcity raises input cost volatility and crop yield risk.
- Legacy equipment incompatibility:High-Brix concentrates above 32 degrees require heated transfer lines and modified filling heads that many mid-scale sauce kitchens lack.
- FDA acidified food compliance:Concentrate pH and water activity thresholds impose formulation constraints that limit flavor innovation and extend R&D timelines.
Strategic Opportunities
- USDA organic certification tailwinds:Premium-tier concentrate demand outpaces certified tomato supply, creating margin expansion for growers with third-party audit infrastructure.
- Direct-to-foodservice distribution:Bypassing traditional broadline distributors through tanker-truck delivery of bulk concentrate cuts handling costs and extends shelf life.
- Umami-forward profiles:Japanese cultivar expertise enables differentiation in Asian-American restaurant chains seeking authentic base flavors.
Industry Challenges
- Food safety certification timelines:SQF and BRC audits for concentrate processing facilities average 8-14 months, delaying market entry for new suppliers.
- Clean-label reformulation complexity:Removing conventional preservatives while maintaining 18-month concentrate stability requires investment in aseptic packaging and cold-chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketchup Concentrates Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Reduced Sodium, Specialty End Use: Food Service, Retail, Industrial, Household Packing Type: Glass Jars, Plastic Bottles, Pouches, Tubs Flavor Profile: Spicy, Smoky, Sweet, Traditional |
| Companies Covered | The Kraft Heinz Company, Conagra Brands, Unilever PLC, Nestlé S.A., Del Monte Foods, Kagome Co., Ltd., Mutti S.p.A., General Mills, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketchup Concentrates Market Shifts & Advancements
Processing technology and regulatory pressure are converging to reshape how tomato solids are concentrated, stored, and reconstituted across institutional kitchens and industrial sauce lines.
Membrane filtration systems are miniaturizing. Reverse osmosis and nanofiltration modules now achieve 28-32 Brix concentration without thermal degradation of volatile flavor compounds. Mid-scale sauce manufacturers in the Midwest are adopting skid-mounted units that slot into existing plant layouts. This distributed processing model is compressing freight costs and enabling regional sourcing of lower-solids tomato paste.
REACH chemical registration requirements in Europe are tightening specifications for processing aids and equipment sanitizers used in concentrate manufacturing. Industrial tomato processors must now document full substance inventories for heat-exchange fluids and cleaning agents. Organic-certified concentrate lines face the strictest compliance burden, driving substitution toward enzyme-based cleaning protocols.
Buyer consolidation among US quick-service chains is concentrating purchasing power and extending contract durations. Ten-unit operators now access pricing tiers previously reserved for hundred-unit groups through cooperative buying organizations. This channel compression is most visible in the Southeast, where regional franchisee associations negotiate directly with concentrate packers for tanker-truck delivery terms.
Ketchup Concentrates Market Segmentation
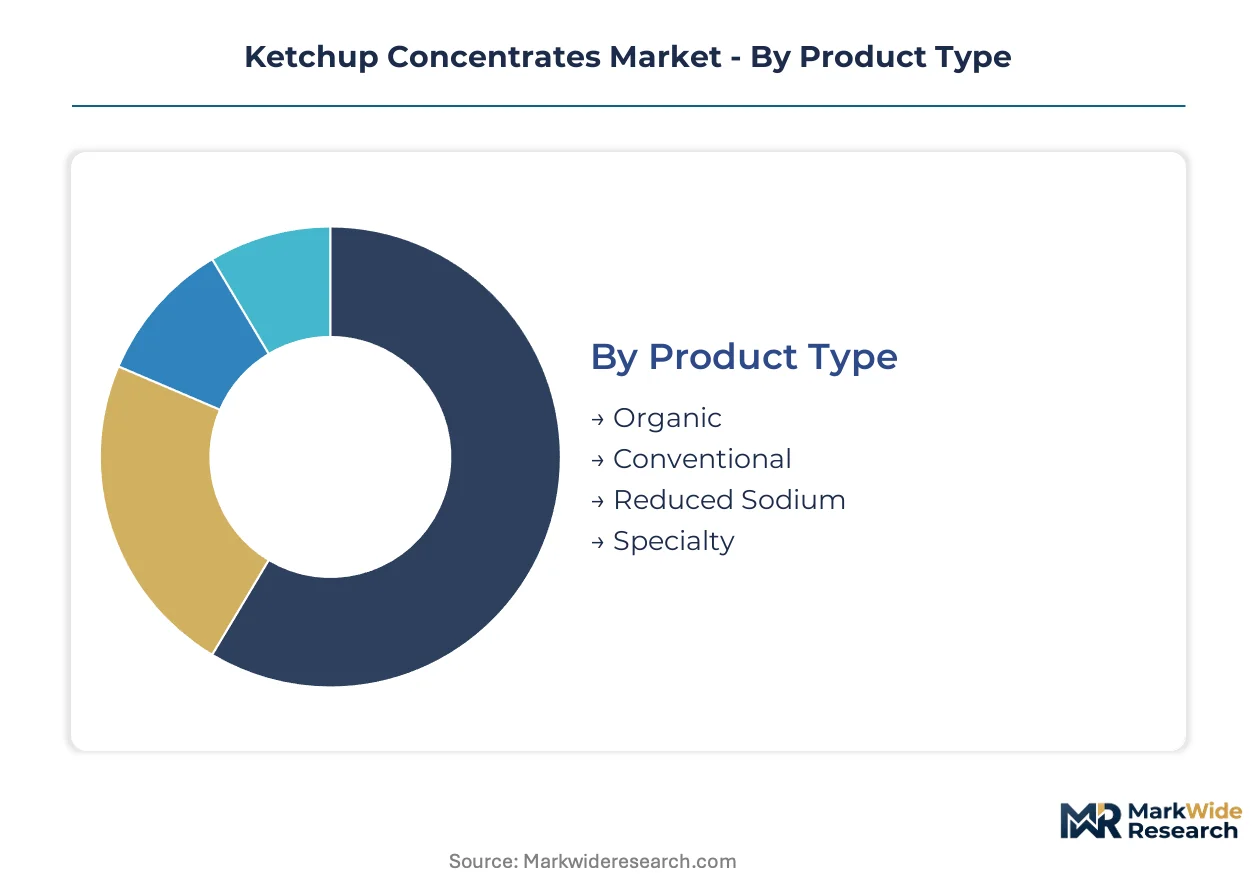
Ketchup concentrate buyers segment procurement by formulation standards, operational use case, and reconstitution requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Substitution pressure from clean-label alternatives and sodium-reduced formulations is fragmenting procurement across product type tiers.
- Conventional:Standard tomato solids concentration between 28-36 degrees Brix without organic certification. Quick-service restaurant chains in the United States drive procurement volume for this tier due to cost sensitivity and legacy equipment compatibility. FDA acidified food regulations govern pH thresholds without imposing premium sourcing constraints.
- Organic:USDA-certified tomato supply chains with third-party audited processing protocols. Premium-tier demand concentrates in food service operators targeting health-conscious consumers, though certified tomato acreage constraints limit supply expansion and compress margins for non-certified processors.
- Reduced Sodium:Reformulated concentrates meeting California and New York state-level sodium labeling mandates. Institutional buyers in school districts and healthcare facilities face procurement pressure from these mandates.
- Specialty:Cultivar-specific profiles including heirloom tomato bases or regionally sourced varietals. Craft sauce manufacturers and upscale restaurant chains absorb limited volumes.
Conventional retains volume leadership; organic holds the steepest expansion curve.
End Use:
Cost tier differentiation separates high-volume industrial contracts from fragmented household procurement with divergent logistics economics.
- Food Service:Bulk concentrate delivery via tanker truck or intermediate bulk containers to centralized sauce kitchens. Quick-service restaurant chains and institutional cafeterias in the United States compress per-unit costs through cooperative buying organizations.
- Industrial:Standardized inputs for ready-meal manufacturers and sauce packagers requiring consistent viscosity and acid profiles for automated filling lines. This channel is expanding most quickly as batch automation spreads across Midwest processing facilities.
- Retail:Branded concentrate bases for private-label ketchup production sold through broadline distributors. Shelf-stable packaging requirements extend formulation complexity.
- Household:Small-format concentrates for consumer reconstitution, typically distributed through e-commerce and club retail channels with higher per-ounce logistics costs.
Food service dominates current procurement tonnage; industrial applications are climbing the fastest.
Packing Type:
Volume concentration in bulk formats is displacing traditional retail packaging across food service procurement.
- Tubs:Intermediate bulk containers ranging from 5-gallon pails to 55-gallon drums for high-throughput sauce kitchens. Chains with centralized batch preparation favor this format for reduced handling labor.
- Pouches:Flexible aseptic packaging for concentrate portions with extended ambient shelf stability. Regional distributors in the Southeast United States are adopting pouch formats for food service delivery.
- Plastic Bottles:Standard retail-facing containers for branded concentrate lines requiring consumer pouring convenience. PET resin cost volatility affects margin stability.
- Glass Jars:Premium-positioned packaging for organic and specialty concentrates targeting clean-label perception. Higher freight costs limit geographic distribution radius.
Tubs retain volume leadership; pouches are gaining share fastest.
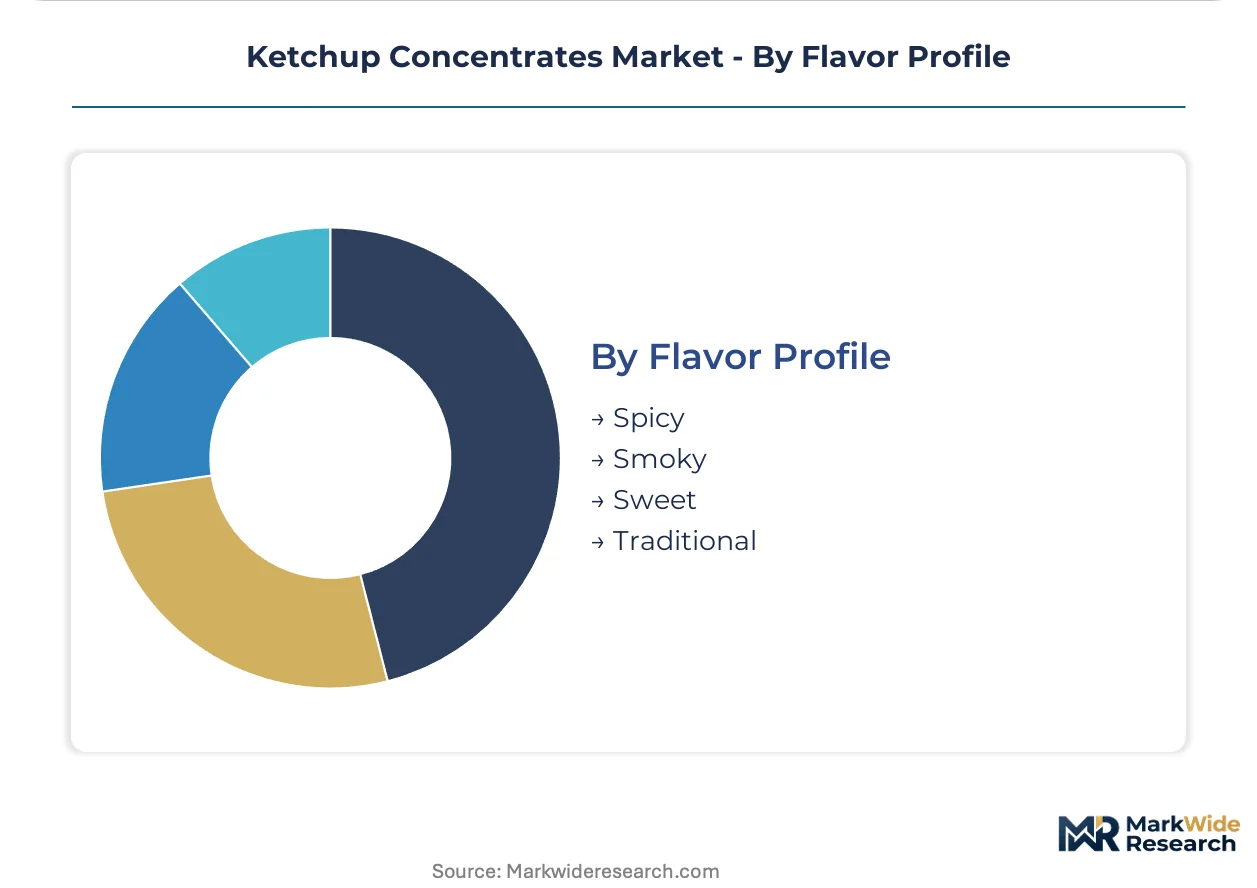
Flavor Profile:
Application-specific demand from ethnic restaurant chains is diversifying flavor procurement beyond traditional tomato bases.
- Traditional:Standard sweet-acid balance derived from processing tomato cultivars with consistent Brix and pH specifications. Legacy quick-service chains maintain procurement concentration here.
- Spicy:Capsicum-infused concentrates with Scoville-calibrated heat levels for Mexican-American and Asian-American restaurant chains. Kagome Co., Ltd. cultivar expertise supports differentiated supply.
- Smoky:Liquid smoke or fire-roasted tomato concentrates for barbecue-focused operators and regional sauce manufacturers.
- Sweet:Elevated sugar or alternative sweetener profiles targeting specific demographic taste preferences in the southeastern United States.
Traditional retains volume leadership; spicy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and institutional food service operators concentrate procurement power in specific national markets where kitchen automation and bulk concentrate delivery have achieved critical mass. Regulatory pressure on sodium content and clean-label standards varies sharply across jurisdictions, reshaping supplier qualification requirements.
United States
California and New York state sodium reduction mandates are accelerating reformulation investments for reduced-sodium concentrate variants. FDA acidified food regulations govern pH thresholds and water activity standards that constrain formulation flexibility. The Central Valley tomato processing cluster faces escalating water scarcity risks that compress crop yields and elevate input cost volatility for concentrate manufacturers.
Japan
Umami-forward concentrate profiles from specialized tomato cultivars command premium positioning in Asian-American restaurant supply chains. METI food safety standards and JIS processing equipment specifications shape facility investment requirements. The Kagome technical center in Nagoya anchors cultivar development programs that differentiate Japanese concentrate supply in export markets.
Italy
Mutti S.p.A. processing infrastructure in Parma exemplifies heritage-brand concentration in specialty and organic concentrate tiers. EFSA labeling standards and EU organic certification protocols constrain ingredient sourcing flexibility. The Po Valley tomato belt maintains contracted acreage relationships that buffer certified organic supply against spot market volatility.
Germany
REACH chemical registration requirements tighten specifications for processing aids and heat-exchange fluids used in concentrate manufacturing. Industrial sauce manufacturers in Baden-Württemberg deploy membrane filtration modules that achieve thermal concentration without volatile compound degradation. The Stuttgart metropolitan area hosts mid-scale processors adopting skid-mounted reverse osmosis units for distributed production.
China
Domestic quick-service expansion drives bulk concentrate procurement through cooperative buying organizations in tier-one cities. SAMR food safety standards and GB processing specifications govern facility licensing and product registration timelines. The Xinjiang processing corridor supplies tomato paste intermediates that feed coastal reconstitution and packaging facilities.
Ketchup Concentrates Market Competitive Landscape
Player mix skews toward diversified food conglomerates with captive tomato processing infrastructure and specialized regional cultivar experts. The competitive structure tiers across three levels: multinational packaged food corporations with backward-integrated supply chains, mid-scale co-manufacturing specialists serving quick-service contracts, and heritage-brand processors occupying organic and specialty niches. Dominant competitive moves include long-term procurement contracting with restaurant chains and technology licensing for evaporative concentration systems.
Among North American packaged food conglomerates, The Kraft Heinz Company and Conagra Brands occupy positions that exemplify scale-driven supply consolidation. Kagome Co., Ltd. represents the specialized cultivar archetype, anchoring umami-forward differentiation in Asian-American food service channels. These three entities illustrate how competitive positioning stratifies across volume efficiency versus flavor specialization vectors.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands |
| Unilever PLC |
| Nestlé S.A. |
| Del Monte Foods |
| Kagome Co., Ltd. |
| Mutti S.p.A. |
| General Mills |
| Kerry Group |
| Others |
Supply & Pricing Matrix
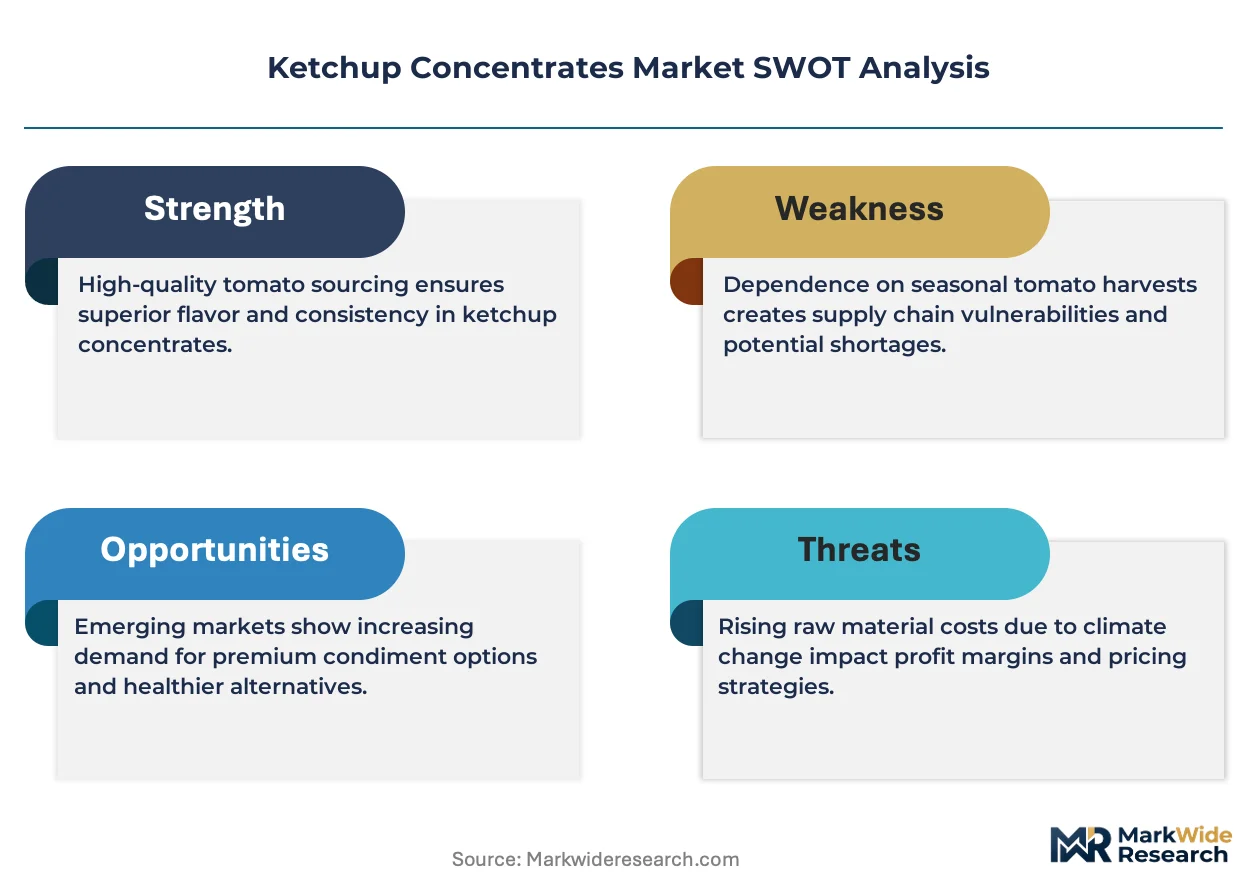
USDA organic certification requirements gate both supplier qualification and price tier separation in ketchup concentrates, compressing uncertified processors into commodity pricing while rewarding third-party-audited infrastructure with premium positioning across food service procurement.
Pricing Analysis
Evaporative concentration technology divides pricing tiers sharply: legacy thermal systems anchor standard-grade concentrates, falling-film mechanical vapor recompression commands mid-tier positioning, and membrane filtration without thermal degradation anchors premium pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification status and Brix concentration precision. Cost compression in conventional tiers intensifies because Central Valley water scarcity elevates raw tomato input volatility. Quick-service restaurant chains exhibit highest price sensitivity through cooperative buying organizations, while Asian-American restaurant operators absorb premium pricing for umami-forward cultivar profiles.
Supply Chain Analysis
Central Valley water allocation bottlenecks expose concentrate processors to yield volatility that propagates through contract pricing. California, Italy's Po Valley, and China's Xinjiang corridor anchor global tomato paste supply. Processing draws from fresh tomato harvests, energy-intensive evaporation equipment, and aseptic packaging materials. Single-source vulnerability concentrates in California's drought-exposed acreage. Distribution runs through tanker-truck direct delivery to centralized sauce kitchens and broadline food service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration miniaturization disrupts incumbent capital structures, compressing regional processing economics and fragmenting supply concentration as mid-scale Midwest facilities adopt skid-mounted units.
For Market Incumbents: Compound defensive positioning through backward integration into captive California tomato acreage and accelerated USDA organic certification timelines. The threat of cooperative buying organizations consolidating purchasing power demands channel control through direct tanker-truck delivery infrastructure. Capacity addition in membrane filtration technology preserves margin position against energy cost volatility. For New Entrants and Emerging Players: Direct-to-foodservice distribution gaps where broadline distributors extract handling margins present the most penetrable white-space target. Tanker-truck delivery partnerships with ten-unit regional quick-service operators bypass incumbent distributor relationships. Specialty umami-forward profiles for Asian-American restaurant chains offer differentiation without competing on conventional concentrate scale economics. For Investors and Strategic Acquirers: California sodium reduction mandates reshape the acquisition landscape toward reduced-sodium formulation capabilities and reformulation R&D assets. Long-term viability centers on processors with dual conventional-organic line flexibility and aseptic packaging infrastructure. The signal to watch is FDA acidified food regulation tightening that would extend compliance timelines and consolidate supplier qualification toward scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tomato Acreage | Captive California supply buffers processors against Central Valley water allocation volatility. |
| Membrane Filtration Technology Adoption | Skid-mounted reverse osmosis units enable Midwest regional processors to compress freight costs. |
| USDA Organic Certification Investment | Third-party audit infrastructure unlocks premium-tier pricing in health-conscious food service channels. |
| Direct-to-Foodservice Distribution Buildout | Tanker-truck delivery bypasses broadline distributor margins and extends concentrate shelf stability. |
| Reduced-Sodium Formulation R&D | California and New York state mandates expand addressable market for compliant concentrate variants. |
Research Methodology
Operator-level perspectives from quick-service restaurant procurement directors, institutional cafeteria supply managers, tomato processing plant engineers, and broadline distributor category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA acidified food regulation filings, USDA organic certification databases, California agricultural water allocation records, and SEC 10-K disclosures from packaged food conglomerates. Bottom-up volume modeling across concentrate Brix tiers and top-down value triangulation against food service expenditure data cross-checked segment-level outputs.
Sensitivity analysis tested forecast robustness across drought severity scenarios in California's Central Valley and membrane filtration adoption curves in Midwest processing facilities. Segmentation dimensions modeled include product type tier, end-use channel, packaging format, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for technology substitution effects and contract duration extensions among cooperative buying organizations. Industry-specific inputs encompass tomato paste trade flows and evaporative concentration energy cost indices.
Underlying assumptions cover stable FDA acidified food pH thresholds, continued California sodium mandate enforcement, and membrane filtration module cost decline curves, with deviation risk concentrated in water scarcity intensity and organic tomato acreage expansion rates. Practitioners should keep alternative scenarios live as state-level labeling requirements and clean-label preservative substitution timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Low Fat Spaghetti Sauce Market
Condiments & Sauces
Soy-Based Sauce Market