
 Sauces and Condiments Market | 2026-2036
Sauces and Condiments Market Size, Share, and Industry Trends Forecast 2026-2036
Sauces and Condiments Market Analysis
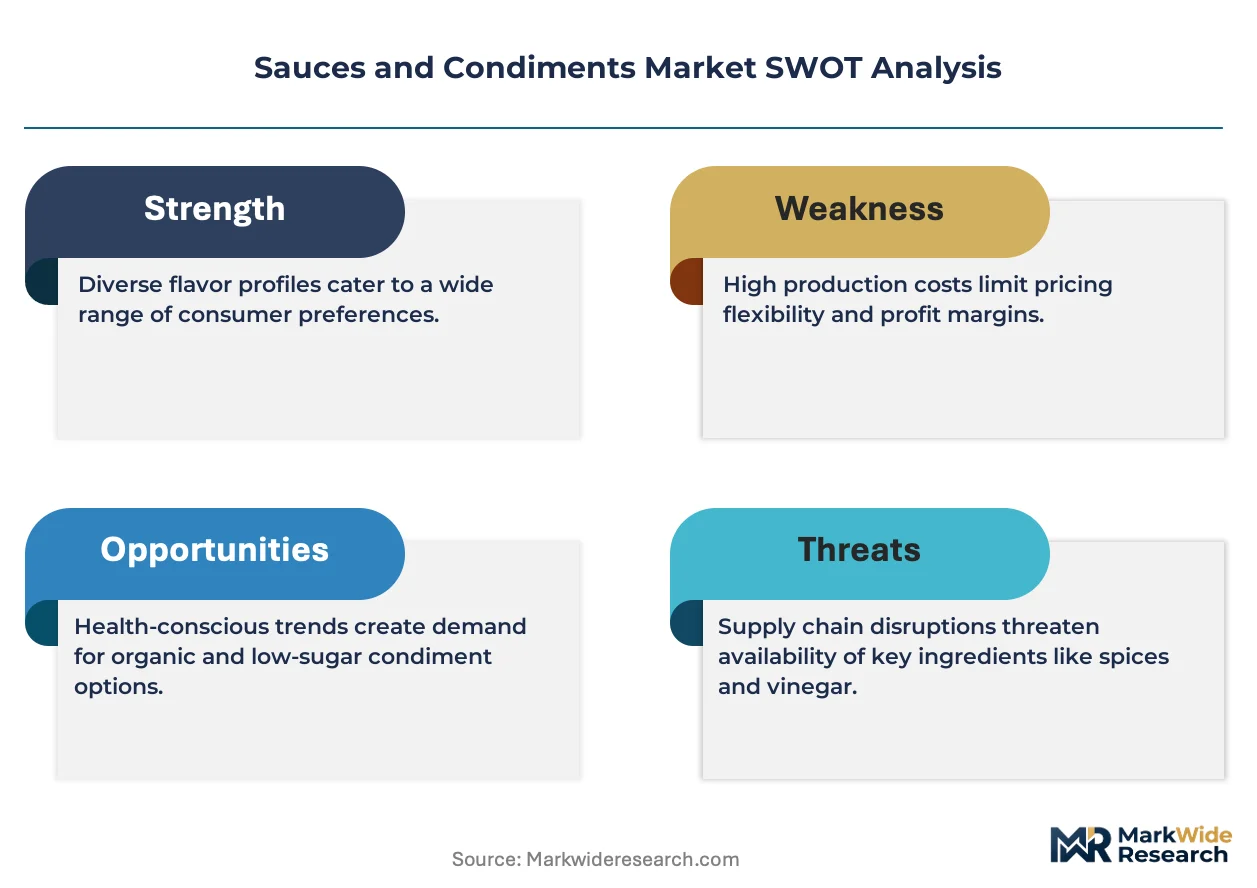
Asset-light co-manufacturing and private-label leasing arrangements is fragmenting competitive dynamics in sauces and condiments, enabling smaller brands to access industrial-scale production without capital-intensive facility investments. Kraft Heinz Company anchors its position through backward integration into tomato processing and vinegar production. Kikkoman Corporation dominates fermented soy sauce capacity with century-old brewing expertise that competitors struggle to replicate. McCormick & Company differentiates through flavor science investments spanning sweet, spicy, and savory profile development.
Sauces and condiments comprise prepared flavor-enhancing preparations typically formulated from vinegar, oil, spices, fermented substrates, or vegetable purees, with functional parameters including pH below 4.6 for shelf-stable products and water activity controls ensuring microbiological safety. These formulations serve industrial food manufacturing, food service portion control, and household consumption as taste modifiers, moisture agents, and cultural signifiers. Ketchup and hot sauce lead volume pools in North American and Latin American markets respectively, while soy sauce commands premium positioning in East Asian and diaspora retail channels. The powder and granular form category is gaining traction in industrial applications where shipping weight reduction and extended ambient stability reduce logistics costs.
FDA enforcement of updated Nutrition Facts labeling and sodium reduction guidance shapes product reformulation timelines for US-market manufacturers. EFSA evaluations under the EU Food Improvement Agent regulation and REACH compliance for packaging migrants constrain ingredient sourcing and material selection across European supply chains. The EU Green Deal packaging waste directives are accelerating transitions toward recyclable and reduced-plastic formats. Stakeholders must monitor evolving front-of-pack labeling schemes and carbon accounting requirements that will determine which formulation and packaging investments preserve market access.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are compressing formulation timelines while co-manufacturing networks fragment production control across the sauces and condiments value chain.
Growth Catalysts
- Street food proliferation:Southeast Asian urban centers from Bangkok to Ho Chi Minh City are expanding quick-service restaurant chains that require standardized condiment portfolios for menu consistency.
- Fermentation biotechnology:Precision-controlled brewing systems are accelerating soy sauce and vinegar production cycles while preserving traditional flavor profiles.
- EU Green Deal packaging directives:Recyclable format mandates are pulling investment into mono-material sachets and glass bottle return schemes across European supply chains.
Market Restraints
- Tomato paste supply concentration:California Central Valley drought cycles and Spanish processing consolidation create raw material volatility for ketchup manufacturers.
- Acetic acid feedstock dependency:Petrochemical-derived ethanol remains the dominant vinegar precursor, exposing margins to crude oil price swings.
- pH stability thresholds:Shelf-stable formulations below 4.6 pH limit clean-label ingredient options, constraining sodium reduction pathways.
Strategic Opportunities
- Industrial powder formats:Shipping weight reduction and extended ambient stability are opening quick-service restaurant and airline catering procurement channels.
- US Nutrition Facts modernization:FDA sodium disclosure rules are creating first-mover advantage for brands with pre-positioned reduced-sodium formulations.
- Umami extract convergence:Yeast-derived flavor enhancers combined with mushroom fermentation byproducts are enabling sodium replacement without taste compromise.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise spanning pH control, water activity management, and clean-label stability commands premium compensation and extended recruitment cycles.
- Legacy equipment retrofit costs:Aseptic filling lines designed for high-acid liquids require substantial modification to handle emerging oil-in-water emulsion formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sauces and Condiments Market |
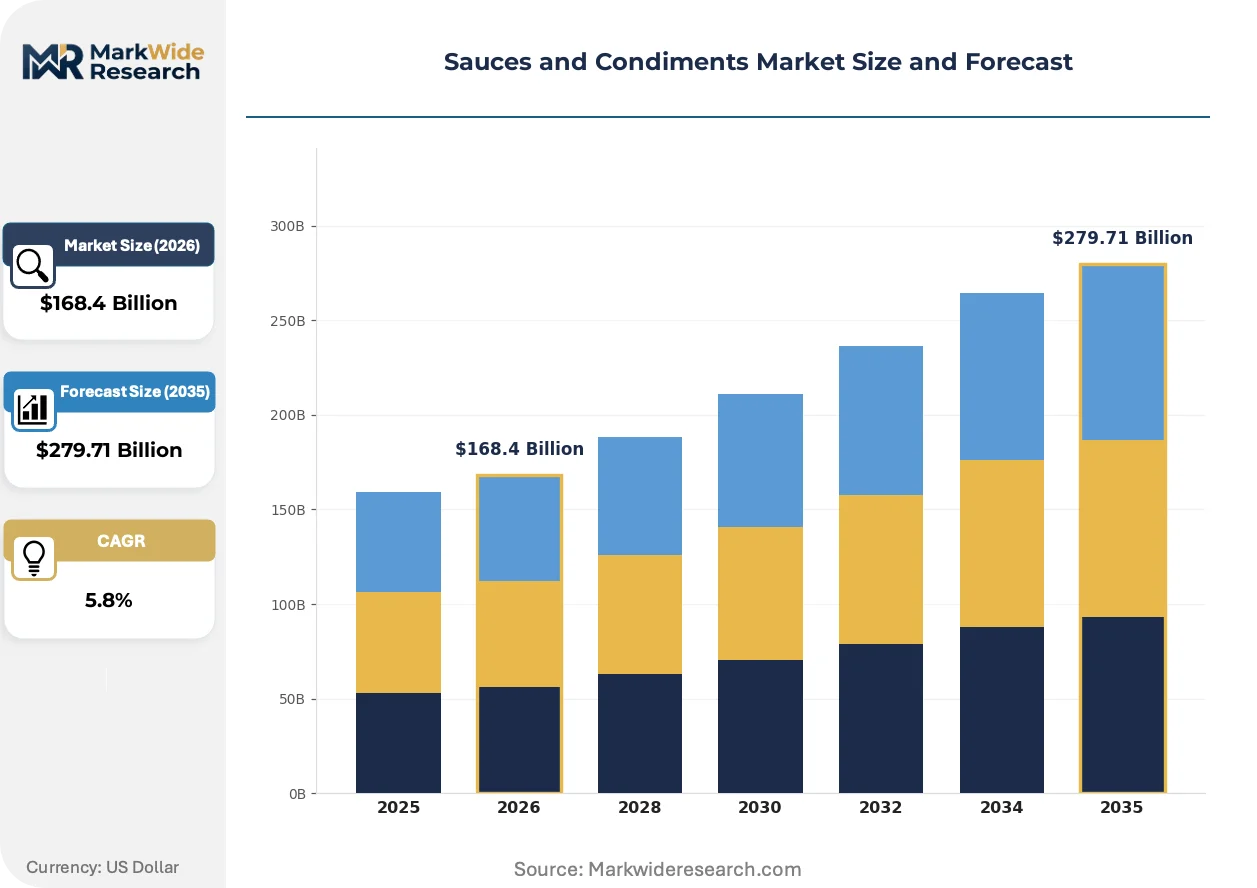
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mustard, Hot Sauce, Soy Sauce Form: Liquid, Paste, Powder, Granular Flavor Profile: Sweet, Spicy, Savory, Tangy End User: Household, Food Service, Retail, Industrial |
| Companies Covered | Unilever PLC, PepsiCo Inc, Kraft Heinz Company, Hormel Foods Corporation, Nestle SA, Kikkoman Corporation, Conagra Brands Inc, Kewpie Corp, McCormick & Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sauces and Condiments Market Emerging Trajectories
Reformulation science and packaging material innovation are converging to reshape competitive positioning in shelf-stable flavor preparations, with regulatory pressure acting as the primary accelerant.
High-pressure processing is collapsing the traditional trade-off between clean-label ingredient lists and extended ambient shelf life. Mid-sized regional brands are adopting HPP systems for refrigerated salsa and pesto lines, compressing the premium pricing window that thermal pasteurization previously commanded. Food service distributors are consolidating procurement around HPP-compatible suppliers to reduce spoilage claims.
REACH compliance for packaging migrants is constraining multilayer film specifications across European supply chains. EFSA evaluations under the Food Improvement Agent regulation are extending approval timelines for novel preservative systems, forcing manufacturers to accelerate natural antimicrobial research. German and French retail chains are imposing front-of-pack scoring requirements that exceed regulatory minimums.
Direct-to-restaurant subscription models are fragmenting traditional broadline distributor control over condiment procurement. Independent operators in Melbourne, Austin, and Copenhagen are sourcing small-batch fermented products through specialized logistics platforms, bypassing conventional food service hierarchies. This channel shift is most pronounced among chef-driven concepts seeking provenance differentiation.
Sauces and Condiments Market Segmentation
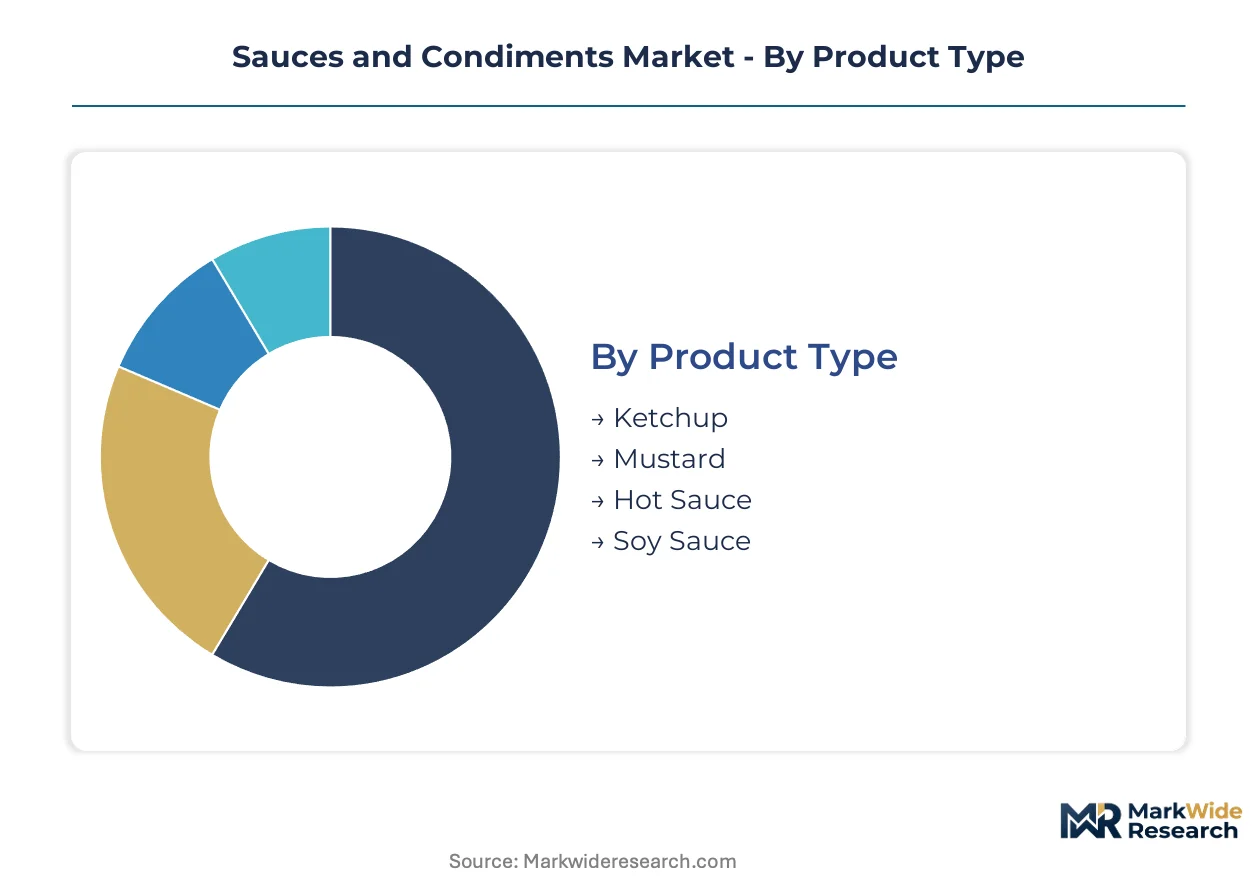
Sauces and condiments manufacturers configure production lines around distinct physical states and consumption contexts. Each segmentation axis carries different margin profiles, shelf-life requirements, and regulatory burdens that shape investment priorities.
Product Type:
Use-case spectrum spans from standardized fast-food accompaniments to artisanal fermentation products commanding premium positioning.
- Ketchup:Tomato-based formulations with pH below 3.9 and viscosity calibrated for controlled dispensing. California drought cycles and Spanish processing consolidation are creating raw material volatility for manufacturers dependent on concentrated tomato paste supply.
- Soy Sauce:Fermented soybean and wheat substrates brewed through koji mold enzymatic hydrolysis. East Asian urban centers and diaspora retail channels in Melbourne, Los Angeles, and Vancouver sustain premium pricing for traditionally brewed varieties.
- Mustard:Brassica seed emulsions with acetic acid preservation. French Dijon and American yellow varieties serve distinct food service procurement channels with incompatible flavor expectations.
- Hot Sauce:Capsicum-derived heat units suspended in vinegar or oil matrices. Latin American markets and Southeast Asian street food vendors drive volume concentration for Scoville-calibrated industrial formulations.
The dominant share belongs to ketchup, while soy sauce is closing the gap fastest through premium positioning in fermentation-authenticated segments.
Form:
Physical state determines logistics economics and microbiological stability thresholds across supply chains.
- Liquid:Pumpable formulations with water activity controlled below 0.85 for ambient shelf stability. Food service portion control systems and retail squeeze bottles represent the primary demand concentration.
- Paste:Viscous suspensions with yield stress engineered for vertical surface adhesion. Industrial pizza manufacturing and sandwich assembly lines in Ho Chi Minh City and Bangkok procurement networks sustain volume.
- Powder:Spray-dried or agglomerated matrices with moisture content below 5%. Airline catering and military ration programs prioritize shipping weight reduction.
- Granular:Free-flowing crystals or flakes with instant reconstitution properties. Quick-service restaurant dry storage requirements and extended ambient stability are opening procurement channels.
Liquid formulations retain the largest volume position, though powder formats are expanding most quickly through industrial procurement shifts.
Flavor Profile:
Taste architecture maps directly to sodium reduction challenges and clean-label reformulation complexity.
- Spicy:Capsaicinoid activation thresholds calibrated through Scoville measurement. Latin American markets and Southeast Asian quick-service chains standardize procurement around defined heat unit specifications.
- Savory:Glutamate and nucleotide enhancement through fermentation or yeast extract addition. FDA sodium disclosure rules are forcing umami extract convergence for taste preservation at reduced salt levels.
- Sweet:Sucrose, high-fructose corn syrup, or alternative carbohydrate matrices. Ketchup formulations face particular pressure from front-of-pack sugar labeling schemes in German and French retail chains.
- Tangy:Organic acid profiles dominated by acetic, citric, or lactic acid. pH stability below 4.6 limits clean-label ingredient options while ensuring microbiological safety.
Savory profiles command the deepest formulation expertise, while spicy variants are gaining share fastest through Southeast Asian menu proliferation.
End User:
Customer type dictates packaging format, order frequency, and price sensitivity across entirely different procurement systems.
- Food Service:Institutional portion control with HACCP compliance requirements. Direct-to-restaurant subscription models in Austin, Copenhagen, and Melbourne are fragmenting traditional broadline distributor control.
- Household:Retail shelf presence with front-of-pack scoring compliance. EU Green Deal packaging directives are accelerating transitions toward recyclable formats in European supermarket channels.
- Industrial:Bulk ingredient supply for processed food manufacturing. Powder and granular forms reduce logistics costs through shipping weight advantages.
- Retail:Branded and private-label placement with barcode traceability. Clean-label reformulation mandates from FDA and EFSA are compressing supplier qualification timelines.
Food service channels absorb the highest volume throughput, while industrial procurement is climbing the fastest through powder format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for tomato paste and fermented soy substrates creates divergent trade positions across major consuming markets. Export-oriented processing clusters in Spain and California supply European and Asian manufacturers respectively. Currency volatility and shipping cost fluctuations are reshaping regional procurement strategies.
United States
Food service operators from Austin to Los Angeles drive demand for portion-control condiment formats. FDA sodium disclosure rules under updated Nutrition Facts labeling compress reformulation timelines for domestic manufacturers. California's Central Valley processing plants face drought-induced supply volatility that ripples through ketchup supply chains.
Germany
Retail chains in Berlin and Hamburg impose front-of-pack scoring requirements exceeding EU regulatory minimums. EFSA evaluations under the Food Improvement Agent regulation constrain novel preservative approvals. The Rhine-Ruhr industrial corridor hosts specialized logistics platforms supplying independent restaurant operators with small-batch fermented products.
China
Urban quick-service expansion in Shanghai and Shenzhen sustains industrial soy sauce demand. SAMR enforcement of GB standards for fermented products shapes manufacturing compliance costs. The Yangtze River Delta concentration of brewing facilities supplies both domestic retail and export markets across Southeast Asia.
Japan
Premium positioning for traditionally brewed varieties supports margin structures in Tokyo and Osaka retail channels. METI guidelines on fermentation process authentication influence export certification requirements. The Kanto region's century-old brewing expertise anchors capacity that competitors struggle to replicate at scale.
Vietnam
Street food vendor networks in Ho Chi Minh City and Hanoi create dispersed demand for standardized condiment portfolios. Rapid quick-service restaurant chain proliferation pulls investment into localized manufacturing capacity. The Mekong Delta's agricultural base supplies raw materials for regional sauce production.
Sauces and Condiments Market Vendor Landscape
On the supply side, the industry is consolidating around fermentation-authenticated premium positioning while fragmenting at the industrial private-label tier. Three strategic archetypes dominate: vertically integrated tomato processors, century-old brewing specialists, and asset-light co-manufacturing platforms. Competitive moves concentrate on backward integration into raw material control and geographic licensing arrangements that bypass capital-intensive facility construction.
Within the integrated processing tier, Kraft Heinz Company and Kikkoman Corporation exemplify divergent moat structures. Kraft Heinz anchors positioning through captive tomato and vinegar supply chains. Kikkoman occupies a position defined by non-replicable brewing expertise accumulated over generations. McCormick & Company sits within the flavor science specialization vector. These three represent the spectrum from agricultural control to biochemical differentiation that shapes competitive boundaries.
| Leading Market Players |
|---|
| Unilever PLC |
| PepsiCo Inc |
| Kraft Heinz Company |
| Hormel Foods Corporation |
| Nestle SA |
| Kikkoman Corporation |
| Conagra Brands Inc |
| Kewpie Corp |
| McCormick & Company Inc |
| Others |
Supply Flow & Price Mechanics
California Central Valley tomato paste processors and Spanish concentrated puree suppliers anchor margin capture upstream, while downstream pricing power fragments across food service distributors, retail chains, and direct-to-restaurant platforms. Kraft Heinz's captive tomato operations and Kikkoman's century-old brewing infrastructure insulate these players from feedstock volatility that compresses margins for asset-light competitors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across quick-service restaurant and airline catering procurement channels. Price differentiation separates fermentation-authenticated premium tiers from commodity private-label supply, with volume scale and geographic delivery cost as secondary drivers. Pricing pressure stems from California drought-induced tomato paste scarcity and petrochemical ethanol volatility for acetic acid feedstocks. Food service distributors exhibit highest price sensitivity due to consolidated procurement leverage, while diaspora retail channels in Melbourne and Los Angeles absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Tomato paste feedstock draws from California and Spain, while fermented soy substrates center on China's Yangtze River Delta and Japan's Kanto region. Acetic acid precursors, glass packaging, and mono-material films constitute critical component dependencies. Single-source vulnerability concentrates in California Central Valley drought exposure and Spanish processing consolidation. Distribution runs through broadline food service distributors, though direct-to-restaurant subscription platforms in Austin and Copenhagen are fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as direct-to-restaurant logistics infrastructure enables small-batch fermenters to bypass incumbent distributor hierarchies, creating interoperability between artisanal provenance and industrial procurement systems.
For Market Incumbents: Harden backward integration into tomato processing and vinegar fermentation capacity to defend against feedstock volatility and private-label erosion. Expand co-manufacturing licensing arrangements to capture revenue from emerging brands without capital deployment, while accelerating clean-label R&D to preempt FDA sodium disclosure compliance deadlines. For New Entrants and Emerging Players: Build out powder and granular format capabilities targeting airline catering and military ration procurement channels where shipping weight reduction commands premium positioning. Target Southeast Asian quick-service restaurant chains in Ho Chi Minh City and Bangkok with localized fermentation-authenticated soy sauce variants, leveraging direct-to-restaurant platforms for channel access. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-authenticated mid-cap specialists with captive brewing expertise and established diaspora retail presence in Los Angeles, Vancouver, and Melbourne. Long-term viability hinges on regulatory pre-positioning for front-of-pack labeling schemes and carbon accounting requirements. Watch for SAMR enforcement patterns in China and EU Green Deal packaging directive implementation timelines as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tomato Processing | Kraft Heinz's captive California operations insulate margins from Central Valley drought cycles. |
| Clean-Label Reformulation Investment | Pre-positions brands for FDA sodium disclosure rules and EFSA additive scrutiny. |
| Direct-to-Restaurant Platform Partnership | Melbourne and Copenhagen logistics networks bypass broadline distributor control. |
| Industrial Powder Format Scale-Up | Airline catering procurement in Southeast Asia prioritizes shipping weight reduction. |
| Fermentation Biotechnology Licensing | Kikkoman's century-old Kanto brewing expertise creates non-replicable capacity moats. |
Methodological Framework
The analysis maps ketchup, soy sauce, mustard, and hot sauce sub-sectors, each validated through fermentation scientists, food service procurement directors, and retail category buyers. Primary interviews with flavor chemists, co-manufacturing platform operators, and regulatory affairs specialists combined with secondary validation from FDA guidance documents, EFSA Food Improvement Agent evaluations, EU Green Deal packaging directives, and customs trade data. Bottom-up volume triangulation across product type, form, and end-user segments converged with top-down macroeconomic anchoring.
Assumptions held fixed include regulatory enforcement timelines for sodium reduction guidance and REACH compliance for packaging migrants, while variables included drought-induced tomato paste supply shocks and petrochemical ethanol price volatility. Segmentation dimensions modeled span product type, physical form, flavor profile, and end-user channel across the analysis window. CAGRs derived from historical volume trajectories, elasticity-adjusted price assumptions, and penetration modeling for powder format adoption in industrial procurement.
Sensitivities concentrate around California drought recurrence, EU packaging waste directive acceleration, and SAMR enforcement intensity in China. Cross-checking against Nielsen retail audit data and food service distributor procurement surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market