
 Spice Oils and Oleoresins Market | 2026-2036
Spice Oils and Oleoresins Market Size, Share, and Industry Trends Forecast 2026-2036
Spice Oils and Oleoresins Market Analytics
Skilled distillation and extraction technician availability is collapsing across traditional spice-processing clusters, constraining batch consistency and throughput expansion. Synthite Industries Ltd leverages backward integration into Kerala-based black pepper and cardamom estates to secure raw material pipelines. Givaudan AG sustains competitive positioning through dedicated biotechnology centers that optimize solvent recovery yields. McCormick & Company anchors North American supply security via long-term contract farming arrangements in Karnataka and Tamil Nadu.
Spice oils and oleoresins comprise concentrated aromatic and pungent principles recovered from botanical spices through steam distillation, solvent extraction, or supercritical CO2 processing, yielding standardized flavor and color potencies measured in Scoville Heat Units or percentage volatile oil content. These extracts serve primarily as precision flavoring, coloring, and preservative agents across formulated food systems and therapeutic preparations. Oleoresins command the dominant value share within the product type dimension due to their complete flavor profile retention and extended shelf stability in industrial applications. The food and beverage application segment absorbs the majority of volume flows, though pharmaceuticals and natural remedies are accelerating fastest as functional ingredient formulators seek standardized phytochemical actives.
FDA GRAS self-affirmation pathways and EPA solvent residue limits govern US market access for imported oleoresin shipments, while REACH registration requirements and EFSA purity specifications constrain European supply eligibility. India's BIS certification mandates and FSSAI contaminant thresholds shape domestic quality benchmarks that ripple through export channels. Stakeholders must monitor evolving solvent restriction lists and carbon accounting disclosures that will redefine supplier qualification criteria.
Market Dynamics
Extraction capacity concentration in India's Kerala and Karnataka spice belts is creating supply bottlenecks as skilled technician pipelines collapse, forcing processors to automate or face batch inconsistency penalties from multinational food manufacturers.
Growth Catalysts
- EU Green Deal compliance mandates:REACH registration requirements and carbon accounting disclosures are accelerating clean-label procurement from European food and beverage formulators seeking residue-free natural colorants.
- Supercritical CO2 processing adoption:Solvent-free extraction technology is expanding across pharmaceutical applications requiring GRAS-certified phytochemical actives for therapeutic formulations.
- Karnataka contract farming density:Long-term raw material agreements with estate-holders are securing black pepper and cardamom pipelines for industrial-scale oleoresin production.
Market Restraints
- Vanilla and capsicum input cost volatility:Weather-induced crop failures in Madagascar and India are destabilizing feedstock pricing for high-value oleoresin categories.
- Single-origin supply concentration:Kerala's dominance in black pepper processing creates geographic vulnerability to monsoon disruption and labor migration.
- EPA solvent residue thresholds:FDA import screening for dichloromethane and hexane traces is blocking non-compliant shipments at US ports.
Strategic Opportunities
- Pharmaceutical phytochemical standardization:CDSCO and USP monograph alignment is opening therapeutic-grade oleoresin channels for Ayurvedic extract exporters.
- Direct-to-manufacturer e-procurement platforms:Digital marketplaces are disintermediating traditional spice broker networks for mid-sized food processors.
- Biotechnology-enabled solvent recovery:Fermentation-derived enzyme assistance is converging with closed-loop extraction systems to yield carbon-negative processing certifications.
Industry Challenges
- Distillation technician skill attrition:Traditional apprenticeship pipelines in Kerala's spice-processing clusters are failing to replace retiring batch operators.
- FSSAI-BIS dual certification timelines:Parallel domestic and export quality mark approvals are extending product launch cycles by 8-14 months.
- Legacy steam distillation retrofit costs:Small-scale processors face capital barriers to supercritical CO2 equipment upgrades required by multinational audit standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spice Oils and Oleoresins Market |
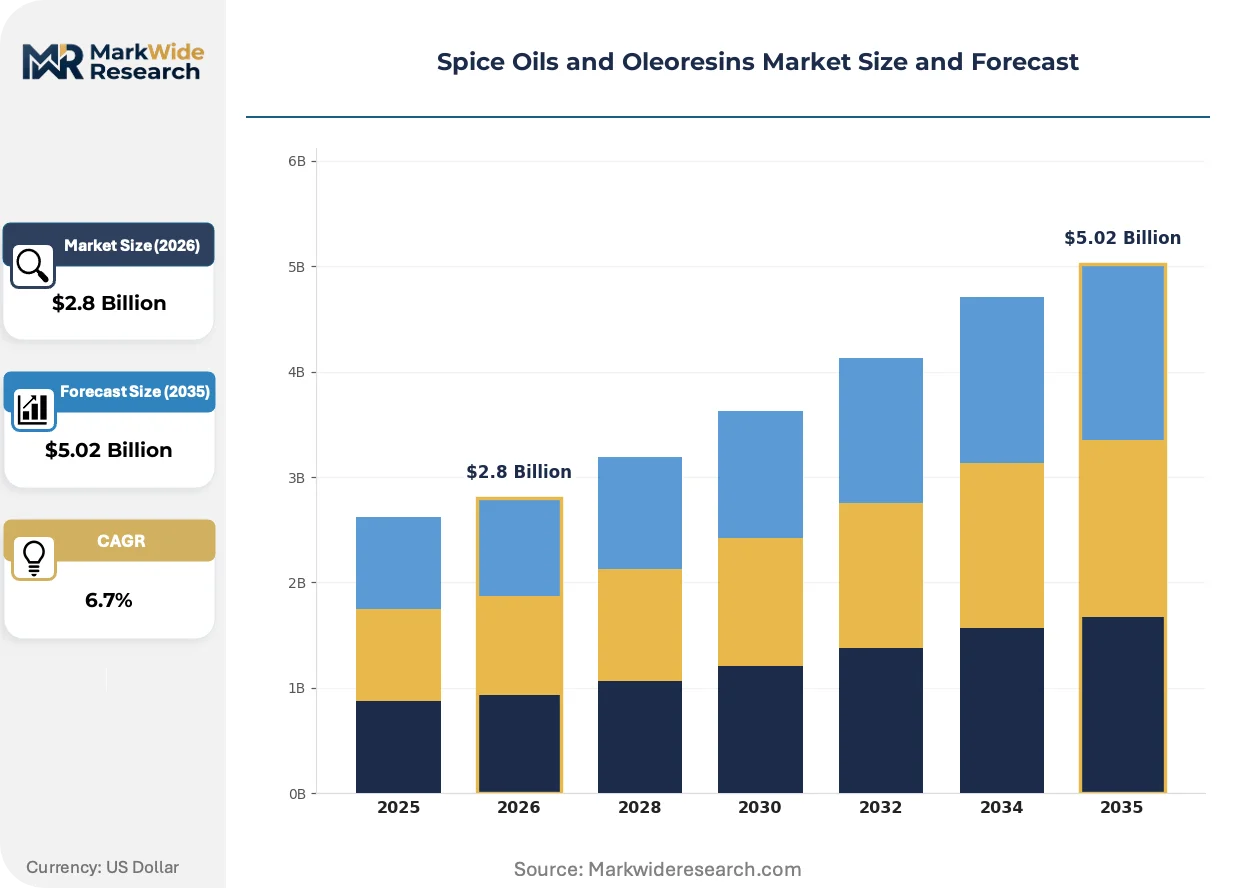
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Extracts, Oleoresins, Distillates Application: Food & Beverage, Pharmaceuticals, Cosmetics, Natural Remedies Form: Liquid, Powder, Gel, Granular Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Synthite Industries Ltd, Symrise AG, Givaudan AG, McCormick & Company, Kalsec Inc, Universal Oleoresins Pvt Ltd, Plant Lipids Private Limited, Olam International, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spice Oils and Oleoresins Market Evolving Landscape
Biotechnology-assisted extraction and regulatory-driven carbon accounting are actively reshaping competitive capabilities across the spice oils and oleoresins value chain. Processors must now demonstrate solvent recovery efficiency alongside traditional purity metrics.
Supercritical CO2 extraction systems are decomposing the traditional solvent-based processing hierarchy by eliminating hexane residue risks entirely. Pharmaceutical formulators in North America and Europe are adopting these systems fastest, compressing the addressable market for conventional extraction equipment and forcing incumbent processors to retrofit or exit premium therapeutic-grade segments.
REACH registration expansion under the EU Green Deal is tightening residue documentation requirements for all imported oleoresin categories. European food manufacturers are now rejecting shipments lacking carbon footprint disclosures, with EFSA purity specifications extending to solvent recovery rates and energy sourcing transparency.
Buyer concentration among multinational food manufacturers is compressing supplier qualification cycles and unbundling after-sales technical service from commodity pricing. Mid-sized Indian processors report that Nestlé and Unilever procurement teams now mandate real-time batch tracking portals, with compliance costs most visible in Karnataka and Tamil Nadu supply bases.
Spice Oils and Oleoresins Market Segmentation
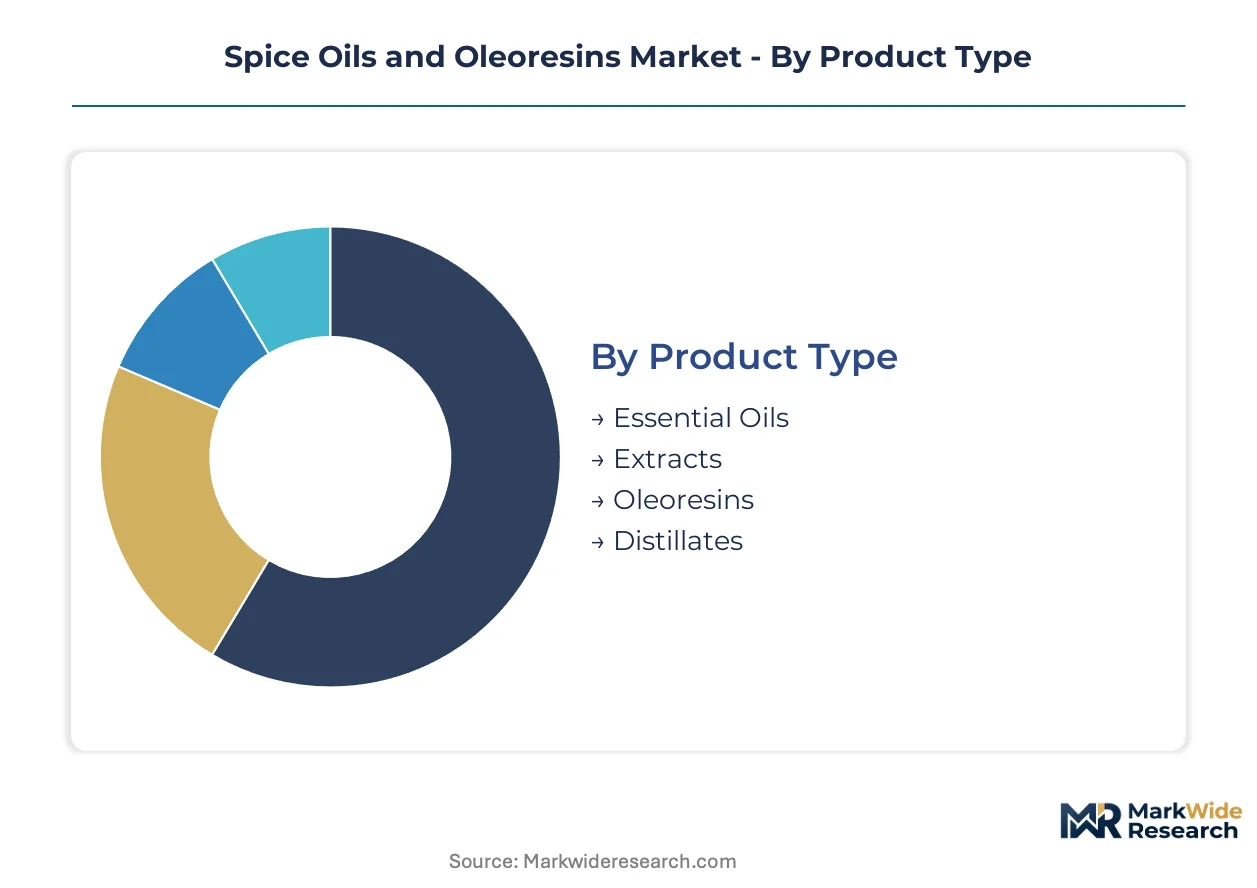
Segmentation in spice oils and oleoresins determines procurement pathways, regulatory scrutiny intensity, and formulation compatibility across end-use industries. Channel-mix patterns vary sharply between commodity-grade food applications and precision pharmaceutical specifications.
Product Type:
Channel-mix divergence separates commodity spice oils moving through wholesale broker networks from pharmaceutical-grade oleoresins flowing via direct manufacturer contracts with full batch traceability.
- Oleoresins:Complete flavor profile matrices retaining both volatile oils and non-volatile resins in standardized concentrations. Food manufacturers in India and Europe absorb the majority of industrial volumes, though EPA solvent residue screening at US ports blocks non-compliant shipments and compresses supplier eligibility.
- Essential Oils:Steam-distilled volatile fractions capturing aromatic principles for flavoring and fragrance applications. Karnataka and Kerala extraction clusters supply these through wholesale channels to North American and European flavor houses, with batch inconsistency penalties rising as skilled technician availability collapses.
- Extracts:Solvent-derived concentrates standardized for specific active markers.
- Distillates:Refined volatile fractions produced via fractional distillation for high-purity applications.
By volume, oleoresins leads. By growth pace, essential oils is ahead.
Application:
Cost-tier stratification separates mass-market food additives from premium therapeutic grades commanding 3-4x unit economics and dedicated regulatory documentation.
- Food & Beverage:Precision flavoring, coloring, and preservative deployment across formulated sauces, seasonings, and beverage systems. Clean-label procurement from European formulators accelerates under EU Green Deal carbon accounting mandates, with Nestlé and Unilever procurement teams now requiring real-time batch tracking portals.
- Pharmaceuticals:Standardized phytochemical actives for therapeutic formulations requiring CDSCO-USP monograph alignment. Supercritical CO2 extraction adoption expands fastest here as GRAS certification becomes mandatory for Ayurvedic extract exports to North America.
- Cosmetics:Fragrance and active ingredient incorporation into personal care formulations.
- Natural Remedies:Traditional medicine system applications with rising documentation requirements.
Food & Beverage captures the largest volume flows. Pharmaceuticals demonstrates the steepest expansion trajectory as functional ingredient standardization intensifies.
Form:
Supply concentration in liquid processing infrastructure creates margin pressure on powder and gel conversion capabilities requiring additional capital equipment.
- Liquid:Standard delivery format for industrial-scale dosing and homogeneous dispersion. Kerala and Karnataka processors dominate liquid oleoresin output, with supercritical CO2 systems yielding solvent-free grades for pharmaceutical channels.
- Powder:Encapsulated or spray-dried formats enabling dry-blend compatibility. Powder demand concentrates in convenience food manufacturing clusters seeking extended shelf stability without refrigeration dependency.
- Gel:Thickened matrices for controlled-release topical applications.
- Granular:Free-flowing particulates for seasoning and rub formulations.
Liquid maintains volume leadership. Powder is climbing the fastest as dry-blend food systems expand.
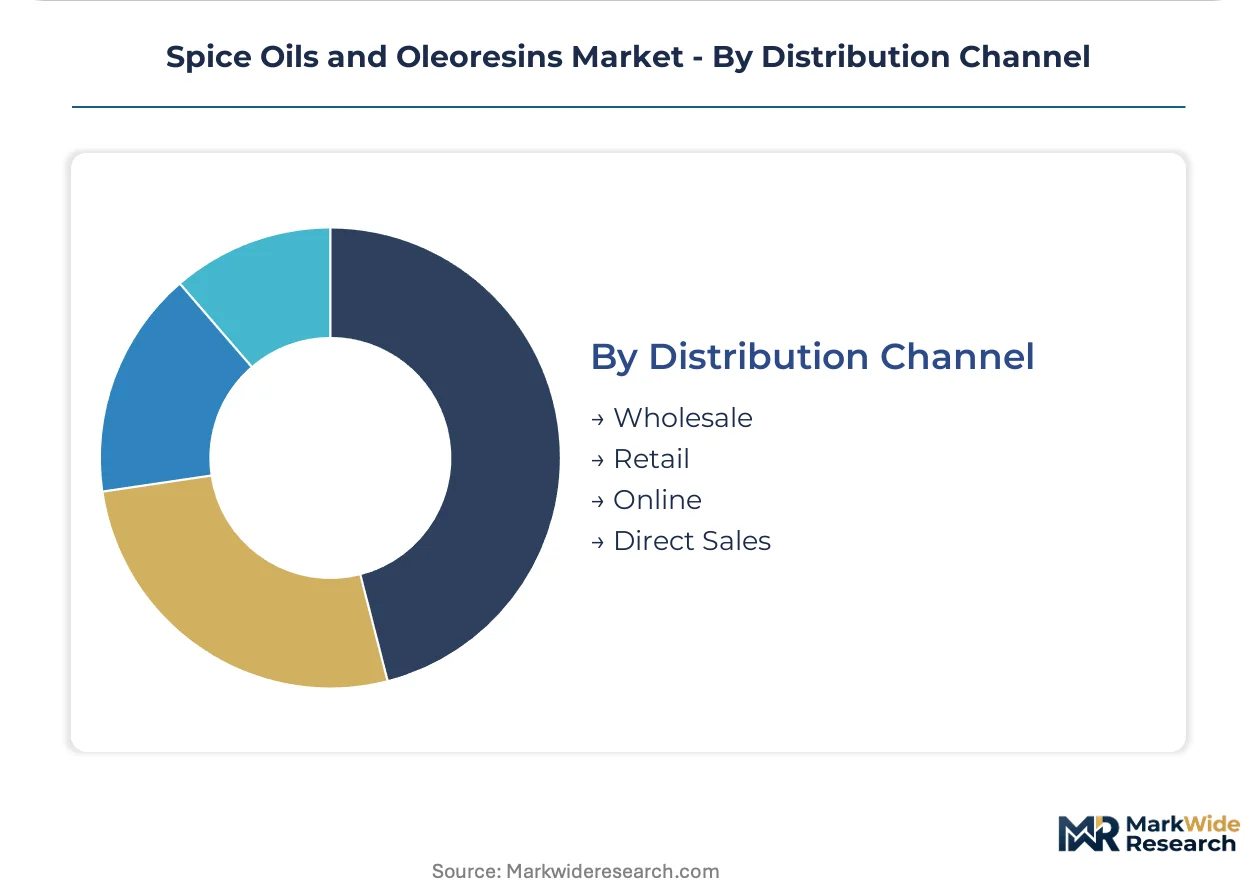
Distribution Channel:
Customer-type bifurcation separates multinational manufacturers demanding direct technical partnerships from mid-sized processors relying on wholesale liquidity.
- Direct Sales:Long-term contract farming arrangements and dedicated technical service relationships. McCormick anchors North American supply security through Karnataka and Tamil Nadu estate agreements, while Givaudan biotechnology centers optimize solvent recovery yields for pharmaceutical-grade shipments.
- Wholesale:Broker-mediated spot market liquidity for commodity-grade materials. Wholesale channels absorb vanilla and capsicum oleoresins subject to weather-induced price volatility from Madagascar and Indian crop zones.
- Online:Digital marketplaces disintermediating traditional spice broker networks.
- Retail:Packaged consumer formats for culinary and wellness applications.
Direct Sales leads by value contribution. Online is gaining share fastest as e-procurement platforms compress transaction friction for mid-sized food processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI certification mandates and BIS quality benchmarks in India anchor the dominant geography, with Kerala and Karnataka spice belts concentrating extraction capacity. REACH compliance requirements and EU Green Deal carbon accounting disclosures in Europe are tightening procurement standards for imported oleoresins. FDA GRAS pathways and EPA solvent residue limits govern US market access.
India
Kerala's black pepper estates and Karnataka's cardamom contract farming arrangements feed industrial-scale oleoresin production. FSSAI contaminant thresholds and BIS certification mandates shape domestic quality benchmarks that ripple through export channels. Cochin and Bangalore extraction clusters face skilled technician attrition that constrains batch consistency for multinational food manufacturers.
United States
GRAS self-affirmation pathways accelerate clean-label procurement from food and beverage formulators seeking residue-free natural colorants. EPA import screening for dichloromethane and hexane traces blocks non-compliant oleoresin shipments at ports. McCormick anchors North American supply security through long-term contract farming arrangements in Karnataka and Tamil Nadu.
Germany
REACH registration requirements and EFSA purity specifications constrain European supply eligibility for therapeutic-grade phytochemical actives. Carbon footprint disclosure mandates under the EU Green Deal are rejecting shipments lacking energy sourcing transparency. Hamburg and Frankfurt distribution hubs filter imports for pharmaceutical formulators demanding solvent recovery documentation.
Switzerland
Swissmedic therapeutic-grade standards and precision flavor house procurement compress supplier qualification cycles for Ayurvedic extract exporters. Givaudan biotechnology centers optimize solvent recovery yields for pharmaceutical-grade shipments. Basel and Geneva anchor flavor science R&D that sets specifications cascading through European formulator networks.
China
GB standards for food additive purity and NMPA pharmaceutical ingredient registration create dual compliance pathways for oleoresin imports. Supercritical CO2 equipment manufacturers in Shanghai and Guangzhou supply solvent-free extraction systems displacing conventional hexane-based processing. Yangtze River Delta chemical parks host fermentation-derived enzyme assistance converging with closed-loop extraction certifications.
Spice Oils and Oleoresins Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with biotechnology-enabled processors commanding premium positioning while estate-integrated operators capture feedstock economics. The market structures around three tiers: multinational flavor houses with dedicated extraction R&D, Indian estate-holders with backward integration into Kerala and Karnataka spice belts, and mid-sized processors facing capital barriers to supercritical CO2 retrofit. Dominant competitive moves include long-term contract farming arrangements securing raw material pipelines and biotechnology center investments optimizing solvent recovery yields.
Within the estate-integrated tier, Synthite Industries Ltd exemplifies backward integration into Kerala-based black pepper and cardamom holdings. Among Swiss-based flavor science specialists, Givaudan AG occupies a position representing biotechnology-enabled solvent recovery optimization. At the North American procurement end, McCormick & Company anchors supply security archetypes through Karnataka and Tamil Nadu contract farming density.
| Leading Market Players |
|---|
| Synthite Industries Ltd |
| Symrise AG |
| Givaudan AG |
| McCormick & Company |
| Kalsec Inc |
| Universal Oleoresins Pvt Ltd |
| Plant Lipids Private Limited |
| Olam International |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Kerala extraction clusters compress margin buffers for processors facing volatile black pepper and cardamom feedstock costs. This lead-time exposure concentrates pricing power with estate-integrated operators who control upstream material flows, while spot-market dependent competitors absorb cost volatility without corresponding pricing leverage.
Pricing Analysis
Cochin-to-Hamburg price spreads widen during monsoon disruptions when Kerala processing capacity contracts. Three-tier pricing structure across pharmaceutical-grade, food-grade, and commodity-grade levels separates buyers by certification intensity and batch documentation depth. Pricing pressure stems from EPA solvent residue screening blocking non-compliant shipments at US ports. Mid-sized food processors exhibit highest price sensitivity, while pharmaceutical formulators accept premiums for GRAS-certified supercritical CO2 grades.
Supply Chain Analysis
Container availability constraints on India-Europe trade lanes elevate inbound logistics costs for oleoresin exporters during peak harvest windows. Geographic concentration in India, Madagascar, and Indonesia creates feedstock dependencies for vanilla and capsicum categories. Raw material pipelines draw from Kerala black pepper estates, Karnataka cardamom contract farms, and Madagascar vanilla cultivation zones. Single-origin vulnerability to monsoon disruption represents the dominant structural risk. Distribution runs through direct manufacturer contracts for pharmaceutical grades and wholesale broker networks for commodity food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as supercritical CO2 processing adoption accelerates across therapeutic-grade segments. Clean-label procurement mandates from European food manufacturers under EU Green Deal compliance create sustained demand tailwinds for residue-free extraction technologies.
For Market Incumbents: Shield market position by securing long-term contract farming arrangements in Karnataka and Tamil Nadu before feedstock competition intensifies. Invest in biotechnology-enabled solvent recovery systems to meet EFSA purity specifications and carbon accounting disclosures that European buyers now mandate. Prioritize automation retrofits to offset skilled distillation technician attrition threatening batch consistency penalties.
For New Entrants and Emerging Players: CDSCO-USP monograph alignment fast-tracks entry into pharmaceutical phytochemical channels where standardization requirements have thinned supplier ranks. Target Ayurvedic extract exports to North America as the most penetrable white-space segment. Deploy direct-to-manufacturer e-procurement platforms to disintermediate traditional spice broker networks and capture mid-sized food processor accounts.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational flavor houses divesting non-core extraction assets. Five-to-ten year viability hinges on backward integration depth and carbon-negative processing certification potential. Acquisition archetypes include Kerala-based estate-holders with captive black pepper supply and supercritical CO2 equipment operators. Watch for FSSAI-BIS dual certification timeline compression as an inflection signal indicating regulatory streamlining.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spice Estates | Synthite Industries Ltd secures Kerala black pepper pipelines against feedstock competition. |
| Biotechnology Center Investment | Givaudan AG optimizes solvent recovery yields for REACH-compliant pharmaceutical shipments. |
| Supercritical CO2 Equipment Retrofit | Processors eliminate hexane residue risks to access GRAS-certified therapeutic channels. |
| Long-term Contract Farming Arrangement | McCormick anchors North American supply security through Karnataka estate agreements. |
| Direct E-procurement Platform Launch | Digital marketplaces compress transaction friction for mid-sized European food manufacturers. |
Research Methodology
Cross-validation between primary interviews with extraction plant managers, procurement leads at multinational flavor houses, FSSAI regulatory officers, and Kerala estate operators anchors the qualitative findings. Secondary validation draws from customs and trade data, BIS certification registries, SEC filings of listed flavor houses, and EFSA scientific opinions. Bottom-up volume estimates from individual processor capacities triangulate against top-down demand projections from end-use industry consumption patterns.
Sensitivity analysis around vanilla and capsicum input cost volatility shapes the forecast confidence intervals across the projection horizon. Segmentation dimensions modeled include product type, application, form, and distribution channel alongside extraction technology tier. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific inputs incorporate monsoon failure frequency patterns and REACH registration expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable India-Europe trade lane capacity; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around skilled technician pipeline recovery and supercritical CO2 equipment cost curves. Weather-induced crop failures in Madagascar or labor migration from Kerala spice belts represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Ghost Pepper Salt Market