
 GMO Labeled Food Market | 2026-2036
GMO Labeled Food Market Size, Share, and Industry Trends Forecast 2026-2036
GMO Labeled Food Market Foresight
Market Context
North American grain processors and seed suppliers is shifting toward segregated handling infrastructure to preserve identity-preserved supply chains for labeled output. Cargill leverages its elevator network to maintain chain-of-custody documentation from farm to processor. Nestle sustains consumer trust through third-party verification partnerships across its packaged food portfolio. Unilever competes on reformulation speed, converting conventional product lines to labeled alternatives in European markets.
Technical Definition and Segments
GMO labeled food comprises agricultural products and processed goods derived from organisms whose genetic material has been altered through recombinant DNA or gene-editing techniques, with labeling mandated when detectable modified DNA exceeds threshold concentrations, typically 0.9% in the European Union and 5% in the United States for unintended presence. The primary commercial purpose is to provide consumers with transparent choice while enabling regulatory compliance across divergent national frameworks. Grains occupy the largest volume share due to widespread corn and soybean cultivation, though oils are capturing margin expansion as high-oleic and omega-3 enhanced variants command premium positioning. Online retail represents the fastest-growing distribution channel, driven by direct-to-consumer subscription models and blockchain-enabled provenance verification that supermarkets have been slower to implement.
Regulatory Framework
The USDA enforces the National Bioengineered Food Disclosure Standard through its Agricultural Marketing Service, requiring mechanical or digital labeling for bioengineered ingredients above specified thresholds. The EU Green Deal and REACH-adjacent traceability protocols, administered by EFSA and national competent authorities, impose stricter detection limits and mandatory origin documentation. The FDA maintains voluntary consultation procedures for genetically engineered foods while coordinating with EPA on plant-incorporated protectant residues. Stakeholders must monitor divergence between U.S. threshold-based disclosure and EU process-based labeling, as this regulatory fragmentation determines which supply chains qualify for premium market access.
Market Dynamics
Divergent regulatory thresholds between major economies are forcing supply chain bifurcation, as processors must maintain parallel handling systems to serve both 0.9% EU and 5% US disclosure limits without cross-contamination.
Growth Catalysts
- EU Green Deal traceability mandates:Stricter origin documentation requirements are pulling investment into segregated elevator infrastructure across member states.
- Blockchain verification protocols:Distributed ledger systems are enabling real-time chain-of-custody tracking that satisfies both consumer transparency demands and regulatory audit trails.
- German retail concentration:Discounter chains in this market are expanding labeled SKU counts faster than conventional alternatives, creating volume pull-through for upstream suppliers.
Market Restraints
- Segregated handling infrastructure:Dedicated storage and transport systems for identity-preserved grains impose capital costs that smaller elevators cannot absorb.
- Input cost volatility:Non-GMO seed premiums fluctuate with patent licensing fees and trait availability, compressing processor margins during contract negotiation windows.
- Regulatory friction from threshold divergence:The gap between EU process-based and US threshold-based labeling forces dual compliance architectures that increase administrative overhead.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail bypasses supermarket slotting fees while capturing higher margins through blockchain-enabled provenance storytelling.
- French organic-conventional hybrid positioning:Retailers in this market are creating intermediate shelf tiers that blend non-GMO verification with other sustainability credentials.
- Gene-editing regulatory clarity:Pending determinations on whether CRISPR-derived products trigger disclosure requirements will open formulation possibilities for oilseed developers.
Industry Challenges
- Chain-of-custody documentation talent:Food safety auditors with expertise in both molecular detection protocols and distributed ledger systems remain scarce across the grain belt.
- Legacy ERP integration:Mid-size processors struggle to retrofit inventory management systems for lot-level traceability without disrupting existing customer fulfillment workflows.
Report Scope
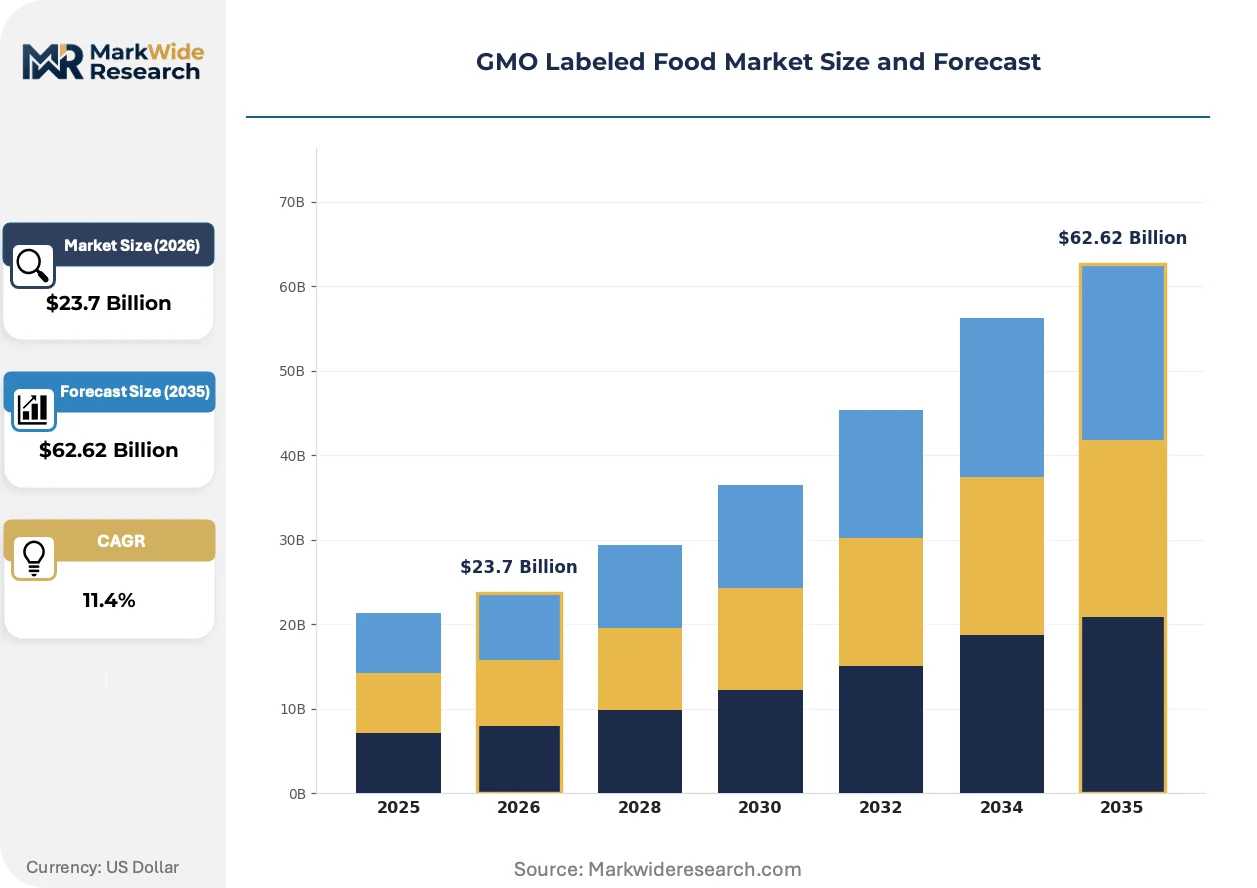
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMO Labeled Food Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Oils Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Consumers, Restaurants, Food Manufacturers, Distributors Certification Type: USDA Organic, Non-GMO Project Verified, EU Organic, Others |
| Companies Covered | Syngenta, Danone, Unilever, Cargill, Nestle, Bayer, Corteva Agriscience, General Mills, Campbell Soup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMO Labeled Food Market Shifts & Advancements
Detection sensitivity improvements and consumer-facing verification interfaces are compressing the gap between laboratory certification and point-of-sale transparency, reshaping how trust is manufactured and communicated.
Quantitative PCR and digital droplet technologies are integrating into elevator receiving protocols, enabling real-time GMO content screening at intake rather than post-aggregation testing. Large cooperatives in Iowa and Illinois are deploying these systems to sort incoming loads into segregated channels before commingling occurs. This capability is integrating identity preservation directly into the first handling node, reducing downstream rejection risk and contract penalty exposure.
REACH-adjacent traceability protocols administered by EFSA are tightening documentary requirements for imported oilseeds and processed ingredients entering EU customs territories. Food manufacturers must now maintain batch-level origin records spanning multiple upstream handlers, with audit trails extending to farm gate. Packaged goods producers reformulating for European markets are responding by contracting dedicated crusher capacity and rejecting spot market purchases that lack complete pedigree documentation.
Subscription-based pantry services are displacing conventional retail discovery for labeled specialty oils and snack products, particularly among urban households in Germany and metropolitan France. These platforms bundle verification storytelling with convenience, capturing price premiums that supermarkets struggle to replicate. Direct channels now account for the fastest-growing volume segment as established brands build captive digital relationships to defend margin structure against private label encroachment.
GMO Labeled Food Market Segmentation
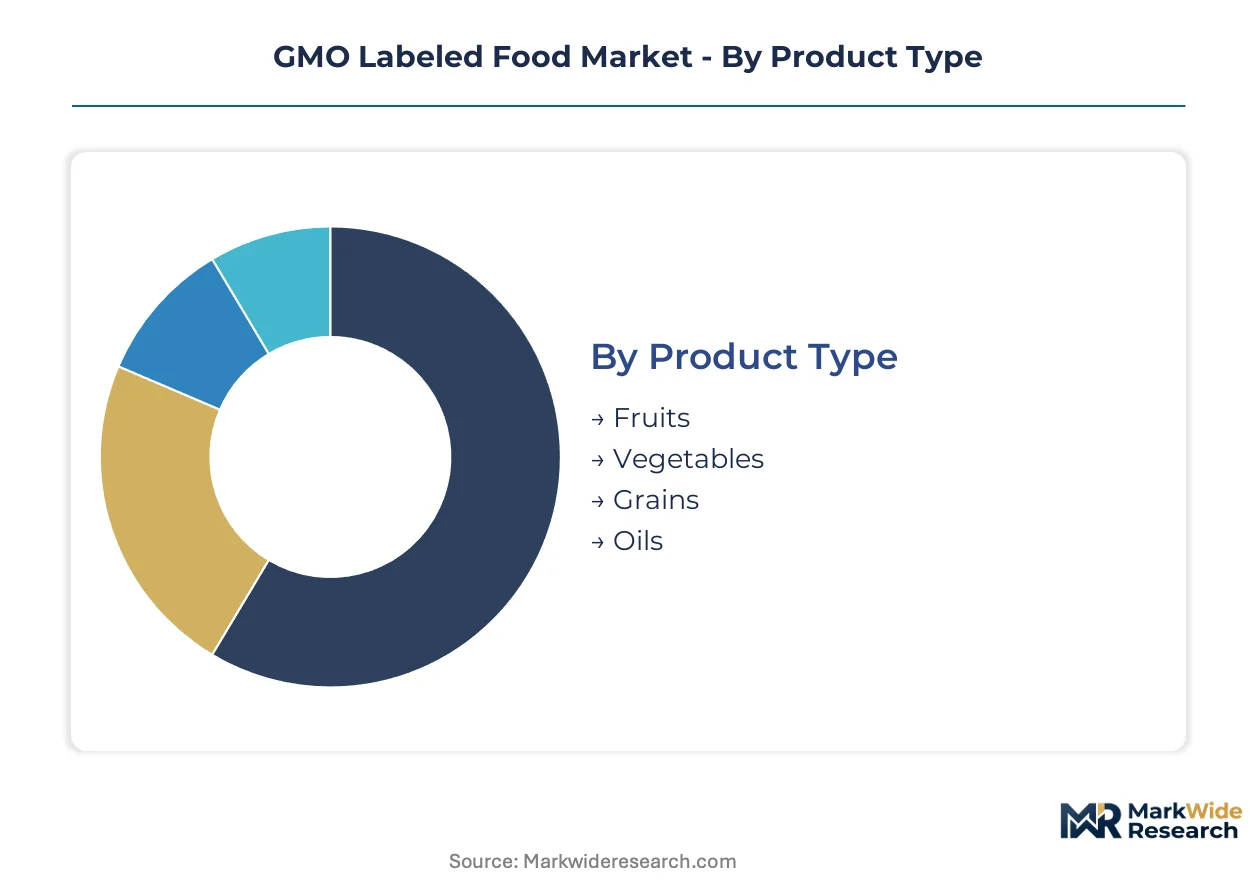
Segmentation in the GMO labeled food market determines compliance pathway selection and margin capture. Buyers prioritize certification credibility, distribution accessibility, and supply chain transparency when allocating procurement budgets across product categories.
Product Type:
Ingredient functionality and processing complexity drive buyer prioritization, with volume buyers favoring commodities that integrate into multiple downstream applications.
- Grains:Corn and soybeans dominate bulk procurement contracts due to their role as feedstock for processed ingredients. Demand concentrates in North American elevator networks serving Cargill and Bunge, where segregated handling infrastructure preserves identity-preserved status through multiple transfer points. The 0.9% EU threshold versus 5% US disclosure limit forces dual-channel sorting at intake.
- Oils:High-oleic and omega-3 enhanced variants command premium positioning in European retail. German and French buyers show willingness to pay for verified non-GMO sunflower and rapeseed oils, particularly when bundled with organic credentials in hybrid shelf tiers.
- Fruits:Papaya and squash varieties with virus-resistance traits trigger disclosure requirements under USDA standards. Fresh produce distributors in California and Florida maintain separate receiving protocols to avoid commingling with conventional loads.
- Vegetables:Sweet corn and potato varieties with modified traits require labeling when detectable DNA exceeds thresholds. Food service distributors specify non-GMO verified alternatives for contract catering accounts in metropolitan France.
Volume sits with grains; growth tilts toward oils.
Distribution Channel:
Channel selection reflects trade-offs between margin retention and customer acquisition efficiency, with digital platforms capturing higher per-unit economics at lower absolute volume.
- Online Retail:Subscription-based pantry services bypass supermarket slotting fees while enabling blockchain-enabled provenance storytelling. Direct-to-consumer models in Germany and France capture urban households seeking convenience bundled with verification transparency.
- Supermarkets:Discounter chains in Germany expand labeled SKU counts faster than conventional alternatives, creating volume pull-through for upstream suppliers. Retail grocery chains across North America and Europe are expanding shelf space for labeled products.
- Health Food Stores:Smaller format retailers emphasize third-party verification partnerships and staff education to justify price premiums over conventional alternatives.
- Specialty Stores:Boutique oil and grain merchants serve artisan food manufacturers requiring lot-level traceability documentation for European export compliance.
Supermarkets move the most units; online retail climbs the fastest.
End User:
User type determines specification stringency, with commercial buyers enforcing stricter documentation requirements than individual consumers.
- Food Manufacturers:Packaged goods producers reformulating for European markets contract dedicated crusher capacity and reject spot market purchases lacking complete pedigree documentation. Nestle and Unilever sustain consumer trust through third-party verification partnerships and reformulation speed.
- Restaurants:Contract catering accounts and quick-service chains specify non-GMO verified oils and grains to meet corporate sustainability commitments, particularly in French and German food service markets.
- Consumers:Individual purchasers respond to shelf-level labeling and digital verification interfaces, with German households showing highest willingness to pay for certified alternatives.
- Distributors:Mid-size processors struggle to retrofit inventory management systems for lot-level traceability without disrupting existing customer fulfillment workflows.
Food manufacturers absorb the most volume; restaurants are expanding specifications fastest.
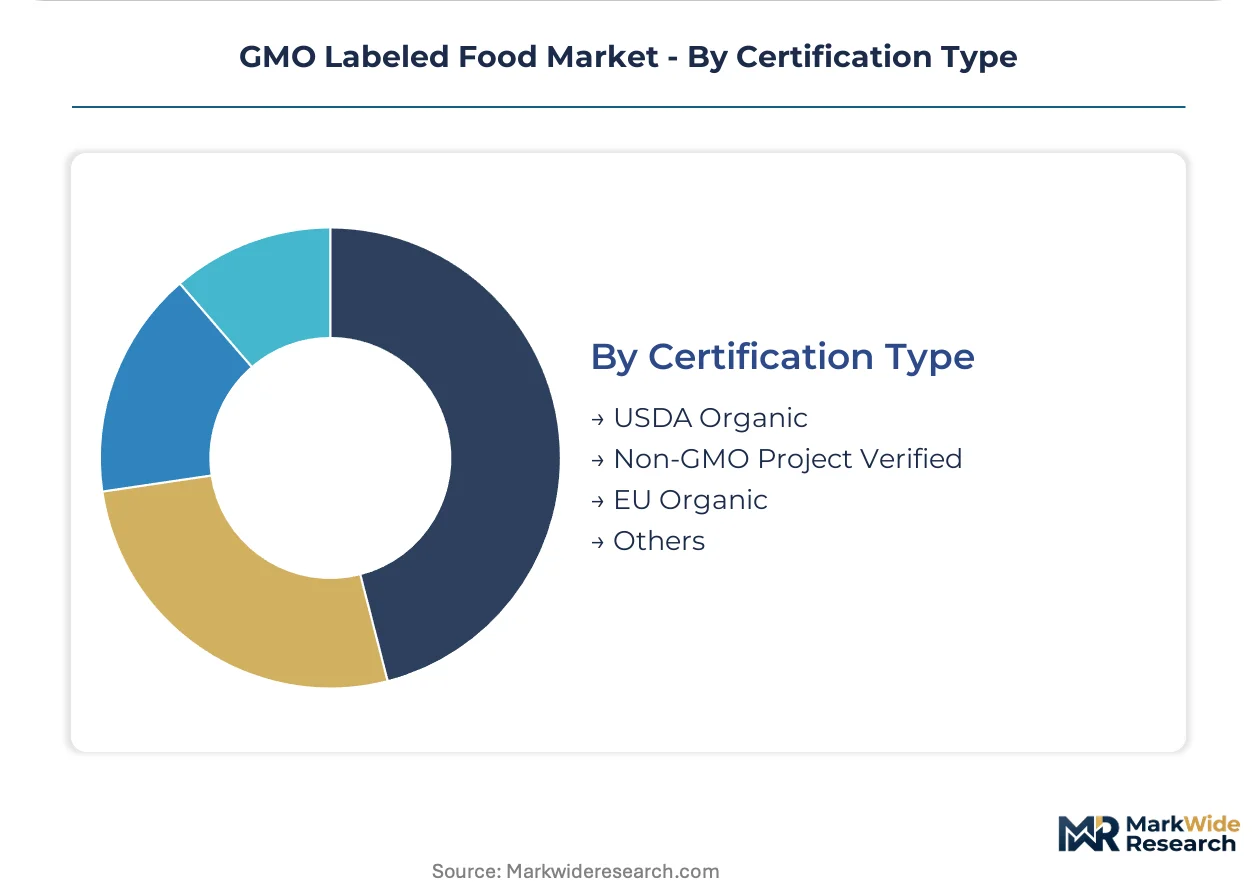
Certification Type:
Certification selection determines market access eligibility, with European process-based requirements creating stricter barriers than US threshold-based alternatives.
- Non-GMO Project Verified:The dominant North American third-party standard requires ongoing testing and supply chain audits. Cargill leverages its elevator network to maintain chain-of-custody documentation meeting these protocols from farm to processor.
- EU Organic:Combines non-GMO verification with additional sustainability credentials, enabling premium positioning in French retail hybrid shelf tiers. REACH-adjacent traceability protocols administered by EFSA impose stricter documentary requirements than US equivalents.
- USDA Organic:Federal standard that prohibits GMO ingredients while mandating additional production practice requirements, creating overlap with but distinction from pure non-GMO claims.
- Others:National standards including French AB and German Bio-Siegel provide regional credibility for domestic market penetration.
Non-GMO Project Verified holds the installed base; EU Organic shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn and soybean belt concentration in the United States Midwest anchors raw material flows for labeled grain supply chains, while European oilseed crushing clusters in northern France and western Germany process identity-preserved rapeseed and sunflower for premium retail positioning.
United States
USDA's National Bioengineered Food Disclosure Standard mandates digital or text labeling for detectable modified DNA above 5% thresholds, driving elevator network investment across Iowa and Illinois. The Agricultural Marketing Service enforces compliance through supply chain audits. Large cooperatives in the Corn Belt deploy real-time PCR screening at intake to sort loads into segregated channels before commingling.
Germany
Discounter chains expand labeled SKU counts faster than conventional alternatives, creating volume pull-through for upstream oilseed suppliers. EU Green Deal traceability mandates administered by EFSA impose stricter documentary requirements than US equivalents. Crushing facilities in Hamburg and the Lower Saxony grain belt maintain dedicated handling lines for identity-preserved rapeseed destined for retail hybrid tiers.
France
Retailers create intermediate shelf positions blending non-GMO verification with organic and other sustainability credentials, commanding premium pricing in Île-de-France and metropolitan Lyon. REACH-adjacent protocols require batch-level origin records extending to farm gate. Oilseed processors in the Paris Basin contract dedicated crusher capacity to satisfy documentation requirements for export-compliant packaged goods.
Canada
Health Canada and the Canadian Food Inspection Agency coordinate on novel food assessments for genetically engineered crops, with voluntary labeling guidance encouraging transparency. Prairie province elevator networks in Saskatchewan and Alberta preserve identity-preserved canola and wheat through segregated storage. Vancouver and Montreal serve as export consolidation points for Asian-bound labeled grain shipments.
Brazil
ANVISA maintains consultation procedures for genetically modified organisms while national grain handlers develop segregated infrastructure to access EU-compliant export markets. Soybean production concentration in Mato Grosso and Paraná drives investment in parallel handling systems. Port terminals in Santos and Paranaguá sort export cargoes by certification status to satisfy divergent regulatory thresholds.
GMO Labeled Food Market Competitive Landscape
Global majors compete with regional champions across certification credibility and supply chain transparency, with market structure consolidating around integrated agribusiness conglomerates and diversified packaged food corporations. Tiered competitive dynamics separate seed-to-shelf integrators from reformulation-focused consumer brands. Three archetypes dominate: elevator-network operators preserving chain-of-custody documentation, packaged food manufacturers leveraging third-party verification partnerships, and seed suppliers managing trait licensing for non-GMO alternatives. Capacity expansion in segregated handling infrastructure and strategic partnerships for blockchain traceability represent the dominant competitive moves.
Within the integrated agribusiness tier, Cargill and Bayer exemplify divergent strategic positioning—Cargill anchoring elevator-network control while Bayer manages upstream seed genetics. Nestle occupies a position among packaged food manufacturers prioritizing reformulation speed and verification partnerships across European retail markets. These three entities represent the competitive spectrum from raw material throughput to consumer-facing brand trust architecture.
| Leading Market Players |
|---|
| Syngenta |
| Danone |
| Unilever |
| Cargill |
| Nestle |
| Bayer |
| Corteva Agriscience |
| General Mills |
| Campbell Soup |
| Others |
Supply & Pricing Matrix
EU Green Deal traceability mandates gate qualified supply and premium-tier pricing access by requiring batch-level origin documentation that only segregated elevator networks can satisfy. Processors lacking identity-preserved infrastructure face exclusion from German and French retail hybrid tiers, compressing their margins to commodity benchmarks.
Pricing Analysis
Verification-bundling separates premium positioning from unbundled commodity alternatives, with third-party certification and blockchain provenance included in top-tier pricing while basic disclosure compliance stands alone. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with EU Organic commanding the highest tier. Cost compression in the standard tier is intensifying as mid-size processors absorb segregated handling overhead without passing through full premiums. Food manufacturers show least price sensitivity due to contract catering specifications, while conventional grain traders remain most sensitive.
Supply Chain Analysis
Domestic-content mandates in France and Germany reshape sourcing by requiring farm-gate documentation from within EU customs territories, excluding spot market purchases from third-country origins. Supply concentrates in the United States Midwest, Brazil's Mato Grosso, and the Paris Basin, drawing from non-GMO seed premiums, segregated elevator capacity, and dedicated crusher infrastructure. Single-source vulnerability runs through Iowa and Illinois elevator networks serving multiple downstream handlers. Distribution runs through discounter chains in Germany and direct-to-consumer subscription platforms capturing urban households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where USDA's National Bioengineered Food Disclosure Standard creates a barrier-to-entry moat for processors with segregated handling infrastructure and chain-of-custody documentation systems.
For Market Incumbents: Deepen elevator network control in the Corn Belt to preserve identity-preserved throughput against emerging blockchain-verified spot market alternatives. Expand dedicated crusher capacity in northern France to capture French retail hybrid tier demand before regional oilseed processors consolidate access.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route, targeting German urban households with bundled verification storytelling that bypasses supermarket slotting fees. White space exists in gene-edited oilseed positioning pending regulatory clarity on CRISPR disclosure requirements.
For Investors and Strategic Acquirers: Gene-editing regulatory determinations by EFSA and USDA are the leading indicator that formulation possibilities for oilseed developers will expand or contract. Long-term viability favors processors with backward integration into seed supply and captive elevator networks. Acquisition targets should combine segregated handling assets with existing third-party verification partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Enables real-time chain-of-custody documentation satisfying EU Green Deal audit requirements. |
| Segregated Elevator Network Expansion | Preserves identity-preserved status through multiple transfer points in Iowa and Illinois. |
| Third-Party Verification Partnership | Builds consumer trust through Non-GMO Project Verified protocols across packaged food portfolios. |
| Direct-to-Consumer Channel Launch | Bypasses German discounter slotting fees while capturing premium pricing through provenance storytelling. |
| Gene-Edited Product Formulation | Opens premium positioning in European oils pending regulatory clarity on CRISPR disclosure thresholds. |
Research Methodology
Independent corroboration across grain elevator operators, packaged food procurement managers, and third-party certification auditors underwrites the qualitative findings in this study. Primary interviews with supply chain directors at North American cooperatives, regulatory affairs leads at European oilseed processors, and category buyers at German discounter chains combined with secondary validation from USDA AMS enforcement records, EFSA guidance documents, and EU customs trade data. Bottom-up volume estimates from elevator throughput and top-down market sizing from retail SKU counts were triangulated to cross-check segmentation outputs.
Comparable historical periods anchored the forecast window to pre- and post-implementation phases of major disclosure standards. The analytical framework modeled product type, distribution channel, certification tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from trajectory fitting to documented capacity expansion timelines and retail shelf space allocation trends. Industry-specific inputs included elevator investment cycles in the Corn Belt and crushing capacity utilization in northern France.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time blockchain verification adoption rates introduce uncertainty bands around digital channel growth projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Food and Beverage Air Filtration Market