
 Gluten-Free Soups and Sauces Market | 2026-2036
Gluten-Free Soups and Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Soups and Sauces Market Foresight
The Gluten-Free Certification Organization (GFCO) standard is rotating competitive access, as brands without third-party verification face delisting from major retail banners. General Mills Inc. leverages its supply chain scale to secure certified oat and rice flour streams for soup bases. The Campbell Soup Company anchors North American distribution through controlled shelf placement in club and conventional grocery channels. Amy's Kitchen Inc. differentiates via organic positioning alongside gluten-free claims, sustaining premium price realization.
Gluten-free soups and sauces comprise liquid and semi-liquid food preparations formulated without wheat, barley, rye, or cross-contaminated oats, typically employing modified starches from tapioca, potato, or rice as thickening agents and achieving less than 20 ppm gluten content under analytical testing. These products serve celiac patients, gluten-sensitive consumers, and clean-label adherents seeking prepared meal components that eliminate allergen exposure while maintaining sensory parity with conventional formulations. Broths and pasta sauces command the largest volume pools within product type segmentation, while pouches are displacing cans as the fastest-growing packaging format due to convenience and microwave compatibility. Meal kits represent the most dynamic end-user channel, with specialty stores capturing disproportionate margin concentration versus hypermarkets.
The FDA gluten-free labeling rule and Health Canada's gluten-free regulations enforce analytical thresholds and manufacturing segregation protocols that determine market access for both domestic producers and importers. The USDA Organic seal intersects with gluten-free positioning, creating dual-certification compliance costs that filter smaller entrants from national retail distribution. Stakeholders must monitor evolving celiac disease diagnostic criteria and restaurant chain procurement mandates, as these clinical and commercial signals will reshape volume allocation between retail and food service channels.
Market Dynamics
Third-party gluten-free certification is concentrating retail access as major banners delist unverified suppliers, while meal kit procurement mandates reshape volume allocation between channels.
Growth Catalysts
- Celiac diagnosis protocols:Updated clinical criteria in the United States and European Union are expanding the diagnosed patient pool, creating sustained demand for certified broths and pasta sauces.
- Restaurant chain supplier mandates:National food service operators now specify gluten-free sauce procurement in contracts, forcing upstream reformulation across contract manufacturers.
- Modified starch innovation:Tapioca and rice-based thickening agents achieve sensory parity with wheat, removing the taste penalty that previously limited repeat purchase.
Market Restraints
- Dual-certification cost burden:USDA Organic compliance layered atop FDA gluten-free requirements filters smaller entrants from national retail distribution.
- Certified oat supply concentration:North American growers with dedicated gluten-free handling infrastructure command premium pricing, compressing margins for soup base manufacturers.
- Analytical testing capacity:Third-party laboratories with 20 ppm detection capability face booking backlogs, delaying product launch timelines.
Strategic Opportunities
- Meal kit channel expansion:Subscription services in the United States represent the fastest-growing end-user segment, with disproportionate margin capture versus conventional retail.
- Pouch packaging conversion:Microwave-compatible flexible formats are displacing cans in premium positioning, enabling single-serve convenience premiums.
- Clean-label convergence:Organic positioning alongside gluten-free claims sustains price realization in specialty stores versus hypermarket commoditization.
Industry Challenges
- Segregation protocol complexity:Manufacturing facilities must maintain dedicated production lines and cleaning validation to prevent cross-contamination, requiring capital-intensive facility redesign.
- Certification timeline compression:GFCO and similar third-party verification processes extend go-to-market cycles, creating working capital pressure for seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Soups and Sauces Market |
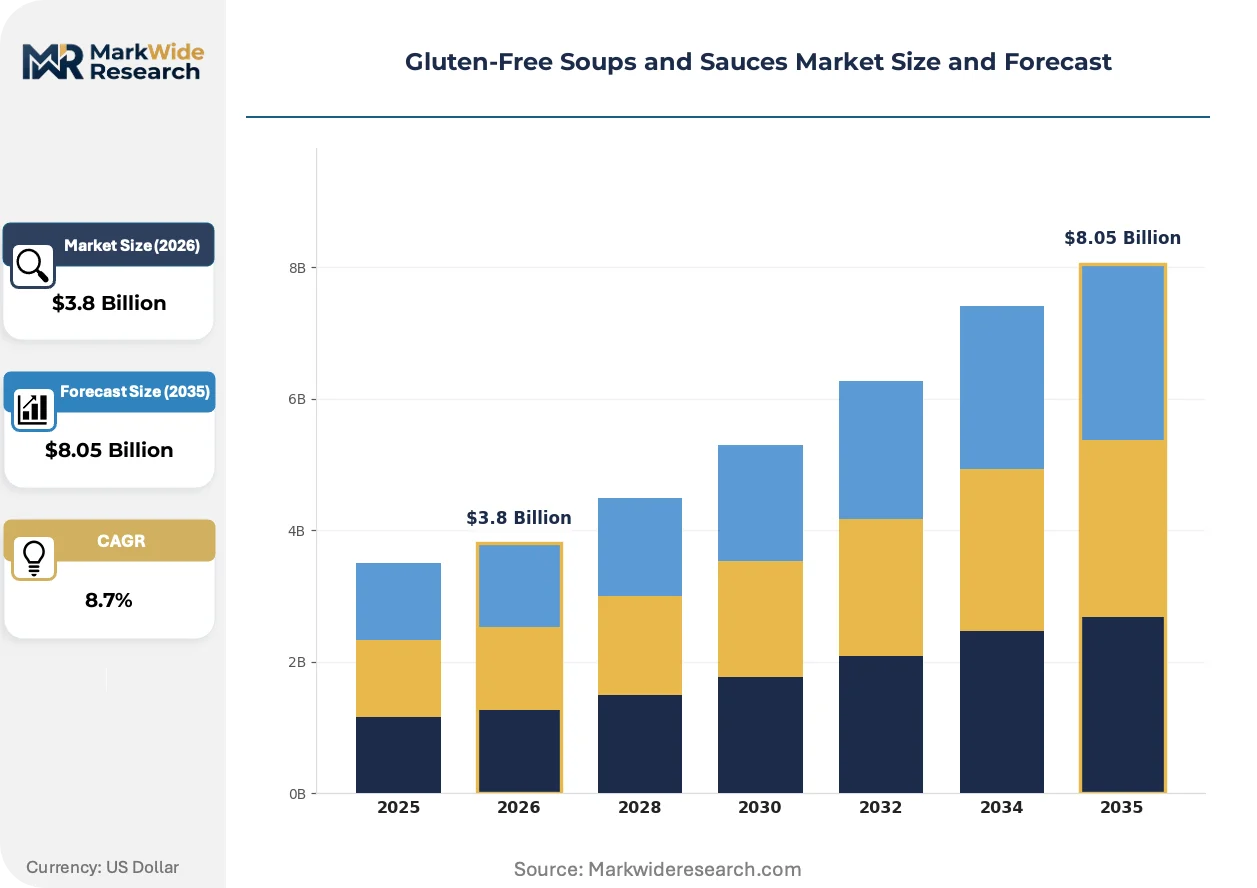
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broths, Gravies, Dips, Pasta Sauces End User: Food Service, Retail, Meal Kits, Restaurants Packaging Type: Tetra Packs, Jars, Pouches, Cans Distribution Channel: Online, Hypermarkets, Supermarkets, Specialty Stores |
| Companies Covered | General Mills Inc., The Campbell Soup Company, Conagra Brands Inc., The Kraft Heinz Company, Kikkoman Corporation, Amy's Kitchen Inc., Pacific Foods of Oregon LLC, The Hain Celestial Group, Barilla Holding S p A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Soups and Sauces Market Shifts & Advancements
Pouch packaging formats, regulatory tightening around analytical thresholds, and procurement centralization by food service aggregators are collectively restructuring competitive access and margin capture in prepared gluten-free meal components.
Modified tapioca and potato starches with enhanced freeze-thaw stability are supplanting traditional wheat-based roux in cream soup formulations. Meal kit services and prepared food manufacturers are adopting these alternatives at accelerating pace to meet supplier contract specifications. The shift is compressing demand for conventional wheat-thickened bases while elevating pricing power for certified-clean-ingredient suppliers.
Health Canada's gluten-free regulations and the FDA's labeling rule are tightening analytical thresholds and manufacturing segregation protocols that determine market access. Domestic producers and importers face expanded compliance documentation requirements for analytical testing and facility audits. Broth and pasta sauce categories bear disproportionate scrutiny due to their ingredient complexity and historical cross-contamination risk.
Buyer concentration through food service procurement platforms is consolidating supplier relationships and compressing switching cycles for gluten-free sauce vendors. National restaurant chains and institutional feeders now mandate third-party certification in vendor qualification, displacing self-declared gluten-free claims. The United States exhibits the most pronounced procurement centralization, with contract manufacturers adapting formulation and certification strategies to retain national account access.
Gluten-Free Soups and Sauces Market Segmentation
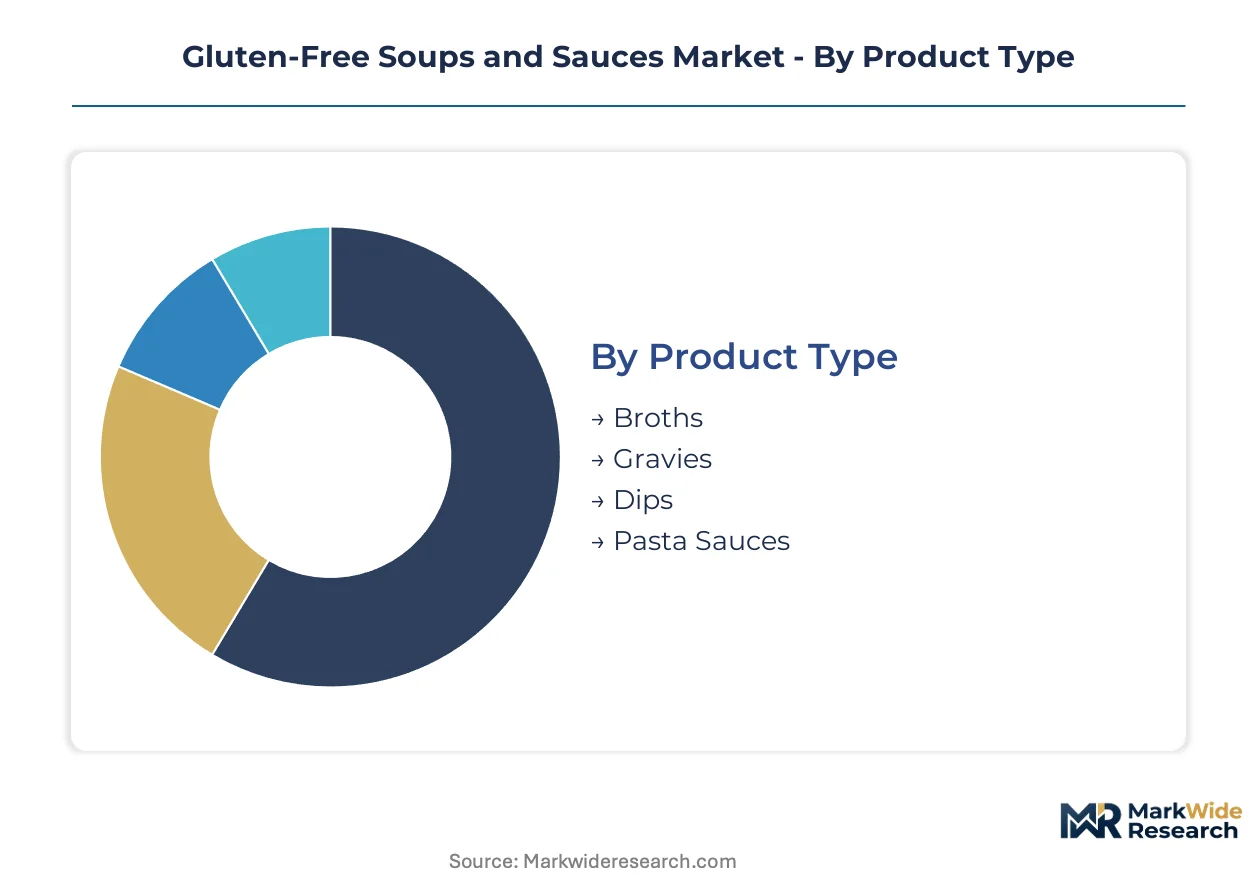
Segmentation in gluten-free soups and sauces determines where formulation investments concentrate and which certification tiers unlock retail access. Manufacturers prioritize categories where third-party verification commands shelf placement and procurement mandates.
Product Type:
Margin pools concentrate in liquid preparations where ingredient complexity and cross-contamination risk justify premium positioning.
- Broths:Clear liquid preparations utilizing certified gluten-free yeast extracts and vegetable bases. Demand clusters in meal kit procurement contracts across the United States, where supplier mandates now require GFCO verification for base ingredients.
- Pasta Sauces:Tomato and cream-based formulations employing modified tapioca or rice starches as wheat flour replacements. Restaurant chains in the United States specify these in centralized supplier agreements, driving reformulation across contract manufacturers.
- Gravies:Semi-liquid meat-based preparations thickened with potato or arrowroot starches.
- Dips:Cold emulsion products including hummus, salsa, and dairy-based variants with gluten-free thickening systems.
The dominant share belongs to Broths, while Pasta Sauces is closing the gap fastest.
End User:
Volume allocation tracks procurement centralization, with contract-driven channels capturing disproportionate margin versus fragmented retail.
- Meal Kits:Subscription-based prepared meal services specifying gluten-free components in supplier contracts. Procurement teams at U.S.-based aggregators now mandate third-party certification, compressing vendor pools to verified manufacturers.
- Restaurants:National food service operators with centralized purchasing and menu transparency requirements. Health Canada and FDA labeling rules force upstream compliance documentation for sauce vendors serving cross-border chains.
- Retail:Conventional grocery and club store channels with certified gluten-free shelf sets.
- Food Service:Institutional feeders including hospitals, schools, and corporate cafeterias with allergen management protocols.
Meal Kits command the steepest expansion trajectory, though Restaurants retain the largest absolute volume position.
Packaging Type:
Format selection determines microwave compatibility, shelf stability, and convenience premiums in channel-specific positioning.
- Pouches:Flexible multilayer films enabling single-serve portions and direct microwave heating. U.S. specialty stores capture margin premiums for this format against commoditized can alternatives.
- Tetra Packs:Aseptic carton systems for ambient-stable broths and stocks. Demand concentrates in European retail where extended shelf life reduces distribution cost.
- Jars:Glass containers for premium pasta sauces and dips with clean-label visibility.
- Cans:Traditional metal containers facing displacement in premium positioning due to heating limitations.
Pouches lead value growth, while Tetra Packs maintain volume leadership in broth categories.
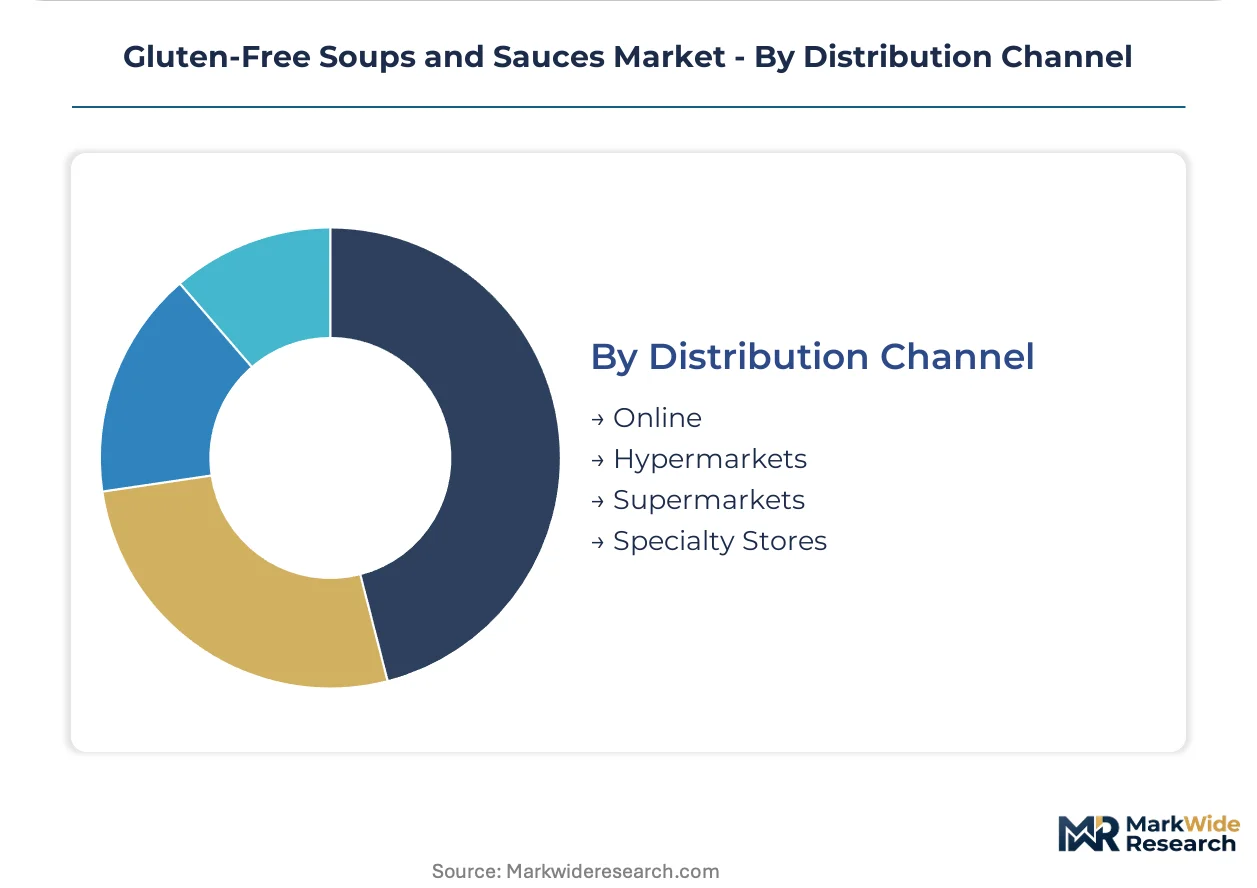
Distribution Channel:
Channel structure filters which certification tiers achieve consumer access, with specialty and online rewarding dual-label positioning.
- Specialty Stores:Natural and organic retailers with dedicated gluten-free sections and educated consumer bases. USDA Organic intersects with gluten-free claims here, sustaining price realization above hypermarket levels.
- Online:Direct-to-consumer and marketplace platforms enabling subscription models and discovery. U.S. consumers utilize these channels for certified products unavailable in conventional retail.
- Supermarkets:Conventional grocery with expanding certified shelf space as celiac diagnosis climbs.
- Hypermarkets:Mass merchandisers driving volume through price-focused private label offerings.
Specialty Stores capture the highest margin per unit, though Online is gaining share fastest in subscription formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's gluten-free labeling rule and Health Canada's parallel standards are tightening compliance thresholds that determine market access for domestic producers and importers across North America and Europe. Celiac diagnosis protocols in the United States and European Union are expanding the addressable patient population, while restaurant chain procurement mandates force upstream reformulation across contract manufacturers.
United States
Meal kit subscription services and national restaurant chains now specify gluten-free sauce procurement in supplier contracts, concentrating volume among verified manufacturers. FDA enforces the 20 ppm analytical threshold and manufacturing segregation protocols through facility audits and documentation requirements. Chicago and Minneapolis-St. Paul host contract manufacturing clusters where facilities maintain dedicated production lines for certified broth and pasta sauce production.
Canada
Health Canada's gluten-free regulations align with FDA standards while imposing additional bilingual labeling requirements that filter smaller importers from national distribution. The Canadian Food Inspection Agency conducts randomized analytical testing at retail to verify compliance with declared gluten content. Toronto and Vancouver anchor retail expansion of certified shelf-stable soups, with club stores capturing disproportionate volume growth versus conventional grocery.
Germany
EFSA guidance on gluten thresholds informs national implementation through the Federal Ministry of Food and Agriculture, creating compliance harmonization pressure for exporters serving multiple European markets. Celiac disease prevalence estimates of approximately 1% drive sustained demand for certified pasta sauces and ready-to-eat soup formulations. The Rhine-Ruhr industrial corridor concentrates food processing capacity where manufacturers retrofit facilities for dedicated gluten-free production lines.
United Kingdom
National Health Service diagnostic criteria expansion and patient advocacy group pressure have elevated celiac awareness, translating into retail shelf space allocation for certified products. The Food Standards Agency maintains enforcement protocols for gluten-free claims that exceed baseline EU requirements post-Brexit. London and the Southeast England retail corridor exhibit the steepest adoption curves for pouch-packaged premium broths and organic-positioned pasta sauces.
Italy
Traditional wheat-based culinary culture creates dual pressure: domestic manufacturers reformulate heritage recipes while export-oriented producers seek gluten-free certification for North American and Northern European markets. The Ministry of Health implements EU Regulation 828/2014 on gluten-free foods with additional national labeling specifications. Emilia-Romagna and Lombardy host pasta sauce manufacturing clusters where facilities invest in analytical testing capacity and third-party certification to retain access to regulated export markets.
Gluten-Free Soups and Sauces Market Competitive Landscape
Player mix skews toward diversified food conglomerates with existing supply chain scale, though specialty organic operators capture premium positioning in certified segments. Market structure exhibits moderate consolidation at the national account level, with procurement centralization by meal kit aggregators and restaurant chains compressing vendor pools. Three archetypes dominate: scale-driven diversified manufacturers leveraging ingredient sourcing advantages, organic-specialist brands commanding dual-certification premiums, and contract manufacturers serving private-label and food service accounts. Competitive dynamics center on third-party certification acquisition and pouch packaging capacity expansion.
Within the diversified conglomerate tier, General Mills Inc. and The Campbell Soup Company exemplify scale-driven positioning where supply chain infrastructure secures certified oat and rice flour streams for soup base production. Amy's Kitchen Inc. occupies the organic-specialist archetype, sustaining price realization through dual USDA Organic and gluten-free certification in specialty retail channels. Conagra Brands Inc. and The Kraft Heinz Company represent portfolio breadth strategies spanning multiple meal component categories with centralized procurement leverage.
| Leading Market Players |
|---|
| General Mills Inc. |
| The Campbell Soup Company |
| Conagra Brands Inc. |
| The Kraft Heinz Company |
| Kikkoman Corporation |
| Amy's Kitchen Inc. |
| Pacific Foods of Oregon LLC |
| The Hain Celestial Group |
| Barilla Holding S p A |
| Others |
Supply & Pricing Matrix
FDA's gluten-free labeling rule gates both supplier qualification and price differentiation simultaneously, as manufacturers without third-party verification face delisting from major retail banners while certified brands command shelf placement premiums. This regulatory threshold concentrates pricing power among verified producers who have absorbed compliance costs, filtering smaller entrants from national distribution and compressing margin pools for unverified competitors.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with GFCO-verified products sustaining price realization in specialty stores while self-declared alternatives face commoditization in hypermarkets. Three-tier pricing structure across premium, standard, and economy levels reflects dual-certification status and packaging format, with organic-gluten-free combinations capturing the highest premiums. Cost compression in the economy tier is intensifying because private-label entrants are scaling pouch production for meal kit procurement. Food service aggregators exhibit the least price sensitivity due to contract-based volume commitments, while hypermarket shoppers drive the steepest discount pressure.
Supply Chain Analysis
The United States and Canada anchor certified oat and rice flour production for gluten-free soup bases, with dedicated handling infrastructure commanding premium input pricing. Modified tapioca and potato starches draw from Southeast Asian processing clusters, while analytical testing capacity rests on third-party laboratories with 20 ppm detection capability. Single-source vulnerability concentrates in certified oat supply, where North American growers with gluten-free handling protocols control limited acreage. Distribution runs through club store and conventional grocery channels in the United States, with direct-to-meal-kit procurement bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a certification-driven consolidation cycle, as updated FDA and Health Canada protocols forced facility investments that are now yielding procurement contract access.
For Market Incumbents: Shield margin position by deepening backward integration into certified oat milling and rice flour processing, securing captive supply streams that smaller competitors cannot replicate. Accelerate pouch packaging capacity expansion in Chicago and Minneapolis-St. Paul manufacturing clusters to capture meal kit procurement mandates before contract windows close. GFCO certification renewal timelines represent the critical threat to shelf placement continuity. For New Entrants and Emerging Players: White-space in organic-positioned pasta sauces for European export markets offers the most penetrable entry vector, as Italian heritage brands face reformulation pressure for North American regulatory compliance. Direct-to-consumer subscription models bypass retail slotting fee barriers that concentrate shelf access among diversified conglomerates. Target dual-certification compliance as the primary go-to-market angle, as USDA Organic intersecting with gluten-free claims unlocks specialty store placement unavailable to single-label competitors. For Investors and Strategic Acquirers: Health Canada's bilingual labeling requirements and FDA facility audit protocols reshape the acquisition landscape toward mid-scale manufacturers with existing third-party verification infrastructure. Five-to-ten year viability favors contract manufacturers serving meal kit aggregators and national restaurant chains, as procurement centralization compresses vendor pools. The signal to monitor is analytical testing laboratory capacity expansion, as booking backlogs indicate certification demand acceleration that precedes volume growth inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Certification Investment | GFCO verification unlocks shelf placement at major U.S. retail banners and meal kit procurement contracts. |
| Pouch Packaging Conversion | Flexible microwave-compatible formats capture premium positioning in specialty stores against commoditized cans. |
| Backward Integration into Certified Grains | Captive oat and rice flour supply secures margin control against North American grower premium pricing. |
| Dual-Label Product Development | USDA Organic intersecting with gluten-free claims sustains price realization above hypermarket private-label tiers. |
| Meal Kit Channel Partnership | Direct supplier contracts with U.S. subscription services bypass traditional wholesale distribution markups. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA compliance documentation, Health Canada regulatory filings, and retail audit data from Nielsen and Circana. Interviews with category buyers at club stores, procurement directors at meal kit aggregators, and plant managers at contract manufacturing facilities in Chicago and Minneapolis-St. Paul informed supply chain dynamics. Secondary sources included GFCO certification databases, USDA organic handler registrations, and customs records for modified starch imports. Bottom-up volume modeling triangulated against top-down market sizing from channel-specific revenue analysis.
Segmentation dimensions modeled encompass product type, end-user channel, packaging format, and distribution channel across the projection horizon. Value outputs reflect price realization by certification tier and channel margin structure, with CAGRs derived from trend extrapolation of celiac diagnosis rates and restaurant chain procurement adoption curves. Forecast inputs incorporated meal kit subscription growth trajectories and analytical testing laboratory capacity expansion timelines.
Material uncertainties — regulatory threshold revisions, certified grain supply disruptions, and procurement contract cancellation rates — sit outside the modeled envelope. Forecasts reflect assumptions about sustained FDA and Health Canada enforcement intensity and stable diagnostic criteria expansion. Recalibration cycles align with material shifts in third-party certification requirements and meal kit aggregator consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market