
 Europe Home Organizers and Storage Market | 2026-2036
Europe Home Organizers and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Organizers and Storage Market Foresight
Asset-light leasing and subscription-based furniture models are tilting competitive dynamics toward players with flexible supply chains. IKEA Group leverages its flat-pack logistics network to sustain low-cost penetration across Nordic and Continental markets. Elfa International AB anchors premium positioning through customizable closet systems. JYSK A/S competes on value-tier density with rapid inventory turns across Eastern European store networks.
Home organizers and storage encompass modular containment and spatial optimization systems fabricated from injection-molded polymers, powder-coated steel, engineered timber, or woven textiles, typically rated for load capacities between five and fifty kilograms depending on mounting configuration. These products serve residential and commercial environments by maximizing usable volume within constrained floor plans. Plastic and metal materials dominate volume production due to cost scalability and durability performance, while wood and fabric segments capture margin pools through aesthetic differentiation in premium residential channels. The residential end-user segment leads absolute consumption, though hospitality procurement is expanding fastest as boutique hotel operators standardize compact-room designs.
REACH regulation and the EU Green Deal mandate chemical safety disclosures and recycled content thresholds that reshape material sourcing decisions for manufacturers serving European markets. ECHA substance restrictions and national extended producer responsibility frameworks in Germany and France add compliance layers that favor larger suppliers with dedicated regulatory teams. Stakeholders must monitor evolving ecodesign requirements and packaging waste directives that will determine which material formats retain market access across the next regulatory cycle.
Market Dynamics
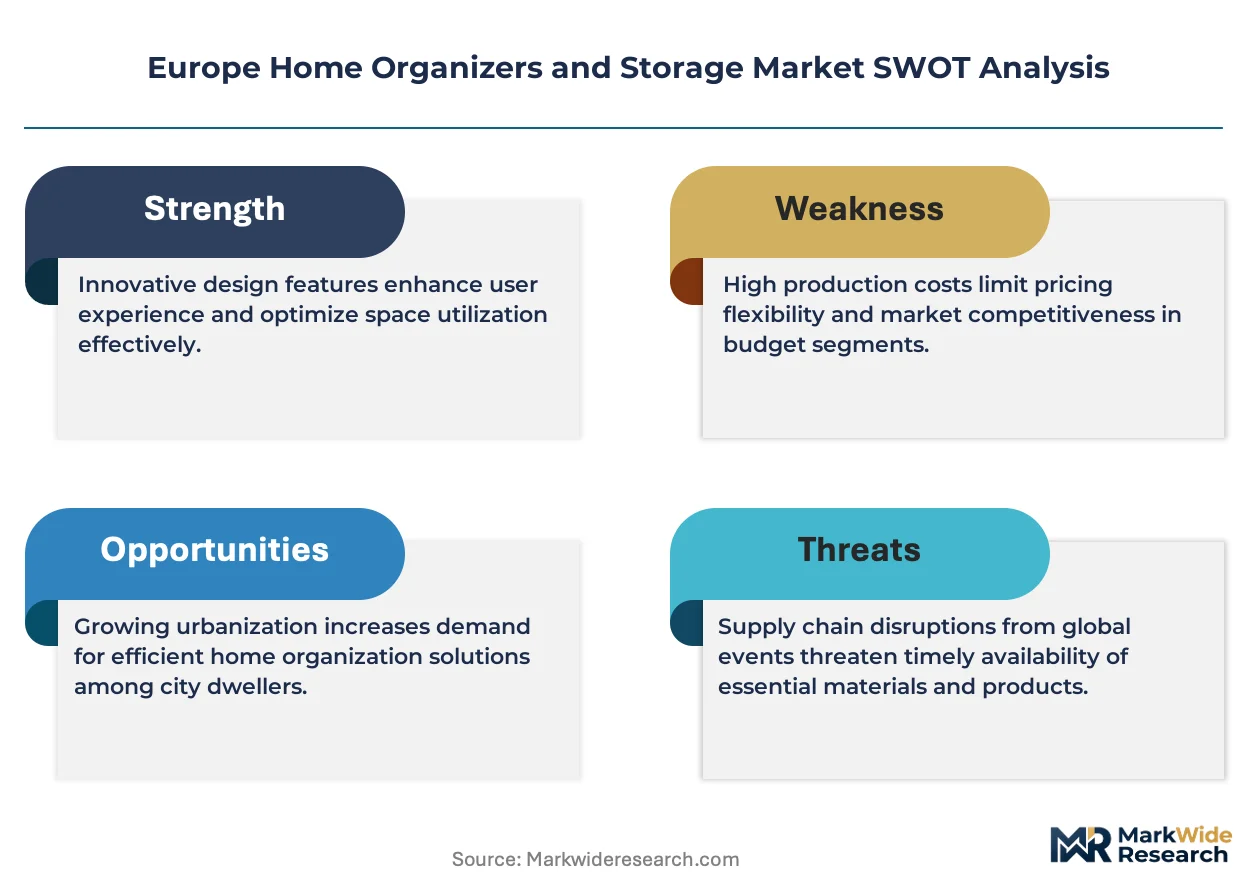
The EU Green Deal and REACH compliance are compressing material choices across European manufacturing, forcing rapid substitution of virgin plastics with recycled feedstocks and low-emission finishes while raising compliance costs for mid-tier suppliers.
Growth Catalysts
- Urban housing densification:Apartment dwellers in Germany, France, and the United Kingdom are expanding purchases of modular closet systems to maximize constrained floor plans. Residential renovation activity remains elevated in these markets.
- Ecodesign mandates:Extended producer responsibility frameworks in Germany and France create procurement preference for suppliers with circular material flows. National packaging waste directives accelerate format innovation.
- Hospitality standardization:Boutique hotel operators across Nordic markets are standardizing compact-room designs, expanding commercial demand for space-optimized containment systems.
Market Restraints
- Polymer feedstock volatility:Injection-molded polymer costs fluctuate with crude oil derivatives, compressing margin predictability for volume producers dependent on petrochemical inputs.
- Regulatory fragmentation:ECHA substance restrictions vary by member state implementation, creating compliance friction for suppliers serving multiple national markets without dedicated regulatory teams.
- Steel tariff exposure:Powder-coated steel sourcing faces import duty uncertainty, particularly for fabricants reliant on non-EU primary metal suppliers.
Strategic Opportunities
- Eastern European expansion:Underpenetrated markets in Poland and Romania present white space for value-tier distribution networks with rapid inventory turn capabilities.
- Textile-woven premiumization:Aesthetic differentiation through fabric-based containment systems captures margin pools in residential channels seeking visual warmth over industrial aesthetics.
- Asset-light leasing models:Subscription-based furniture procurement is tilting competitive dynamics toward players with flexible reverse logistics and refurbishment capabilities.
Industry Challenges
- REACH documentation timelines:Chemical safety disclosure requirements for recycled content create product development bottlenecks, particularly for suppliers without in-house toxicology expertise.
- Legacy retail integration:Flat-pack logistics networks require substantial reconfiguration to accommodate circular economy return flows and refurbishment operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Organizers and Storage Market |
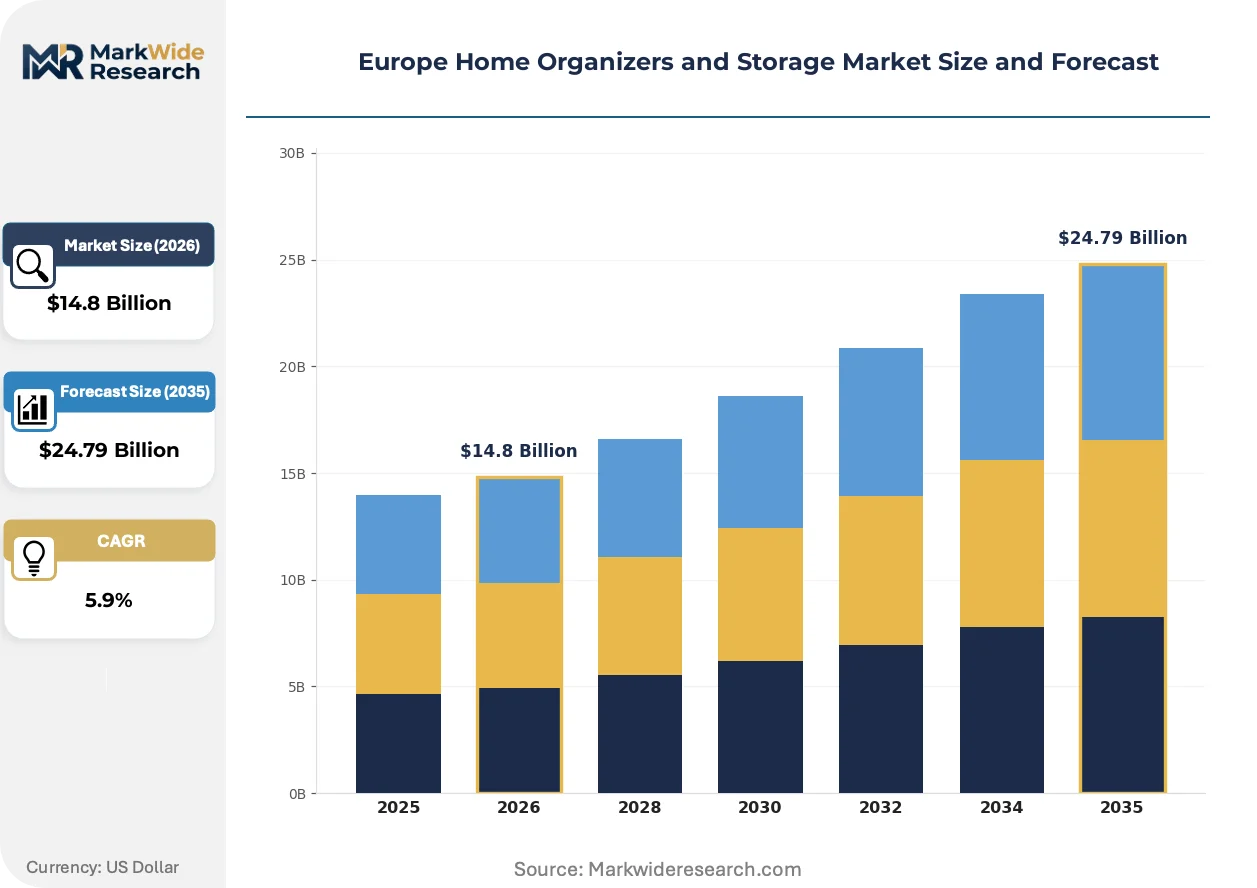
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bins, Shelving Units, Closet Organizers, Hooks Material: Plastic, Metal, Wood, Fabric End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online Retail, Specialty Stores, Home Improvement, Wholesale |
| Companies Covered | IKEA Group, Elfa International AB, JYSK A/S, Brabantia Branding BV, Orthex Group, Hettich Holding GmbH, Laura Ashley, Childhome, Awekris, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Organizers and Storage Market Shifts & Advancements
Material science and regulatory chemistry are converging to reshape competitive positioning, with sustainability credentials becoming a gatekeeper for retail shelf access rather than a premium overlay.
Recycled polymer compounding is migrating from niche certification plays to baseline procurement requirements. Retail buyers in Germany and France now mandate post-consumer content thresholds for injection-molded storage products. This shift is compressing virgin resin demand while rewarding suppliers with backward integration into mechanical recycling operations.
REACH regulation and the EU Green Deal are mandating chemical safety disclosures and recycled content thresholds that reshape material sourcing decisions. ECHA substance restrictions and national extended producer responsibility frameworks add compliance layers favoring larger suppliers with dedicated regulatory teams. Manufacturers must monitor evolving ecodesign requirements that will determine which material formats retain market access.
Leasing and subscription-based furniture procurement is displacing traditional ownership models in urban residential segments. IKEA Group leverages its flat-pack logistics network to sustain low-cost penetration, while premium players build customizable closet systems for affluent households. This bifurcation is most visible in Nordic markets where circular economy literacy among consumers exceeds Continental averages.
Europe Home Organizers and Storage Market Segmentation
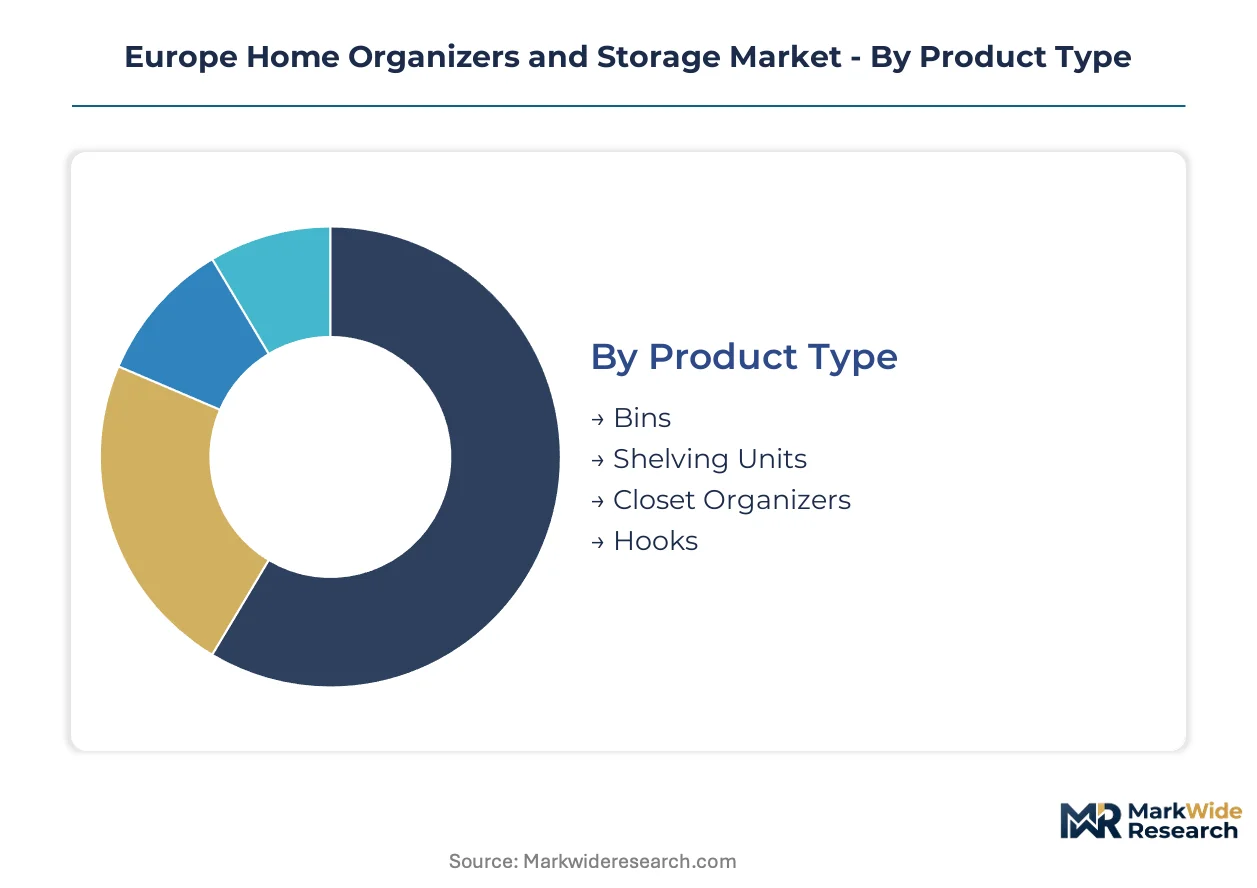
Segmentation reveals how material science, distribution economics, and end-use requirements fragment purchasing behavior across European markets. Manufacturers must align product architectures with distinct performance thresholds and channel economics governing each category.
Product Type:
Mature formats dominate absolute volume while emerging configurations capture renovation-driven replacement cycles.
- Bins:Injection-molded polymer containers with stackable geometries and lid-sealing mechanisms serve pantry, garage, and under-bed storage applications. German and French households prioritize transparent or color-coded variants for closet system integration. REACH-compliant recycled polypropylene feedstocks are becoming baseline procurement requirements for retail buyers.
- Closet Organizers:Modular rail-and-shelf systems with adjustable hanging rods and drawer modules maximize vertical volume in urban apartments. United Kingdom residential renovation activity sustains demand for customizable configurations that accommodate sloped ceilings and alcove dimensions.
- Shelving Units:Freestanding or wall-mounted systems fabricated from powder-coated steel or engineered timber serve garage and utility room applications.
- Hooks:Adhesive, magnetic, or screw-mounted hardware for entryway and kitchen organization completes the product spectrum.
Bins retain volume leadership; closet organizers hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity feedstocks from aesthetic premium positioning.
- Plastic:Recycled polypropylene and ABS compounds deliver cost scalability and moisture resistance for high-turnover retail channels. Ecodesign mandates in Germany and France now enforce post-consumer content thresholds, compressing virgin resin demand.
- Metal:Powder-coated steel tubing and wire grids provide load-bearing capacity for garage and commercial applications. Import duty exposure on non-EU primary metal creates margin volatility for fabricants without captive European sourcing.
- Wood:Engineered timber and solid hardwood variants capture residential premium channels seeking visual warmth.
- Fabric:Woven textile containment systems with collapsible frames serve seasonal storage and wardrobe applications.
Plastic commands absolute unit volume; fabric is climbing the fastest on aesthetic differentiation premiums.
End User:
Application context determines durability specifications and procurement decision structures.
- Residential:Individual households purchasing through retail or direct channels prioritize modular adaptability and visual integration with interior finishes. Urban densification in German, French, and United Kingdom metropolitan areas sustains replacement demand for space-optimized systems.
- Hospitality:Boutique hotel operators across Nordic markets standardize compact-room designs with built-in storage, creating specification-driven procurement with volume consolidation potential.
- Commercial:Office and co-working space fit-outs require durable, high-cycle hardware for shared environments.
- Retail:Back-of-house inventory management and customer-facing merchandise display systems complete the segment map.
Residential channels absorb the majority of unit flow; hospitality procurement is gaining share fastest on standardization trends.
Distribution Channel:
Customer type and purchase urgency shape channel selection and margin extraction.
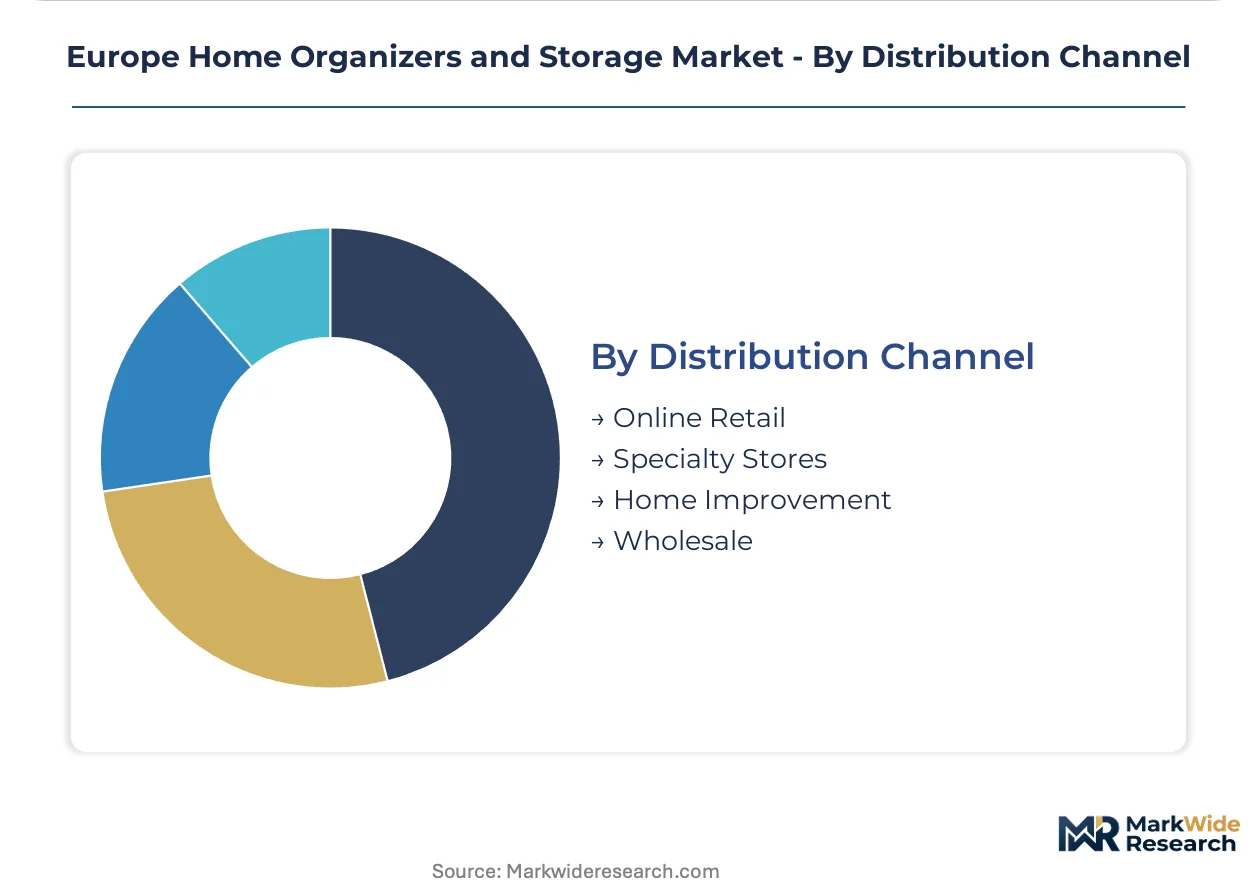
- Specialty Stores:Curated assortments with in-person configuration consultation support premium closet system sales. United Kingdom and German urban centers sustain showroom economics for customized installations.
- Online Retail:Flat-pack logistics and augmented reality visualization tools enable remote specification of modular systems. Nordic markets exhibit highest digital penetration for furniture-category purchases.
- Home Improvement:Big-box retailers serve immediate-need replacement and renovation project bundling.
- Wholesale:Contract furnishing and hospitality procurement channels consolidate large-format orders.
Specialty stores retain margin leadership; online retail is expanding most quickly on logistics network maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies and national renovation incentives are channeling procurement toward recycled-content storage systems across member states. REACH compliance timelines vary by enforcement intensity, creating differentiated market access conditions. Housing density gradients and urban renewal pipelines determine where modular closet demand concentrates most acutely.
Germany
Residential renovation tax credits and KfW efficiency programs sustain demand for space-optimized closet systems in Berlin and Hamburg apartment stock. Extended producer responsibility frameworks under the Verpackungsgesetz mandate circular material flows for injection-molded storage products. The North Rhine-Westphalia manufacturing belt hosts compounders scaling recycled polypropylene feedstocks for retail buyer compliance.
France
MaPrimeRénov grants and Parisian housing densification accelerate modular containment purchases for compact urban dwellings. ANSM chemical safety disclosures and AGEC anti-waste provisions enforce recycled content thresholds for plastic storage formats. The Île-de-France logistics corridor concentrates distribution hubs serving both domestic retail and cross-border hospitality procurement.
United Kingdom
Sloped-ceiling renovations and alcove conversions in London and Manchester sustain demand for customizable closet configurations. Building safety regulations post-Grenfell tighten material certification requirements for residential fit-outs. The Midlands manufacturing cluster supplies powder-coated steel shelving systems to home improvement retailers with rapid inventory turn requirements.
Sweden
Stockholm and Gothenburg rental markets exhibit highest circular economy literacy, accelerating subscription-based furniture procurement over ownership models. Swedish Chemicals Agency (KEMI) enforcement of REACH substance restrictions exceeds baseline EU compliance, filtering supplier access. The Nordic flat-pack logistics network enables reverse logistics integration for refurbishment and leasing operations.
Poland
Warsaw and Kraków urbanization rates outpace storage product penetration, creating white space for value-tier distribution expansion. National packaging waste directives align with EU ecodesign trajectories but enforcement lags Western counterparts. The Silesian industrial zone hosts injection molding capacity serving price-sensitive Eastern European retail channels.
Europe Home Organizers and Storage Market Competitive Landscape
On the supply side, the industry is bifurcated between scale-driven flat-pack operators and premium customization specialists. Tiered competitive dynamics separate logistics-heavy volume players from margin-focused design houses. Three archetypes dominate: multinational furniture conglomerates with captive retail networks, regional specialists in modular closet engineering, and value-tier discounters with rapid inventory velocity. Consolidation pressures favor M&A activity among mid-tier compounders lacking backward integration, while portfolio diversification into textile-woven formats captures aesthetic premium pools.
Among Nordic-based operators, IKEA Group exemplifies scale-driven logistics integration, while Elfa International AB occupies the premium customization tier with closet system specialization. JYSK A/S represents the value-tier velocity archetype across Eastern European store networks. These three anchors illustrate how geographic origin and organizational structure map to competitive positioning without mandating identical strategic moves.
| Leading Market Players |
|---|
| IKEA Group |
| Elfa International AB |
| JYSK A/S |
| Brabantia Branding BV |
| Orthex Group |
| Hettich Holding GmbH |
| Laura Ashley |
| Childhome |
| Awekris |
| Others |
Supply & Pricing Matrix
The North Rhine-Westphalia manufacturing belt hosts compounders scaling recycled polypropylene feedstocks, concentrating backward integration capabilities among German suppliers and amplifying pricing power against mid-tier competitors lacking captive recycling operations. This geographic supply concentration shapes downstream cost structures across retail buyer negotiations.
Pricing Analysis
Certification level (REACH-compliant recycled content thresholds) creates the primary spread between premium and value-tier positioning. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by post-consumer content ratios and ECHA disclosure documentation. Cost compression in the standard tier is intensifying because virgin resin volatility compresses margin predictability. Hospitality procurement exhibits lowest price sensitivity due to specification-driven consolidation, while Eastern European retail channels remain most price-sensitive.
Supply Chain Analysis
REACH substance restrictions and ECHA documentation requirements limit feedstock flows from non-compliant jurisdictions, filtering supplier access to European markets. Manufacturing concentrates in Germany, Poland, and Sweden, with raw material dependencies on recycled polymer feedstocks, powder-coated steel tubing, and engineered timber panels. Single-source vulnerability runs through mechanical recycling compounders serving retail buyer mandates. Distribution runs through flat-pack logistics networks with reverse logistics integration for circular economy refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH compliance documentation and extended producer responsibility frameworks erect barriers that favor incumbents with dedicated toxicology teams.
For Market Incumbents: Build regulatory moats through REACH substance pre-registration and AGEC anti-waste certification ahead of enforcement intensification. Consolidate backward integration into mechanical recycling operations to secure post-consumer polypropylene feedstocks. Threat of mid-tier compounder margin collapse from documentation bottlenecks creates acquisition opportunities. Leverage vertical integration to defend position against value-tier discounters. For New Entrants and Emerging Players: Build out textile-woven premium positioning in underpenetrated Polish and Romanian markets where aesthetic differentiation commands margin premiums. Target hospitality specification channels in Nordic markets where circular economy literacy accelerates subscription-based procurement. White space exists in fabric-based containment systems for seasonal storage applications. Go-to-market through direct digital channels with augmented reality visualization tools. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier compounders lacking backward integration face structural margin compression from recycled content mandates. Acquisition target archetype: regional specialists with REACH documentation capabilities and captive recycling feedstock access. Signal to watch is enforcement intensity divergence between German/French regulators and Eastern European counterparts, which would reshape competitive access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captive post-consumer polypropylene supply secures retail buyer compliance with AGEC thresholds. |
| REACH Substance Pre-Registration | ECHA documentation capabilities filter competitor access and sustain premium positioning. |
| Textile-Woven Product Line Extension | Fabric-based containment captures aesthetic premium pools in residential renovation channels. |
| Subscription-Based Furniture Leasing Launch | Reverse logistics integration enables circular economy participation in Swedish rental markets. |
| Eastern European Distribution Expansion | Warsaw and Kraków urbanization outpaces storage penetration, creating value-tier white space. |
Research Methodology
A standing panel of category buyers at German and French home improvement retailers, procurement directors at Nordic hospitality operators, plant managers at North Rhine-Westphalia polymer compounders, and regulatory affairs leads at REACH-compliant manufacturers provided ongoing calibration. Primary interviews combined with secondary validation from ECHA substance restriction databases, national packaging waste directive filings, customs trade data on polymer feedstock flows, and SEC disclosures from listed furniture conglomerates. Bottom-up unit economics triangulated against top-down market sizing across material format and end-use segments.
Scenario-bracketing framed low, base, and high cases across regulatory enforcement intensity, polymer feedstock cost volatility, and hospitality procurement standardization velocity. Segmentation dimensions modeled include product type, material composition, end-user application, and distribution channel complexity. CAGRs derived from trend extrapolation adjusted for replacement cycle dynamics and renovation activity indices. Industry-specific inputs encompassed KfW efficiency program uptake rates and MaPrimeRénov grant disbursement patterns.
Stress conditions across REACH documentation timeline extensions, recycled polymer feedstock cost spikes, and Eastern European retail channel expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and circular economy adoption curves. Material shifts in ECHA substance restriction scope or national extended producer responsibility fee structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Shop Shelving Market