
 United Kingdom Home Decor Market | 2026-2036
United Kingdom Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Home Decor Market Analytics
UK furniture manufacturing is broadening output capacity to serve renewed domestic refurbishment cycles. Kingfisher plc anchors extensive DIY and trade distribution through B&Q and Screwfix banners. Dunelm Group plc specializes in vertically integrated textile and soft furnishing production. Wayfair Inc. competes through digital-native inventory breadth and rapid delivery fulfillment.
United Kingdom home decor encompasses movable and fixed interior enhancement products—furniture, lighting, textiles, and wall treatments—typically specified by dimensional fit, fire-retardant fabric ratings, and FSC-certified timber sourcing, serving residential and hospitality environments where aesthetic cohesion and functional durability intersect. Furniture and lighting together occupy the largest value share, reflecting high-ticket replacement cycles and energy-efficient retrofit mandates. Rustic and industrial style segments are gaining velocity as heritage-influenced and loft-conversion aesthetics penetrate suburban markets outside London.
The Office for Product Safety and Standards enforces flammability standards under the Furniture and Furnishings (Fire Safety) Regulations, while the UK Timber Regulation restricts illegal logging in imported wood supply chains. Building Regulations Part L and the emerging Future Homes Standard shape demand for thermally efficient windows, doors, and integrated lighting systems. Stakeholders must track regulatory divergence from EU Ecodesign requirements and calibrate sourcing strategies accordingly.
Market Dynamics
The UK Home Decor Market faces structural pressure from the Future Homes Standard mandating thermal efficiency upgrades, while millennial first-time buyers accelerate renovation cycles and modular furniture uptake across Greater London and South East corridors.
Growth Catalysts
- Future Homes Standard compliance:Building Regulations Part L revisions mandate thermally efficient windows, doors, and integrated lighting systems. Residential retrofit demand concentrates in pre-1990 housing stock requiring fabric upgrades.
- Millennial first-time buyer renovation:This demographic segment prioritizes modular furniture systems and heritage-influenced aesthetics. Suburban markets outside London exhibit accelerating uptake of loft-conversion styling.
- Greater London housing turnover:Elevated disposable income levels in the South East support premium home styling expenditure. High-ticket replacement cycles for furniture and lighting sustain value concentration in this corridor.
Market Restraints
- Timber sourcing compliance costs:The UK Timber Regulation restricts illegal logging in imported wood supply chains. FSC-certified timber sourcing adds procurement complexity and certification overhead for domestic manufacturers.
- Flammability testing burden:The Furniture and Furnishings (Fire Safety) Regulations enforce fabric and filling standards. Fire-retardant ratings require extensive laboratory validation extending product development timelines.
- EU regulatory divergence risk:Ecodesign requirements may diverge from UK standards post-Brexit. Stakeholders face dual compliance burdens for cross-border supply chains serving both markets.
Strategic Opportunities
- Digital-native fulfillment models:Rapid delivery platforms are capturing share from traditional retail. Inventory breadth and logistics speed differentiate competitors in textile and soft furnishing categories.
- Rustic-industrial aesthetic penetration:Heritage-influenced styling is migrating from urban cores to suburban markets. Regional housing stock outside London presents underpenetrated demand for loft-conversion aesthetics.
- Trade professional channel expansion:DIY and trade distribution networks serve renovation contractors directly. Screwfix and B&Q banners anchor professional procurement relationships with volume builders.
Industry Challenges
- Fire safety certification timelines:The Office for Product Safety and Standards maintains rigorous flammability enforcement. Product launch delays result from extended laboratory testing protocols for fabric ratings.
- Supply chain reconfiguration friction:Post-Brexit customs procedures disrupt just-in-time timber and textile imports. Warehouse capacity constraints in port regions compound inventory management complexity.
- Skills shortage in heritage craft techniques:Industrial and rustic styling demands specialized upholstery and metalworking competencies. Training pipeline gaps limit production scaling for authentic heritage reproductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Home Decor Market |
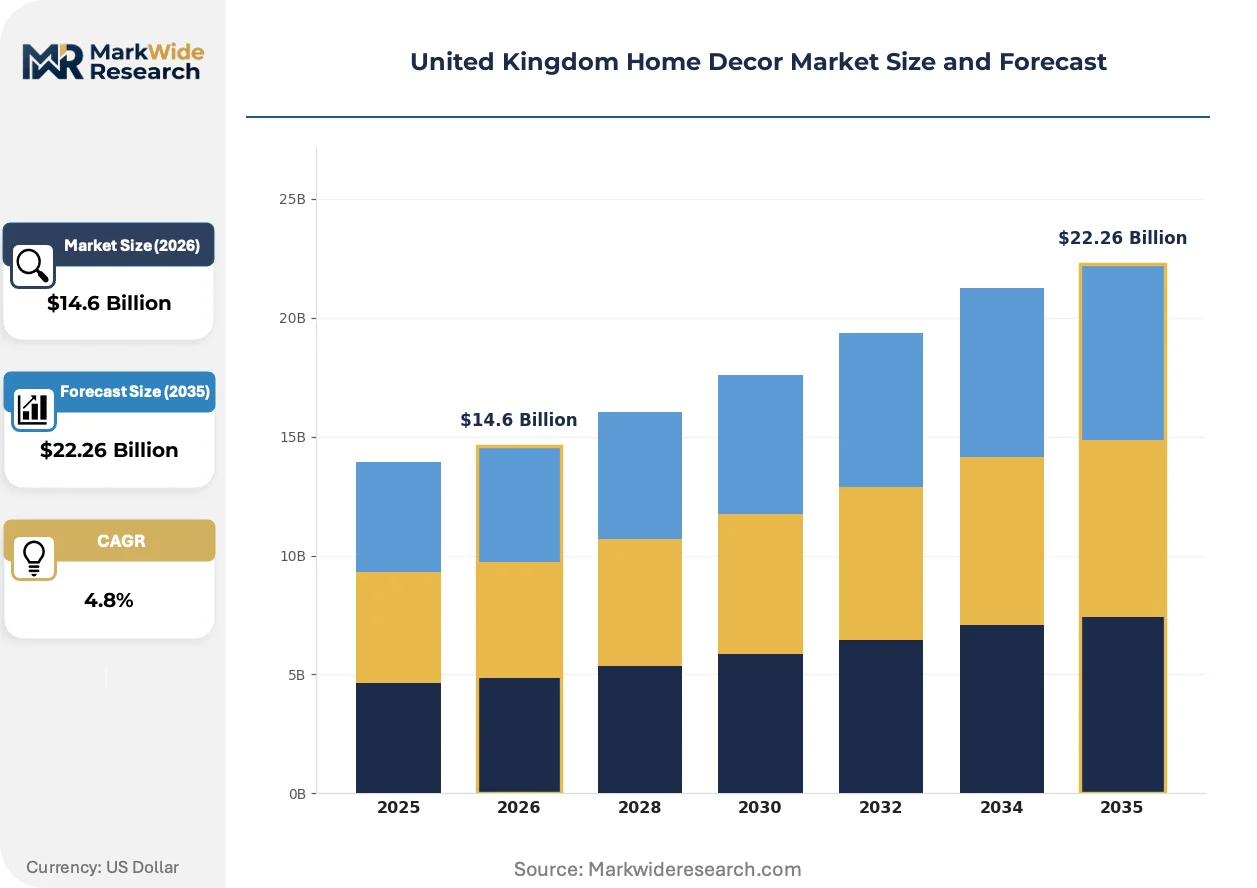
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $22.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Lighting, Rugs, Wall Art Material: Wood, Metal, Fabric, Glass Style: Modern, Traditional, Rustic, Industrial Price Tier: Luxury, Mid-range, Budget, Discount |
| Companies Covered | Kingfisher plc (B&Q), Wayfair Inc., IKEA Ltd (UK), Next plc, Homebase Ltd, Dunelm Group plc, John Lewis & Partners, Wickes Group plc, DFS Furniture plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Home Decor Market Evolving Landscape
Active transformation in UK home decor centers on energy-efficient retrofit mandates, digital distribution acceleration, and aesthetic migration from metropolitan cores to suburban markets.
Smart lighting control systems are expanding into residential retrofit projects. Homeowners in Greater London and the South East adopt app-enabled dimming and circadian programming at accelerating rates. This technology is compressing traditional fixture replacement cycles while elevating electrical contractor involvement in decor specification.
The Future Homes Standard is tightening thermal efficiency requirements for domestic fittings. Window and door manufacturers must upgrade insulated glazing and frame systems to meet 2025 implementation deadlines. Residential builders in the South East corridor are pre-emptively sourcing compliant products to avoid construction timeline disruptions.
Heritage-influenced styling preferences are rotating demand toward suburban markets. Millennial buyers outside London prioritize authentic industrial metalwork and reclaimed timber finishes over mass-produced alternatives. Regional furniture retailers are reconfiguring showroom inventory to capture this geographic demand shift.
United Kingdom Home Decor Market Segmentation
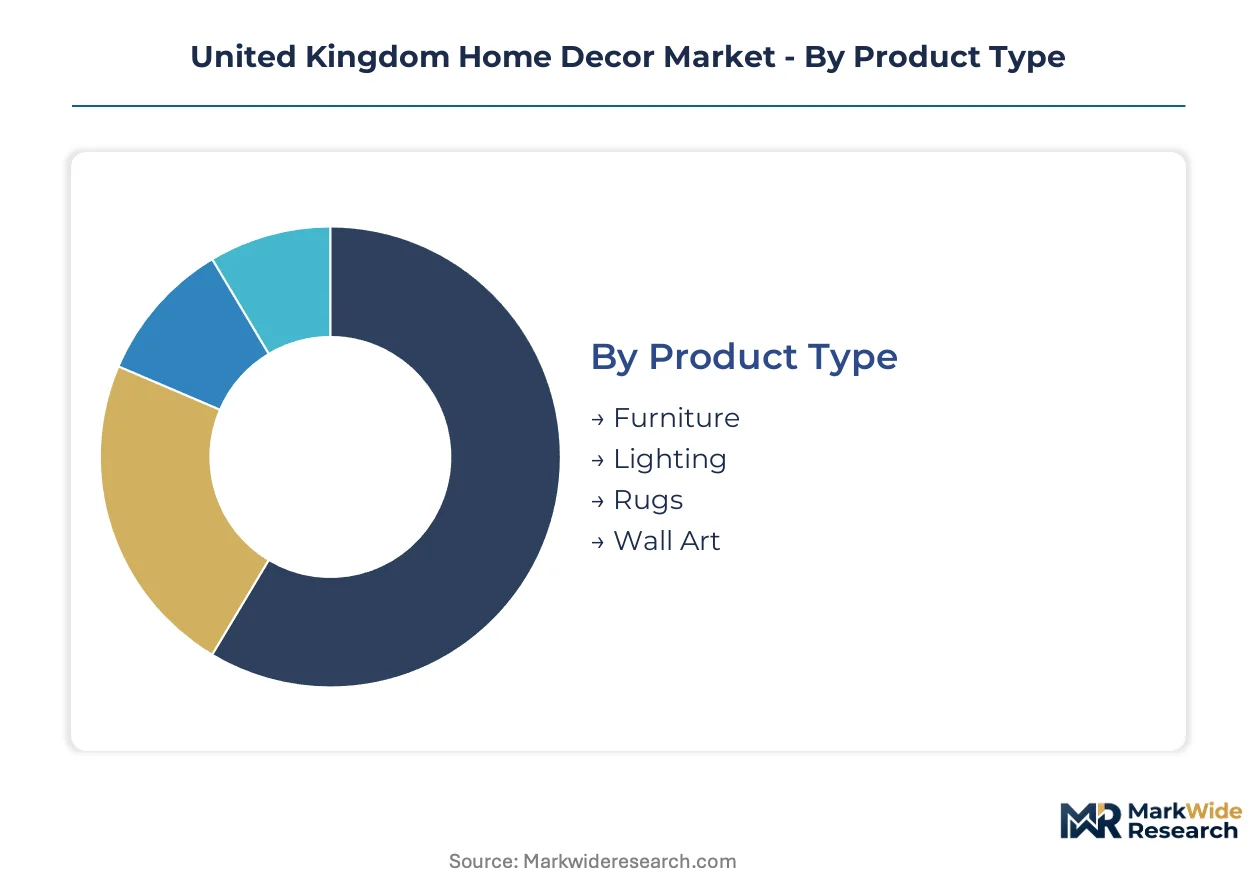
Segmentation in UK home decor reveals how capital deployment, regulatory exposure, and aesthetic migration create divergent profitability profiles across product categories. Manufacturers must align production capacity with the specific compliance burdens and replacement cycles governing each segment.
Product Type:
Furniture and lighting command the heaviest upfront tooling and inventory investment, while rugs and wall art require lighter capital commitment but faster style turnover.
- Furniture:Modular systems dominate millennial first-time buyer specifications, with FSC-certified timber sourcing mandatory under UK Timber Regulation compliance. Greater London housing turnover sustains premium upholstery demand, though fire-retardant fabric testing extends development timelines.
- Lighting:Smart control integration and circadian programming capabilities are compressing traditional replacement cycles in South East residential retrofits. Building Regulations Part L mandates thermally efficient integrated systems ahead of Future Homes Standard implementation.
- Rugs:Textile production concentrates in vertically integrated domestic facilities serving rapid fulfillment platforms.
- Wall Art:Digital printing technology has lowered entry barriers, fragmenting supply across artisan and mass-market producers.
Furniture absorbs the bulk of installed capacity; lighting is expanding most quickly.
Material:
Raw material selection determines regulatory touchpoint density and supply chain reconfiguration costs post-Brexit.
- Wood:FSC certification overhead constrains sourcing flexibility for timber-dependent manufacturers. Heritage-influenced styling in suburban markets outside London prioritizes reclaimed and authentic finishes over mass-produced alternatives.
- Metal:Industrial aesthetic penetration drives loft-conversion styling specifications across Greater London and South East corridors. Fabrication competency gaps limit scaling for authentic heritage reproductions.
- Fabric:Flammability testing under Furniture and Furnishings Regulations imposes extended laboratory validation protocols.
- Glass:Thermal efficiency upgrades for windows and doors dominate residential retrofit demand concentration.
Wood commands the deepest supply relationships; metal is gaining share fastest in aesthetic-driven specifications.
Style:
Styling preferences map directly to geographic demand migration patterns and housing stock characteristics.
- Modern:Clean lines and minimal ornamentation align with smart home integration requirements in new-build South East developments. Circadian lighting and app-enabled controls favor uncluttered fixture specifications.
- Rustic:Heritage-influenced finishes are penetrating suburban markets outside London as millennial buyers prioritize authentic timber and hand-forged metalwork. Regional furniture retailers are reconfiguring showroom inventory to capture this demand shift.
- Traditional:Established upholstery patterns serve older housing stock renovation cycles with predictable replacement timing.
- Industrial:Loft-conversion aesthetics from urban cores now specify exposed metalwork and reclaimed materials in commuter belt locations.
Traditional styling maintains the largest installed base; rustic is climbing the fastest as geographic demand shifts.
Price Tier:
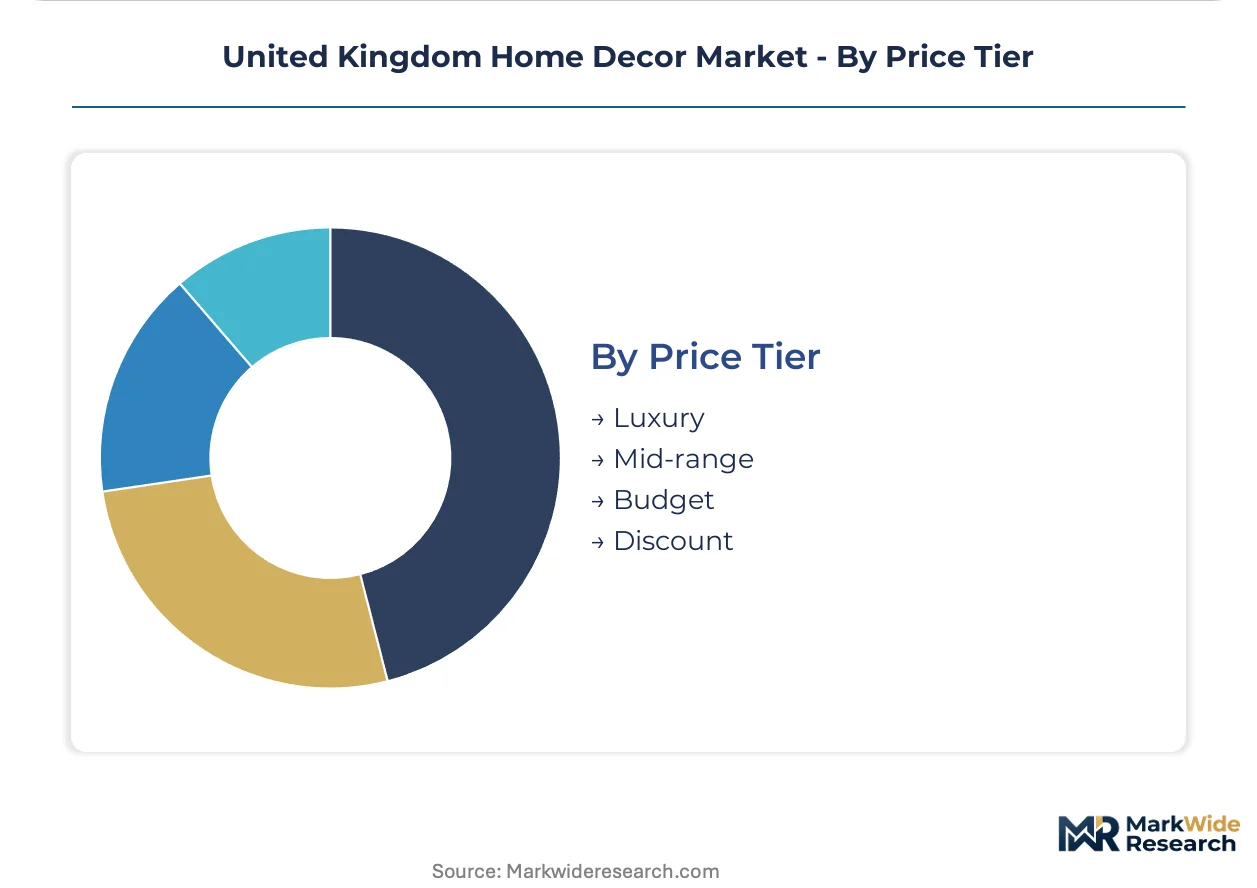
Pricing stratification reflects certification grade exposure, volume scale economics, and channel positioning against trade professional networks.
- Luxury:Bespoke fabrication and heritage craft techniques command premium positioning in Greater London and South East corridors. Fire safety certification timelines and FSC sourcing constraints filter competition to established vertically integrated producers.
- Mid-range:Modular furniture systems balance customization flexibility with manufacturing scale, capturing millennial first-time buyer renovation cycles across suburban markets.
- Budget:Rapid fulfillment platforms compete on inventory breadth and logistics speed in textile and soft furnishing categories.
- Discount:Price-sensitive positioning concentrates in DIY distribution through B&Q and Screwfix banners serving volume builders.
Mid-range absorbs the majority of unit volume; luxury is gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Timber supply chains from Baltic and Scandinavian forests anchor UK home decor manufacturing, with FSC-certified sourcing concentrated around port logistics hubs serving furniture fabricators.
London and South East
Millennial first-time buyers drive modular furniture demand across Greater London commuter belts. The Future Homes Standard mandates thermal efficiency upgrades for pre-1990 housing stock. Croydon and Reading distribution clusters support rapid fulfillment platforms for textile and soft furnishing categories.
Midlands
Heritage-influenced industrial styling penetrates Birmingham and Leicester suburban renovation cycles. The Furniture and Furnishings (Fire Safety) Regulations impose flammability testing protocols on upholstery manufacturers. Nottinghamshire timber processors supply reclaimed finishes to regional furniture retailers.
North England
Loft-conversion aesthetics accelerate uptake of exposed metalwork and authentic timber finishes across Manchester and Leeds housing stock. Building Regulations Part L shapes window and door retrofit specifications. Sheffield metalworking clusters fabricate industrial-style lighting fixtures for national distribution.
Scotland
Scottish housing renovation concentrates in Edinburgh and Glasgow metropolitan areas with elevated disposable income levels. The UK Timber Regulation restricts illegal logging in imported wood supply chains. Glasgow upholstery workshops specialize in heritage craft techniques for rustic styling segments.
Wales
Regional furniture manufacturing serves domestic refurbishment demand across Cardiff and Newport corridors. Fire-retardant fabric ratings require laboratory validation extending product development timelines. Pembrokeshire timber merchants source FSC-certified materials for heritage reproduction specialists.
United Kingdom Home Decor Market Competitive Landscape
Global majors compete with regional champions across distribution format and fulfillment speed, producing a tiered structure where DIY banners anchor volume and digital-native platforms capture style-driven segments. Kingfisher plc and IKEA Ltd exemplify scale-driven archetypes with extensive physical networks. Dunelm Group plc and Next plc occupy vertically integrated positions in textile and soft furnishing production. Wayfair Inc. represents the digital-native fulfillment model competing on inventory breadth. Dominant competitive moves include trade professional channel expansion and rapid delivery infrastructure deployment.
Among UK-listed operators, Kingfisher plc anchors DIY and trade distribution through B&Q and Screwfix banners, exemplifying the scale-driven archetype with professional procurement relationships. Dunelm Group plc occupies a vertically integrated position specializing in textile and soft furnishing production with captive manufacturing capabilities. Wayfair Inc. represents the digital-native fulfillment model competing on inventory breadth and logistics speed rather than physical showroom presence. These three operators collectively illustrate the competitive tension between physical network density and digital fulfillment acceleration reshaping UK home decor distribution.
| Leading Market Players |
|---|
| Kingfisher plc (B&Q) |
| Wayfair Inc. |
| IKEA Ltd (UK) |
| Next plc |
| Homebase Ltd |
| Dunelm Group plc |
| John Lewis & Partners |
| Wickes Group plc |
| DFS Furniture plc |
| Others |
Value Network & Pricing Analysis
FSC-certified timber sourcing costs cascade through UK home decor pricing tiers, with certification overhead compressing margins at the budget end while premium tiers absorb compliance through heritage craft positioning. Baltic and Scandinavian forest supply chains feed Greater London and South East distribution clusters, where rapid fulfillment platforms compete on logistics speed rather than price alone.
Pricing Analysis
Warranty and installation bundling separates premium furniture tiers from unbundled budget alternatives, with heritage craft guarantees commanding substantial markups in Greater London corridors. Three-tier pricing structure across premium, standard, and economy levels reflects fire-retardant certification grade and FSC timber sourcing tier. Pricing pressure stems from post-Brexit customs friction elevating landed costs for Baltic timber imports. Budget buyers exhibit highest price sensitivity, while luxury segments prioritize authentic finishes over cost optimization.
Supply Chain Analysis
UK Timber Regulation domestic-content mandates are reshaping sourcing patterns, forcing reconfiguration away from non-certified Baltic suppliers toward FSC-verified Scandinavian forest networks. UK manufacturing draws from Estonia, Latvia, and Sweden for timber feedstock, with Sheffield metalworking and Nottinghamshire upholstery providing domestic component capacity. Single-source vulnerability concentrates in Baltic port logistics corridors serving just-in-time furniture fabrication. Distribution runs through B&Q and Screwfix trade banners anchoring professional procurement, complemented by Wayfair digital-native fulfillment for residential direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK home decor operates as a supply-constrained market where FSC-certified timber scarcity props pricing power across heritage-influenced styling segments. Certification bottlenecks limit rapid scaling for authentic reproduction specialists.
For Market Incumbents: Anchor defensive positioning through captive FSC timber sourcing relationships and heritage craft training pipelines. Kingfisher plc's Screwfix banner demonstrates trade channel control insulating against digital-native fulfillment erosion. Incumbents should secure Baltic-Scandinavian forest supply agreements before regulatory tightening accelerates.
For New Entrants and Emerging Players: Smart lighting control integration offers a technology-first wedge into South East residential retrofit cycles underserved by traditional fixture manufacturers. Suburban rustic styling outside London presents the most penetrable white-space, with regional showroom networks lacking authentic industrial metalwork inventory. Direct-to-installer go-to-market bypasses established retail margin structures.
For Investors and Strategic Acquirers: Future Homes Standard implementation timeline acceleration is the leading indicator that thermal efficiency retrofit demand will concentrate procurement relationships among pre-qualified window and door fabricators. Long-term viability favors vertically integrated producers with captive timber certification and in-house upholstery capacity. Investors should track Building Regulations Part L enforcement intensity as the signal for construction timeline disruption and pre-emptive sourcing behavior.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Program Expansion | Secures timber supply chain access ahead of UK Timber Regulation tightening. |
| Heritage Craft Training Pipeline | Addresses Sheffield and Glasgow upholstery competency gaps limiting rustic styling scale. |
| Trade Professional Channel Deepening | Screwsfix and B&Q banner relationships anchor volume builder procurement loyalty. |
| Smart Lighting Platform Integration | Circadian programming capabilities compress fixture replacement cycles in South East retrofits. |
| Rapid Fulfillment Infrastructure Deployment | Croydon and Reading distribution clusters enable textile and soft furnishing delivery speed. |
Research Methodology
Document review covered UK Timber Regulation enforcement records, Furniture and Furnishings Fire Safety Regulations compliance databases, and Future Homes Standard consultation documents, complemented by interviews with furniture manufacturing executives, upholstery workshop proprietors, DIY retail category buyers, and residential construction procurement managers. Secondary validation drew from Office for Product Safety and Standards bulletins, Building Regulations Part L revision drafts, and customs trade data for Baltic-Scandinavian timber flows. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish market size boundaries.
Segmentation outputs reflect product type, material composition, style category, and price tier dimensions across the projection horizon. CAGRs were derived from housing stock turnover rates, renovation cycle frequencies, and regulatory implementation schedules. Forecast inputs incorporated millennial first-time buyer demographic penetration patterns and thermal efficiency retrofit mandate compliance timelines.
Several conditions sit outside the modeled scope, including potential EU-UK regulatory divergence beyond Ecodesign alignment scenarios, extreme weather disruptions to Baltic forest harvesting, and currency volatility effects on Scandinavian timber import costs. Forecasts reflect documented assumptions regarding Future Homes Standard adherence schedules and heritage craft training pipeline development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Slipcases Market